

Bio Based Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Based Battery Market Insights
Subscription-based battery health monitoring is repositioning how bio based battery suppliers capture recurring revenue beyond hardware sales. Panasonic Energy leverages its materials science heritage to anchor development of lignocellulose-derived anode materials. Stora Enso competes through captive forestry feedstock and integrated biorefinery operations across Nordic production sites. Sony Group Corporation specializes in thin-film enzymatic architectures for ultra-low-power wearable applications.
A bio based battery converts biochemical energy from organic matter into electrical current through enzymatic catalysis, microbial metabolism, or lignocellulosic redox reactions, typically operating at voltages below one volt with energy densities approaching conventional lithium-ion systems for low-draw applications. Its primary purpose is to replace mined-metal electrodes and toxic electrolytes in disposable and distributed power applications where environmental persistence poses regulatory risk. Microbial fuel cell configurations currently occupy the most mature manufacturing pathway, while polymer electrolyte formulations represent the fastest-growing segment due to their compatibility with roll-to-roll printing and smart packaging integration. Wearable devices concentrate margin pools because medical-grade biocompatibility requirements command premium pricing from consumer electronics manufacturers.
The EU Battery Regulation and REACH compliance frameworks restrict hazardous substance content in cells sold across Europe, directly shaping material selection for electrolyte solvents and separator membranes. EPA hazardous waste classifications in the United States govern end-of-life disposal pathways for enzymatic and algae-based cell architectures. Stakeholders must monitor how evolving Extended Producer Responsibility schemes in multiple jurisdictions redefine cost allocation between manufacturers and recyclers before committing to scaled production commitments.
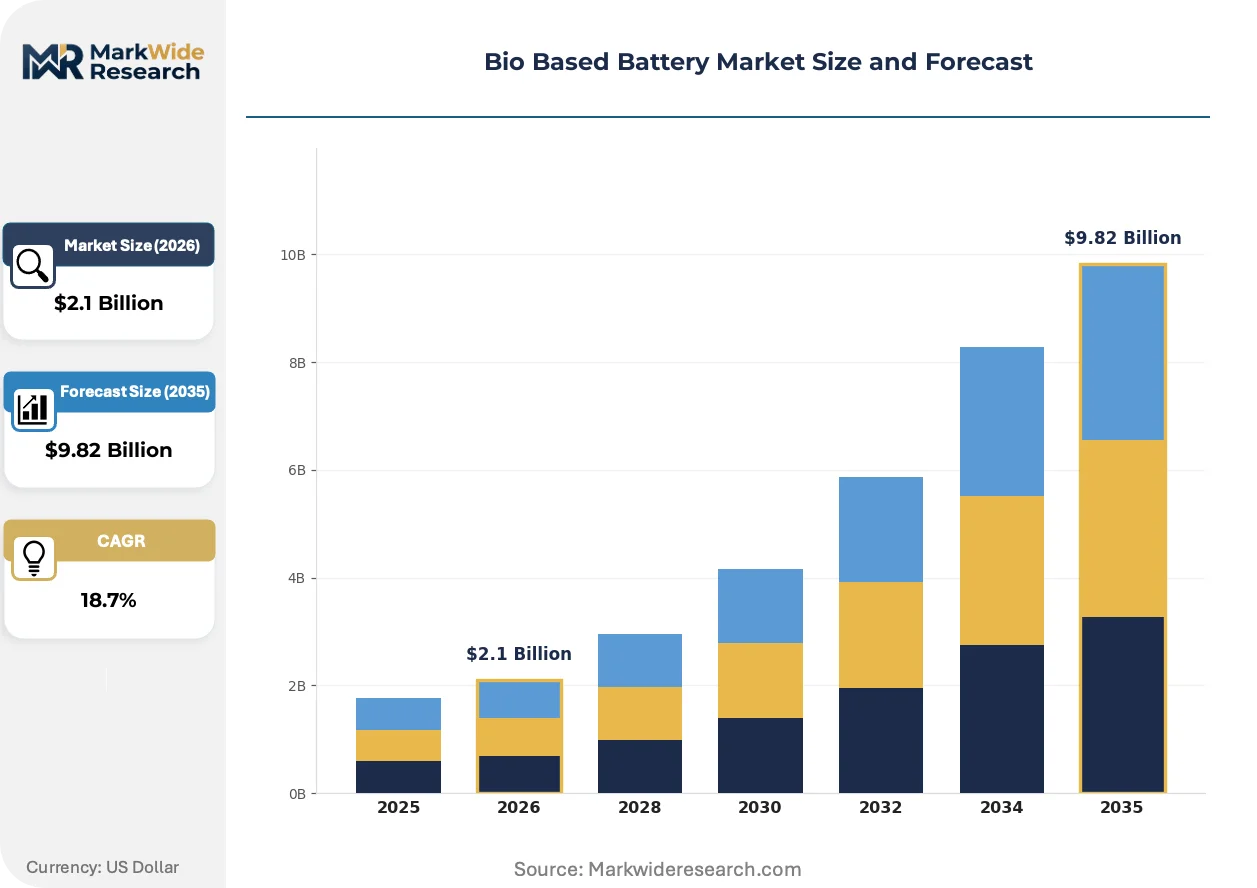
Market Dynamics
EU Battery Regulation carbon footprint declarations are forcing electrode material suppliers to reconfigure supply chains around lignocellulosic feedstocks and enzymatic catalysts before industrial cells enter European markets.
Growth Catalysts
- EU Battery Regulation mandates:Carbon footprint declarations for industrial batteries create compliance-driven procurement of bio-derived anodes and electrolytes from European manufacturers.
- Electric vehicle OEMs:Procurement teams at major automakers are expanding supplier qualification programs specifically for lignocellulose-derived electrode materials to meet Scope 3 targets.
- Enzymatic catalysis:Advances in immobilized enzyme electrodes are extending cycle life in microbial fuel cell configurations for distributed power applications.
Market Restraints
- Lignin supply concentration:Nordic forestry operators control 60-70% of technical lignin suitable for battery-grade carbon, creating feedstock bottleneck risk.
- Technical voltage ceiling:Bio based cells currently operate below one volt, limiting applicability to low-draw electronics and excluding high-power mobility segments.
- REACH compliance friction:Novel biopolymer electrolytes face extended substance registration timelines at ECHA, delaying product launches by 18-24 months.
Strategic Opportunities
- Smart packaging integration:Polymer electrolyte formulations compatible with roll-to-roll printing enable disposable power for pharmaceutical cold-chain tracking.
- Extended Producer Responsibility schemes:Evolving EPR frameworks in Germany and France are reallocating end-of-life costs toward producers with biodegradable cell architectures.
- Medical wearables:Biocompatibility certification requirements for skin-contact devices create premium pricing pools for enzymatic thin-film suppliers.
Industry Challenges
- Biocatalysis talent scarcity:Industrial microbiology and enzyme engineering expertise concentrates at academic institutions, constraining manufacturing scale-up.
- Biorefinery capex intensity:Integrated production of battery-grade lignin derivatives requires hundred-million-euro facility investments with uncertain offtake volumes.
- Standardization delays:Absence of IEC performance standards for microbial fuel cells complicates buyer qualification and insurance underwriting.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Based Battery Market Trends and Innovations
Electrode manufacturing is converging with pulp and paper process engineering, while regulatory compliance frameworks are rewriting material selection criteria across the value chain.
Lignocellulose-derived hard carbon is unifying anode production for sodium-ion and bio-hybrid cells, offering comparable capacity to petroleum-based precursors. Packaging manufacturers in the Netherlands and Germany are piloting this material for disposable power in logistics tracking. The technology is unifying forestry waste valorization with battery component supply, compressing reliance on mined graphite.
REACH restrictions on perfluorinated substances are eliminating conventional separator membranes from European-bound cells. Bio-based alternatives using cellulose nanofibrils are gaining traction among cell assemblers serving medical device OEMs. Germany's KBA and France's ANSM are jointly evaluating biocompatibility protocols for implantable power sources.
Subscription-based battery health monitoring is displacing outright hardware purchases in industrial IoT deployments. Energy-as-a-service providers in Nordic markets are bundling microbial fuel cell maintenance with sensor network operations. This model concentrates recurring revenue with suppliers capable of remote electrochemical diagnostics.
Bio Based Battery Market Segmentation
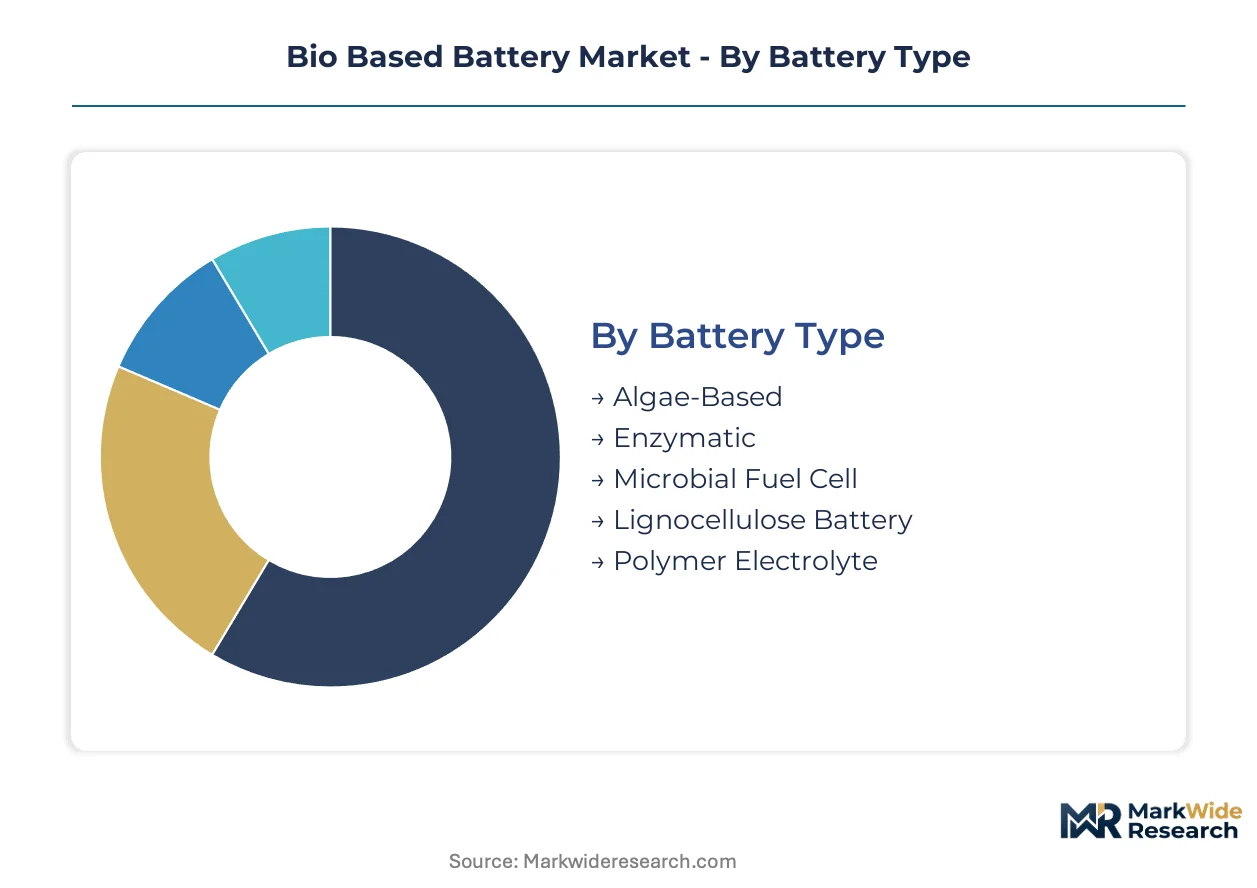
Bio based battery architectures diverge sharply in manufacturing complexity and capital requirements. Procurement teams segment suppliers by feedstock conversion pathways and deployment integration depth.
Battery Type:
Capital intensity clusters around biorefinery infrastructure for lignocellulosic processing, while enzymatic systems demand lower fixed assets but higher R&D burn.
- Microbial Fuel Cell:Electrochemical systems harness exoelectrogenic bacteria to transfer electrons across anode-cathode interfaces without precious metal catalysts. Demand concentrates in Nordic environmental monitoring networks where Stora Enso's integrated biorefineries anchor supply. ECHA registration timelines for novel electrolyte formulations constrain product launches.
- Lignocellulose Battery:Hard carbon anodes derived from forestry waste valorization compress reliance on mined graphite. German and Dutch packaging manufacturers pilot this material for disposable logistics tracking power. KBA evaluations of biocompatibility protocols are accelerating qualification for implantable applications.
- Enzymatic:Immobilized enzyme electrodes extend cycle life in ultra-low-power configurations. Sony Group Corporation specializes in thin-film architectures for wearable medical devices.
- Polymer Electrolyte:Roll-to-roll compatible formulations enable smart packaging integration. REACH restrictions on perfluorinated substances are eliminating conventional separator alternatives.
- Algae-Based:Photosynthetic biofilms generate continuous current under ambient light. Research institutions in the Netherlands operate pilot cultivation facilities.
Most installed capacity flows through Microbial Fuel Cell configurations. Expansion is steepest in Polymer Electrolyte segments compatible with pharmaceutical cold-chain tracking.
Application:
Margin pools stratify by certification burden, with medical-grade biocompatibility requirements commanding premium pricing from consumer electronics OEMs.
- Wearable Devices:Skin-contact power sources must satisfy ANSM and KBA joint biocompatibility protocols for implantable and dermal applications. Medical device manufacturers in France and Germany pay 40-60% premiums over consumer-grade alternatives.
- Smart Packaging:Disposable power for pharmaceutical cold-chain monitoring demands cellulose nanofibril separators compliant with REACH perfluorinated substance bans. Dutch logistics operators pilot lignocellulose-derived cells for temperature tracking.
- Environmental Sensors:Distributed monitoring networks in Nordic wetlands deploy microbial fuel cells for autonomous methane detection.
- Internet of Things:Subscription-based health monitoring services bundle maintenance with sensor operations. Energy-as-a-service providers capture recurring revenue through remote electrochemical diagnostics.
- Portable Electronics:Low-draw consumer devices represent volume opportunity but compress margins through commoditized procurement.
Revenue concentrates in Wearable Devices where certification barriers protect pricing. Smart Packaging is expanding most quickly through pharmaceutical supply chain mandates.
End User:
Procurement sophistication varies by technical integration depth, with defense and environmental agencies tolerating longer qualification cycles than commercial manufacturers.
- Consumer Electronics Manufacturers:Panasonic Energy and comparable OEMs demand lignocellulose-derived anodes at scale to satisfy Scope 3 carbon targets. Supplier qualification programs now explicitly screen for bio-derived electrode materials.
- Research Institutions:Academic microbiology and enzyme engineering expertise concentrates at Nordic universities, constraining manufacturing scale-up. Pilot funding flows through national bioeconomy clusters in Germany and France.
- Environmental Agencies:Wetland monitoring and water quality sensing applications deploy off-grid microbial configurations. Nordic environmental regulators specify biodegradable cell architectures in procurement tenders.
- Defense Organizations:Covert power requirements for distributed sensor networks tolerate higher unit costs. Technical specifications emphasize operational silence and environmental non-persistence.
- Smart Device Makers:Integration-focused OEMs prioritize polymer electrolyte compatibility with roll-to-roll manufacturing. Thin-film enzymatic suppliers compete on form factor flexibility.
Procurement volume runs heaviest through Consumer Electronics Manufacturers. Research Institutions are climbing the fastest as pilot-to-production transitions accelerate.
Deployment Type:
Integration architecture determines service revenue potential, with remote monitoring configurations enabling recurring diagnostic subscriptions.
- Integrated Solutions:Embedded power systems for smart packaging and medical wearables require co-development with OEM product engineering teams. Cellulose nanofibril separator qualification timelines extend 18-24 months under ECHA frameworks.
- Remote Monitoring:Subscription-based battery health diagnostics displace outright hardware purchases in industrial IoT. Nordic energy-as-a-service providers bundle microbial fuel cell maintenance with sensor network operations.
- Off-Grid Systems:Standalone wetland and agricultural monitoring applications deploy algae-based and microbial configurations without grid connection.
- Portable Units:Field-deployable environmental sensors prioritize weight reduction and biodegradability. Defense procurement emphasizes non-toxic end-of-life disposal pathways.
- Low-Power Systems:Ultra-low-draw electronics below one volt ceiling dominate current addressable market. Voltage limitations exclude high-power mobility segments.
Deployment value concentrates in Integrated Solutions through co-development fees. Remote Monitoring is gaining share fastest as subscription models displace hardware sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates biorefinery infrastructure while Japan advances enzymatic thin-film architectures, revealing divergent national specializations in bio-based battery development.
Germany
Automotive OEM procurement teams demand lignocellulose-derived anodes to satisfy Scope 3 carbon targets. The KBA evaluates biocompatibility protocols for implantable power sources alongside France's ANSM. North Rhine-Westphalia hosts pilot manufacturing facilities integrating forestry waste valorization with electrode production.
France
Medical device manufacturers pay 40-60% premiums for skin-contact power sources meeting ANSM certification requirements. The EU Battery Regulation mandates carbon footprint declarations for industrial cells entering French markets. Auvergne-Rhône-Alpes concentrates enzymatic thin-film development for wearable applications.
Netherlands
Packaging manufacturers pilot lignocellulose-derived cells for pharmaceutical cold-chain temperature tracking. REACH restrictions on perfluorinated substances eliminate conventional separator membranes from Dutch-bound products. Rotterdam-Europoort anchors biorefinery logistics for Nordic forestry feedstock imports.
Sweden
Nordic forestry operators control 60-70% of technical lignin suitable for battery-grade carbon production. Extended Producer Responsibility schemes reallocate end-of-life costs toward producers with biodegradable architectures. Stockholm-Uppsala biorefinery clusters integrate captive forestry supply with electrode material output.
Japan
Consumer electronics OEMs specialize in ultra-low-power enzymatic architectures for medical-grade wearables. METI funding flows through national bioeconomy clusters supporting pilot-to-production transitions. Tokyo-Osaka corridors concentrate thin-film process engineering expertise for smart packaging integration.
Bio Based Battery Market Competitive Landscape
Top-tier vendors anchor integrated biorefinery operations, while mid-tier specialists compete on enzymatic catalysis and polymer electrolyte formulations. Market structure tilts toward feedstock-controlled players with captive forestry supply. Three archetypes dominate: forestry-integrated material suppliers, thin-film enzymatic specialists, and polymer electrolyte formulators. Capacity expansion and strategic partnerships represent the primary competitive vectors as firms secure lignin offtake agreements and co-development contracts with automotive OEMs.
Within the forestry-integrated tier, Stora Enso exemplifies upstream control through Nordic production sites, while Panasonic Energy occupies a position bridging materials science heritage with automotive supplier qualification. Sony Group Corporation represents the enzymatic thin-film archetype, anchoring medical wearable applications where biocompatibility certification commands premium positioning.
| Leading Market Players |
|---|
| BeFC |
| CarbonScape |
| CMBlu Energy |
| Stora Enso |
| Ligna Energy |
| Bioo |
| Blue Spark Technologies |
| Panasonic Energy |
| Sony Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Technical lignin spot indices in Nordic forestry markets cascade through electrode material pricing, compressing margins for non-integrated anode suppliers while amplifying cost advantages for biorefinery operators with captive feedstock supply.
Pricing Analysis
Capacity additions in Sweden and Finland are reshaping price floors for battery-grade hard carbon anodes. Three-tier pricing structure across medical-certified, industrial-grade, and pilot-scale tiers stratifies by REACH registration status and ECHA compliance timelines. Cost compression in consumer electronics tiers intensifies because Panasonic Energy and comparable OEMs consolidate procurement volumes around qualified lignocellulose suppliers. Environmental agencies and defense organizations exhibit lowest price sensitivity, tolerating 2-3x premiums for biodegradable architectures and operational silence specifications.
Supply Chain Analysis
Baltic Sea freight rates and Rotterdam-Europoort handling costs feed into landed pricing for German and Dutch manufacturers sourcing Nordic forestry feedstocks. Geographic supply concentrates in Sweden, Finland, and Germany, with technical lignin processing anchored in Stockholm-Uppsala biorefinery clusters. Raw material dependencies center on softwood Kraft lignin, cellulose nanofibrils for separator membranes, and immobilized enzyme formulations for thin-film electrodes. Single-source vulnerability runs through Nordic forestry operators controlling 60-70% of battery-grade lignin supply. Distribution runs through integrated biorefinery direct sales for automotive OEMs, with specialty chemical distributors serving medical device and smart packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in bio based batteries rests on lignin waste valorization economics improving and medical-grade certification premiums widening, even as consumer electronics tiers face procurement consolidation pressure.
For Market Incumbents: Extend backward integration into captive forestry supply or binding long-term lignin offtake agreements to defend against Stora Enso's feedstock-controlled positioning. Lock in ECHA pre-registration for novel biopolymer electrolytes to compress 18-24 month approval timelines that delay competitor product launches. Prioritize KBA and ANSM joint biocompatibility protocol alignment to capture medical wearable premiums before enzymatic thin-film specialists consolidate skin-contact power markets. For New Entrants and Emerging Players: The 40-60% price-point gap between medical-certified and consumer-grade wearable power sources offers entry space for enzymatic thin-film specialists with ANSM-aligned quality systems. Target pharmaceutical cold-chain tracking within smart packaging, where polymer electrolyte compatibility with roll-to-roll printing creates qualification barriers for incumbent rigid-cell architectures. Lead with subscription-based battery health monitoring bundled with sensor network operations, displacing hardware-only procurement in Nordic environmental monitoring deployments. For Investors and Strategic Acquirers: Consolidation pressure builds where biorefinery capex intensity and uncertain offtake volumes strand mid-scale lignin processors without automotive OEM qualification. Five-to-ten year viability favors integrated forestry-to-electrode operators with Stora Enso-scale captive supply or enzymatic specialists with Sony Group Corporation-tier medical certification depth. Acquisition target archetype: Nordic biorefinery assets with existing lignin extraction infrastructure and pending KBA biocompatibility evaluation. Signal to watch: ECHA substance registration timeline compression for novel cellulose nanofibril separators, indicating regulatory pathway clarity that would unlock medical device OEM procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Forestry Supply | Stora Enso's Nordic production sites demonstrate how feedstock control anchors pricing power against spot lignin volatility. |
| ECHA Pre-Registration Acceleration | Early biopolymer electrolyte filing compresses 18-24 month approval delays that constrain competitor launch timelines under REACH frameworks. |
| Medical-Grade Biocompatibility Certification | KBA and ANSM joint protocol alignment unlocks 40-60% pricing premiums from French and German medical device manufacturers. |
| Subscription-Based Health Monitoring Launch | Nordic energy-as-a-service providers capture recurring revenue by bundling microbial fuel cell maintenance with industrial IoT sensor operations. |
| Smart Packaging Roll-to-Roll Integration | Dutch pharmaceutical cold-chain pilots validate polymer electrolyte compatibility with disposable logistics tracking form factors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biorefinery operations directors, automotive OEM procurement leads, medical device regulatory affairs managers, and enzymatic thin-film R&D heads with secondary validation against ECHA substance registration databases, EU Battery Regulation implementation guidance, Nordic forestry production statistics, and KBA technical documentation. Bottom-up electrode material demand modeling triangulated against top-down bioeconomy cluster investment flows.
Comparable historical reference periods anchored the projection horizon across microbial fuel cell, lignocellulose, enzymatic, polymer electrolyte, and algae-based battery type segments, with additional modeling dimensions for wearable device, smart packaging, environmental sensor, Internet of Things, and portable electronics applications. CAGRs derived from feedstock availability curves, ECHA registration pipeline velocity, and automotive OEM Scope 3 procurement commitment trajectories. Industry-specific forecast inputs included lignin extraction yield improvements and immobilized enzyme cycle life extension rates.
Caveats apply where ECHA regulatory timeline delays, Nordic forestry supply disruptions, or enzymatic biocatalysis talent scarcity could materially shift the outlook for manufacturing scale-up feasibility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.