
 Lead Carbon Battery Market | 2026-2036
Lead Carbon Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Carbon Battery Market Insights
Multi-source electrode material procurement is broadening across the lead carbon battery supply chain as manufacturers hedge against lead price volatility. ShuangDeng leverages captive lead smelting capacity to control input costs across its production base. China Tianneng sustains R&D intensity in carbon additive formulations through dedicated research centers in Jiangsu province. Narada anchors its competitive position with specialized valve-regulated lead acid lines for telecom base station deployments across Africa and the Middle East.
Lead carbon batteries integrate activated carbon or carbon black into the negative electrode of a lead-acid cell, enhancing charge acceptance and extending cycle life to 2,000–4,000 cycles at partial state-of-charge operation. The chemistry serves primarily as a cost-efficient stationary storage alternative to lithium-ion for applications requiring moderate energy density with extreme temperature tolerance. Flooded product types retain manufacturing scale advantages for utility-scale installations where maintenance access is practical. Energy storage applications absorb the fastest demand growth as grid operators seek four-to-eight hour duration assets without lithium supply chain exposure. Hybrid technology configurations are gaining share as manufacturers blend conventional lead-acid construction with carbon-enhanced negative plates to balance capital cost against performance metrics.
China's MIIT enforces GB/T standards for lead-acid battery recycling and carbon content disclosure, while India's BIS certification mandates cycle-life testing for stationary storage imports. The EPA in the United States regulates lead smelter emissions under the National Ambient Air Quality Standards, constraining domestic electrode material supply and shaping import dependency patterns. Stakeholders must monitor how carbon additive sourcing geography shifts under evolving battery passport and supply chain due diligence frameworks.
Market Dynamics
Lead carbon battery manufacturers face intensifying pressure from China's MIIT cycle-life standards while navigating lead price volatility through multi-source electrode material strategies. The chemistry's positioning against lithium-ion alternatives hinges on capital cost advantages in four-to-eight hour stationary storage applications.
Growth Catalysts
- Telecommunications backup power expansion:Southeast Asian operators are deploying lead carbon systems at base stations as grid reliability fluctuates across Indonesia, Vietnam, and the Philippines.
- India's solar-plus-storage mandates:State-level renewable integration targets under CEA guidelines are specifying durable chemistry for rural microgrids and agricultural pumping stations.
- Carbon additive formulation advances:Dedicated R&D centers in Jiangsu province are refining activated carbon loading rates to push cycle life toward 4,000 cycles at partial state-of-charge operation.
Market Restraints
- Lead price volatility:Electrode material costs swing with London Metal Exchange pricing, compressing margins for manufacturers lacking captive smelting capacity.
- Lithium-ion substitution threat:Declining lithium iron phosphate pack costs are encroaching on lead carbon's traditional stronghold in two-to-four hour duration applications.
- EPA smelter emissions constraints:National Ambient Air Quality Standards enforcement has constrained domestic US lead supply, forcing import dependency for electrode materials.
Strategic Opportunities
- African telecom infrastructure:Valve-regulated lead acid lines specialized for high-temperature operation are capturing base station deployments across Nigeria and Kenya where maintenance access is limited.
- Hybrid technology configurations:Blending conventional lead-acid construction with carbon-enhanced negative plates is opening mid-market segments seeking balanced capital cost against performance metrics.
- Battery passport alignment:Early adoption of supply chain due diligence frameworks for carbon additive sourcing is positioning compliant manufacturers for EU market access under evolving CSRD requirements.
Industry Challenges
- Carbon additive quality certification:BIS cycle-life testing mandates for stationary storage imports are extending product validation timelines for suppliers targeting the Indian market.
- Electrochemistry talent scarcity:Formulation expertise for negative plate carbon integration remains concentrated among aging specialist workforces in China's battery manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Carbon Battery Market |
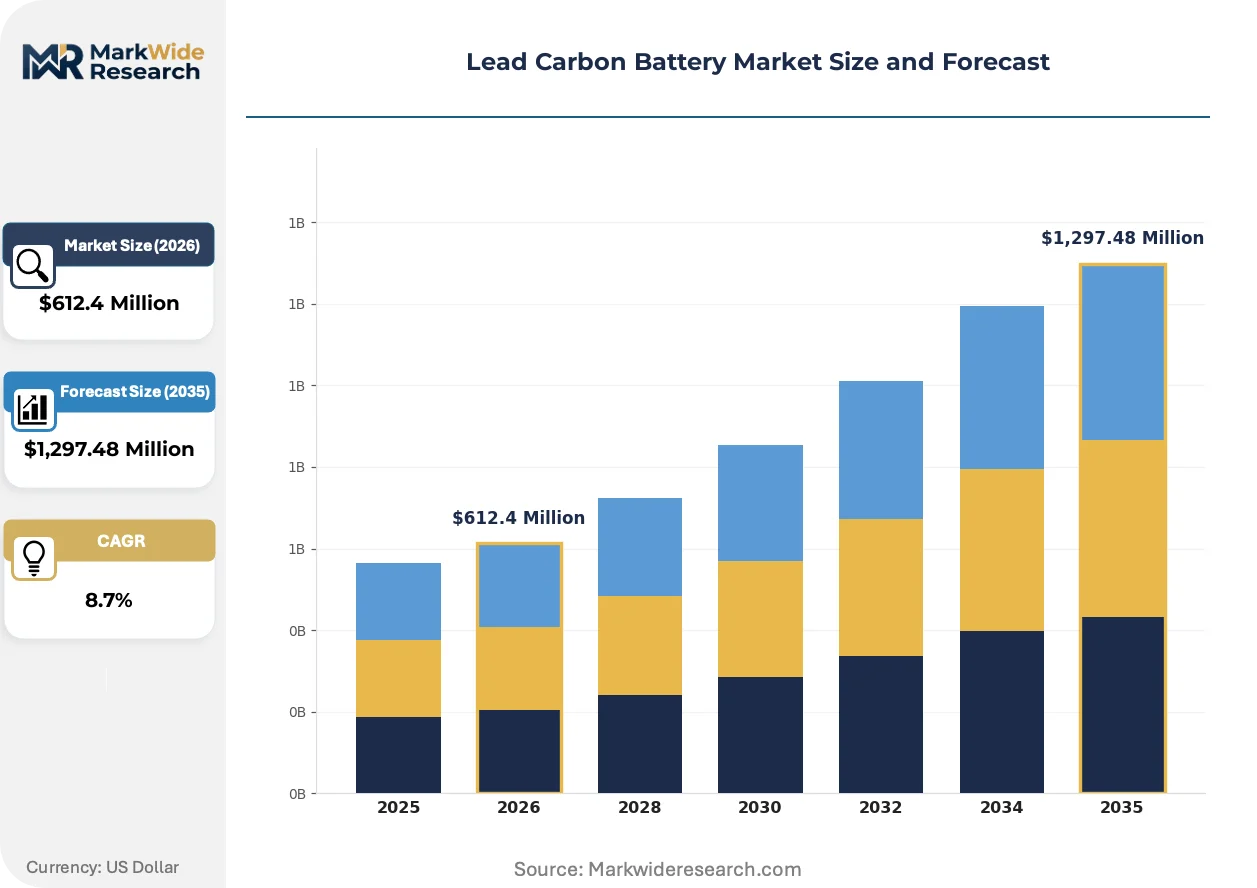
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Lead Acid, Flooded, Gel, Valve-Regulated Lead Acid End User: Automotive, UPS, Renewable Energy, Telecommunications Technology: Hybrid, Conventional, Advanced, Smart Application: Energy Storage, Portable Power, Marine, Industrial Equipment |
| Companies Covered | ShuangDeng, China Tianneng, Furukawa, Eastpenn, Sacred Sun, Narada, XiongZhuang, Huafu Energy Storage, Axion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Carbon Battery Market Trends and Innovations
Manufacturing process digitization is compressing electrode formation cycles while regulatory disclosure requirements are reshaping material sourcing transparency. These forces are converging to redefine competitive advantage around quality consistency rather than scale alone.
Automated carbon slurry mixing systems are automating the dispersion of activated carbon within negative plate pastes. Indian renewable project developers are specifying these production lines to secure consistent charge acceptance across large solar-plus-storage deployments. The technology is automating quality variance reduction that previously required manual operator intervention, enabling tier-two manufacturers to meet utility-grade specifications.
China's MIIT GB/T standards for carbon content disclosure are mandating batch-level traceability from electrode production through module assembly. Domestic manufacturers must now document additive sourcing geography and purity grades in regulatory filings. Stationary storage product lines face the steepest compliance burden as cycle-life claims require third-party verification against disclosed carbon loading rates.
Telecom operators are consolidating procurement around performance-guaranteed service contracts rather than capital equipment purchases. African and Middle Eastern base station owners now contract for guaranteed backup hours with battery replacement obligations shifting to manufacturers. This model is most visible in Nigeria's tower company market, where infrastructure-as-a-service arrangements are displacing traditional equipment sales channels.
Lead Carbon Battery Market Segmentation
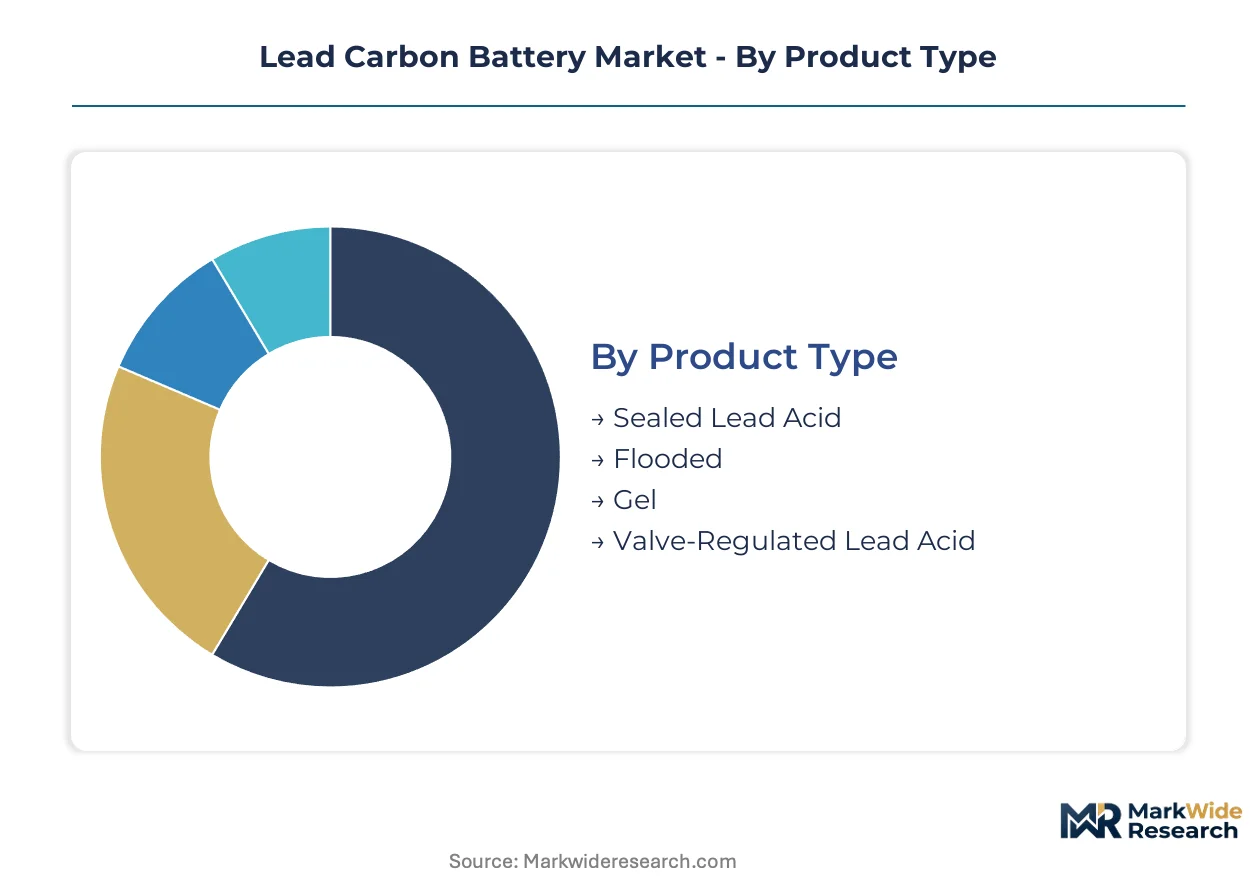
Lead carbon battery procurement patterns diverge sharply across product architectures and end-use requirements. Manufacturers configure production lines around distinct technical specifications that govern cycle life, maintenance access, and temperature tolerance in target deployments.
Product Type:
Capital intensity and maintenance protocols separate buyers in this category, with utility-scale operators accepting flooded designs while remote installations demand sealed architectures.
- Flooded:Open-vented cells with liquid electrolyte require periodic watering but deliver the lowest cost per kilowatt-hour for utility-scale installations. Demand concentrates in India's solar-plus-storage tenders where maintenance crews access containerized battery enclosures at centralized renewable parks. CEA guidelines for rural microgrids explicitly specify flooded lead-acid variants for cost-sensitive agricultural pumping stations.
- Valve-Regulated Lead Acid:Starved electrolyte designs with pressure-relief valves eliminate watering requirements while tolerating high-temperature operation. Southeast Asian telecom operators in Indonesia and Vietnam specify these for base station cabinets where technician visits are infrequent and ambient temperatures exceed 40°C. MIIT carbon content disclosure standards apply most stringently to this product line given its dominance in Chinese stationary storage exports.
- Sealed Lead Acid:Fully enclosed recombinant designs suit portable and indoor installations where acid spillage poses liability risks.
- Gel:Silica-thickened electrolyte variants resist deep discharge cycling in marine and mobility applications.
Volume sits with Flooded configurations; growth tilts toward Valve-Regulated Lead Acid as telecom infrastructure-as-a-service contracts expand.
End User:
Procurement scale and contract structure vary dramatically across this dimension, from million-unit automotive supply agreements to performance-guaranteed utility service contracts.
- Telecommunications:Tower companies and mobile network operators contract for guaranteed backup hours rather than equipment ownership. Nigeria's infrastructure-as-a-service market exemplifies this shift, with battery replacement obligations shifting to manufacturers under multi-year service agreements. African deployments in Kenya and the Middle East specify high-temperature-tolerant valve-regulated designs for off-grid base stations.
- Renewable Energy:Solar-plus-storage developers under India's state-level mandates specify durable chemistry for four-to-eight hour duration assets. CEA guidelines for rural electrification prioritize cost-effective stationary storage over lithium-ion alternatives where supply chain exposure is unacceptable. Jiangsu province R&D centers supply carbon additive formulations tuned for partial state-of-charge operation in these deployments.
- UPS:Data center and critical facility operators specify standardized form factors with rapid discharge capability.
- Automotive:Start-stop and mild-hybrid vehicle programs absorb volume through tier-one supplier integration.
Automotive contracts anchor current manufacturing volume; Renewable Energy procurement is climbing the fastest as grid-scale tenders multiply.
Technology:
Performance tier and carbon integration depth define competitive positioning in this category, with premium configurations commanding substantial price premiums.
- Hybrid:Blends conventional lead-acid construction with carbon-enhanced negative plates to balance capital cost against cycle-life metrics. Indian project developers specify hybrid lines for mid-market solar-plus-storage segments where full carbon loading exceeds budget constraints. Automated carbon slurry mixing systems from Jiangsu province suppliers enable consistent quality in these intermediate products.
- Advanced:Optimized carbon loading rates and proprietary additive formulations push cycle life toward 4,000 cycles. MIIT GB/T standards for carbon content disclosure and batch-level traceability apply most rigorously to this tier, with third-party verification required for cycle-life claims in Chinese domestic tenders.
- Conventional:Standard lead-acid construction without carbon enhancement serves price-sensitive replacement markets.
- Smart:Integrated battery management systems with remote monitoring capability for distributed asset fleets.
Conventional technology retains the largest installed base; Advanced configurations are gaining share fastest as cycle-life guarantees become contract requirements.
Application:
Duration requirements and operating environment severity dictate specification choices across this dimension.
- Energy Storage:Grid-connected and off-grid stationary systems requiring four-to-eight hour discharge duration. India's renewable integration mandates under CEA guidelines specify these applications for rural microgrids and agricultural pumping, with durability requirements favoring lead carbon over lithium-ion chemistry. BIS certification mandates cycle-life testing for all stationary storage imports targeting this segment.
- Portable Power:Mobile and backup power systems for construction, events, and emergency response. Southeast Asian rental equipment markets in Indonesia and the Philippines specify sealed designs for tropical humidity exposure.
- Marine:Deep-cycle resistant designs for propulsion and house loads in commercial and recreational vessels.
- Industrial Equipment:Motive power for forklifts and automated guided vehicles in manufacturing facilities.
Energy Storage commands the dominant revenue share; Portable Power is expanding most quickly as disaster preparedness programs accelerate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lead smelting capacity concentrates in China's Jiangsu province, where integrated manufacturers control electrode material supply chains. Grid-scale storage tenders in India and telecom infrastructure rollouts across Southeast Asia are redrawing demand geography.
China
MIIT GB/T standards for carbon content disclosure and cycle-life verification are tightening compliance burdens for domestic manufacturers. Jiangsu province hosts dedicated R&D centers refining activated carbon loading rates for utility-grade specifications. Yangtze River Delta production clusters supply carbon-enhanced negative plate formulations to Indian solar-plus-storage developers.
India
CEA guidelines for rural electrification mandate durable chemistry for agricultural pumping stations and microgrid installations. BIS certification requires cycle-life testing for all stationary storage imports, extending validation timelines for foreign suppliers. Gujarat and Maharashtra renewable parks specify flooded lead carbon configurations for cost-sensitive four-to-eight hour duration assets.
Indonesia
Telecom operators deploy valve-regulated systems at base stations where grid reliability fluctuates and ambient temperatures exceed 40°C. National infrastructure programs prioritize backup power for archipelago connectivity. Java-based tower companies contract infrastructure-as-a-service arrangements with guaranteed backup hour obligations.
United States
EPA National Ambient Air Quality Standards enforcement has constrained domestic lead smelter emissions, forcing electrode material import dependency. FERC grid interconnection rules favor four-to-eight hour duration assets for utility-scale storage procurement. Domestic project developers seek chemistry without lithium supply chain exposure.
Nigeria
African telecom infrastructure expansion specifies high-temperature-tolerant valve-regulated designs for off-grid base stations. Tower company markets have shifted to performance-guaranteed service contracts with battery replacement obligations shifting to manufacturers. Lagos-based infrastructure-as-a-service arrangements displace traditional equipment sales channels.
Lead Carbon Battery Market Competitive Landscape
Global majors compete with regional champions across carbon additive formulation expertise and captive lead supply control. Market structure tilts toward vertically integrated manufacturers with in-house smelting capacity and dedicated R&D facilities. Three archetypes dominate: integrated miners-to-battery producers, specialized carbon formulation houses, and telecom-focused service contractors. Competitive moves concentrate on backward integration into electrode materials and hybrid technology licensing to mid-market segments.
Among China-based integrated producers, ShuangDeng and China Tianneng exemplify the captive smelting archetype, anchoring cost control through upstream lead supply. Narada occupies a position within the telecom-specialist tier, with its geographic naming suggesting focused regional positioning. These three represent distinct competitive vectors: raw material security, formulation R&D intensity, and end-use service contracting.
| Leading Market Players |
|---|
| ShuangDeng |
| China Tianneng |
| Furukawa |
| Eastpenn |
| Sacred Sun |
| Narada |
| XiongZhuang |
| Huafu Energy Storage |
| Axion |
| Others |
Pricing and Supply Chain Analysis
Lead price volatility on the London Metal Exchange transmits directly through electrode material costs to downstream pricing tiers, with manufacturers lacking captive smelting capacity absorbing margin compression while integrated producers maintain pricing power across utility-scale and telecom contract segments.
Pricing Analysis
Warranty and service-hour guarantees increasingly bundle into headline pricing rather than standing as unbundled add-ons. African telecom infrastructure-as-a-service contracts embed battery replacement obligations within per-tower monthly fees, obscuring true equipment pricing behind performance commitments. Pricing stratifies across premium certified tiers with MIIT GB/T carbon disclosure verification, standard utility-grade configurations, and economy flooded variants for rural microgrids. Cost compression in economy tiers intensifies as Jiangsu province manufacturers automate carbon slurry mixing to match tier-one quality at lower price points. Renewable energy developers in India exhibit highest price sensitivity, while data center UPS procurement prioritizes cycle-life guarantees over capital cost.
Supply Chain Analysis
Ocean freight rates from Yangtze River Delta ports to Indian west coast terminals shape landed cost competitiveness for electrode material shipments. Raw material sourcing anchors in China's Jiangsu province for activated carbon formulations, with secondary supply nodes emerging for lead ore concentrate in Australia and Peru. Component dependencies span lead ingot from captive smelters, carbon black from petrochemical processors, and fiberglass separator mat from specialized textile manufacturers. Single-source vulnerability concentrates in high-purity activated carbon grades where Jiangsu R&D centers hold formulation expertise. Distribution runs through project-direct channels for utility-scale deployments and tower company procurement consortia for telecom infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MIIT carbon content disclosure standards erect a compliance moat that favors incumbent manufacturers with established batch-level traceability systems, raising capital requirements for market entry while rewarding early adopters with preferred supplier status in domestic tenders.
For Market Incumbents: Anchor competitive position through backward integration into lead smelting capacity in Jiangsu province, eliminating electrode material cost exposure that erodes margins during London Metal Exchange price spikes. Defend against lithium iron phosphate substitution in two-to-four hour duration applications by accelerating hybrid technology licensing to mid-market solar-plus-storage developers in Gujarat and Maharashtra. Prioritize certification investment for BIS cycle-life testing to shorten validation timelines for Indian import tenders.
For New Entrants and Emerging Players: India's CEA rural electrification guidelines open a window for specialized valve-regulated lead acid configurations targeting agricultural pumping stations with high-temperature tolerance requirements. Focus initial penetration on Nigeria's infrastructure-as-a-service tower company market, where performance-guaranteed contracts displace capital equipment sales and favor service-oriented entrants over manufacturing-heavy incumbents. Pursue go-to-market partnerships with Jiangsu province carbon additive suppliers to secure consistent charge acceptance specifications without proprietary R&D investment.
For Investors and Strategic Acquirers: Shifts in African telecom procurement from equipment ownership to service contracting is the leading indicator that asset-light business models will capture disproportionate value in emerging market deployments. Frame long-term viability around chemistry diversification strategies that hedge against lithium-ion cost curves while retaining lead carbon's temperature tolerance advantages in extreme climate zones. Target acquisition candidates with established MIIT GB/T compliance infrastructure and existing BIS certification for Indian market access. Monitor FERC grid interconnection rulemakings for signals of duration requirement shifts that could expand or contract addressable market for four-to-eight hour storage chemistry.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive electrode material supply eliminates London Metal Exchange price exposure for Jiangsu province producers. |
| Hybrid Technology Licensing | Carbon-enhanced negative plate formulations open mid-market solar-plus-storage segments in Indian state tenders. |
| MIIT GB/T Compliance Certification | Batch-level traceability systems secure preferred supplier status in Chinese domestic stationary storage procurement. |
| Infrastructure-as-a-Service Contracting | Performance-guaranteed service models displace equipment sales in Nigeria's tower company market. |
| BIS Cycle-Life Testing Investment | Accelerated validation timelines enable faster market entry for Indian renewable energy integration projects. |
Research Methodology
Document review covered MIIT regulatory filings, CEA rural electrification guidelines, BIS certification standards, and FERC grid interconnection dockets, complemented by interviews with battery manufacturing executives, telecom infrastructure procurement managers, renewable energy project developers, and lead smelting operations directors. Secondary validation drew from London Metal Exchange price data, customs import records for electrode materials, and utility-scale storage tender databases. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Historical capacity deployment patterns cross-referenced against expert panel input on carbon additive formulation roadmaps. The projection framework spans product architectures from flooded to valve-regulated lead acid, end-use segments from telecommunications to renewable energy, technology tiers from conventional to advanced carbon loading, and regional regulatory clusters spanning China, India, and Southeast Asia. CAGRs were derived from regression analysis of tender award volumes and manufacturing capacity announcements. Key forecast inputs include MIIT enforcement timelines for carbon disclosure and CEA mandate expansion rates for rural microgrid deployment.
The model assumes a particular technology adoption path favoring hybrid configurations in mid-market segments; alternative pathways involving accelerated lithium iron phosphate cost reduction would alter the outlook for two-to-four hour duration applications. Forecasts reflect assumptions regarding lead price stability, regulatory enforcement consistency, and telecom infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Inverter Battery Market
Batteries
Automotive AGM Battery Market
Batteries
Global Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
Molten Salt Battery Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Asia Power Tool Batteries Market
Batteries
Wood-Based Batteries Market
Batteries
Middle-East Battery Market
Batteries
Marine Low-Voltage Battery Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Low Temperature Battery Market
Batteries
Japan Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Behind-The-Meter (BTM) Battery Market