
 Submarine Lead-Acid Battery Market | 2026-2036
Submarine Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Lead-Acid Battery Market Insights
The shift toward valve-regulated lead-acid architectures is narrowing the performance gap with lithium-ion alternatives for non-nuclear submarine propulsion and auxiliary power. EnerSys leverages its tubular plate expertise to anchor long-cycle contracts with NATO-aligned naval shipyards. Saft Batteries competes through sealed maintenance-free designs optimized for constrained hull spaces. East Penn Manufacturing sustains domestic supply security for U.S. Navy submarine battery refurbishment programs.
Submarine lead-acid batteries are electrochemical energy storage systems using lead dioxide and sponge lead electrodes immersed in sulfuric acid electrolyte, engineered to deliver sustained deep-discharge currents at pressures exceeding 30 atmospheres for underwater vessel propulsion and silent-running operations. Flooded lead-acid cells still dominate retrofit demand from aging diesel-electric fleets, while absorbent glass mat variants capture margin pools in new-build programs where reduced maintenance access justifies premium positioning. Valve-regulated lead-acid technology leads growth in research submarine applications where hydrogen off-gassing constraints limit conventional vented designs.
FCC marine equipment standards, NATO STANAG submarine safety codes, and EPA hazardous material handling rules collectively shape cell chemistry approvals and fleet-wide replacement schedules. Naval forces must monitor evolving underwater drone integration requirements that could bifurcate procurement between large-format propulsion batteries and compact auxiliary packs.
Market Dynamics
Valve-regulated lead-acid technology is displacing flooded-cell architectures across NATO-aligned submarine fleets, compressing replacement cycles and reshaping supplier qualification requirements for naval shipyards.
Growth Catalysts
- NATO STANAG submarine safety codes:Mandates for reduced hydrogen off-gassing in battery compartments are accelerating fleet-wide upgrades from vented to sealed cell designs.
- Diesel-electric submarine retrofit programs:Aging underwater fleets in South Korea and Australia require deep-discharge battery replacements compatible with extended silent-running operations.
- Absorbent glass mat chemistry:Eliminates electrolyte maintenance access requirements, enabling battery placement in constrained hull sections previously unsuitable for flooded cells.
Market Restraints
- Lead price volatility:Primary lead ingot costs fluctuate with mining output from Australia and China, squeezing cell manufacturer margins on fixed-price naval contracts.
- Lithium-ion substitution pressure:Non-nuclear submarine programs in France and Sweden are evaluating solid-state lithium alternatives for propulsion duty cycles.
- Single-source sulfuric acid supply:Battery-grade electrolyte production concentrates among three European chemical processors, creating input vulnerability for Asian shipyards.
Strategic Opportunities
- Research submarine niche:Manned deep-ocean vessels operating below 6,000 meters require pressure-resistant VRLA packs with specialized terminal sealing.
- Underwater drone auxiliary power:Autonomous underwater vehicles need compact maintenance-free battery modules for extended survey missions.
- Japan's indigenous submarine construction:Tokyo's naval shipbuilding expansion creates demand for localized battery assembly and testing facilities.
Industry Challenges
- NATO qualification timelines:New cell designs require 18-24 months of pressure-chamber testing and sea trials before fleet approval.
- Legacy flooded-cell integration:Shipyards must maintain dual supply chains and technician training for mixed-architecture fleets during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Lead-Acid Battery Market |
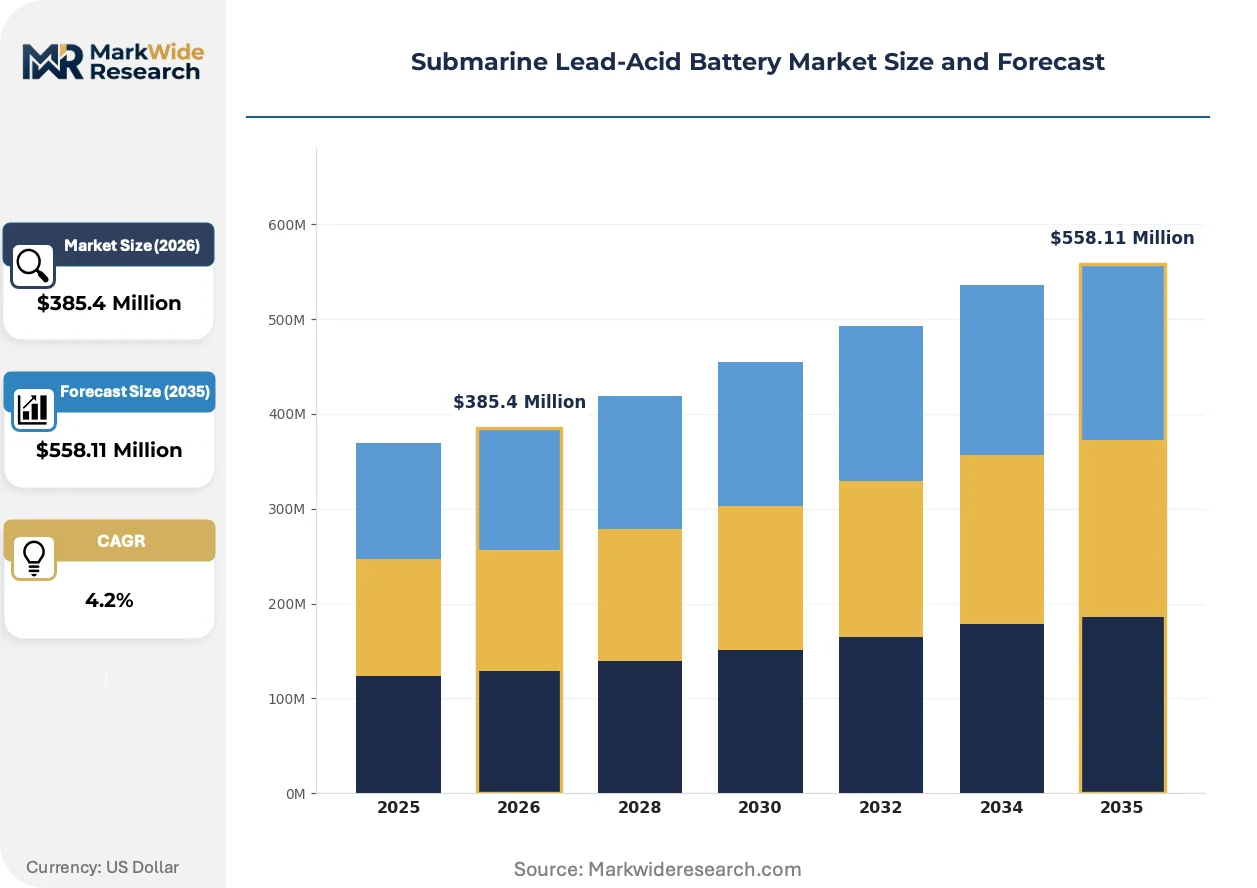
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flooded Lead-Acid, Valve-Regulated Lead-Acid, Absorbent Glass Mat, Gel, Carbon Batteries Technology: Sealed Maintenance-Free, Tubular Plate, Flat Plate, Spiral Wound, Lead-Calcium Alloy Application: Military Submarines, Research Submarines, Deep-Sea Exploration, Underwater Drones, Maritime Surveillance End User: Naval Forces, Scientific Organizations, Oil & Gas Explorers, Marine Contractors, Oceanographic Institutes |
| Companies Covered | EnerSys, Exide Technologies, Hawker Batteries, Saft Batteries, East Penn Manufacturing, ABL Power Systems, Concorde Battery, MarathonNorco Aerospace, Battery Builders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Lead-Acid Battery Market Trends and Innovations
Submarine battery engineering is pivoting toward maintenance-free architectures that compress total cost of ownership while extending operational depth ratings for conventional underwater fleets.
Tubular positive plate designs are migrating from industrial standby power into marine propulsion applications. Korean shipbuilders are specifying these architectures for new diesel-electric hulls. This migration from stationary to mobile duty cycles is narrowing the performance gap with advanced lithium-ion systems for non-nuclear underwater propulsion.
EPA hazardous material handling rules are tightening sulfuric acid containment standards for U.S. Navy battery refurbishment facilities. Shipyards must install secondary containment systems and automated neutralization equipment. Pacific Northwest naval stations are responding by consolidating battery maintenance operations at two certified sites.
Naval procurement offices are unbundling battery supply from platform construction contracts. Australian and Japanese defense ministries now source propulsion cells through separate competitive tenders, displacing sole-source shipyard arrangements. This shift is most visible in Canberra's Attack-class submarine program, where battery selection precedes hull construction awards.
Submarine Lead-Acid Battery Market Segmentation
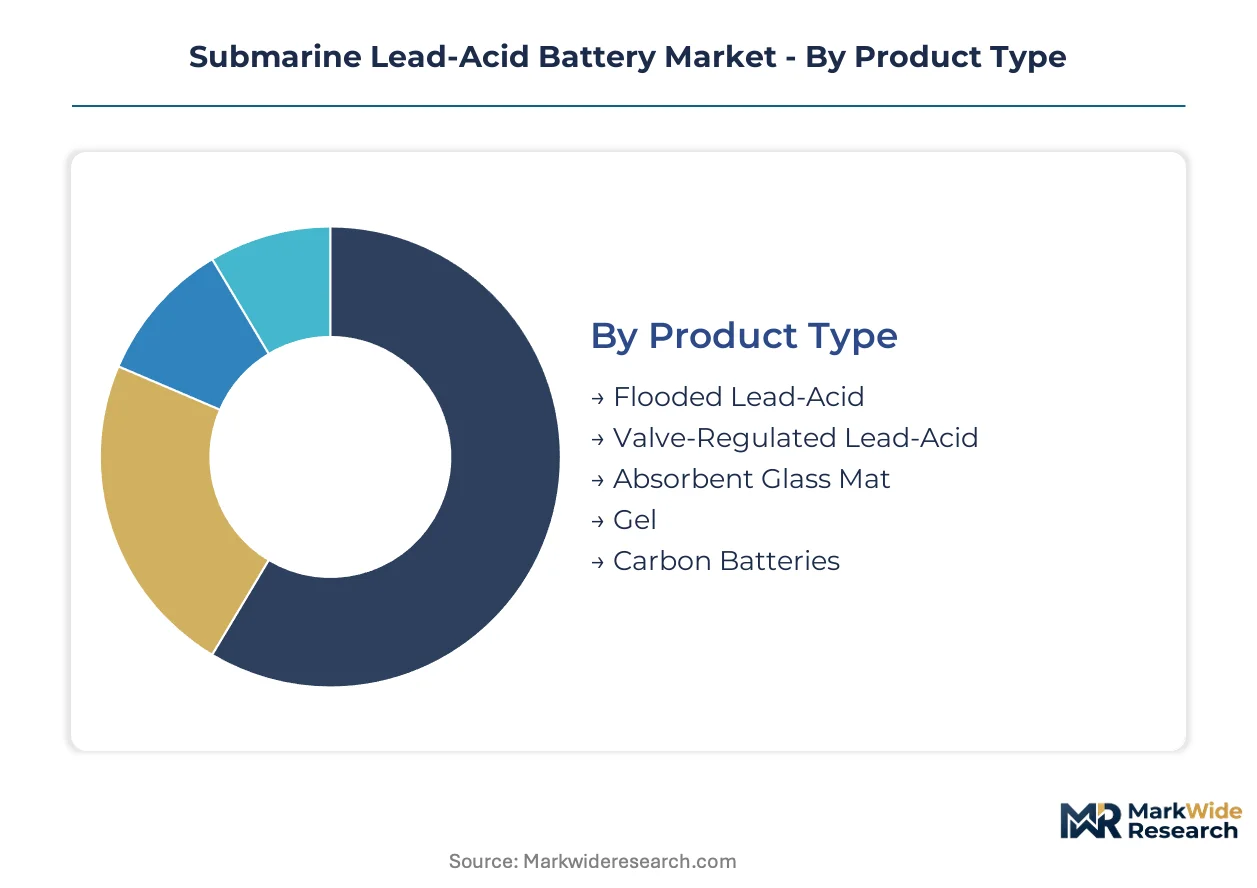
Segmentation in submarine lead-acid batteries reveals how procurement patterns diverge across pressure-rated applications and maintenance-access constraints. Technical specifications for deep-discharge cycles and hull-space limitations create distinct demand clusters that reshape supplier qualification requirements.
Product Type:
After-sales service intensity varies sharply across cell architectures, with flooded designs demanding quarterly electrolyte monitoring while sealed variants shift revenue toward replacement cycles rather than maintenance contracts.
- Flooded Lead-Acid:Vented cells with liquid sulfuric acid electrolyte require routine specific gravity checks and distilled water topping. South Korean naval shipyards specify these for retrofit programs on aging diesel-electric hulls where crew access to battery compartments remains unobstructed.
- Valve-Regulated Lead-Acid:Sealed recombinant designs eliminate electrolyte maintenance through internal oxygen recombination. Australian Attack-class procurement favors VRLA packs for new-build pressure hull sections where technician access is severely constrained.
- Absorbent Glass Mat:Electrolyte suspended in fiberglass mat separators enables vibration-resistant mounting. Japan's indigenous submarine construction programs specify AGM for silent-running auxiliary power.
- Gel:Silica-thickened electrolyte prevents stratification in tilted installations. Research submarines operating at extreme pitch angles adopt gel chemistry for stability.
- Carbon Batteries:Lead-carbon hybrid electrodes enhance partial state-of-charge tolerance. Emerging interest from extended-range underwater drone programs drives pilot contracts.
By volume, Flooded Lead-Acid leads. By growth pace, Valve-Regulated Lead-Acid is ahead.
Technology:
Cost tier stratification separates premium tubular plate architectures from commodity flat plate alternatives, with alloy composition choices determining cycle life warranties and depth rating certifications.
- Sealed Maintenance-Free:Recombinant gas technology eliminates watering requirements entirely. NATO STANAG safety codes accelerate fleet-wide conversion to this architecture for reduced hydrogen accumulation risk.
- Tubular Plate:Cylindrical positive electrodes with active material packed inside lead alloy spines deliver superior deep-cycle endurance. Korean shipbuilders specify tubular designs for new diesel-electric propulsion systems.
- Flat Plate:Conventional pasted grid construction offers lower capital cost for auxiliary power applications. U.S. Navy refurbishment programs maintain flat plate supply chains for budget-constrained lifecycle extensions.
- Spiral Wound:Cylindrical cell geometry with tightly wound electrodes enables high-rate discharge. Compact form factor suits underwater drone battery modules where space is at premium.
- Lead-Calcium Alloy:Reduced antimony content minimizes water loss and self-discharge. Stationary standby applications in shore-based submarine support facilities favor this chemistry.
By volume, Flat Plate leads. By value capture, Tubular Plate is expanding most quickly.
Application:
Customer type differentiation separates sovereign naval procurement with decade-long qualification timelines from commercial expeditions demanding rapid field replacement.
- Military Submarines:Diesel-electric and air-independent propulsion systems require pressure-rated deep-discharge banks. South Korea, Japan, and Australia drive demand through indigenous construction and fleet modernization.
- Research Submarines:Manned deep-ocean vessels operating below 6,000 meters need specialized terminal sealing and pressure-compensated electrolyte systems.
- Deep-Sea Exploration:Battery-powered submersibles for commercial resource survey operate on multi-day missions with strict weight constraints.
- Underwater Drones:Autonomous vehicles need compact maintenance-free modules for extended survey missions without recovery.
- Maritime Surveillance:Coastal monitoring submersibles require silent-running capabilities for acoustic discretion.
By volume, Military Submarines leads. By growth pace, Underwater Drones is climbing the fastest.
End User:
Supply concentration patterns differ markedly between state-controlled naval procurement with sole-source qualification requirements and fragmented scientific contracting with competitive tender processes.
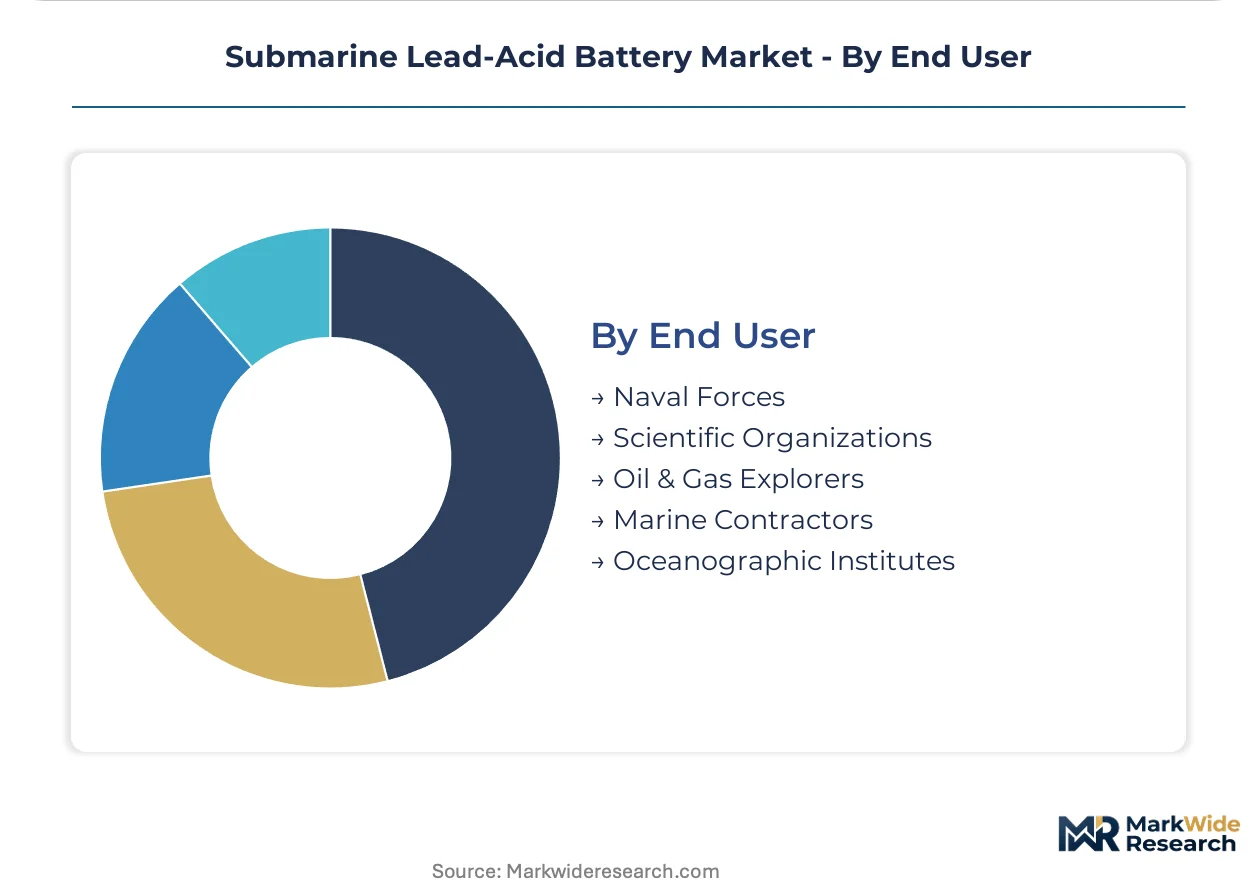
- Naval Forces:Sovereign defense procurement offices specify pressure-tested designs through multi-year framework agreements. Australian and Japanese defense ministries now unbundle battery selection from platform construction.
- Scientific Organizations:Academic research institutions operating leased submersibles prioritize total cost of ownership over capital expenditure.
- Oil & Gas Explorers:Commercial seabed survey contractors demand rapid battery swap capability to minimize vessel downtime.
- Marine Contractors:Infrastructure inspection and cable-laying support vessels need reliable auxiliary power for dynamic positioning.
- Oceanographic Institutes:Government-funded research bodies balance mission duration against maintenance access limitations in remote expedition contexts.
By volume, Naval Forces leads. By contract value growth, Scientific Organizations is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical processors export battery-grade sulfuric acid electrolyte to South Korean and Australian shipyards, anchoring a transcontinental supply corridor that feeds NATO-aligned submarine construction programs.
South Korea
DSME and Hyundai Heavy Industries drive demand through indigenous KSS-III submarine construction and retrofit programs for aging Chang Bogo-class hulls. The Defense Acquisition Program Administration mandates localized battery assembly under offset agreements. Busan-Ulsan shipbuilding clusters host pressure-chamber testing facilities for valve-regulated lead-acid qualification.
Japan
Mitsubishi Heavy Industries and Kawasaki Shipbuilding expand Soryu-class successor programs requiring maintenance-free battery architectures. METI naval procurement guidelines prioritize sealed recombinant designs for reduced hydrogen risk. Kobe-Osaka industrial corridors concentrate tubular plate manufacturing for diesel-electric propulsion systems.
Australia
Canberra's Attack-class program unbundles battery selection from platform construction, creating standalone competitive tenders for propulsion cells. The Department of Defence mandates NATO STANAG safety compliance for all submarine battery installations. Adelaide shipbuilding precincts host qualification trials for absorbent glass mat variants in constrained hull sections.
United States
Electric Boat and Newport News Shipyard sustain Virginia-class auxiliary battery refurbishment demand through decade-long lifecycle contracts. EPA hazardous material handling rules tighten sulfuric acid containment standards at Pacific Northwest naval stations. Groton and Bremerton facilities consolidate battery maintenance operations under consolidated certification.
Sweden
Saab Kockums evaluates solid-state lithium alternatives for Gotland-class successor programs, pressuring lead-acid suppliers to demonstrate cost-performance parity. The Swedish Defence Materiel Administration funds hybrid propulsion research. Karlskrona naval base hosts comparative sea trials for sealed lead-acid against emerging chemistries.
Submarine Lead-Acid Battery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where NATO qualification timelines create steep barriers to entry. The vendor base separates into three tiers: integrated energy-systems conglomerates with naval shipyard relationships, dedicated marine battery specialists with pressure-rating expertise, and regional fabricators serving refurbishment demand. Dominant competitive moves include capacity consolidation around certified pressure-chamber testing facilities and backward integration into lead-calcium alloy casting to secure input cost stability.
Among North American industrial battery manufacturers, EnerSys, Exide Technologies, and East Penn Manufacturing occupy positions spanning the integrated-to-specialist spectrum. EnerSys exemplifies the conglomerate archetype with tubular plate expertise anchoring long-cycle NATO contracts. Exide Technologies sits within the mid-tier specialist category, leveraging sealed maintenance-free architectures for constrained hull applications. East Penn Manufacturing represents the domestic supply-security anchor, sustaining U.S. Navy refurbishment programs through flat plate production.
| Leading Market Players |
|---|
| EnerSys |
| Exide Technologies |
| Hawker Batteries |
| Saft Batteries |
| East Penn Manufacturing |
| ABL Power Systems |
| Concorde Battery |
| MarathonNorco Aerospace |
| Battery Builders |
| Others |
Pricing and Supply Chain Analysis
Busan-Ulsan shipbuilding clusters anchor Korean pressure-chamber testing capacity, concentrating qualification leverage among three certified facilities and compressing margin negotiation room for European sulfuric acid suppliers serving Asian naval programs.
Pricing Analysis
Cost-plus contracts with London Metal Exchange lead indexation dominate NATO-aligned procurement, with premium-mid-economy pricing differentiation separating tubular plate architectures from flat plate alternatives. Certification grade under STANAG submarine safety codes commands substantial premia over uncertified commercial equivalents. Cost compression in flooded-cell refurbishment tiers intensifies because Australian and Japanese defense ministries unbundle battery selection from platform construction. Scientific organizations operating leased research submersibles exhibit highest price sensitivity, while sovereign naval procurement offices prioritize pressure-rating warranties over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and South Korea dominates electrolyte logistics, as three European chemical processors feed battery-grade sulfuric acid to Asian shipyards under long-term offtake arrangements. Primary lead ingot supply concentrates in Australia, China, and domestic U.S. smelters, with lead-calcium alloy casting capacity tethered to Korean and Japanese industrial corridors. Single-source vulnerability in certified pressure-chamber testing equipment creates chokepoint risk for new entrant qualification. Distribution runs through sovereign defense procurement frameworks with decade-long framework agreements, displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure-rated battery engineering talent concentrates among retiring specialists at Korean and Australian naval shipyards, constraining expansion velocity for suppliers lacking captive qualification expertise.
For Market Incumbents: Insulate tubular plate margins through backward integration into lead-calcium alloy casting at Busan-Ulsan facilities, while accelerating NATO STANAG certification investment to forestall solid-state lithium substitution pressure from Swedish hybrid propulsion programs. Channel control through exclusive pressure-chamber testing partnerships with DSME and Hyundai Heavy Industries reinforces replacement cycle capture. For New Entrants and Emerging Players: Japan's indigenous submarine construction programs represent underpenetrated white space, as METI procurement guidelines favor localized assembly under offset agreements absent established supplier relationships. Research submarine niche applications below 6,000 meters offer secondary entry path with reduced qualification timelines. Target carbon battery pilot contracts for extended-range underwater drone programs as technology demonstration platform. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive pressure-rating expertise over pure-play component suppliers. Long-term viability rests on decade-long sovereign defense procurement visibility rather than commercial expedition cyclicality. Watch Swedish Defence Materiel Administration hybrid propulsion research funding levels as inflection indicator for lead-acid displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure-Chamber Testing Capacity Expansion | Busan-Ulsan consolidation creates qualification bottleneck for new entrant certification. |
| Backward Integration into Lead-Calcium Alloy Casting | Korean shipbuilders specify captive alloy supply for STANAG-compliant tubular plate production. |
| Carbon Battery Pilot Program Launch | Extended-range underwater drone procurement at Australia's Defence Science and Technology Group validates partial state-of-charge tolerance. |
| Localized Assembly Joint Venture | Japan's METI offset agreements mandate domestic battery testing facilities for Soryu-class successor programs. |
| Sealed Maintenance-Free Certification Pathway | NATO STANAG hydrogen off-gassing mandates accelerate fleet-wide conversion from flooded-cell architectures. |
Research Methodology
Operator-level perspectives from submarine battery engineering directors, naval shipyard procurement officers, pressure-chamber testing facility managers, and defense ministry acquisition specialists anchored the qualitative base. Secondary validation drew from NATO STANAG documentation, EPA hazardous material handling rule filings, customs trade data for battery-grade sulfuric acid, and Korean Defense Acquisition Program Administration offset agreement disclosures. Bottom-up demand modeling across military submarine, research submarine, and underwater drone applications triangulated against top-down lead-acid industrial battery production capacity assessments.
Scenario-bracketing around lithium-ion substitution velocity and NATO qualification timeline compression framed the analytical approach across the analysis window. Segmentation dimensions modeled included product type architecture, pressure-rating certification tier, application duty cycle, and end-user procurement framework. CAGRs derived from exponential smoothing of replacement cycle frequencies and indigenous construction program announcements. Industry-specific forecast inputs incorporated Korean KSS-III hull delivery schedules and Australian Attack-class battery tender sequencing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state lithium developers or accelerated unbundling of battery procurement by additional NATO-aligned defense ministries would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Automotive Start-Stop Battery Market
Batteries
Battery Swapping Market
Batteries
Utility Battery Market
Batteries
Battery Wash System Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Nanicl Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Flow Battery Market
Batteries
North America NMC Battery Pack Market
Batteries
Molten Salt Battery Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
Battery Plate Market
Batteries
Semi-Solid Flow Battery Market