
 PERC Battery Market | 2026-2036
PERC Battery Market Size, Share, and Industry Trends Forecast 2026-2036
PERC Battery Market Insights
A capital-intensity divergence between polysilicon ingot producers and cell fabricators is reorganizing competitive hierarchies in PERC manufacturing. Tongwei leverages captive polysilicon supply to sustain margin resilience against wafer price volatility. Longi anchors its position through monocrystalline wafer scale and downstream module integration. LG Energy Solution competes by specializing in high-efficiency cell exports to European utility developers.
Passivated Emitter and Rear Contact cells employ dielectric passivation layers and localized rear-point contacts to suppress electron recombination, achieving conversion efficiencies exceeding 23 percent in commercial production. The technology serves grid-scale photovoltaic generation and distributed rooftop systems where levelized cost of electricity drives procurement decisions. Monocrystalline PERC dominates installed capacity given superior efficiency metrics, while bifacial architectures capture expanding share in utility applications through dual-side energy yield. The utility end-user segment concentrates procurement volume, though residential demand accelerates in markets with net-metering frameworks.
China's MIIT enforces GB standards for photovoltaic cell efficiency thresholds, while the EU Green Deal's carbon border adjustments reshape import competitiveness for non-European cell manufacturers. The US IRA production tax credits incentivize domestic PERC assembly capacity expansion. Stakeholders must monitor evolving efficiency mandates and trade remedy proceedings to align capacity investments with qualifying supply chain geographies.
Market Dynamics
China's dual carbon goals and the EU Green Deal's carbon border adjustments are compressing margins for non-integrated PERC manufacturers while rewarding captive polysilicon supply chains. This regulatory divergence is fragmenting competitive advantage along vertical integration lines.
Growth Catalysts
- Utility-scale solar procurement:Grid operators in Germany and Spain prioritize high-efficiency bifacial PERC modules for auction-tied capacity additions, accelerating demand for 23%+ conversion efficiency architectures.
- MIIT efficiency mandates:China's GB standards for photovoltaic cell thresholds force technology upgrades across Jiangsu and Zhejiang manufacturing clusters, consolidating output toward leading producers.
- US IRA production incentives:Domestic assembly tax credits under the Inflation Reduction Act attract module fabricators to establish PERC cell capacity within qualifying supply chain geographies.
Market Restraints
- Polysilicon price volatility:Ingot supply concentration in Xinjiang exposes non-integrated cell fabricators to input cost swings that erode wafer-thin fabrication margins.
- TOPCon substitution pressure:Tunnel oxide passivated contact cells achieve 24%+ efficiency in pilot production, threatening PERC's technology lifecycle as utility procurement shifts toward next-generation architectures.
- EU carbon border friction:The Green Deal's CBAM mechanism imposes embodied carbon reporting requirements on imported Chinese modules, raising compliance costs for non-European supply chains.
Strategic Opportunities
- Agrivoltaic deployment:Bifacial PERC installations on agricultural land in Italy and Greece unlock dual-use revenue streams for farmers while meeting national renewable targets.
- US domestic supply chain:The IRA's 45X manufacturing credit creates a 10-year window for polysilicon-to-module vertical builds in Arizona and Texas.
- TOPCon-PERC hybrid lines:Equipment retrofit pathways allow incumbent cell fabricators to bridge technology generations without full greenfield capex commitments.
Industry Challenges
- Process engineering talent scarcity:Passivation layer optimization and laser contact opening require specialized semiconductor fabrication skills that concentrate in East Asian equipment vendor ecosystems.
- Certification timeline compression:IEC 61215 and IEC 61730 testing protocols for bifacial PERC variants extend module qualification cycles, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PERC Battery Market |
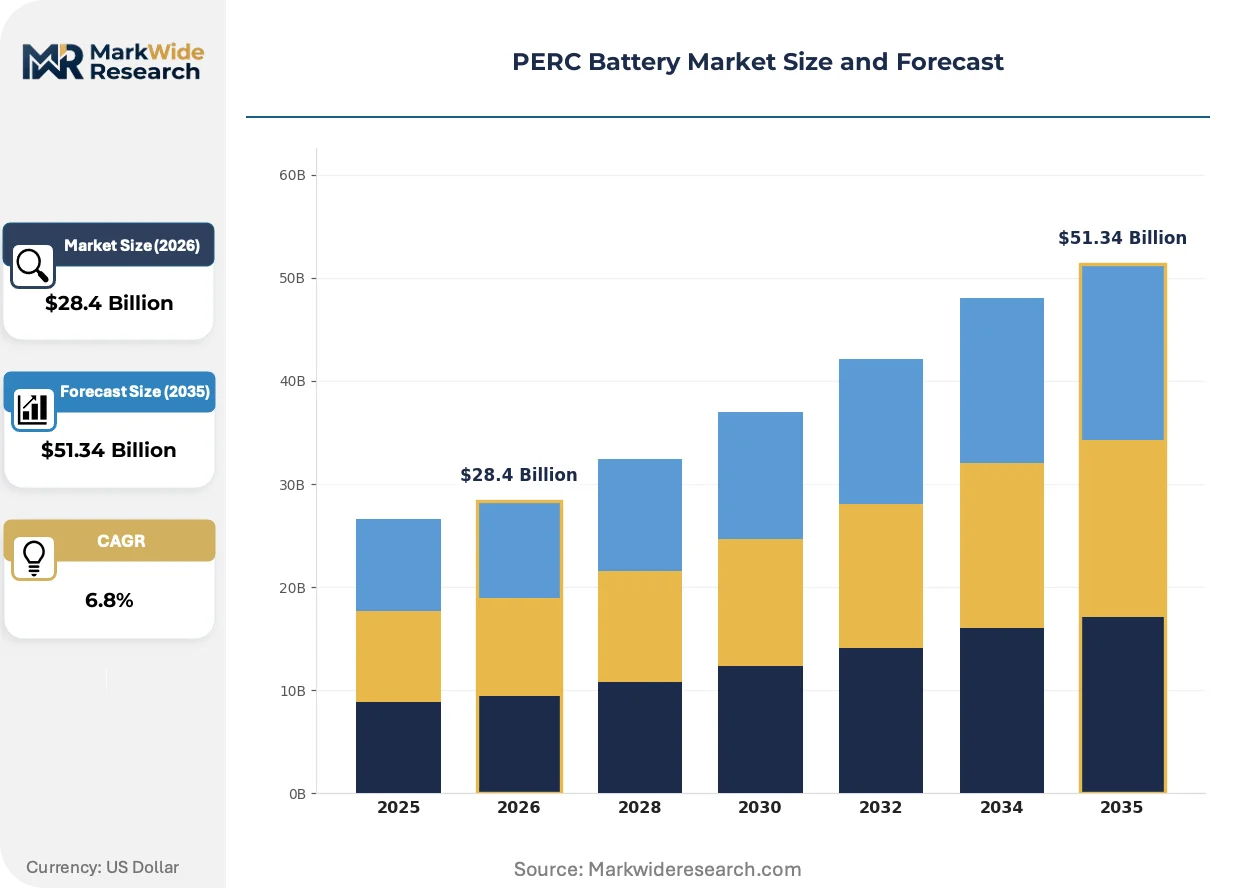
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Heterojunction End User: Utility, Residential, Commercial, Industrial Application: Energy Storage, Grid Integration, Off-Grid Solutions, Transportation Technology: Silicon-Based, Thin-Film, Advanced Recycling, SMART Integration |
| Companies Covered | CATL, LG Energy Solution, Panasonic Holdings Corporation, BYD Company Limited, Samsung SDI, Tongwei, Longi, SK Innovation, EVE Energy Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PERC Battery Market Trends and Innovations
Dielectric passivation architectures and laser processing techniques are decomposing the cost-efficiency frontier for commercial photovoltaic generation. Equipment suppliers and cell fabricators are racing to extend PERC's technology runway against next-generation alternatives.
ALD-deposited alumina rear surface passivation is decomposing the efficiency ceiling for monocrystalline PERC architectures. European utility developers now specify this layer configuration in tender documents. The technology is decomposing the price premium once commanded by heterojunction alternatives in distributed generation segments.
The EU Green Deal's carbon border adjustment mechanism is reshaping import competitiveness for photovoltaic supply chains. Non-European cell manufacturers face escalating compliance burdens for embodied carbon documentation. Chinese exporters are responding by relocating polysilicon refining and ingot pulling to lower-carbon electricity grids in Yunnan and Sichuan provinces.
Aggregated procurement by European independent power producers is consolidating buyer power against module suppliers. Long-term offtake agreements now specify efficiency degradation curves and bifaciality coefficients rather than simple wattage ratings. This behavioral shift is most pronounced in Spanish and Portuguese utility-scale auctions where levelized cost of electricity drives vendor selection.
PERC Battery Market Segmentation
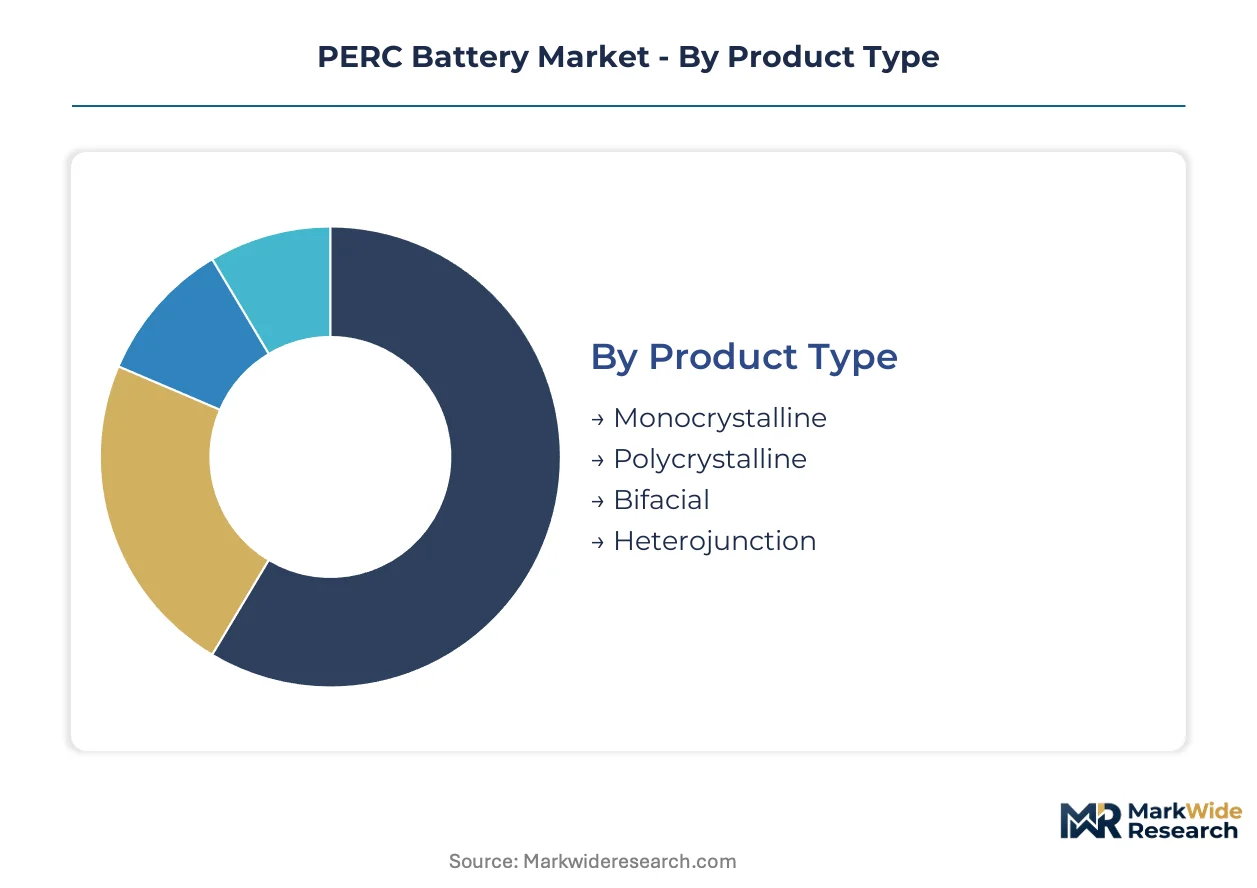
Segmentation in the PERC battery market reveals how efficiency thresholds, procurement scale, and integration complexity reshape vendor selection criteria across distinct customer and technology profiles. Manufacturers align capacity investments with the margin characteristics of each segment cluster.
Product Type:
Margin pools concentrate in architectures that command efficiency premiums from utility-scale developers and distributed generation installers.
- Monocrystalline:Silicon ingots from single-crystal boules deliver conversion efficiencies exceeding 23 percent in commercial production. Demand concentrates in Jiangsu and Zhejiang manufacturing clusters serving European utility developers who specify GB-standard efficiency thresholds in procurement tenders.
- Bifacial:Dual-side energy capture through transparent rear-side passivation layers enables 10-20 percent yield uplift in utility-scale deployments. Procurement from Spanish and Portuguese independent power producers now mandates bifaciality coefficients in long-term offtake agreements.
- Polycrystalline:Multi-crystalline wafers from directional solidification furnaces trade efficiency for lower capital intensity. Cost-sensitive distributed installers in emerging markets specify this architecture where space constraints are secondary.
- Heterojunction:Amorphous silicon layers deposited on crystalline substrates achieve superior temperature coefficients. Japanese and South Korean equipment vendors dominate the specialized CVD tool supply chain for this architecture.
Monocrystalline PERC holds installed capacity. Bifacial is rotating up the share rankings.
End User:
Procurement scale and contract duration vary sharply across customer types, with utility offtake driving volume and residential segments demanding financing flexibility.
- Utility:Grid operators in Germany and Spain procure multi-gigawatt tranches through auction-tied capacity additions. German TSOs specify 25-year degradation curves and bifacial performance guarantees in framework agreements.
- Residential:Net-metering frameworks in Italy and Australia accelerate rooftop deployment where homeowners prioritize payback period over absolute efficiency. Installer networks in these markets demand module-level power electronics integration.
- Commercial:C&I off-takers with behind-the-meter load profiles optimize for peak shaving and demand charge reduction. Warehouse operators in Texas and Arizona specify PERC modules with IRA-compliant domestic content for tax credit eligibility.
- Industrial:Energy-intensive manufacturers with 24/7 load requirements prioritize reliability and warranty terms over upfront cost. Aluminum smelters and data centers in Norway and Iceland source modules matched to their carbon-free electricity procurement strategies.
Utility procurement absorbs manufacturing volume. Residential is gaining share fastest.
Application:
Integration complexity and system architecture requirements fragment the addressable market by use case.
- Grid Integration:Utility-scale solar farms with centralized inverters and high-voltage transmission interconnection demand modules with tight power tolerance and low temperature coefficients. Spanish and Portuguese auction winners specify these performance characteristics.
- Energy Storage:DC-coupled battery-PV hybrid systems require module-level power electronics and communication protocols. US developers in Arizona and Texas optimize configurations for IRA production tax credit stacking.
- Off-Grid Solutions:Standalone systems with battery backup prioritize reliability and low-light performance over peak efficiency. Rural electrification programs in Sub-Saharan Africa and Southeast Asia specify these architectures.
- Transportation:Vehicle-integrated photovoltaics and charging infrastructure applications demand lightweight, flexible form factors. European automotive OEMs pilot these integrations for commercial fleet electrification.
Grid integration commands deployment scale. Energy storage is climbing the fastest.
Technology:
Manufacturing process differentiation and supply chain qualification requirements stratify competitive positioning.
- Silicon-Based:Crystalline silicon wafers processed through diffusion, passivation, and metallization steps dominate commercial production. Chinese MIIT efficiency mandates force continuous tool upgrades across Jiangsu fabrication lines.
- Thin-Film:Cadmium telluride and CIGS deposition on glass substrates offers manufacturing cost advantages at lower efficiency. First Solar maintains specialized capacity for US utility projects with domestic content requirements.
- Advanced Recycling:End-of-life module recovery and semiconductor material reclamation emerging as regulatory compliance capability. EU Green Deal circular economy directives mandate producer responsibility frameworks.
- SMART Integration:Module-level monitoring, optimization, and rapid shutdown electronics embedded at manufacturing stage. NEC compliance in US jurisdictions drives specification of these integrated architectures.
Silicon-based technology holds manufacturing capacity. SMART integration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers in Spain and Germany prioritize bifacial PERC modules for auction-tied capacity, while Chinese manufacturing clusters optimize for monocrystalline cell efficiency thresholds. Residential rooftop demand in Australia and Italy accelerates under net-metering frameworks that emphasize payback period over absolute conversion rates.
China
Jiangsu and Zhejiang fabrication clusters process the majority of global PERC cell output for export markets. MIIT enforces GB efficiency standards that force continuous equipment upgrades across monocrystalline production lines. Tongwei leverages captive polysilicon supply in Sichuan to sustain margin resilience against wafer price volatility.
Germany
Grid operators specify 25-year degradation curves and bifacial performance guarantees in multi-gigawatt framework agreements. The EU Green Deal's carbon border adjustment mechanism raises compliance costs for imported modules from non-European supply chains. Bavarian utility developers anchor procurement volume for high-efficiency architectures in auction-tied capacity additions.
United States
Developers in Arizona and Texas optimize DC-coupled battery-PV hybrid configurations for IRA production tax credit stacking. The 45X manufacturing credit creates a 10-year window for polysilicon-to-module vertical builds in qualifying supply chain geographies. Warehouse operators specify IRA-compliant domestic content for behind-the-meter peak shaving applications.
Spain
Independent power producers consolidate buyer power through aggregated procurement that mandates bifaciality coefficients in long-term offtake agreements. National renewable targets accelerate utility-scale deployment in Andalusia and Extremadura. Auction winners specify tight power tolerance and low temperature coefficients for centralized inverter configurations.
Australia
Net-metering frameworks accelerate residential rooftop deployment where homeowners prioritize payback period metrics. Installer networks demand module-level power electronics integration for NEC compliance. Queensland and New South Wales concentrate distributed generation procurement volume.
PERC Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in PERC manufacturing. Captive polysilicon supply and downstream module integration separate margin-resilient players from fabrication-only competitors. Three archetypes dominate: vertically integrated polysilicon-to-module producers, pure-play cell fabricators, and battery-integrated energy storage specialists. Capacity expansion and strategic partnerships constitute the primary competitive moves as manufacturers navigate technology transition risks.
Among Chinese fabricators, Tongwei and Longi occupy positions within the integrated tier, while LG Energy Solution exemplifies the specialist archetype focused on high-efficiency cell exports. These three anchors represent distinct strategic postures: captive supply chain control, monocrystalline wafer scale, and premium export specialization respectively.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| Samsung SDI |
| Tongwei |
| Longi |
| SK Innovation |
| EVE Energy Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Gigawatt-scale wafer processing in Jiangsu and Zhejiang manufacturing clusters compresses unit economics for monocrystalline PERC cells while simultaneously concentrating supply-side leverage among integrated producers. This scale dynamic establishes price floors that fabrication-only competitors cannot match without captive polysilicon supply or downstream module integration.
Pricing Analysis
After-sales service contracts covering degradation monitoring and performance guarantees drive lifetime value for utility-scale developers. Long-term offtake agreements employ contract-based pricing with efficiency-tier differentiation tied to GB-standard certification levels from China's MIIT. Cost compression in standard-efficiency tiers is intensifying because TOPCon pilot production achieves 24%+ conversion rates, forcing PERC fabricators to defend margins through bifaciality premiums. Distributed installers in residential segments exhibit highest price sensitivity, while European independent power producers prioritize 25-year degradation curves over upfront module cost.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo port congestion shape module delivery economics for European utility developers. Polysilicon ingot supply concentrates in Xinjiang, Sichuan, and Yunnan provinces, with cell fabrication drawing from high-purity metallurgical-grade silicon and silver paste metallization materials. Single-source vulnerability in Xinjiang polysilicon refining exposes non-integrated fabricators to input cost volatility and EU carbon border compliance burdens. Distribution runs through module integrators with downstream EPC partnerships for utility-scale deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance guarantee and O&M service contracts represent the fastest-expanding revenue layer in PERC markets, with attach rates climbing faster than hardware shipments as utility developers prioritize bankability over upfront capital cost.
For Market Incumbents: Shield margin resilience through backward integration into Sichuan and Yunnan polysilicon supply chains with low-carbon electricity sourcing. Prioritize certification investment for EU Green Deal CBAM compliance before carbon border adjustments fully phase in. Defend position against TOPCon substitution by retrofitting existing lines for bifacial PERC-plus architectures rather than greenfield capacity commitments. For New Entrants and Emerging Players: Differentiate on agrivoltaic application engineering for Italian and Greek dual-use land deployments where incumbent module suppliers lack specialized mounting and agricultural integration expertise. Target US domestic content compliance for IRA 45X credit eligibility in Arizona and Texas manufacturing geographies. Lead with DC-coupled battery-PV hybrid system design as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated polysilicon-to-module producers with captive utility offtake agreements spanning multi-gigawatt tranches. Long-term viability over a 5-10 year window favors acquisition targets with Yunnan or Sichuan polysilicon assets and established European certification pathways. Watch TOPCon equipment retrofit timelines as the inflection signal for PERC technology runway extension.| Strategic Initiative | Industry Significance |
|---|---|
| Polysilicon Capacity Buildout | Yunnan and Sichuan ingot pulling secures low-carbon supply for EU CBAM compliance. |
| Bifacial Module Certification | IEC 61215 bifacial variant testing unlocks Spanish and Portuguese auction eligibility. |
| Agrivoltaic Joint Venture | Italian landowner partnerships create dual-use revenue streams with agricultural integration. |
| IRA Domestic Supply Chain | Arizona and Texas vertical builds qualify for 45X manufacturing credit stacking. |
| TOPCon-PERC Retrofit | Equipment conversion pathways bridge technology generations without full greenfield investment. |
Research Methodology
Operator-level perspectives from cell fabrication engineers, utility procurement managers, EPC contractors, and polysilicon supply planners anchored the qualitative base for this study. Primary interviews with Jiangsu and Zhejiang manufacturing cluster operators combined with secondary validation from MIIT GB standard filings, EU Green Deal regulatory texts, FERC interconnection queues, and IEA photovoltaic deployment databases. Bottom-up capacity utilization data and top-down auction volume aggregation enabled triangulation across modeling approaches.
Sensitivity analysis tested demand trajectories against polysilicon price volatility, EU carbon border adjustment stringency, and TOPCon substitution velocity across the projection horizon. Segmentation dimensions modeled include cell architecture type, end-user procurement scale, application integration complexity, and regional regulatory framework cluster. CAGRs derived from installed capacity buildout curves and module average selling price evolution through the analysis window. Forecast inputs incorporated MIIT efficiency mandate compliance timelines and IRA domestic content qualification thresholds.
Decision-makers should treat outputs as directional under base assumptions of continued bifacial PERC technology relevance and stable EU-China trade pathways; material deviation would warrant model refresh. Forecasts reflect assumptions of policy continuity for production tax credits and carbon border mechanisms. Specific risk factors that could revise projections include abrupt TOPCon cost parity achievement, EU CBAM expansion to embodied carbon intensity thresholds, or Xinjiang supply chain sanctions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Printable Battery Market
Batteries
Stretchable Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
Molten Salt Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Printed Batteries Market
Batteries
Portable Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Aluminum-Air Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
Micro Battery Market
Batteries
East Africa Battery Market
Batteries
Taiwan Battery Market
Batteries
Lithium Marine Battery Market