
 UAV Battery Pack Market | 2026-2036
UAV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Battery Pack Market Insights
Defense procurement is shifting toward extended-endurance platforms while agricultural monitoring contracts flatten. DJI leverages its manufacturing scale to dominate consumer and commercial multirotor segments globally. Shenzhen Grepow Battery Co., Ltd. specializes in high-discharge lithium polymer cells for racing and industrial drones. EaglePicher Technologies anchors military-grade solid-state development with decades of aerospace battery heritage.
A UAV battery pack is an integrated electrochemical energy storage and power management system, typically rated between 3.7V and 48V nominal, designed to deliver sustained current under variable load profiles during flight operations. Solid-state chemistry variants promise higher energy density with reduced thermal runaway risk compared to conventional lithium-ion architectures. Lithium polymer configurations lead in multirotor applications due to their form-factor flexibility and high discharge rates, while fixed-wing platforms increasingly favor lithium-ion for longer mission profiles where weight-to-capacity ratios determine range. Defense end users concentrate purchasing power around MIL-STD-810G certified packs, creating a margin pool distinct from commercial segments.
The FAA governs commercial UAV operations under Part 107, indirectly shaping battery safety certification requirements for flight authorization. China's MIIT enforces GB standards on lithium battery transport and manufacturing, affecting export-oriented suppliers. The EU AI Act and CE marking frameworks extend to autonomous drone systems, embedding battery traceability into market access protocols. Stakeholders must track evolving chemistry-specific regulations across jurisdictions to align R&D pipelines with compliance timelines.
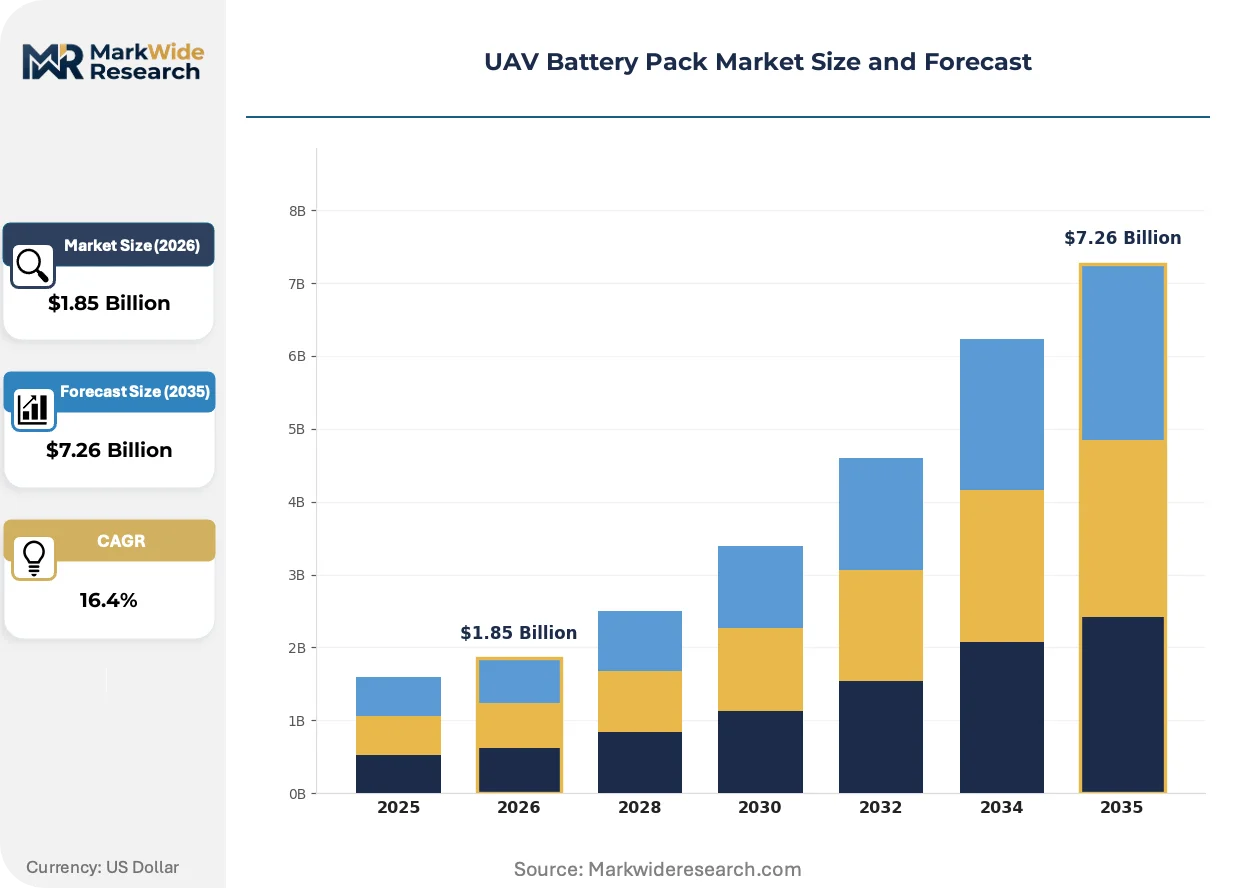
Market Dynamics
Lithium-sulfur chemistry advances are compressing energy density benchmarks while defense procurement tightens certification requirements around MIL-STD-810G standards, creating a bifurcation between military-grade and commercial battery architectures.
Growth Catalysts
- FAA Part 107 commercial authorization:Expanded flight permissions for beyond-visual-line-of-sight operations are extending mission profiles and driving demand for higher-capacity packs.
- Agricultural precision spraying:Crop monitoring fleets in the United States and China are replacing fuel-powered ground equipment with electric UAV systems requiring rapid-swap battery logistics.
- Lithium-sulfur energy density gains:Laboratory-scale prototypes are achieving theoretical capacity multiples above lithium-ion, attracting defense R&D funding for endurance-critical reconnaissance platforms.
Market Restraints
- Cobalt and lithium carbonate price volatility:Raw material input swings compress margins for pack assemblers unable to pass through costs to fixed-price government contracts.
- Cell manufacturing concentration in East Asia:Dependence on cylindrical and prismatic cell supply from China creates geopolitical exposure for Western defense integrators.
- Thermal runaway containment limitations:Conventional lithium-polymer architectures face hard ceiling on safe discharge rates, constraining power output for heavy-lift cargo drones.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are drawing pack integrators to establish local assembly for agricultural and surveillance UAV programs.
- EU AI Act battery traceability mandates:Embedded digital passport requirements create service revenue streams for compliance software and lifecycle tracking platforms.
- Solid-state electrolyte convergence with silicon anodes:Paired innovations promise simultaneous gains in energy density and cycle life, opening premium positioning for next-generation defense contracts.
Industry Challenges
- MIL-STD-810G certification timelines:Environmental testing protocols for shock, vibration, and temperature extremes extend product development cycles by 18-24 months.
- Electrochemical engineering talent scarcity:Shortage of specialists fluent in both solid-state materials science and aerospace power management systems constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Battery Pack Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-ion, Lithium Polymer, Nickel Metal Hydride, Lead Acid, Solid State UAV Type: Multirotor, Fixed Wing, Hybrid, Single Rotor, VTOL Application: Surveillance, Agricultural Monitoring, Package Delivery, Mapping, Search & Rescue End User: Defense Forces, Cinematography, Surveying Companies, Emergency Responders |
| Companies Covered | EaglePicher Technologies, Shenzhen Grepow Battery Co., Ltd., RRC Power Solutions GmbH, DJI, Denchi Group Ltd, Sion Power Corporation, Tadiran Batteries, Amprius Technologies, Epsilor-Electric Fuel Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Battery Pack Market Trends and Innovations
Solid-state architectures are displacing conventional liquid-electrolyte designs across defense and commercial segments, while regulatory traceability mandates and procurement centralization are reshaping how battery packs are specified, certified, and sourced.
Silicon nanowire anodes are converging with solid-state electrolyte architectures to push gravimetric energy density past 400 Wh/kg thresholds. Defense agencies in Israel and the United States are piloting these configurations for extended-endurance surveillance missions. The technology is converging with distributed power management electronics, enabling modular pack architectures that swap individual cells rather than entire units.
EU AI Act battery passport requirements are mandating digital traceability from raw material extraction through end-of-life recycling. Pack manufacturers must now embed RFID or blockchain-enabled identifiers to access CE-marked drone system markets. Agricultural UAV operators in Germany and France are prioritizing suppliers with pre-certified passport systems to avoid customs delays.
Defense procurement consolidation around prime contractors is compressing supplier tiers and demanding longer warranty periods from battery pack vendors. Tier-2 pack assemblers in the United States are responding by forming captive service networks for field replacement and refurbishment. Military end-users in Israel now specify 10-year lifecycle support contracts as standard terms.
UAV Battery Pack Market Segmentation
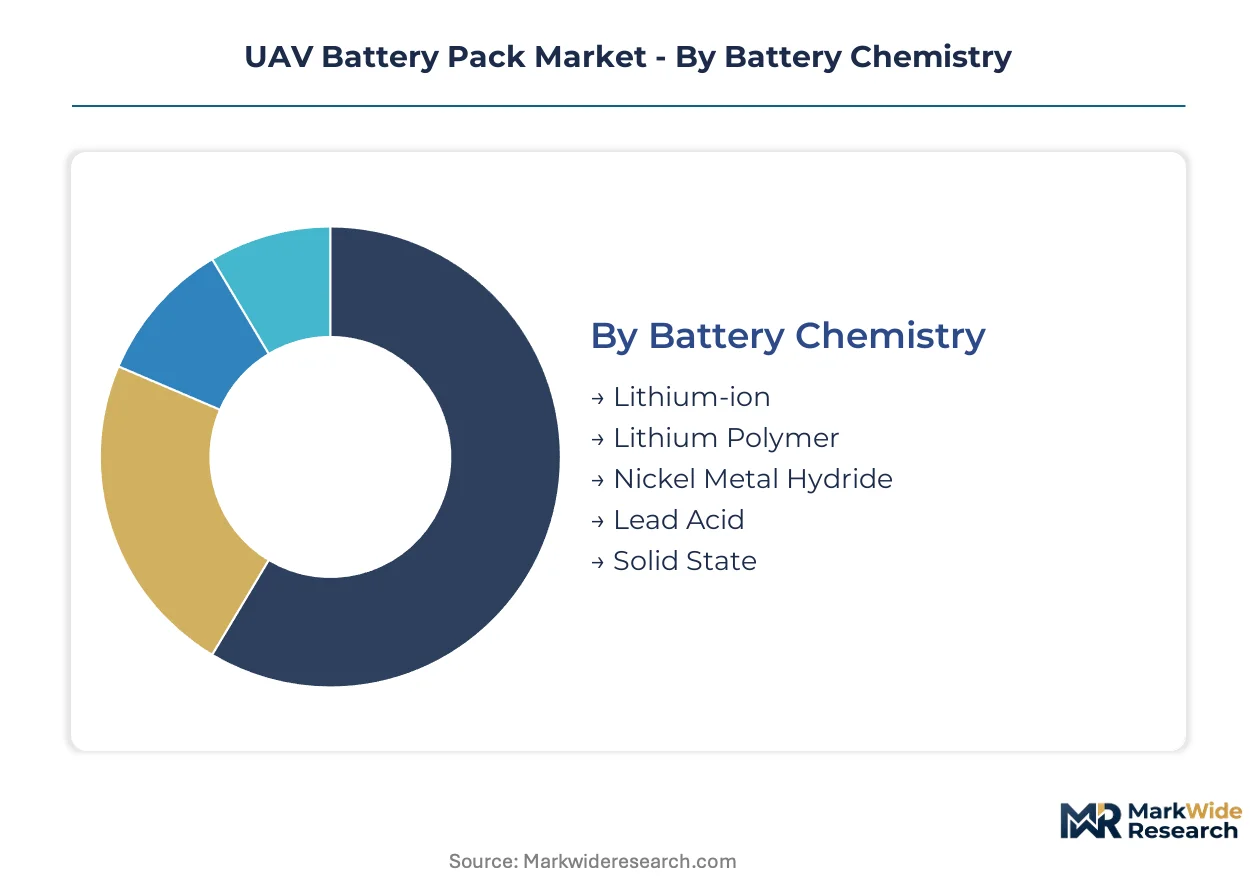
Segmentation in the UAV battery pack market reveals distinct capital requirements, certification burdens, and margin profiles across chemistry types and platform architectures. Defense procurement concentrates purchasing power around MIL-STD-810G certified configurations, while commercial segments prioritize rapid-swap logistics and cost-per-flight-hour economics.
Battery Chemistry:
Lithium polymer and solid-state variants demand the heaviest upfront R&D investment due to materials science complexity and aerospace certification protocols.
- Lithium Polymer:Flexible pouch-cell construction enables form-factor adaptation for multirotor airframes with high discharge-rate requirements. Demand clusters in Shenzhen and Los Angeles for racing and cinematography drones where rapid-swap logistics dominate operational economics.
- Solid State:Ceramic or sulfide electrolyte architectures eliminate thermal runaway risk while pushing energy density past conventional lithium-ion ceilings. Defense agencies in Israel and the United States are funding pilot programs for extended-endurance reconnaissance platforms where cell failure carries mission-critical consequences.
- Lithium-ion:Cylindrical and prismatic formats anchor fixed-wing commercial applications with established supply chains and predictable degradation curves.
- Nickel Metal Hydride:Legacy chemistry persists in training UAV fleets and budget-constrained agricultural programs where energy density tradeoffs are acceptable.
- Lead Acid:Limited to ground-station power and charging infrastructure; negligible airborne deployment due to weight penalties.
Lithium polymer absorbs the bulk of installed capacity; solid-state is expanding most quickly.
UAV Type:
Platform architecture determines pack configuration, thermal management complexity, and replacement cycle frequency.
- Multirotor:Distributed motor configurations require high-C-rate discharge capability and rapid-swap mechanical interfaces. Agricultural spraying fleets in California and Hubei Province operate 8-12 battery cycles daily, driving demand for 15-minute fast-charge compatibility.
- Fixed Wing:Extended mission profiles favor energy density over peak power, with packs optimized for steady-state cruise loads rather than hover-induced voltage sag.
- Hybrid:Combustion-electric architectures split power generation between onboard fuel and battery buffers, complicating pack sizing for transient load spikes.
- Single Rotor:Helicopter-style platforms mirror manned aviation battery specifications, inheriting certification pathways from aerospace suppliers.
- VTOL:Transition-flight regimes impose dual-mode electrical demands, requiring packs tolerant of both hover-intensive discharge and efficient cruise profiles.
Multirotor platforms dominate unit shipments; VTOL configurations are gaining share fastest in logistics trials.
Application:
Mission duration and payload weight establish divergent procurement criteria across use cases.
- Surveillance:Defense and law enforcement programs specify 4-6 hour endurance with encrypted power telemetry. Border patrol contracts in Texas and Arizona prioritize cold-weather discharge reliability.
- Agricultural Monitoring:Crop-spraying operations in the United States and China tolerate shorter flight times in exchange for rapid field-level battery exchange infrastructure.
- Package Delivery:Urban logistics trials impose strict weight limits and noise constraints, favoring high-cycle-life chemistries over raw energy density.
- Mapping:Survey-grade photogrammetry demands stable voltage output across temperature extremes to preserve geospatial accuracy.
- Search & Rescue:Emergency responder programs prioritize operational readiness over cost optimization, accepting premium pricing for guaranteed availability.
Surveillance commands the highest pack value per unit; agricultural monitoring is scaling fastest in absolute volume.
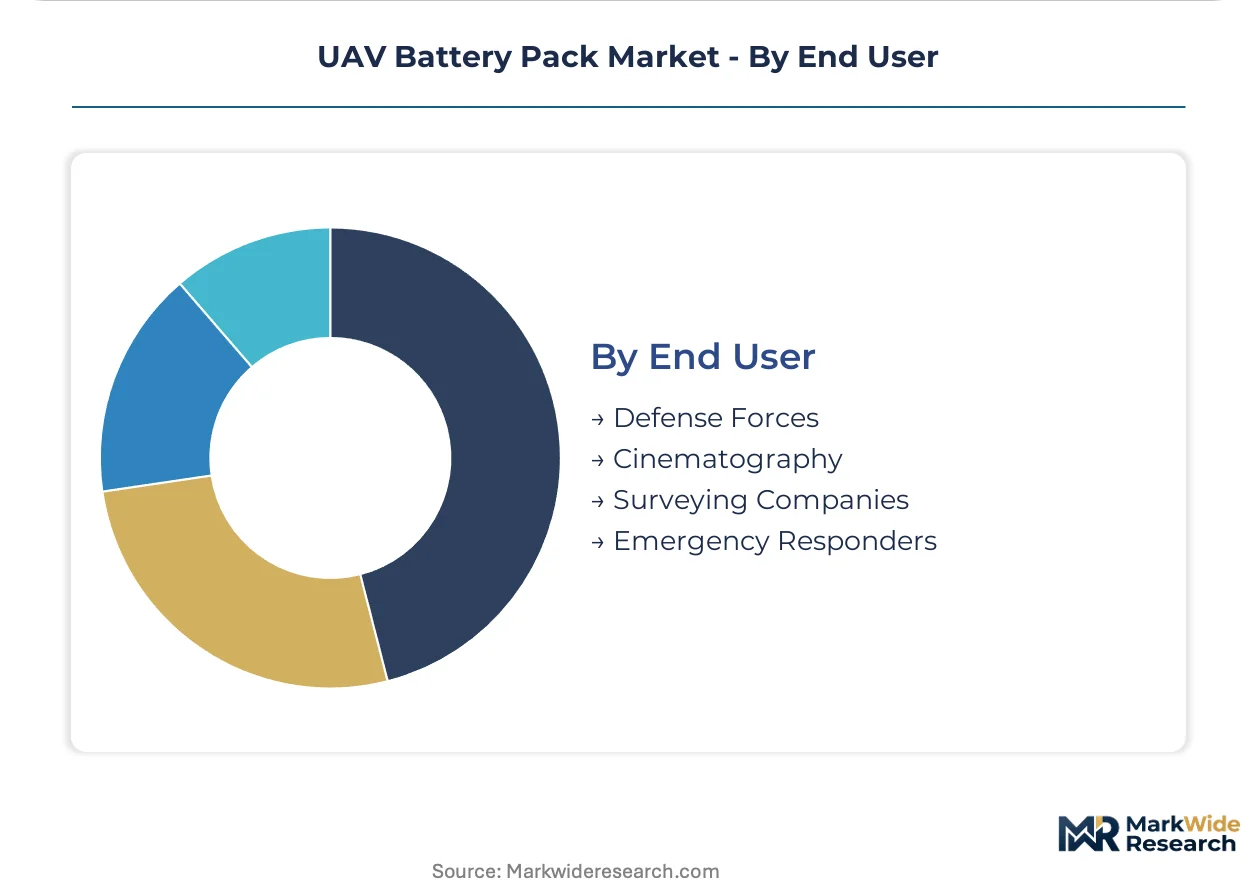
End User:
Customer type dictates warranty terms, technical support expectations, and compliance documentation depth.
- Defense Forces:MIL-STD-810G certification mandates 18-24 month validation timelines and 10-year lifecycle support contracts. Israeli and United States procurement offices now require domestic final assembly for security-cleared supply chains.
- Cinematography:Production studios in Los Angeles and London prioritize rapid field replacement and international shipping compatibility over extended warranties.
- Surveying Companies:Geospatial service providers calculate total cost of ownership across 500+ cycle lifespans, favoring predictable degradation curves.
- Emergency Responders:Fire departments and disaster relief agencies specify hot-swap compatibility with existing vehicle charging infrastructure.
Defense forces concentrate purchasing power in the premium tier; emergency responders are adopting fastest among commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's special economic zone incentives have concentrated lithium polymer cell production for multirotor platforms. Defense procurement in Israel and the United States drives premium-tier demand for solid-state architectures.
United States
Border patrol surveillance contracts in Texas and Arizona require cold-weather discharge reliability for extended missions. FAA Part 107 regulations govern commercial authorization and indirectly shape battery safety certification requirements. Los Angeles anchors cinematography demand where production studios prioritize rapid field replacement over extended warranties.
China
Agricultural spraying fleets in Hubei Province operate 8-12 battery cycles daily, driving rapid-swap logistics infrastructure. MIIT enforces GB standards on lithium battery transport and manufacturing, affecting export-oriented suppliers. Shenzhen clusters high-discharge lithium polymer production for racing and industrial drone segments.
Israel
Defense agencies prioritize longer flight endurance for reconnaissance missions, funding pilot programs for next-generation chemistries. Military procurement offices require domestic final assembly for security-cleared supply chains. Tel Aviv concentrates R&D activity for extended-endurance surveillance platforms where cell failure carries mission-critical consequences.
Germany
Agricultural UAV operators prioritize suppliers with pre-certified passport systems to avoid customs delays under EU AI Act mandates. CE marking frameworks extend to autonomous drone systems, embedding battery traceability into market access protocols. Bavaria hosts precision spraying fleet operators calculating total cost of ownership across 500-plus cycle lifespans.
India
Domestic manufacturing incentives under the PLI scheme for advanced chemistry cells are drawing pack integrators to establish local assembly. The country's national electronics regulator enforces standards on lithium battery transport affecting import flows. Karnataka and Telangana are emerging as assembly hubs for agricultural and surveillance UAV programs.
UAV Battery Pack Market Competitive Landscape
Top-tier vendors anchor defense and aerospace certification tiers, while mid-cap specialists occupy commercial multirotor segments. The structure fragments across chemistry specializations and end-use certifications rather than consolidating around scale. Three archetypes dominate: legacy aerospace suppliers with MIL-STD heritage, Shenzhen-based lithium polymer mass producers, and solid-state R&D ventures attracting defense funding. Competitive moves center on captive service networks for field replacement and backward integration into cell manufacturing.
Among defense-aerospace specialists, EaglePicher Technologies occupies a position exemplifying decades of aerospace battery heritage and MIL-STD-810G certification capability. Shenzhen Grepow Battery Co., Ltd. represents the high-volume lithium polymer archetype serving racing and industrial drone segments from its China base. DJI anchors the integrated platform-and-power-system tier, leveraging manufacturing scale across consumer and commercial multirotor markets globally.
| Leading Market Players |
|---|
| EaglePicher Technologies |
| Shenzhen Grepow Battery Co., Ltd. |
| RRC Power Solutions GmbH |
| DJI |
| Denchi Group Ltd |
| Sion Power Corporation |
| Tadiran Batteries |
| Amprius Technologies |
| Epsilor-Electric Fuel Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU AI Act battery passport mandates gate qualified supply access and premium-tier pricing power, filtering out pack assemblers unable to embed RFID or blockchain-enabled traceability. Military procurement offices in Israel and the United States further concentrate pricing leverage by demanding MIL-STD-810G certification and decade-long lifecycle support contracts.
Pricing Analysis
Lead-time compression commands substantial premiums in defense procurement, with Israeli and United States military offices paying steep markups for 90-day delivery guarantees versus standard 18-24 month certification timelines. Three-tier pricing structure across MIL-certified, commercial-aerospace, and consumer-industrial levels separates segments by documentation depth and warranty length. Cost compression in commercial multirotor tiers is intensifying because Shenzhen-based lithium polymer mass producers are absorbing cell price volatility to defend volume slots. Agricultural spraying fleets in Hubei Province exhibit highest price sensitivity, calculating cost-per-flight-hour across rapid-swap logistics, while defense forces accept premium positioning for mission-critical reliability.
Supply Chain Analysis
Freight cost escalation from cylindrical and prismatic cell origins in China, South Korea, and Japan is reshaping pack assembly economics for Western defense integrators. Raw material flows draw from lithium carbonate brine operations in Chile, cobalt hydroxide refining in the Democratic Republic of Congo, and separator membrane production in Japan. Single-source vulnerability concentrates in East Asian electrolyte formulation capacity, exposing non-Chinese pack integrators to export restriction risk. Distribution runs through prime contractor consolidation in defense tiers and direct OEM relationships in commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive cell manufacturing and certified assembly capacity determine margin retention. Players are pursuing upstream control over solid-state electrolyte materials to escape commodity lithium-ion pricing cycles.
For Market Incumbents: Deepen backward integration into silicon anode and ceramic electrolyte materials to defend premium positioning against solid-state R&D ventures attracting defense funding. Expand captive service networks for field replacement in Texas and Arizona border patrol corridors where 10-year lifecycle contracts are becoming standard terms. Lock in MIL-STD-810G certification capacity to extend product development timelines as competitive moats.
For New Entrants and Emerging Players: The gap between premium solid-state defense pricing and economy lithium polymer agriculture pricing offers white-space entry for mid-tier commercial surveillance packs. Target India's PLI scheme jurisdictions in Karnataka and Telangana where domestic assembly incentives are drawing integrators for agricultural UAV programs. Pursue EU AI Act pre-certification as a go-to-market wedge to bypass customs delays plaguing non-compliant suppliers in Germany and France.
For Investors and Strategic Acquirers: Defense agency pilot program announcements for lithium-sulfur endurance platforms are the leading indicator that solid-state chemistry convergence is accelerating toward contractable revenue. Long-term viability over the next decade hinges on chemistry-specific R&D pipelines rather than pack assembly scale alone. Target acquisition archetypes are mid-cap specialists with MIL-STD heritage and captive cell prototyping capability. Watch for Israeli procurement office domestic final assembly mandates as the inflection signal for Western supply chain reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solid-State Electrolytes | Ceramic and sulfide electrolyte captive supply secures defense R&D funding pipelines in Israel and the United States. |
| MIL-STD-810G Certification Capacity Expansion | Environmental testing protocol investments extend product development timelines and filter out commercial-grade competitors. |
| EU Battery Passport Pre-Certification | RFID and blockchain traceability embedding unlocks CE-marked drone system markets in Germany and France. |
| Captive Field Service Network Buildout | Hot-swap logistics infrastructure in Texas and Arizona border corridors captures 10-year lifecycle support contracts. |
| PLI Scheme Manufacturing Localization | Domestic assembly in Karnataka and Telangana qualifies integrators for India's advanced chemistry cell incentives. |
Research Methodology
Independent corroboration across battery pack procurement officers at defense primes, agricultural UAV fleet operators in California and Hubei Province, and solid-state R&D directors at Israeli and United States defense agencies underwrites the qualitative findings. Primary interviews with plant managers at Shenzhen lithium polymer facilities, distribution channel partners serving cinematography studios in Los Angeles, and regulatory affairs leads navigating EU AI Act compliance were cross-checked against secondary validation. Secondary sources include FAA Part 107 enforcement databases, MIIT GB standard filings, Israeli Ministry of Defense procurement disclosures, and customs records for lithium cell trade flows. Bottom-up unit economics from pack assembly operations were triangulated with top-down defense budget allocation analysis.
Comparable-period anchoring to historical procurement cycles established the forecast window baseline, with segment-level CAGRs derived from chemistry adoption curves and platform shipment trajectories across the analysis window. Segmentation dimensions modeled include battery chemistry tier, UAV platform architecture, mission application profile, and end-user certification requirements. Industry-specific inputs encompass lithium-sulfur laboratory prototype announcements, defense agency pilot program funding levels, and agricultural spraying fleet battery cycle frequency data.
Underlying measurement precision varies by segment; defense procurement disclosures and established certification timelines carry tighter precision than emerging solid-state chemistry commercialization forecasts. Projections reflect assumptions regarding regulatory stability for EU AI Act implementation and sustained government funding for unmanned aerial system programs in the United States, China, and Israel. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Inverter Battery Market
Batteries
North Europe Battery Market
Batteries
India Micro Batteries Market
Batteries
Absorbent Glass Mat (AGM) Battery Market
Batteries
North Africa Battery Market
Batteries
Japan Mobile Battery Market
Batteries
Printed Batteries Market
Batteries
Middle-East Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Wireless Power Bank Market
Batteries
Battery Plate Market
Batteries
Automotive AGM Battery Market
Batteries
48 Volt Battery System Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Elastic Battery Binders Market