
 Battery Anode Materials Market | 2026-2036
Battery Anode Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Anode Materials Market Outlook
Chinese synthetic graphite producers is recalibrating capacity allocations toward battery-grade purification lines. BTR New Material Group leverages integrated mining-to-refining assets across Inner Mongolia and Guizhou. POSCO Future M anchors its anode supply chain through captive needle coke relationships with Korean steel affiliates. SGL Carbon competes via specialized carbon fiber precursor technologies that reduce thermal expansion in fast-charging architectures.
Battery anode materials are carbonaceous or alloy-based active substances, typically 95-99.5% pure, that intercalate lithium ions during charge cycles at potentials near 0.05 V versus Li/Li+. These materials determine cell energy density, cycle stability, and rate capability in lithium-ion systems. Graphite retains dominant share across Electric Vehicles and Consumer Electronics applications due to mature supply chains and established formation protocols. Silicon blends command premium positioning in high-energy configurations for Automotive OEMs despite swelling challenges that constrain cycle life. Hard Carbon occupies niche roles in sodium-ion and low-temperature lithium systems where lattice disorder enables superior ion accessibility.
China's SAMR enforces GB/T standards for anode material purity and heavy metal content that directly gate market access for imported powders. The EU's CSRD and Battery Regulation mandate supply chain due diligence and recycled content disclosures that reshape procurement criteria for European Automotive OEMs. South Korea's MFDS coordinates with METI-aligned JIS standards to harmonize qualification testing across Northeast Asian cell manufacturing corridors. Stakeholders must track how carbon border adjustments and critical mineral list revisions alter cost structures for synthetic versus natural graphite sourcing strategies.
Market Dynamics
Automotive OEM procurement of high-capacity silicon-blend anodes is compressing qualification timelines and forcing upstream graphite suppliers to accelerate purification capacity expansion. This demand pull from electric vehicle platforms is restructuring capacity allocation across synthetic and natural graphite supply chains.
Growth Catalysts
- China's dual carbon goals:National carbon intensity benchmarks for synthetic graphite production are accelerating battery-grade purification line investments. Domestic producers are recalibrating capacity toward higher-margin anode formulations.
- South Korea's cathode-anode cluster:Concentrated cell manufacturing around Pohang and Gwangyang is generating localized demand for qualified anode material supply. Captive needle coke relationships with steel affiliates are securing feedstock access.
- Silicon blend technology:High-energy configurations for automotive platforms are commanding premium positioning despite swelling management challenges. Material suppliers are developing carbon matrix architectures to constrain volumetric expansion.
Market Restraints
- Needle coke supply concentration:Petroleum-based and coal-tar precursor supply remains concentrated among integrated steel-chemical complexes. Battery-grade needle coke availability constrains synthetic graphite expansion timelines.
- GB/T standard compliance costs:China's SAMR-enforced purity and heavy metal content standards impose capital-intensive purification requirements. Imported powder market access gates favor domestic producers with integrated refining assets.
- Silicon anode cycle life limitations:Particle pulverization during lithiation-delithiation cycling degrades cell longevity. Automotive OEMs are restricting silicon content to sub-10% blends until solid-electrolyte interphase stabilization improves.
Strategic Opportunities
- EU Battery Regulation recycled content mandates:Due diligence and recycled material disclosure requirements are reshaping procurement criteria for European automotive OEMs. Qualified recycled graphite supply chains command sourcing preference.
- Sodium-ion battery hard carbon demand:Lattice-disordered carbon structures for sodium-ion systems are creating parallel demand streams. Low-temperature lithium applications are expanding addressable market beyond conventional graphite.
- Fast-charging architecture specialization:Carbon fiber precursor technologies that reduce thermal expansion are enabling differentiated positioning. Specialized thermal management materials command technology premiums in premium vehicle segments.
Industry Challenges
- Carbon border adjustment mechanism compliance:EU CBAM implementation is forcing synthetic graphite producers to document embedded emissions across calcination and graphitization stages. Supply chain reconfiguration friction is delaying European market entry.
- IP licensing complexity in silicon-carbon composite architectures:Patent thickets around nano-structured silicon encapsulation and void-engineered particles are constraining formulation freedom. Material suppliers face royalty stacking or litigation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Anode Materials Market |
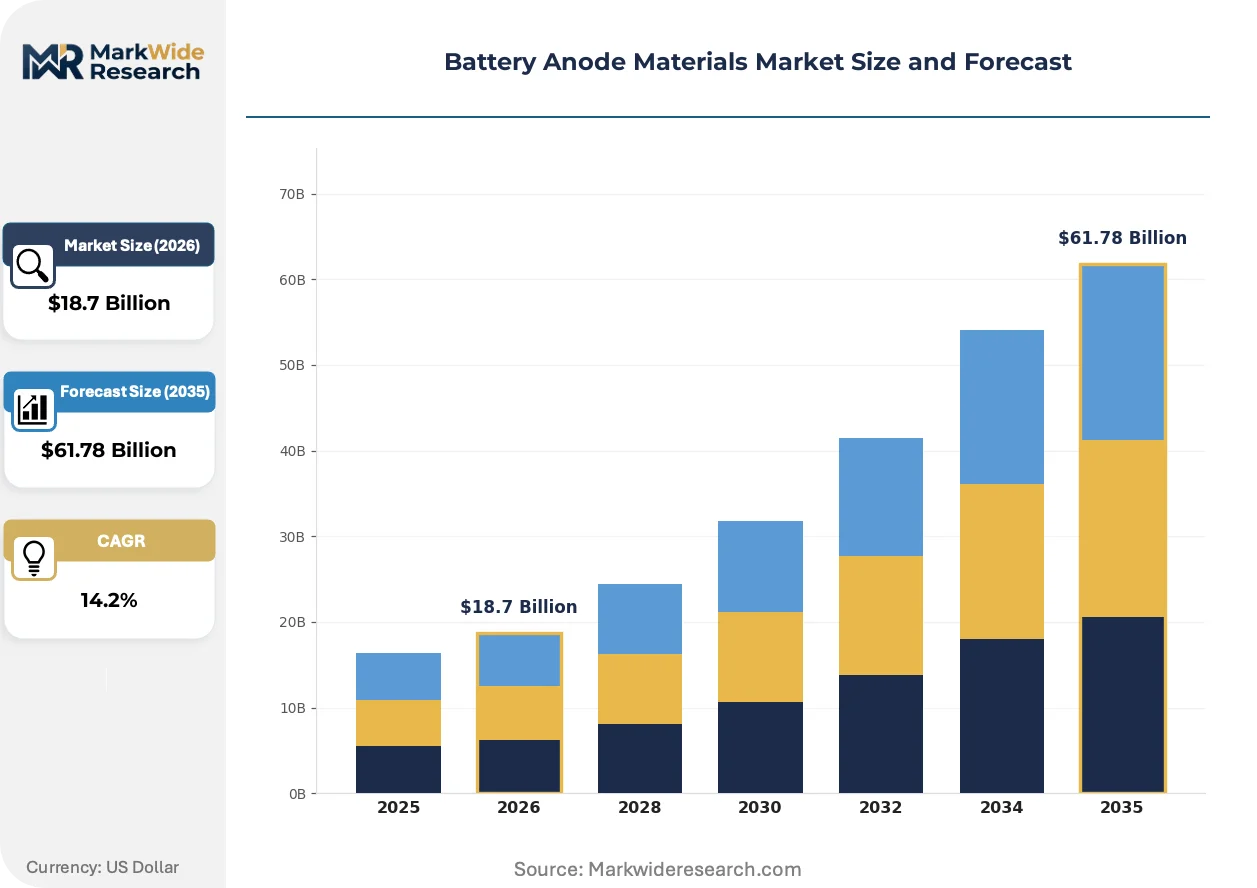
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Hard Carbon, Tin Application: Electric Vehicles, Consumer Electronics, Industrial Energy Storage, Grid Storage End User: Aerospace, Automotive OEMs, Electronics Manufacturers, Energy Providers Form Factor: Powder, Coated Foil, Composite, Sheet |
| Companies Covered | Resonac Holdings Corporation, SGL Carbon, BTR New Material Group, NOVONIX, Group14 Technologies, Ningbo Shanshan Co., Ltd., Mitsubishi Chemical Group, Amprius Technologies, POSCO Future M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Anode Materials Market Strategic Shifts
Active materials engineering is fragmenting the incumbent graphite monoculture. Three parallel developments are redrawing competitive boundaries: silicon-carbon composite architectures, regulatory-driven supply chain traceability mandates, and procurement model consolidation among tier-one cell manufacturers.
Silicon-carbon composite anodes with engineered void structures are decentralizing the graphite-dominated capacity landscape. Automotive OEMs are qualifying 15-20% silicon content blends for 2026 platform launches. This material transition is compressing formation protocol timelines and forcing electrode binder reformulation.
EU Battery Regulation due diligence requirements are mandating supply chain traceability from mine to cell. The CSRD-aligned disclosure framework is forcing anode suppliers to document carbon intensity and conflict mineral status. European automotive OEMs are restricting qualified supplier lists to entities with audited ESG credentials.
Cell manufacturer consolidation is concentrating procurement leverage among CATL, LG Energy Solution, and Samsung SDI. Long-term offtake agreements with volume commitments and price floors are displacing spot market transactions. South Korean and Chinese cell makers are enforcing dual-source requirements that fragment supplier share.
Battery Anode Materials Market Segmentation
Material specification determines electrode performance ceilings and manufacturing compatibility. Procurement patterns diverge sharply between mass-market electric vehicle platforms and specialized aerospace applications. Understanding how technical requirements map to end-use constraints enables targeted capacity allocation across purification and formulation investments.
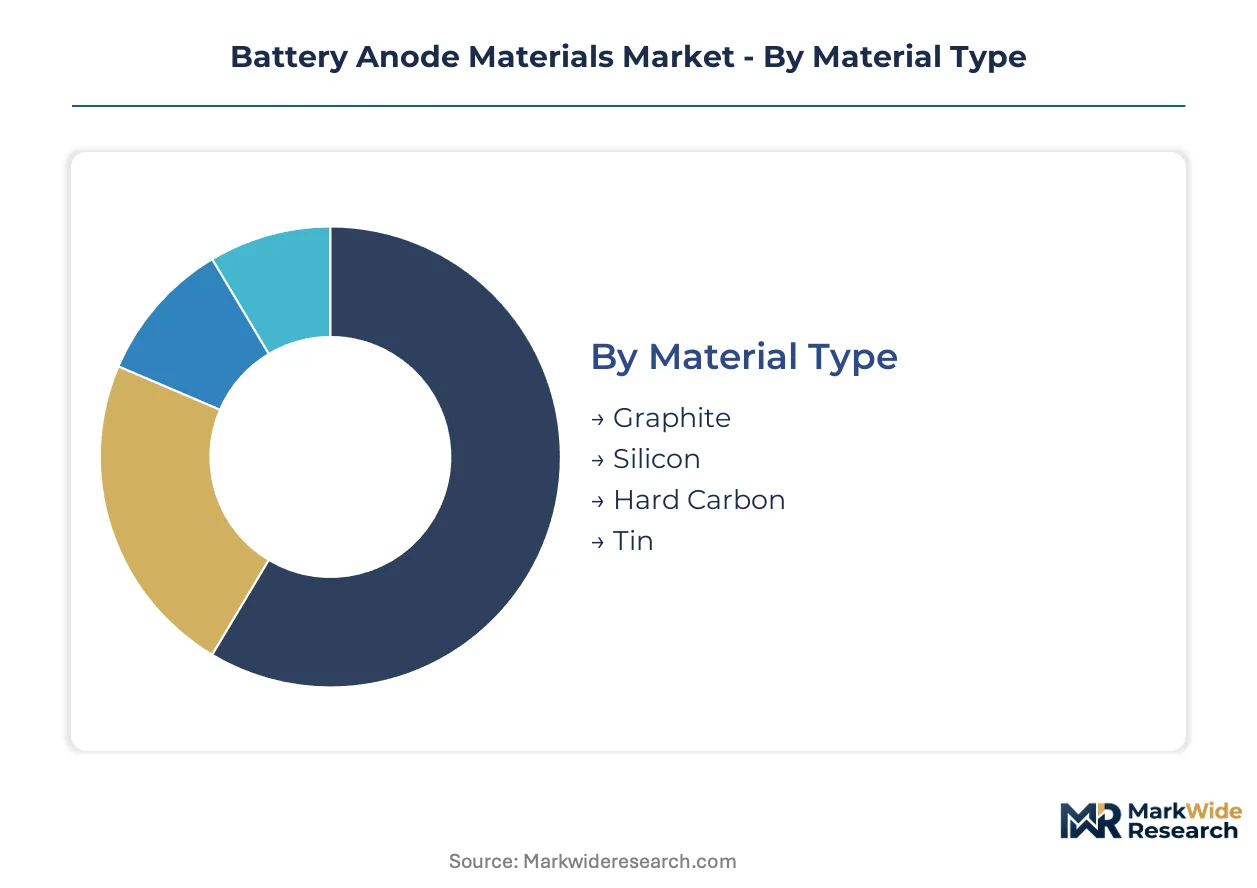
Material Type:
Technical specifications around lithium intercalation potential, volumetric expansion tolerance, and cycle stability define competitive positioning across active material categories.
- Graphite:Crystalline carbon structures intercalate lithium ions at 0.05 V versus Li/Li+ with theoretical capacity of 372 mAh/g. Electric vehicle OEMs in South Korea's Pohang-Gwangyang corridor anchor procurement volumes around battery-grade synthetic formulations qualified to GB/T purity standards.
- Silicon:Alloy-based lithium storage delivers theoretical capacities exceeding 3,500 mAh/g but induces 300% volumetric expansion during lithiation. Automotive platforms are qualifying sub-10% blends constrained by solid-electrolyte interphase stabilization challenges.
- Hard Carbon:Disordered lattice structures enable sodium-ion intercalation and low-temperature lithium operation. Niche demand streams from grid storage applications favor its superior ion accessibility.
- Tin:Metallic alloy anodes offer intermediate capacity between graphite and silicon with distinct volumetric expansion profiles. Limited commercial deployment reflects electrode binder compatibility constraints.
Graphite leads on scale; silicon leads on momentum.
Application:
End-use performance requirements reshape material selection criteria across energy density, cycle life, and cost sensitivity axes.
- Electric Vehicles:Platform-specific energy density targets drive silicon-blend adoption timelines. Cell manufacturers enforce dual-source qualification protocols that fragment supplier share across CATL, LG Energy Solution, and Samsung SDI procurement networks.
- Consumer Electronics:Smartphone and laptop applications prioritize volumetric energy density over absolute cycle life. Premium device segments absorb cost premiums for fast-charging optimized formulations.
- Industrial Energy Storage:Duty cycle predictability favors mature graphite systems with established formation protocols. Cost sensitivity restricts silicon content to demonstration projects.
- Grid Storage:Duration requirements and capital cost constraints align with hard carbon's sodium-ion compatibility. Chinese dual carbon policy incentives are accelerating dedicated production lines.
Electric vehicles anchor procurement volumes; grid storage applications are climbing the fastest.
End User:
Customer technical capabilities and qualification timelines segment addressable markets by integration complexity and volume commitment structures.
- Automotive OEMs:Platform-level cell integration demands multi-year qualification cycles and audited ESG credentials under EU Battery Regulation due diligence mandates. Long-term offtake agreements with volume floors are displacing spot market transactions.
- Electronics Manufacturers:Rapid product refresh cycles compress material qualification to 12-18 month windows. Supply chain fragmentation across Southeast Asian assembly locations favors standardized graphite formulations.
- Energy Providers:Utility-scale procurement emphasizes bankability metrics and decade-scale performance warranties. Recycled content disclosure requirements under CSRD-aligned frameworks reshape sourcing criteria.
- Aerospace:Extreme reliability requirements and low-volume, high-specification procurement favor specialized carbon fiber precursor technologies. SGL Carbon's thermal expansion control solutions address fast-charging thermal management needs.
Automotive OEMs concentrate procurement leverage; energy providers are gaining share fastest.
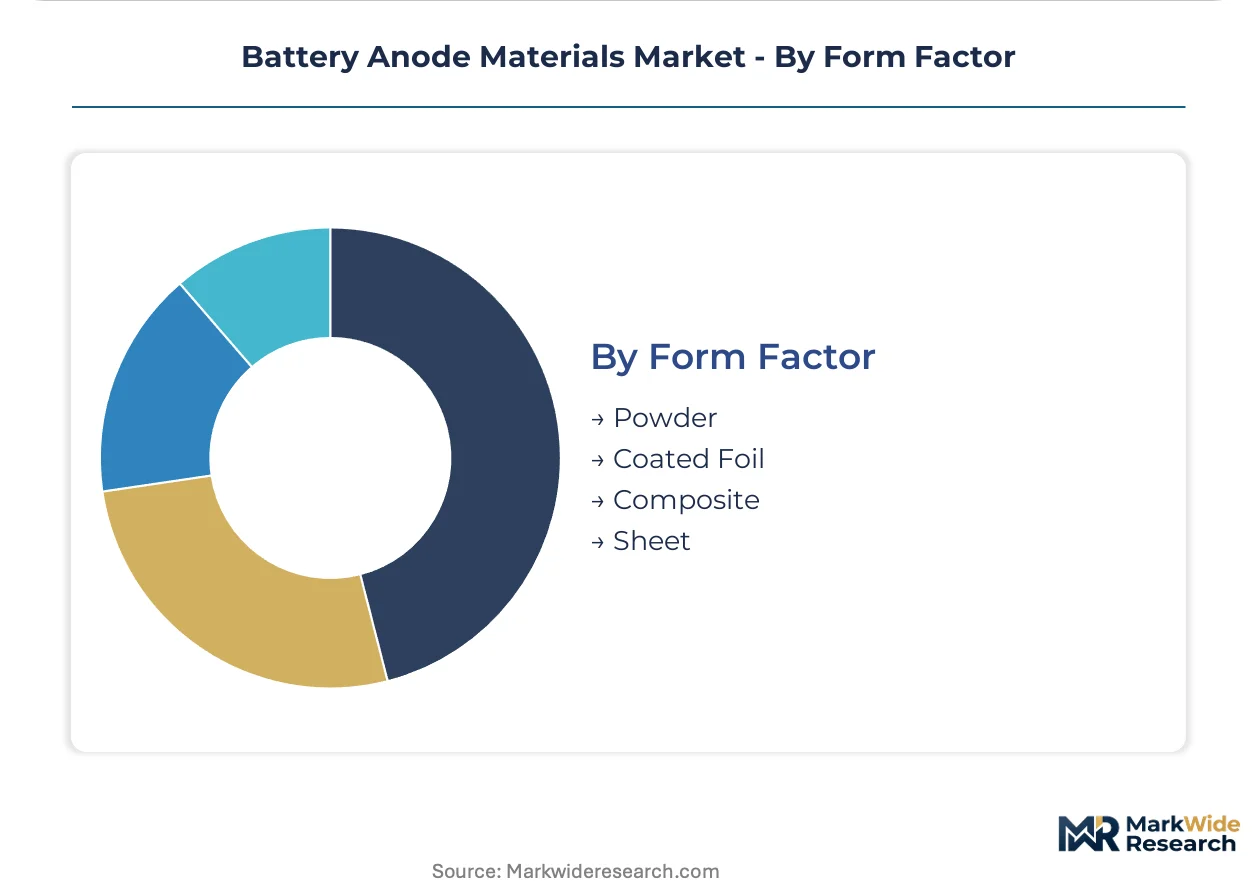
Form Factor:
Manufacturing integration depth separates commodity powder supply from value-added electrode component delivery.
- Powder:Unprocessed active material requires downstream electrode coating and calendering. BTR New Material Group's integrated mining-to-refining assets across Inner Mongolia and Guizhou dominate battery-grade purification capacity.
- Coated Foil:Pre-applied active material layers on copper current collectors reduce cell manufacturer capital intensity. South Korean cathode-anode clusters around Pohang are driving localized demand.
- Composite:Engineered silicon-carbon architectures with void-engineered particles address swelling management. Patent thickets around nano-structured encapsulation constrain formulation freedom.
- Sheet:Self-supporting electrode structures for solid-state and specialized cell architectures. Limited commercial scale reflects manufacturing yield challenges.
Powder dominates supply volumes; coated foil formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon intensity benchmarks for synthetic graphite production are widening cost-of-compliance gaps between jurisdictions, redirecting capacity investments toward regions with integrated feedstock access and streamlined permitting. Battery-grade purification lines are concentrating where steel-chemical complexes anchor needle coke supply.
China
Domestic OEM procurement of high-capacity anode formulations is accelerating battery-grade purification line investments across Inner Mongolia and Guizhou. SAMR-enforced GB/T standards for purity and heavy metal content are tightening carbon intensity benchmarks for synthetic graphite production. Integrated mining-to-refining assets in these provinces dominate capacity expansion timelines.
South Korea
Cell manufacturing concentration around Pohang and Gwangyang is generating localized demand for qualified anode material supply. MFDS coordination with METI-aligned JIS standards harmonizes qualification testing across Northeast Asian manufacturing corridors. Captive needle coke relationships with steel affiliates are securing feedstock access for domestic producers.
Japan
Automotive OEM qualification of silicon-blend anodes for 2026 platform launches is compressing formation protocol timelines. METI-aligned technical standards govern material qualification for cell integration into domestic EV platforms. Specialized carbon fiber precursor technologies are addressing fast-charging thermal management needs in premium vehicle segments.
United States
IRA production tax credits for domestic battery material processing are reshaping investment decisions for synthetic graphite capacity. EPA emissions documentation requirements intersect with state-level clean energy procurement mandates. Emerging purification investments are targeting locations with access to petroleum coke feedstock from domestic refining.
Germany
EU Battery Regulation due diligence mandates are restricting qualified supplier lists to entities with audited ESG credentials. ECHA REACH compliance for imported anode powders imposes substance registration obligations. Industrial clusters in North Rhine-Westphalia are developing recycled graphite supply chains to meet CSRD-aligned disclosure requirements.
Battery Anode Materials Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue silicon-carbon composite architectures and specialized thermal management materials. The supplier base stratifies across integrated mining-to-refining operators, captive needle coke processors, and technology-focused composite developers. Archetypes include scale-driven purification specialists, steel-affiliated feedstock integrators, and IP-heavy silicon encapsulation developers. Capacity expansion and strategic partnerships dominate competitive moves as cell manufacturers enforce dual-source qualification protocols.
Within the integrated purification tier, BTR New Material Group and POSCO Future M exemplify divergent geographic anchoring strategies. SGL Carbon occupies a position among specialized carbon precursor developers targeting thermal expansion control in fast-charging architectures. Japanese chemical conglomerates and Australian battery technology developers represent alternative archetypes emphasizing materials engineering over vertical feedstock control.
| Leading Market Players |
|---|
| Resonac Holdings Corporation |
| SGL Carbon |
| BTR New Material Group |
| NOVONIX |
| Group14 Technologies |
| Ningbo Shanshan Co., Ltd. |
| Mitsubishi Chemical Group |
| Amprius Technologies |
| POSCO Future M |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers across China's Inner Mongolia and Guizhou provinces anchor battery-grade purification capacity, translating state-supported financing into disciplined pricing power over synthetic graphite supply. Their integrated mining-to-refining assets compress cost structures while GB/T standard compliance gates favor domestic market access, reshaping procurement economics for imported powders.
Pricing Analysis
Direct-to-OEM discount structures dominate high-volume procurement, with long-term offtake agreements displacing spot market transactions among tier-one cell manufacturers. Price differentiation rests on purity certification tiers and volume scale commitments, with battery-grade synthetic formulations commanding premiums over natural graphite alternatives. Cost compression in mid-tier formulations is intensifying because automotive OEMs enforce dual-source qualification protocols that fragment supplier leverage. Consumer electronics manufacturers exhibit highest price sensitivity due to rapid product refresh cycles, while aerospace applications absorb technology premiums for thermal expansion control.
Supply Chain Analysis
Skilled technician availability constraints in South Korea's Pohang-Gwangyang corridor and Japan's metropolitan manufacturing zones are tightening labor competition among synthetic graphite producers. Supply concentrates in China, South Korea, and Japan, with needle coke feedstock drawing from integrated steel-chemical complexes. Raw material dependencies rest on petroleum coke precursors, coal-tar pitch, and carbon fiber precursors. Single-source vulnerability around needle coke supply creates structural risk exposure. Distribution runs through captive relationships with cell manufacturing clusters and qualified supplier lists enforced by automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Battery Regulation due diligence mandates and recycled content disclosures restructuring procurement criteria for European automotive OEMs.
For Market Incumbents: Acquire captive needle coke processing assets to secure feedstock access against petroleum-based precursor supply concentration. Expand battery-grade purification lines in jurisdictions with streamlined carbon intensity benchmarking to defend margin position against Chinese domestic producers with integrated refining advantages. GB/T standard compliance investments remain essential for market access gates. For New Entrants and Emerging Players: Silicon-carbon composite architectures with engineered void structures offer the most penetrable technology wedge, targeting automotive OEM qualification timelines for high-energy platform configurations. White-space opportunities concentrate in hard carbon production for sodium-ion battery demand and specialized thermal management materials for fast-charging architectures. Partner with qualified recycling operators to meet CSRD-aligned disclosure requirements as a go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap purification specialists with unqualified ESG credentials facing EU Battery Regulation exclusion. Long-term viability centers on backward integration into needle coke supply and carbon intensity documentation capabilities across the analysis window. Monitor carbon border adjustment mechanism implementation timelines as the critical inflection signal for European market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Supply | Captive feedstock access secures synthetic graphite expansion timelines against steel-chemical complex concentration. |
| GB/T Standard Certification Investment | SAMR-enforced purity gates favor domestic producers with audited heavy metal content compliance. |
| Silicon-Carbon Composite R&D Partnership | Engineered void architectures address swelling management for automotive OEM platform qualification. |
| Recycled Graphite Supply Chain Development | CSRD-aligned disclosure requirements reshape European automotive OEM procurement criteria. |
| Fast-Charging Thermal Management Specialization | Carbon fiber precursor technologies command technology premiums in premium vehicle segments. |
Study Parameters
Coverage spans China, South Korea, Japan, the United States, and Germany, with primary inputs from each market informing demand-side validation. Primary interviews with synthetic graphite plant managers, automotive OEM procurement leads, cell manufacturer technical qualification directors, and needle coke supply specialists combined with secondary validation from SEC filings, customs trade data, SAMR GB/T standard documentation, and ECHA REACH substance registrations. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Rate-of-change decomposition across material type, application, end user, and form factor dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by purity grade pricing tiers and regional carbon intensity compliance cost differentials. Forecast inputs incorporated automotive OEM platform launch timelines, sodium-ion battery commercialization curves, and EU Battery Regulation implementation phasing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon anode cycle life breakthroughs, carbon border adjustment mechanism scope expansion, and needle coke supply disruptions from steel industry decarbonization. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Asia-Pacific Battery Market
Batteries
Portable Battery Station Market
Batteries
Solid Electrolyte Market
Batteries
Denmark Rechargeable Battery Market
Batteries
Battery Cell Market
Batteries
China Rechargeable Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Wood-Based Batteries Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
48 Volt Battery System Market
Batteries
Portable Battery Market
Batteries
North America Consumer Battery Market
Batteries
Battery Swapping Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
United Kingdom SLI Battery Market