
 South America Micro Battery Market | 2026-2036
South America Micro Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Micro Battery Market Insights
Brazil's ANVISA medical device battery safety protocols is expanding compliance costs for foreign suppliers entering the South America Micro Battery Market. Panasonic Holding Corporation leverages its lithium-ion manufacturing depth to sustain premium positioning across Brazilian consumer electronics channels. Murata Manufacturing Co., Ltd. anchors its regional presence through specialized solid-state cell distribution networks serving Argentine medical OEMs.
A micro battery is a compact electrochemical power source typically measuring under 20 millimeters in diameter, engineered to deliver stable voltage output in constrained form factors for miniature electronic systems. These cells employ layered electrode architectures and precision-sealed electrolyte containment to power implantable sensors, wireless earbuds, and distributed IoT nodes where volumetric energy density governs design feasibility. Solid-state micro batteries command the highest margin pools due to manufacturing complexity and safety certification premiums, while lithium-polymer variants capture volume leadership across wearable technology applications in Chile and Peru. Thin film technology segments are gaining structural traction among healthcare providers seeking biocompatible power for continuous glucose monitors and cardiac event recorders.
ANVISA regulates medical device battery imports through updated thermal runaway testing mandates, compelling suppliers to certify cycle-life documentation before customs clearance. Brazil's INMETRO conformity assessment requirements for consumer electronics batteries add a second compliance layer that filters out uncertified Asian exporters. Argentina's national telecommunications regulator imposes electromagnetic compatibility standards on IoT device power modules that reshape product design priorities for regional manufacturers. Stakeholders must monitor evolving Mercosur technical harmonization negotiations, as unified battery safety standards would consolidate testing burdens but also accelerate cross-border supply chain integration.
Market Dynamics
ANVISA's thermal runaway testing mandates for medical device batteries are compressing import timelines and forcing suppliers to restructure certification workflows before Brazilian customs clearance.
Growth Catalysts
- Portable diagnostic equipment procurement:Brazilian medical device manufacturers are scaling orders for compact power units to supply point-of-care testing devices deployed across São Paulo's healthcare network.
- Solid-state cell safety premiums:Healthcare providers in Argentina's Córdoba cluster are prioritizing solid-state micro batteries for implantable sensors due to superior thermal stability profiles.
- INMETRO conformity pathways:Streamlined certification routes for lithium-polymer variants are accelerating wearable technology launches in Chile and Peru consumer channels.
Market Restraints
- Lithium carbonate price volatility:Input cost swings from Chilean and Argentine salar brine operations are squeezing margin structures for regional cell assemblers.
- Single-source solid-state electrolyte supply:Dependence on Japanese and Korean ceramic membrane suppliers creates vulnerability for Argentine medical OEMs qualifying next-generation designs.
- ANVISA documentation bottlenecks:Cycle-life certification requirements are extending customs hold times for Asian-imported cells destined for Brazilian diagnostic equipment lines.
Strategic Opportunities
- Colombian medical technology corridor:Underdeveloped local cell sourcing creates first-mover advantage for suppliers establishing Bogotá distribution hubs serving Andean healthcare clusters.
- Thin film biocompatibility convergence:Continuous glucose monitor manufacturers in Brazil are integrating flexible micro cells with polymer substrates to enable skin-adherent power architectures.
- Mercosur technical harmonization:Unified battery safety standards under negotiation would collapse redundant testing burdens and enable single-certification access across Brazilian, Argentine, and Uruguayan markets.
Industry Challenges
- Solid-state manufacturing skill scarcity:Regional workforce gaps in ceramic sintering and thin-film deposition are constraining Argentine medical OEMs' internal cell qualification timelines.
- Dual certification capex burden:Simultaneous ANVISA and INMETRO compliance investments are diverting capital from R&D programs at Brazilian mid-tier battery distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Micro Battery Market |
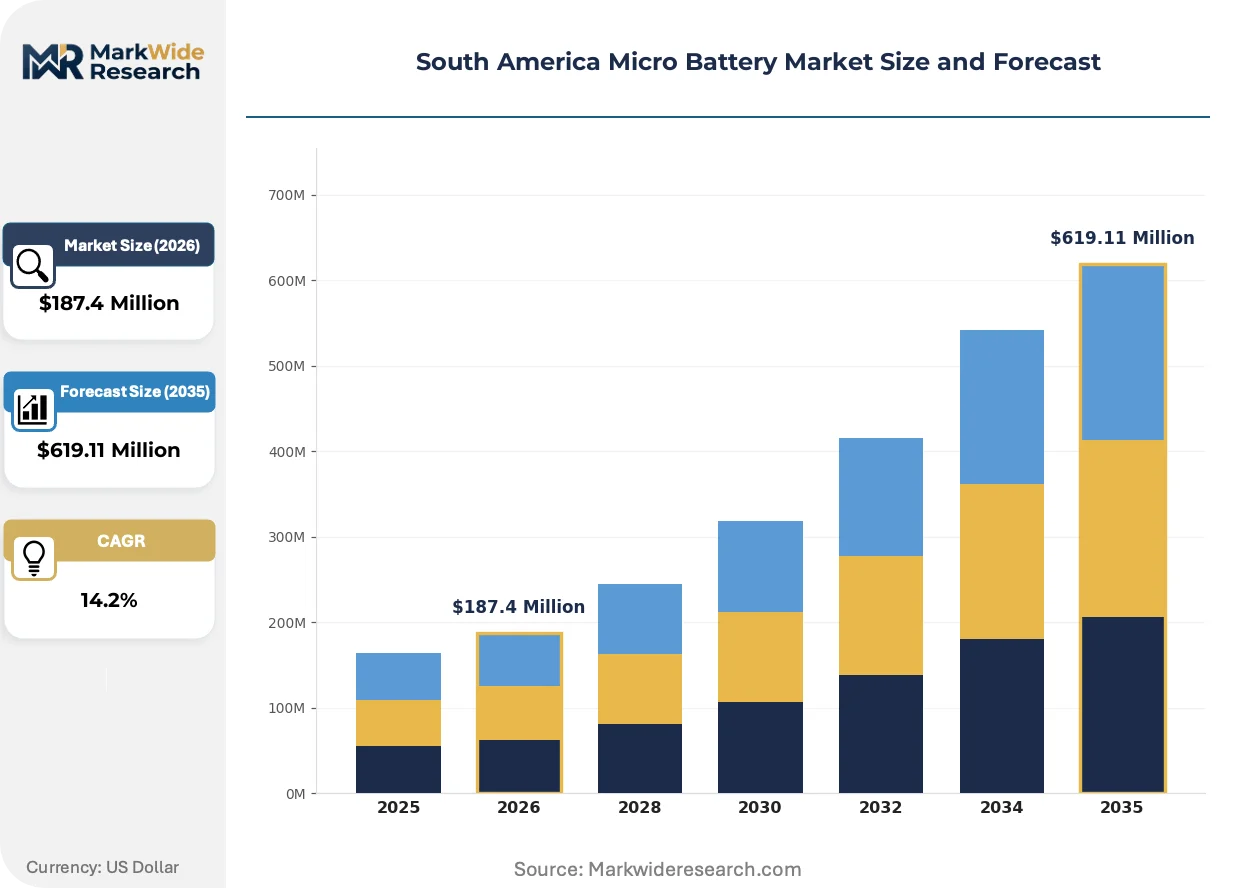
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lithium-polymer, Nickel-metal Hydride, Solid State Application: Consumer Electronics, Medical Devices, Wearable Technology, IoT Devices End User: Manufacturers, Retailers, Healthcare Providers, Tech Startups Technology: Thin Film, Microfabrication, 3D Printing, Conventional |
| Companies Covered | Panasonic Holding Corporation, Murata Manufacturing Co., Ltd., Maxell, Ltd, Duracell Inc., Varta AG, TDK Corporation, Renata SA, Enfucell Oy, Molex, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Micro Battery Market Trends and Innovations
Electrochemical architectures and regulatory frameworks are converging to reshape competitive positioning across South American micro battery channels, with safety certification premiums and form-factor miniaturization dictating procurement priorities.
Solid-state ceramic electrolyte technology is rewriting the safety-performance tradeoff for implantable medical devices. Argentine cardiac event recorder manufacturers are adopting these cells at accelerated qualification paces. The technology is compressing liability insurance costs and enabling extended device lifecycles in chronic monitoring applications.
ANVISA's updated thermal runaway testing protocols are mandating third-party cycle-life documentation for all imported lithium-based cells. This regulatory shift is filtering out uncertified Asian suppliers from Brazilian medical device supply chains. Domestic distributors are responding by building captive testing capabilities to preempt customs delays.
Healthcare procurement teams are consolidating supplier relationships around certified cell vendors capable of delivering biocompatibility documentation. This concentration is displacing fragmented spot-buying patterns previously common in Brazilian diagnostic equipment channels. The shift is most visible in São Paulo state, where hospital procurement consortiums now mandate pre-qualified battery supplier lists for tender participation.
South America Micro Battery Market Segmentation
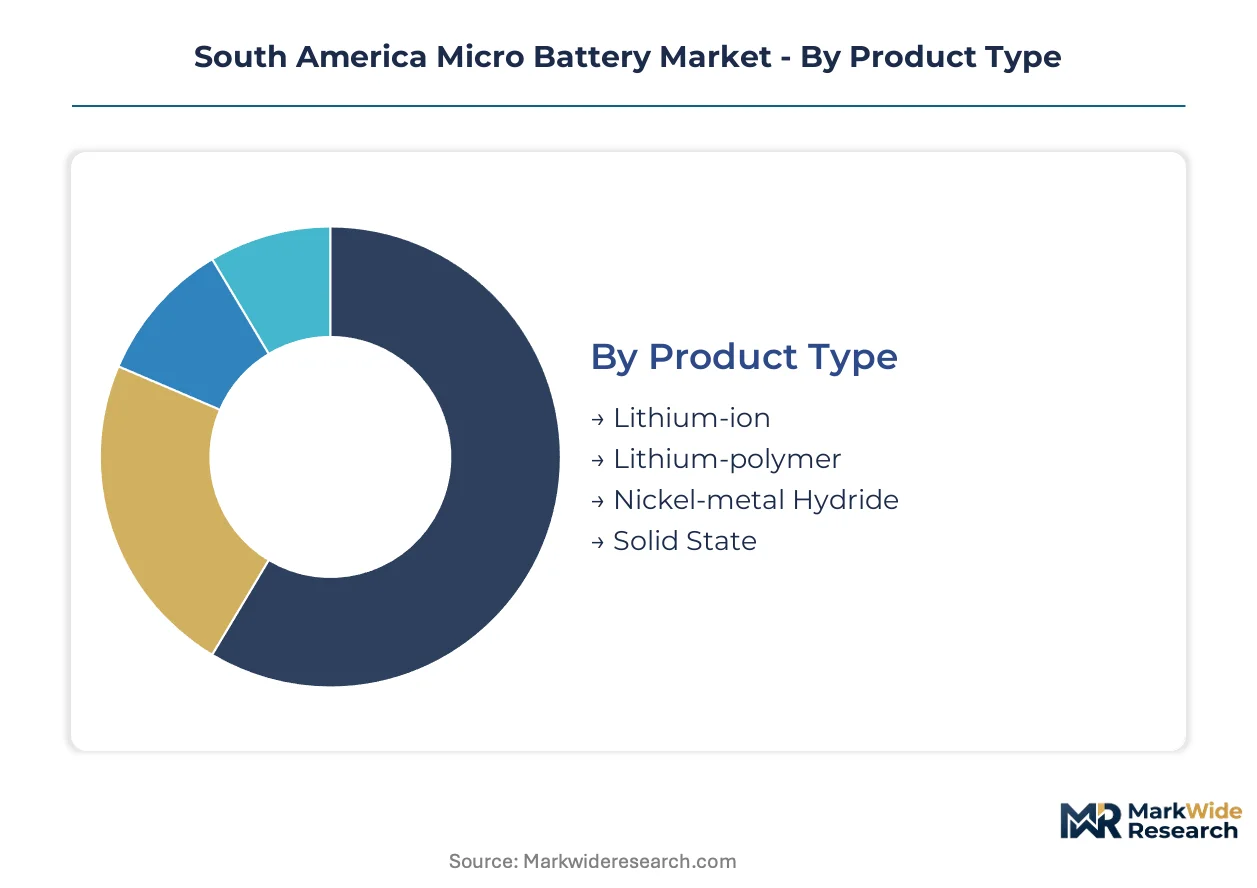
Micro battery procurement across South America fragments sharply across certification regimes, with ANVISA medical protocols and INMETRO consumer standards creating divergent qualification pathways. Suppliers must map segment-specific compliance burdens to avoid customs bottlenecks and tender disqualification.
Product Type:
ANVISA thermal runaway documentation requirements apply selectively across chemistries, with solid-state cells facing the steepest certification premiums while lithium-polymer variants navigate streamlined INMETRO pathways.
- Lithium-ion:Layered oxide cathode architectures deliver stable voltage output across Brazilian consumer electronics channels. São Paulo state distributors prioritize these cells for smartphone and tablet applications where cycle-life predictability governs procurement decisions.
- Lithium-polymer:Gel electrolyte containment enables ultra-thin form factors that dominate Chilean and Peruvian wearable technology launches. INMETRO's streamlined conformity routes for pouch-cell configurations are compressing time-to-market for regional OEMs.
- Nickel-metal Hydride:Mature chemistry retains cost positioning in price-sensitive Argentine medical device segments.
- Solid State:Ceramic electrolyte manufacturing complexity commands premium positioning in Córdoba implantable sensor applications.
Lithium-polymer sits at the top of the volume ranking, with solid state climbing the fastest.
Application:
End-use concentration determines whether suppliers face ANVISA medical certification, INMETRO consumer electronics compliance, or Argentina's telecommunications electromagnetic standards.
- Consumer Electronics:Wireless earbuds and portable charging cases absorb the highest cell volumes across Brazilian retail channels. São Paulo electronics corridor distributors report procurement consolidation around certified vendors capable of delivering INMETRO documentation bundles.
- Medical Devices:Point-of-care diagnostic equipment and implantable sensors trigger ANVISA's updated thermal runaway mandates. Brazilian hospital procurement consortiums now exclude battery suppliers lacking pre-qualified certification status from tender participation.
- Wearable Technology:Fitness trackers and health monitors concentrate demand in Chilean and Peruvian consumer markets.
- IoT Devices:Distributed sensor networks face Argentina's national telecommunications regulator electromagnetic compatibility requirements.
Consumer electronics captures the dominant volume position, with medical devices gaining share fastest.
End User:
Procurement sophistication varies dramatically across buyer categories, with healthcare providers imposing the most stringent documentation requirements and tech startups prioritizing speed over certification depth.
- Manufacturers:Brazilian medical device OEMs and Argentine cardiac equipment producers drive specification-grade demand. These buyers mandate cycle-life documentation and biocompatibility certifications that filter out uncertified Asian suppliers.
- Healthcare Providers:Hospital procurement consortiums in São Paulo state enforce pre-qualified supplier lists that consolidate purchasing around certified cell vendors. ANVISA compliance documentation has become a non-negotiable tender requirement.
- Retailers:Consumer electronics distributors across Brazil and Chile prioritize INMETRO-marked inventory.
- Tech Startups:Early-stage wearable ventures in Colombia's emerging Bogotá corridor favor rapid prototyping cycles over full certification.
Manufacturers command the highest volume throughput, with healthcare providers expanding procurement fastest.
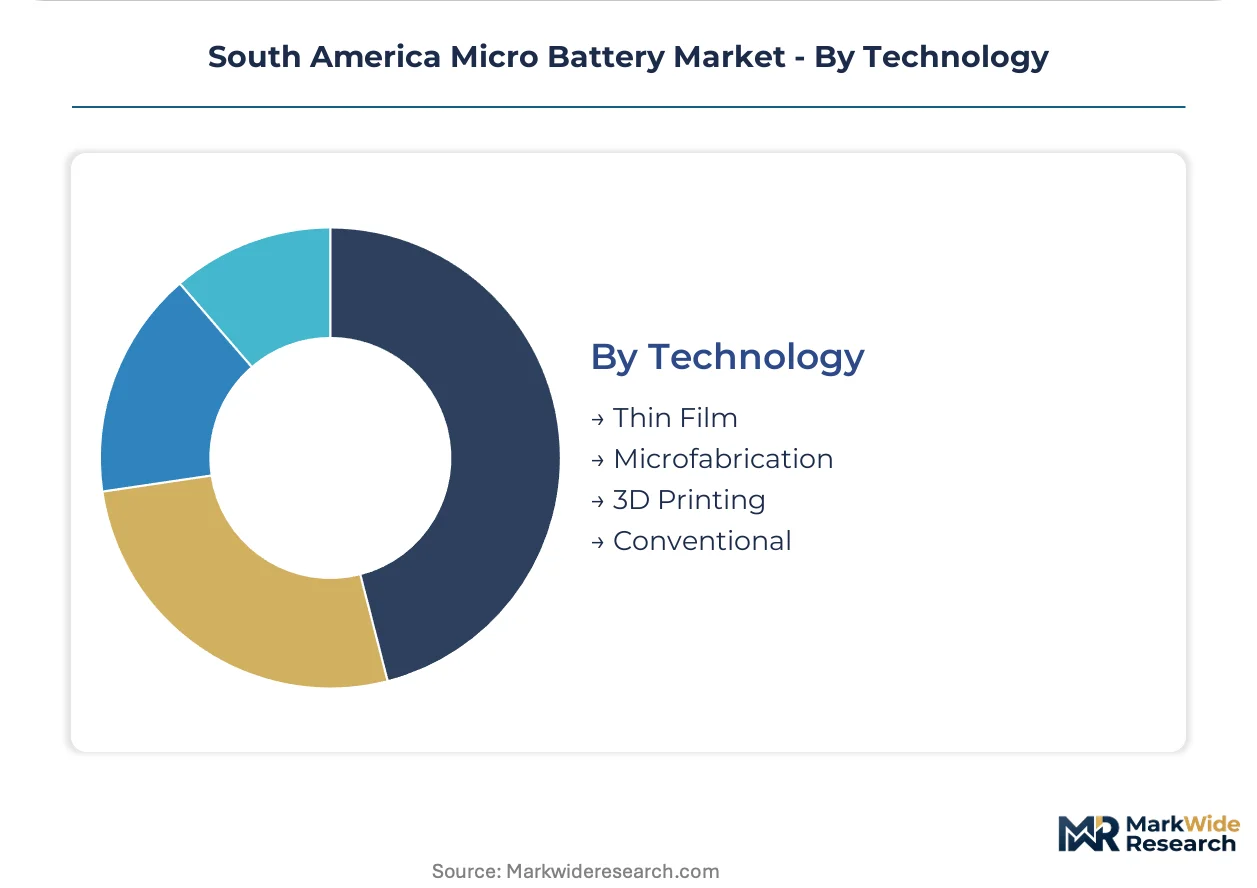
Technology:
Manufacturing process selection determines biocompatibility eligibility and form-factor limits, with thin-film architectures unlocking skin-adherent medical applications while conventional methods retain cost advantages.
- Thin Film:Sputtered electrode deposition enables flexible substrates that integrate with polymer backing for continuous glucose monitors. Brazilian healthcare providers are adopting these architectures for skin-adherent cardiac event recorders where conformal power delivery governs patient compliance.
- Microfabrication:Photolithographic patterning delivers precision dimensional control for Argentine implantable sensor manufacturers. The technology supports miniaturized cell geometries that fit within cardiac pacemaker form-factor constraints.
- 3D Printing:Additive electrode structuring remains experimental for regional medical OEMs.
- Conventional:Stacked electrode winding dominates lithium-polymer production for Chilean wearable volume.
Conventional technology retains volume leadership, with thin film expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ceramic sintering technicians and thin-film deposition engineers concentrate in Brazil's São Paulo electronics corridor and Argentina's Córdoba medical technology cluster, anchoring regional manufacturing capabilities for next-generation micro battery architectures.
Brazil
ANVISA thermal runaway testing mandates compress import timelines for lithium-based cells destined for diagnostic equipment lines. INMETRO conformity assessment requirements add a second compliance layer filtering uncertified Asian exporters from consumer electronics channels. São Paulo state electronics corridor distributors consolidate procurement around certified vendors capable of delivering documentation bundles for hospital tender participation.
Argentina
Córdoba medical technology cluster manufacturers prioritize solid-state micro batteries for implantable sensors due to superior thermal stability profiles. The national telecommunications regulator imposes electromagnetic compatibility standards on IoT device power modules that reshape product design priorities. Single-source dependence on Japanese and Korean ceramic membrane suppliers creates vulnerability for medical OEMs qualifying next-generation designs.
Chile
Lithium-polymer variants capture volume leadership across wearable technology applications as INMETRO's streamlined conformity routes for pouch-cell configurations compress time-to-market. Lithium carbonate price volatility from Chilean salar brine operations squeezes margin structures for regional cell assemblers. Consumer electronics distributors prioritize INMETRO-marked inventory across retail channels.
Colombia
Underdeveloped local cell sourcing creates first-mover advantage for suppliers establishing Bogotá distribution hubs serving Andean healthcare clusters. Early-stage wearable ventures in the emerging Bogotá corridor favor rapid prototyping cycles over full certification. Tech startups drive demand for flexible micro cells with polymer substrates.
Peru
Fitness trackers and health monitors concentrate demand in Peruvian consumer markets as lithium-polymer gel electrolyte containment enables ultra-thin form factors. INMETRO streamlined certification accelerates wearable technology launches. Retail procurement patterns favor rapid inventory turns over deep certification documentation.
South America Micro Battery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-intensive segments, creating a tiered structure where ANVISA compliance capabilities separate premium-positioned suppliers from price-driven commodity players. The vendor base fragments across Japanese and Korean ceramic membrane suppliers, European precision cell manufacturers, and regional distributors building captive testing capabilities. Three strategic archetypes dominate: diversified electronics conglomerates leveraging lithium-ion manufacturing depth, specialized solid-state cell producers, and regional distributors integrating certification services. Competitive moves center on strategic partnerships with medical OEMs and geographic expansion through distribution hub establishment.
Within the diversified conglomerate tier, Panasonic Holding Corporation exemplifies scale-driven positioning across Brazilian consumer electronics channels, while Murata Manufacturing Co., Ltd. anchors specialized solid-state presence through distribution networks serving Argentine medical OEMs. Maxell, Ltd. occupies a position representing precision cell manufacturing archetypes with heritage in compact power solutions. These three Japanese-origin corporations collectively illustrate how manufacturing depth and certification infrastructure determine competitive viability in ANVISA-regulated environments.
| Leading Market Players |
|---|
| Panasonic Holding Corporation |
| Murata Manufacturing Co., Ltd. |
| Maxell, Ltd |
| Duracell Inc. |
| Varta AG |
| TDK Corporation |
| Renata SA |
| Enfucell Oy |
| Molex |
| Others |
Pricing and Supply Chain Analysis
Specialized ceramic sintering technicians and thin-film deposition engineers concentrated in Brazil's São Paulo electronics corridor and Argentina's Córdoba medical technology cluster create labor-cost differentials that widen pricing-tier spreads between ANVISA-certified premium cells and uncertified economy imports.
Pricing Analysis
Bundled certification-and-testing services versus unbundled cell-only supply splits the market into divergent pricing architectures. Three-tier pricing structure across premium solid-state, standard lithium-polymer, and economy nickel-metal hydride levels reflects ANVISA documentation depth and INMETRO conformity status. Cost compression in the economy tier is intensifying because Asian exporters absorb customs hold penalties to maintain volume. Hospital procurement consortiums in São Paulo state exhibit the lowest price sensitivity, while Colombian tech startups in Bogotá's emerging corridor prioritize unit cost over certification bundles.
Supply Chain Analysis
Freight cost differentials between air-shipped solid-state ceramic membranes and sea-freighted lithium-polymer pouch cells reshape procurement economics for Argentine medical OEMs. Manufacturing concentration in Japan, South Korea, and China feeds regional assembly operations in Brazil and Argentina. Raw material dependencies on Chilean and Argentine salar brine lithium carbonate, Japanese ceramic electrolyte substrates, and Korean separator films create multi-point exposure. Single-source vulnerability for solid-state ceramic membranes constrains Córdoba implantable sensor manufacturers. Distribution runs through São Paulo state electronics corridor distributors serving Brazilian retail channels and certified medical device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Micro Battery Market functions as a regulatory compounder where ANVISA's updated thermal runaway testing mandates for medical device batteries are accelerating demand concentration around certified suppliers capable of delivering cycle-life documentation.
For Market Incumbents: Lock in hospital procurement consortium relationships in São Paulo state by building captive ANVISA pre-certification testing capabilities that preempt customs delays. Deepen backward integration into lithium-polymer cell assembly within Mercosur trade zones to deflect tariff exposure from Asian imports. Certification infrastructure investments represent the critical defensive lever against emerging European precision cell manufacturers seeking Mercosur market entry. For New Entrants and Emerging Players: Capture the Colombian medical technology corridor by establishing Bogotá distribution hubs before incumbent distributors consolidate Andean healthcare cluster relationships. The underdeveloped local cell sourcing environment in Colombia offers the most penetrable geography for first-mover suppliers. A go-to-market angle emphasizing rapid prototyping support for wearable tech startups differentiates against certification-heavy incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors building captive ANVISA testing capabilities rather than diversified electronics conglomerates with premium positioning. Long-term viability over the next decade hinges on Mercosur technical harmonization outcomes that could collapse redundant certification burdens. The signal to watch is unified battery safety standard ratification, which would trigger consolidation premiums for single-certification-capable suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pre-Certification Testing Investment | Captive thermal runaway documentation capabilities preempt Brazilian customs bottlenecks for medical device cell imports. |
| Mercosur Distribution Hub Establishment | Bogotá-based logistics nodes enable single-point access to Colombian, Peruvian, and Ecuadorian healthcare procurement channels. |
| Solid-State Ceramic Membrane Supply Agreement | Long-term offtake contracts with Japanese or Korean suppliers secure thermal stability credentials for Argentine implantable sensor OEMs. |
| Thin-Film Biocompatibility Certification Pathway | Polymer substrate integration documentation unlocks skin-adherent power architectures for Brazilian continuous glucose monitor manufacturers. |
| INMETRO Conformity Streamlining Program | Pouch-cell configuration pre-approval accelerates wearable technology launches across Chilean and Peruvian consumer channels. |
Research Methodology
Direct dialogue with biomedical engineers at Brazilian diagnostic equipment manufacturers, ANVISA regulatory affairs specialists, Argentine cardiac device procurement managers, and São Paulo state electronics corridor distributors grounded qualitative findings. Secondary validation drew from ANVISA medical device registration databases, INMETRO conformity assessment records, Mercosur technical harmonization negotiation documents, and Chilean salar brine production reports. Bottom-up cell shipment tracking and top-down healthcare procurement budget analysis enabled triangulation across data sources.
Bottom-up modeling of lithium-ion, lithium-polymer, nickel-metal hydride, and solid-state cell volumes by application—consumer electronics, medical devices, wearable technology, and IoT devices—anchored value projections across the analysis window. Segmentation dimensions included product chemistry, end-use certification regime, technology architecture, and geographic procurement cluster. CAGRs were derived from fitted growth curves incorporating ANVISA regulatory implementation timelines and INMETRO pathway streamlining effects. Industry-specific forecast inputs captured lithium carbonate price volatility from Chilean and Argentine salar operations and solid-state ceramic membrane supply constraints.
ANVISA protocol amendments, lithium carbonate spot price swings, and Mercosur technical harmonization ratification delays are the dominant revision risks to modeled projections. Forecasts reflect assumptions regarding certification timeline stability and raw material supply continuity. A model refresh is warranted upon material change in ANVISA thermal runaway testing mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
West Africa Battery Market
Batteries
HIT Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Solid Electrolyte Market
Batteries
Inverter Battery Market
Batteries
Nas Battery Market
Batteries
Lithium-Based Battery Charger Market
Batteries
France Rechargeable Battery Market
Batteries
Military Battery Packs Market
Batteries
Disposable Batteries Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
Lithium Starters Market
Batteries
Li-Mno2 Button Battery Market