
 Global Automotive Engine Management System Market | 2026-2036
Global Automotive Engine Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Engine Management System Market Intelligence
The divergence between feature-rich systems for luxury vehicles and cost-optimized units for mass-market cars is realigning the competitive landscape. Robert Bosch GmbH leverages its extensive R&D to dominate the high-end segment with integrated solutions. Continental AG competes by offering modular systems adaptable for various OEM platforms. Meanwhile, DENSO Corporation sustains its market position through manufacturing scale and strong relationships with Japanese automakers.
An automotive engine management system comprises a network of sensors, actuators, and an Electronic Control Unit (ECU) that collectively optimize an internal combustion engine's performance. Its primary function is to control fuel injection, ignition timing, and variable valve timing to maximize power output while minimizing emissions and fuel consumption. The Electronic Control Unit remains the core, highest-value component within the product type segmentation. Among technologies, turbocharging control and variable valve timing are seeing rapid integration to meet efficiency mandates.
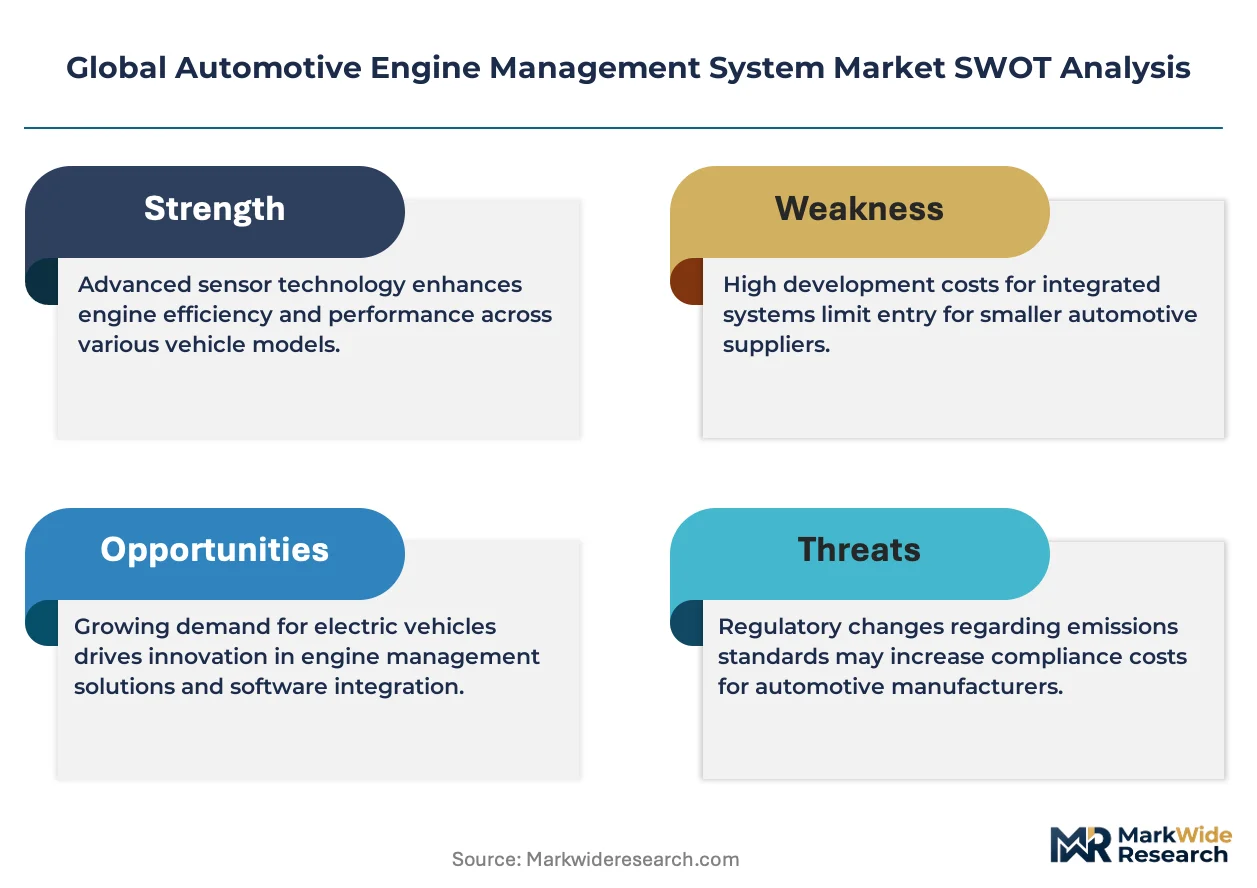
Stringent emissions regulations are the primary market driver, with mandates from the US Environmental Protection Agency (EPA), Europe's Euro 7, and China's VI standards setting the pace. These frameworks compel automakers to adopt more sophisticated engine management technologies to comply with tightening limits on NOx and CO2. The critical decision for suppliers is how to balance investment in legacy internal combustion engine technology against the long-term transition to electric vehicle platforms.
Market Dynamics
The central dynamic is the strategic conflict between maximizing the efficiency of internal combustion engines to meet near-term regulations and allocating R&D capital towards the inevitable long-term transition to electric vehicle powertrains.
Growth Catalysts
- Stringent Emissions Mandates:Europe's Euro 7 and China's VI standards create non-negotiable demand for advanced systems that can precisely control combustion to minimize NOx and CO2 output, particularly in passenger vehicles.
- Engine Downsizing and Boosting:The push for improved fuel economy drives the adoption of smaller, turbocharged engines, which require more complex management systems to control boost pressure, fuel delivery, and prevent engine knock.
- Manufacturing Hubs in Asia:The concentration of automotive production in China and India, coupled with government support for cleaner vehicle technologies, accelerates the adoption of sophisticated engine management systems in high-volume segments.
Market Restraints
- BEV Substitution:The accelerating market penetration of battery electric vehicles, which do not use internal combustion engines, directly reduces the total addressable market for engine management systems over the long term.
- Divergent R&D Investment:Suppliers face the capital-intensive burden of simultaneously funding R&D for next-generation ICE technologies and developing entirely new component portfolios for electric and hybrid vehicle platforms.
- ECU Integration Cost:The high cost and complexity of the Electronic Control Unit (ECU), the system's core component, can be a barrier for cost-sensitive, mass-market vehicle segments in emerging economies.
Strategic Opportunities
- Hybrid Vehicle Systems:The growing market for hybrid electric vehicles creates an opportunity for integrated systems that manage the complex interplay between the internal combustion engine and the electric motor for optimal efficiency.
- Performance Aftermarket:A significant opportunity exists in the performance aftermarket, where enthusiasts and racing teams demand customizable ECUs and sensors to optimize engine output beyond factory specifications.
- Two-Wheeler Market in India:The vast and modernizing two-wheeler market in India presents a large, underpenetrated segment for cost-effective, emissions-compliant engine management systems as its own emissions regulations tighten.
Industry Challenges
- Software Complexity and Validation:The exponential growth in software code within modern ECUs creates significant challenges in debugging and validation, extending development timelines and increasing cybersecurity risks.
- Sensor Integration and Calibration:Integrating a growing network of sensors for parameters like exhaust gas temperature and particulate matter requires extensive calibration to ensure accurate data for the ECU, increasing system-level complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Engine Management System Market |
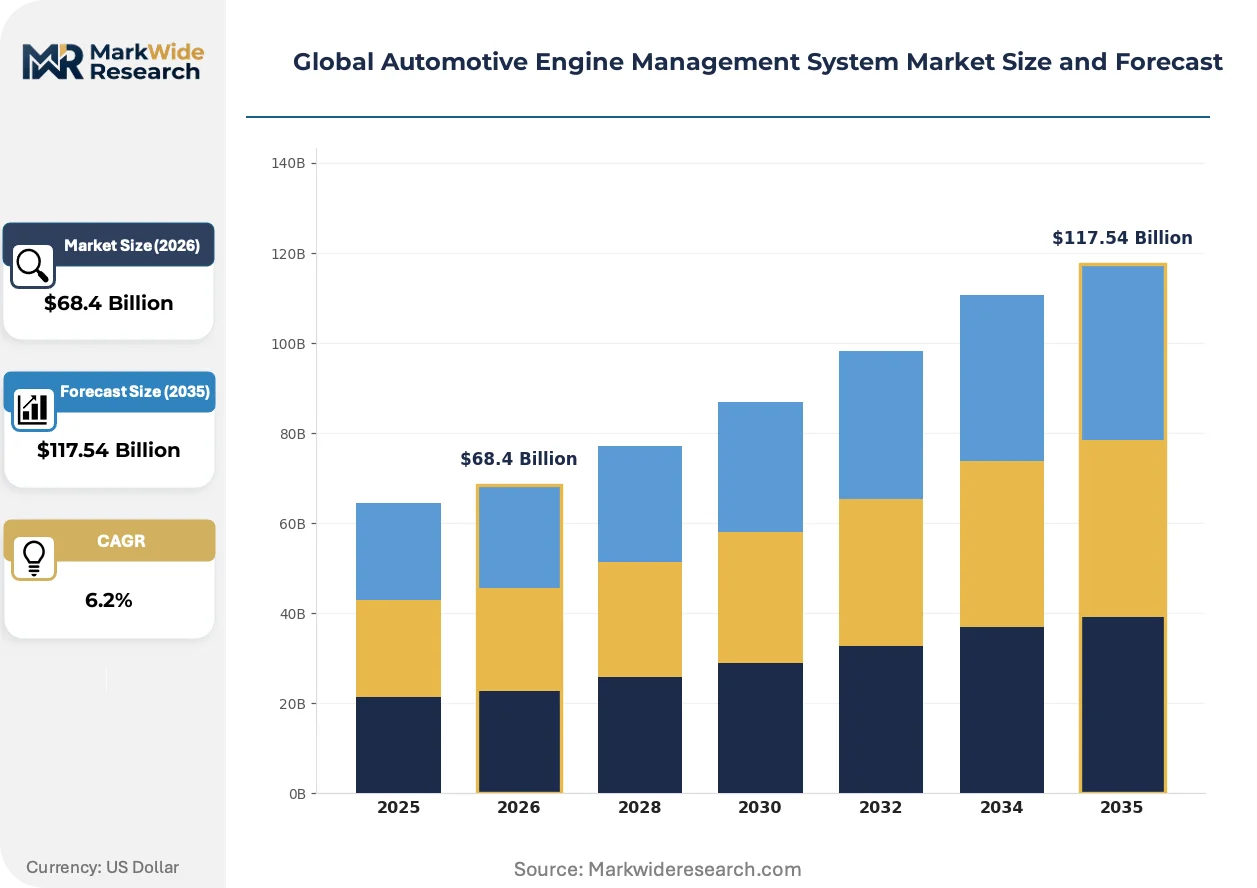
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Control Unit, Fuel Injection Control, Ignition Control, Transmission Control, Sensor Systems, Emission Control Technology: Drive-by-Wire, Turbocharging Control, Cylinder Deactivation, Variable Valve Timing, Electronic Throttle Control, Exhaust Gas Recirculation Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Off-Road Vehicles, Two-Wheelers, Marine Engines End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Dealerships, Fleet Operators |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, BorgWarner Inc., Valeo SA, Hitachi Automotive Systems, Infineon Technologies AG, NGK Spark Plug Co., Ltd., Magneti Marelli S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Engine Management System Market Strategic Shifts & Innovations
A fundamental shift is underway where software and data analytics are becoming the primary value drivers in engine optimization. This trend redefines system performance beyond mechanical hardware, focusing on intelligent control and predictive capabilities.
Variable valve timing (VVT) technology dynamically alters the timing of an engine's valve lift to improve performance and efficiency. Passenger vehicle OEMs are rapidly adopting advanced VVT to meet fuel economy targets. Sophisticated VVT control is integrating with turbocharging and direct injection systems, enabling a more holistic and responsive powertrain management strategy.
The US Environmental Protection Agency's (EPA) tightening emissions standards for both criteria pollutants and greenhouse gases place direct pressure on engine performance. This forces automakers to deploy more advanced ECU logic and sensor suites for precise, real-time combustion control. The commercial truck segment is particularly impacted, accelerating adoption of engine management systems that coordinate with exhaust after-treatment technologies.
Automakers are increasingly sourcing complete, modular engine management platforms from single Tier-1 suppliers. This model disrupts the traditional approach of procuring discrete sensors, actuators, and ECUs from a fragmented base of component specialists. This preference for pre-integrated solutions is most visible in North America and Europe, where it helps OEMs reduce internal development costs and shorten vehicle launch cycles.
Global Automotive Engine Management System Market Segmentation
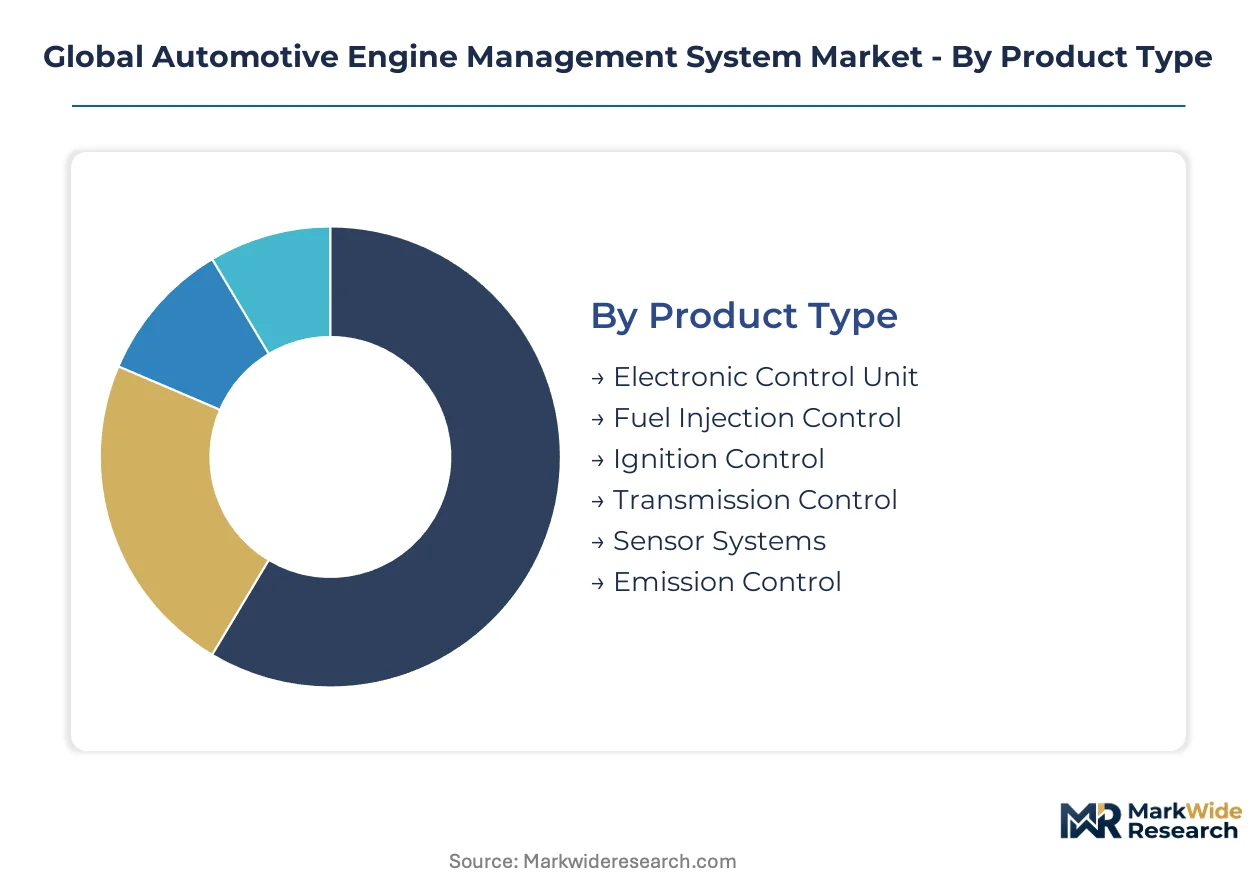
The global automotive engine management system market segments across various product types, technologies, applications, and end-users. This segmentation reflects the diverse requirements for optimizing internal combustion engine performance and meeting stringent emission standards worldwide. Understanding these categories is critical for strategic planning.
Product Type:
The product type segmentation highlights components ranging from standalone control units to deeply integrated sensor networks within engine management systems.
- Electronic Control Unit:This component serves as the central processing unit, executing complex algorithms for engine operation. Demand concentrates in new vehicle production in China, driven by precise combustion control requirements.
- Sensor Systems:These encompass a network of sensors monitoring parameters like exhaust gas temperature, feeding data to the ECU. Automakers in Europe drive adoption to comply with Euro 7 emission standards.
- Fuel Injection Control:This system precisely meters and delivers fuel into engine cylinders, optimizing combustion efficiency.
- Ignition Control:The ignition control module manages spark timing for efficient combustion and reduced emissions.
- Transmission Control:This system optimizes gear shifts for improved fuel economy and vehicle performance.
- Emission Control:These components manage exhaust gases to reduce pollutants like NOx and CO2.
Electronic Control Unit leads volumes today; Sensor Systems is gaining share fastest.
Technology:
Technology segmentation showcases innovations aimed at enhancing engine efficiency and reducing environmental impact across diverse vehicle applications.
- Variable Valve Timing:This technology dynamically adjusts valve operation to optimize engine breathing, improving performance and fuel economy. Passenger vehicle OEMs globally adopt VVT to meet fuel efficiency targets.
- Turbocharging Control:This system manages boost pressure in turbocharged engines, enhancing power output while maintaining fuel efficiency. Demand is high in Europe due to engine downsizing strategies.
- Drive-by-Wire:This technology replaces mechanical linkages with electronic signals for throttle, steering, or braking control.
- Cylinder Deactivation:This system temporarily shuts down engine cylinders during light loads to save fuel.
- Electronic Throttle Control:This system electronically manages the throttle valve opening for precise air intake control.
- Exhaust Gas Recirculation:EGR systems reduce NOx emissions by reintroducing exhaust gas into engine cylinders.
Variable Valve Timing and Turbocharging Control see widespread integration, while Exhaust Gas Recirculation remains foundational for emissions.
Application:
Application segmentation reflects the varying scale and performance requirements for engine management systems across different vehicle types.
- Passenger Vehicles:This segment represents the largest volume market, with adoption accelerating due to stringent emission regulations like Europe's Euro 7. Automakers integrate advanced systems for fuel economy.
- Two-Wheelers:The vast Indian market presents a significant opportunity for cost-effective engine management systems as local emission regulations tighten. Modernizing two-wheelers require precise fuel and ignition control.
- Commercial Vehicles:This segment includes vans and light trucks, requiring robust systems for efficiency and durability.
- Heavy-Duty Trucks:These vehicles demand highly durable and efficient engine management systems to meet strict EPA emissions standards.
- Off-Road Vehicles:Engine management for off-road vehicles focuses on reliability and performance under harsh operating conditions.
- Marine Engines:Marine applications require specialized systems to operate efficiently in diverse water environments.
Passenger Vehicles drive significant regulatory compliance, while Heavy-Duty Trucks face increasingly strict mandates.
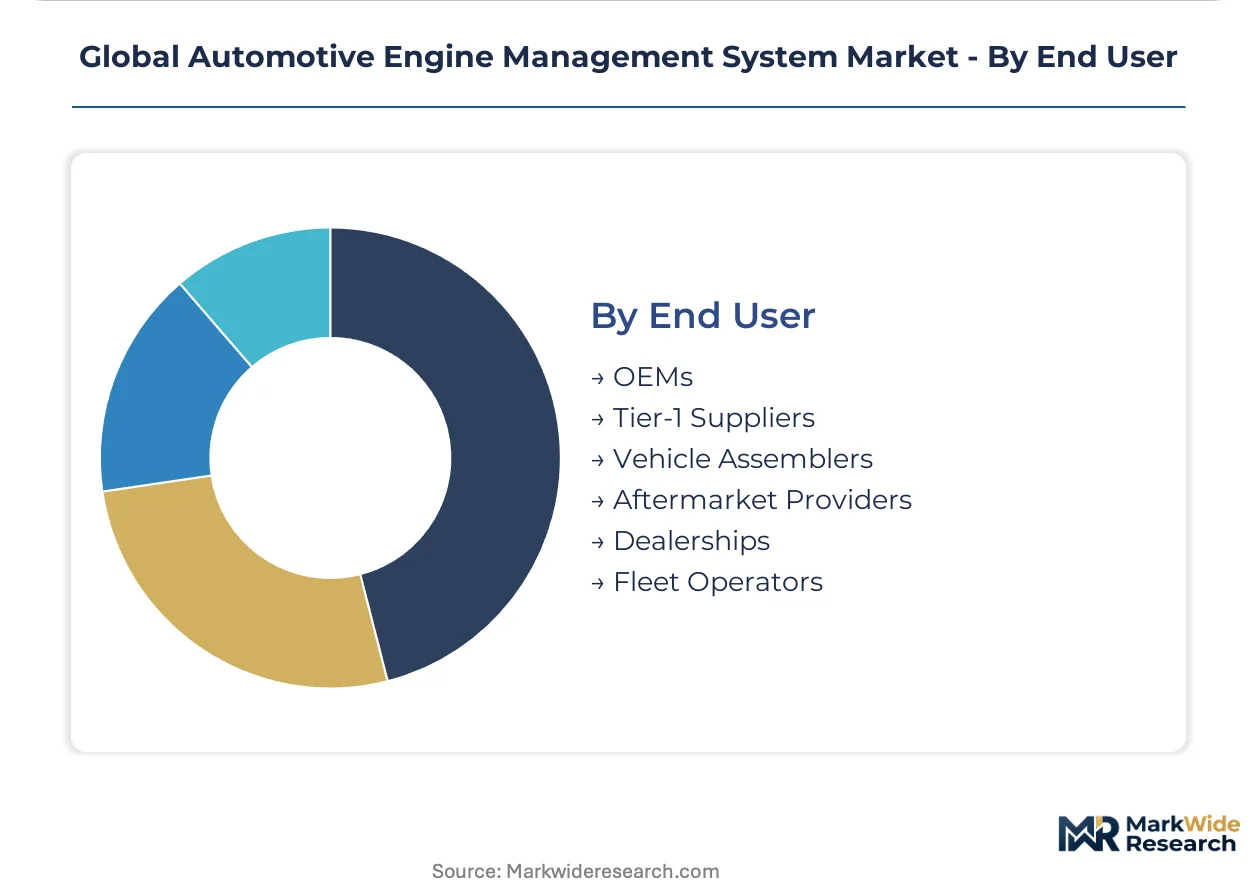
End User:
End-user segmentation delineates the various stakeholders across the automotive value chain involved in the procurement and utilization of engine management systems.
- OEMs:Original Equipment Manufacturers are the primary consumers, integrating complete engine management systems into new vehicle designs. Preference for pre-integrated solutions is notable in North America.
- Aftermarket Providers:This segment caters to vehicle owners and racing teams seeking customizable ECUs and sensors for performance optimization. Enthusiasts demand enhanced engine output.
- Tier-1 Suppliers:These companies develop and supply integrated engine management system modules directly to OEMs.
- Vehicle Assemblers:These entities integrate engine management components into the final vehicle assembly process.
- Dealerships:Dealerships primarily provide maintenance and replacement services for engine management system components.
- Fleet Operators:Fleet operators focus on systems enhancing fuel efficiency and reducing maintenance costs.
OEMs exert substantial influence over product development, while Aftermarket Providers cater to specialized performance demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled engineering talent in Germany anchors the European automotive engine management system market. This talent pool drives innovation in sophisticated systems for internal combustion engines. Demand for advanced solutions is concentrated in manufacturing hubs across Europe.
China
China's extensive automotive manufacturing workforce drives demand for advanced engine management systems. The country's VI emission rules compel automakers to adopt precise combustion control technologies. Production hubs like Shanghai and Guangzhou concentrate new vehicle output, integrating complex ECUs.
Germany
German engineering prowess fuels the development of feature-rich engine management systems for luxury vehicles. Europe's Euro 7 standards place significant pressure on manufacturers to minimize emissions. Stuttgart and Munich serve as key centers for R&D and advanced system integration.
India
India's growing automotive manufacturing base, particularly for two-wheelers, presents a substantial market for cost-effective engine management solutions. The country's evolving emission regulations necessitate more sophisticated fuel and ignition control. Chennai and Pune are significant manufacturing clusters for these high-volume applications.
United States
United States Environmental Protection Agency (EPA) standards for criteria pollutants and greenhouse gases compel adoption of advanced engine management. Commercial truck manufacturers integrate robust systems coordinating with exhaust after-treatment technologies. Detroit remains a core hub for automotive OEM and Tier-1 supplier R&D.
Japan
Japanese automakers, with their strong supplier relationships, prioritize reliable and efficient engine management systems. METI initiatives support the integration of advanced variable valve timing and turbocharging control. Toyota City and Hiroshima are central to powertrain development and manufacturing.
Global Automotive Engine Management System Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized component manufacturers compete in niche areas with cost-optimized units. The market exhibits a tiered structure, with established players dominating integrated system solutions for high-end vehicles. Several strategic archetypes emerge, including comprehensive solution providers, adaptable platform specialists, and regional manufacturing powerhouses. Companies pursue strategic partnerships and portfolio diversification to enhance their offerings and maintain competitive positioning across diverse vehicle segments.
On the premium-tier vector, Robert Bosch GmbH exemplifies a comprehensive solution provider, leveraging extensive R&D for integrated systems across diverse vehicle types. Continental AG, a German-based AG, occupies a position as a modular systems specialist, adapting its solutions for various OEM platforms globally. DENSO Corporation, a Japanese Corporation, anchors the market through significant manufacturing scale and strong relationships with Asian automakers, particularly in high-volume segments. These prominent players represent distinct approaches to market penetration and technology integration within the evolving automotive engine management system landscape.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| BorgWarner Inc. |
| Valeo SA |
| Hitachi Automotive Systems |
| Infineon Technologies AG |
| NGK Spark Plug Co., Ltd. |
| Magneti Marelli S.p.A. |
| Others |
Cost & Logistics Intelligence
Semiconductor component costs for ECUs, sourced globally, directly influence the final pricing of engine management systems across premium and mass-market vehicle segments. This upstream cost pressure flows through Tier-1 suppliers to OEMs, impacting overall vehicle manufacturing expenses.
Pricing Analysis
Bundled engine management system solutions from Tier-1 suppliers command premium pricing due to integrated software and validation services, while discrete component sales follow a transactional model. Customization level for specific vehicle platforms and brand premium for advanced technology are key price differentiation drivers. Pricing pressure stems from cost-sensitive mass-market vehicle segments in emerging economies. Luxury vehicle OEMs demonstrate lower price sensitivity for feature-rich systems.
Supply Chain Analysis
Semiconductor raw material sourcing for microcontrollers depends on specialized fabs primarily in Taiwan and South Korea. Key components like precision sensors and power semiconductors also draw from concentrated manufacturing in Japan and Germany. Single-source vulnerability for advanced chipsets represents a structural supply chain risk. Distribution runs through direct supply relationships from Tier-1 manufacturers to global automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive engine management system market presents a late-cycle quality story, driven by a demand-shift toward premium specifications for precise emissions control.
For Market Incumbents: Anchor research and development efforts in software-defined engine management systems to anticipate evolving vehicle architectures. Develop integrated hybrid powertrain control solutions to mitigate the threat of BEV substitution. Establish strong IP in predictive maintenance algorithms. Pursue strategic vertical integration into critical sensor manufacturing to secure supply chains.
For New Entrants and Emerging Players: Begin with niche applications in the performance aftermarket, where demand for customizable ECUs is high. Target the cost-effective Indian two-wheeler market for emissions-compliant systems, leveraging its high volume and underpenetration. Focus on specialized solutions for commercial vehicle retrofits to extend ICE lifespan. A direct-to-consumer digital platform for aftermarket sales provides a viable go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where software complexity and validation costs create barriers to entry for smaller players. Long-term viability depends on dual investment in ICE optimization and EV component development over the next 5-10 years. Acquisition targets include mid-sized specialists with strong software IP or niche sensor expertise. OEM preference for complete, modular engine management platforms is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in software-defined vehicle platforms | Enhances system adaptability and enables over-the-air updates for performance optimization. |
| Develop integrated hybrid powertrain controls | Optimizes energy management between ICE and electric motors for efficiency gains. |
| Expand manufacturing footprint in Asia | Captures high-volume demand from growing automotive production hubs in China and India. |
| Secure long-term semiconductor supply agreements | Mitigates supply chain risks and ensures component availability for ECU production. |
| Enhance cybersecurity for ECUs | Protects critical vehicle systems from evolving digital threats and ensures functional safety. |
Research Approach
Bottom-up passenger vehicle modeling reconciled against top-down Tier-1 supplier tracking forms the analytical core for this study. Primary interviews with OEM platform engineers, Tier-1 procurement leads, aftermarket distributors, and regulatory compliance officers provided qualitative insights. Secondary validation drew from vehicle production databases, IHS Markit registration data, government emissions reports, and industry association publications. This approach ensured robust bottom-up and top-down triangulation.
An input-output matrix underpins the forecast framework, correlating market drivers with anticipated segment growth across the analysis window. Modeled segmentation dimensions include product type, technology, application, end-user, and regional manufacturing clusters. Compound annual growth rates were derived from projected segment growth rates. Vehicle production volumes and emission regulation timelines served as critical forecast inputs.
Caveats apply where rapid shifts in electric vehicle adoption rates could materially shift the outlook. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Geopolitical events or raw material price volatility represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market