
 Steering Column Control Modules Market | 2026-2036
Steering Column Control Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Column Control Modules Market Outlook
Germany is tilting toward expanded steering module capacity as domestic OEMs electrify platforms. Leopold Kostal GmbH & Co. KG leverages deep integration with European premium vehicle programs. Valeo sustains R&D intensity in drive-by-wire architectures across multiple continents. ZF TRW anchors production scale for electromechanical steering columns in North American and Asian assembly plants.
Steering column control modules integrate electronic control units, sensor arrays, and mechanical couplings within the steering shaft assembly to translate driver input into directional vehicle response with precision feedback. The units typically incorporate torque sensors, angle position encoders, and CAN bus interfaces operating at 500 kbit/s to communicate with vehicle dynamics controllers. Electronic Control Units capture the dominant margin pool as software-defined steering functions proliferate across passenger vehicle platforms. Drive-by-Wire technology represents the fastest-expanding segment, though hydraulic systems retain substantial share in heavy-duty commercial applications where load-bearing requirements exceed electric actuator limits.
EU Green Deal emissions mandates and ECE R79 steering equipment regulations shape product certification requirements across European markets, while NHTSA FMVSS 126 electronic stability control standards govern North American market access. REACH chemical compliance and RoHS substance restrictions further constrain material selection for circuit boards and sensor housings. Stakeholders must monitor regulatory divergence between EU AI Act provisions for autonomous steering systems and emerging functional safety standards for software-defined vehicle architectures.
Market Dynamics
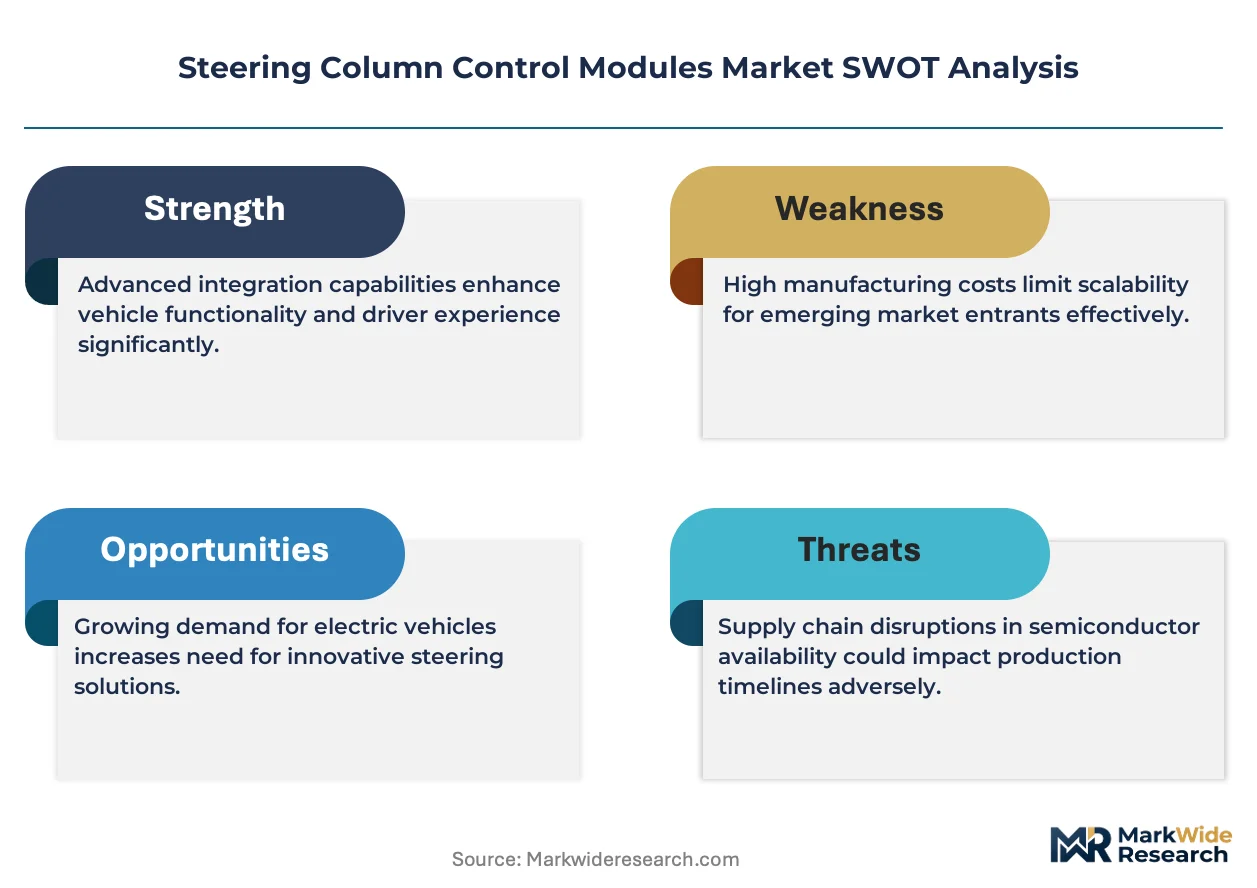
Drive-by-wire architectures are compressing mechanical steering linkages into software-defined control loops, forcing module suppliers to absorb torque-sensor calibration and functional-safety validation burdens previously held by tier-two component makers.
Growth Catalysts
- EU Green Deal electrification mandates:Germany, France, and Italy have tightened fleet emissions targets that require integrated steering electronics for energy-efficient electric powertrains.
- Passenger vehicle platform consolidation:OEMs are unifying steering control architectures across multiple nameplates to reduce variant complexity and software validation costs.
- Stuttgart-Wolfsburg supplier clustering:Tier-1 engineering density around German assembly ecosystems accelerates prototype-to-production cycles for electromechanical modules.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese processing facilities destabilize electric motor actuator cost models.
- Single-source torque sensor dependency:Precision magnetic encoder supply concentrates in Japanese and German specialty manufacturers, creating vulnerability.
- ECE R79 certification friction:Type-approval timelines for steer-by-wire systems extend 18-24 months, delaying revenue recognition for new platform launches.
Strategic Opportunities
- Commercial vehicle electrification:Heavy-duty truck fleets in Germany and the Netherlands are retrofitting hydraulic steering with electromechanical alternatives for urban low-emission zones.
- EU AI Act autonomous steering provisions:Functional-safety certification frameworks for self-driving systems create first-mover advantage for validated module suppliers.
- Sensor-actuator convergence:Integration of torque, angle, and force-feedback sensing into single-package smart actuators reduces wiring harness complexity.
Industry Challenges
- ISO 26262 functional-safety talent scarcity:ASIL-D certified firmware engineers command premium compensation, constraining R&D scaling.
- Legacy CAN bus integration complexity:New 500 kbit/s steering modules must coexist with older 250 kbit/s vehicle networks without signal latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Column Control Modules Market |
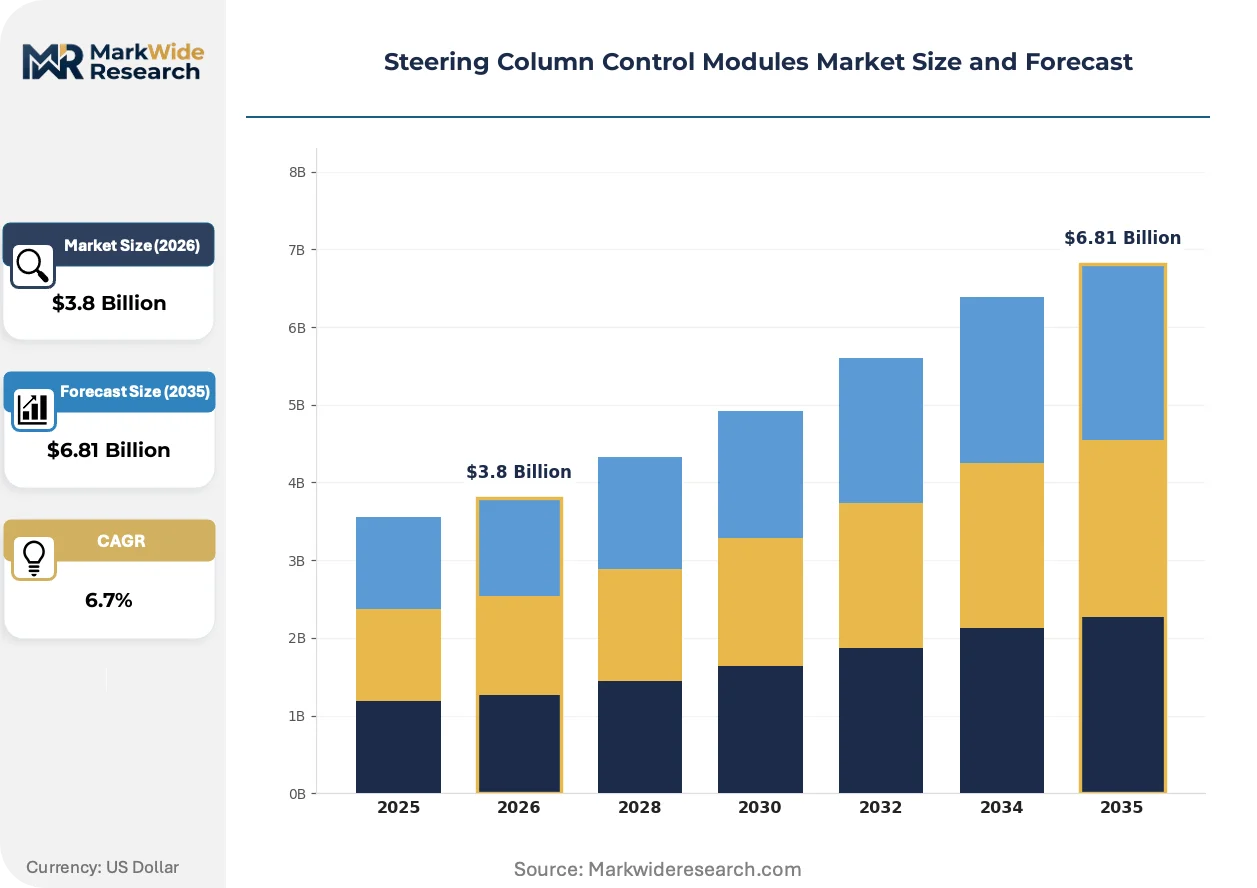
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Control Units, Mechanical Couplings, Integrated Modules, Safety Systems Technology: Power Steering, Drive-by-Wire, Electric Control, Hydraulic Systems End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Specialty Vehicles |
| Companies Covered | Leopold Kostal GmbH & Co. KG, Ididit, Valeo, DENSO Corp., BorgWarner Inc., ZF TRW, Nexteer Automotive, HELLA GmbH and Co. KGaA, Delphi Automotive LLP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Column Control Modules Market Strategic Shifts
Steering module architectures are bifurcating into compact integrated units for passenger cars and ruggedized heavy-duty variants, with software-defined functionality becoming the primary differentiation axis across both segments.
Magnetic torque sensing with tunnel magnetoresistance technology is rendering obsolete traditional strain-gauge load cells in electromechanical steering columns. German premium OEMs have adopted TMR-based modules across their electric vehicle platforms since 2022. The shift eliminates mechanical wear points while enabling sub-degree steering precision for lane-keeping assistance.
REACH chemical compliance and RoHS substance restrictions are constraining solder alloy selection and sensor housing metallurgy across European supply chains. Module manufacturers must validate alternative tin-silver-copper compositions for high-vibration steering environments. The regulatory pressure falls most heavily on mid-volume suppliers lacking in-house materials laboratories.
Fleet procurement departments are consolidating steering module sourcing through long-term platform agreements rather than model-specific contracts. Tier-1 suppliers now negotiate multi-year supply commitments covering five to seven vehicle generations. The pattern is most pronounced in German OEM purchasing organizations seeking volume leverage for electromechanical system transitions.
Steering Column Control Modules Market Segmentation
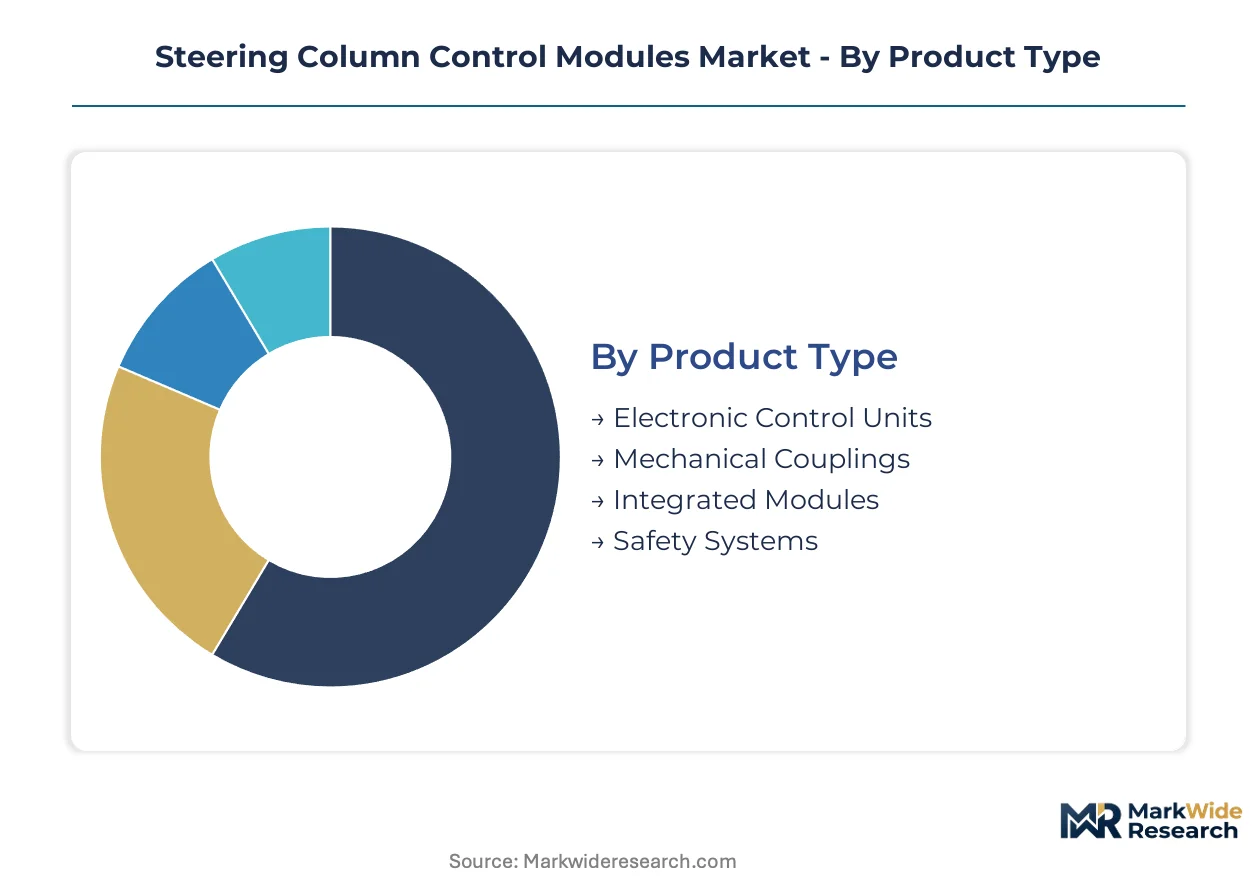
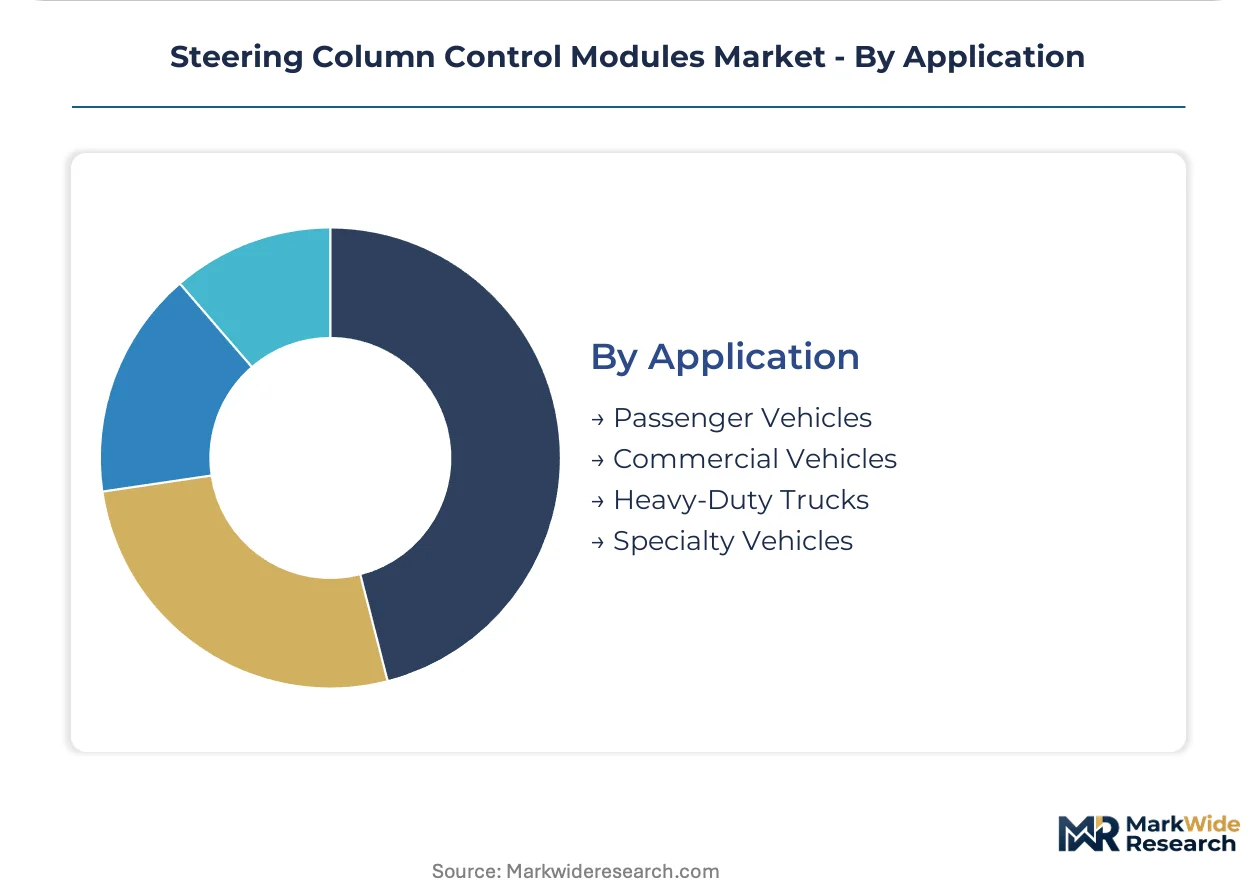
Steering column control modules serve divergent performance requirements across vehicle platforms, from precision feedback systems in passenger cars to load-bearing architectures in commercial fleets. Segmentation reveals how torque-sensor calibration, functional-safety certification, and electromechanical integration priorities shift by application context and supply-chain position.
Product Type:
Use-case spectrum spans discrete component supply for legacy platform maintenance through fully integrated smart actuators for next-generation electric vehicles.
- Electronic Control Units:Embedded firmware platforms executing torque-vectoring algorithms and lane-keeping assistance protocols at ASIL-D safety integrity. Demand concentrates in Stuttgart and Wolfsburg assembly ecosystems where German premium OEMs electrify platforms under EU Green Deal mandates.
- Integrated Modules:Single-package units combining ECU, sensor arrays, and mechanical couplings to reduce wiring harness complexity and assembly-line touchpoints. French and Italian OEM procurement departments favor these for platform consolidation across multiple nameplates.
- Mechanical Couplings:Precision-machined shaft assemblies transmitting driver input to steering racks in hybrid architectures retaining partial mechanical linkage.
- Safety Systems:Redundant torque-limiting and column-collapse mechanisms meeting ECE R79 occupant protection requirements.
The dominant share belongs to Electronic Control Units, while Integrated Modules is closing the gap fastest.
Technology:
Cost tier stratification separates premium electromechanical systems from legacy hydraulic architectures still prevalent in heavy-duty applications.
- Drive-by-Wire:Fully electronic steering control eliminating mechanical linkage through redundant actuator networks and force-feedback motors. German KBA type-approval timelines extend 18-24 months for these systems, delaying revenue recognition despite OEM demand for autonomous-ready platforms.
- Electric Control:Electromechanical power steering with retained mechanical backup, dominating mid-range passenger vehicle segments where energy efficiency targets meet cost constraints.
- Power Steering:Conventional assisted steering architectures with electric motor augmentation of mechanical linkages.
- Hydraulic Systems:Fluid-pressure steering assist retaining substantial share in heavy-duty commercial applications where load-bearing requirements exceed electric actuator torque limits.
Electric Control holds the dominant position, though Drive-by-Wire demonstrates the steepest expansion trajectory as EU AI Act autonomous steering provisions mature.
End User:
Volume concentration varies sharply between direct OEM supply relationships and fragmented aftermarket channels with divergent certification burdens.
- OEMs:Direct supply to vehicle manufacturers with multi-year platform agreements covering five to seven vehicle generations, concentrated in German purchasing organizations seeking leverage for electromechanical transitions.
- Vehicle Assemblers:Contract manufacturing partners requiring validated module supply for badge-engineered or regional-market variants.
- Fleet Operators:Heavy-duty truck and bus fleets in Germany and the Netherlands retrofitting hydraulic steering with electromechanical alternatives for urban low-emission zone compliance.
- Aftermarket Providers:Replacement module distribution through independent service networks facing REACH and RoHS compliance validation without in-house materials laboratories.
OEMs command the dominant procurement volume, while Fleet Operators are gaining share fastest as commercial electrification mandates tighten.
Application:
Margin structure diverges between high-volume passenger vehicle production and specialized heavy-duty variants with ruggedized component requirements.
- Passenger Vehicles:Compact integrated units prioritizing sub-degree steering precision for lane-keeping assistance, with tunnel magnetoresistance torque sensors displacing strain-gauge load cells across German premium electric platforms.
- Heavy-Duty Trucks:Load-bearing electromechanical columns with enhanced thermal management and vibration isolation for continuous-duty commercial operation.
- Commercial Vehicles:Mid-duty buses and delivery vans requiring modular actuator architectures adaptable to multiple wheelbase configurations.
- Specialty Vehicles:Agricultural, construction, and military applications with sealed-environment requirements and non-standard steering geometries.
Passenger Vehicles retains the dominant application share, while Heavy-Duty Trucks is climbing the fastest as fleet electrification retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes steering column control modules through premium OEM electrification programs, while the United States and China deploy them across broader vehicle segments with divergent regulatory timelines for autonomous steering certification.
Germany
KBA type-approval requirements for steer-by-wire systems extend 18-24 months, compressing supplier revenue cycles despite Stuttgart and Wolfsburg assembly ecosystems driving prototype-to-production velocity for electromechanical modules under EU Green Deal fleet mandates.
United States
NHTSA FMVSS 126 electronic stability control standards govern market access, with Detroit-area OEM procurement consolidating multi-year platform agreements covering five to seven vehicle generations to leverage volume for electromechanical transitions.
China
MIIT new energy vehicle mandates accelerate domestic OEM demand for integrated steering electronics, with Yangtze River Delta manufacturing clusters absorbing module supply for both local brands and joint-venture platforms serving export markets.
Japan
METI carbon neutrality roadmaps pressure domestic automakers toward drive-by-wire architectures, while precision magnetic encoder supply concentration in Japanese specialty manufacturers creates single-source dependency for torque-sensor calibration.
France
ANSM technical standards alignment with EU AI Act autonomous steering provisions shapes functional-safety certification frameworks, as Paris-based OEM procurement departments favor integrated modules for platform consolidation across multiple nameplates.
Steering Column Control Modules Market Competitive Environment
Capability concentration sits with precision sensor and firmware specialists; scale advantage sits with diversified automotive suppliers possessing multi-continental manufacturing footprints. The vendor base separates into three archetypes: integrated module specialists, ECU-focused firmware developers, and diversified Tier-1 systems integrators. Dominant competitive moves include long-term platform agreements binding OEMs to single-source supply and backward integration into torque-sensor manufacturing to reduce rare-earth magnet cost exposure.
Among Germany-based fabricators, Leopold Kostal GmbH & Co. KG and ZF TRW exemplify the integrated module archetype, occupying positions within Stuttgart-Wolfsburg supplier ecosystems. Valeo represents the diversified Tier-1 category, anchoring multi-continental R&D intensity in drive-by-wire architectures. These three entities collectively illustrate how geographic clustering around premium OEM electrification programs shapes competitive positioning.
| Leading Market Players |
|---|
| Leopold Kostal GmbH & Co. KG |
| Ididit |
| Valeo |
| DENSO Corp. |
| BorgWarner Inc. |
| ZF TRW |
| Nexteer Automotive |
| HELLA GmbH and Co. KGaA |
| Delphi Automotive LLP |
| Others |
Value Chain & Pricing Dynamics
Stuttgart-Wolfsburg supplier clustering concentrates electromechanical module capacity, translating engineering proximity into pricing leverage for Tier-1 incumbents serving German premium OEM electrification programs. Module manufacturers absorb torque-sensor calibration burdens while passing rare-earth magnet cost volatility downstream, compressing margins for mid-volume suppliers lacking captive magnet supply.
Pricing Analysis
German-manufactured modules command 15-25% premiums over Asian-sourced equivalents, reflecting KBA type-approval validation and ASIL-D certification tiers. Pricing stratifies across premium, standard, and economy levels based on functional-safety integrity and software-defined feature depth. Cost compression in the standard tier intensifies because Chinese OEM procurement teams negotiate volume leverage for electric powertrain platforms. Fleet operators exhibit highest price sensitivity due to retrofit budget constraints, while German premium OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for rare-earth magnet procurement. Manufacturing concentrates in Germany, China, and Japan, with precision magnetic encoder supply anchored in Japanese specialty manufacturers. The industry draws from neodymium-dysprosium magnets, copper windings, and silicon steel laminations as critical inputs. Single-source vulnerability concentrates in torque-sensor calibration equipment. Distribution runs through direct OEM platform agreements rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as commercial vehicle electrification mandates tighten across German and Dutch urban low-emission zones, triggering fleet retrofit demand that absorbs excess module capacity.
For Market Incumbents: Build certification moats through accelerated ASIL-D firmware validation and KBA type-approval pipeline expansion. Backward integration into torque-sensor manufacturing reduces rare-earth magnet cost exposure from Chinese processing volatility. Capacity addition in the Yangtze River Delta captures MIIT new energy vehicle mandate growth for domestic OEM supply. For New Entrants and Emerging Players: Mid-volume aftermarket providers lacking REACH-compliant materials laboratories represent the most penetrable entry point for certified module refurbishment services. Dutch heavy-duty truck fleets retrofitting hydraulic steering for urban low-emission zone compliance offer concentrated demand aggregation. Go-to-market execution should anchor on long-term platform agreements mimicking German OEM procurement patterns. For Investors and Strategic Acquirers: Long-term, this sits as a functional-safety consolidation play because ISO 26262 talent scarcity and ECE R79 certification friction create durable barriers for unvalidated competitors. Acquisition targets should display captive torque-sensor calibration capability and existing KBA approval pipeline depth. The signal to watch is EU AI Act autonomous steering provision finalization accelerating steer-by-wire platform commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | German OEM procurement consolidates multi-generational supply agreements reducing variant complexity. |
| Software-Defined Vehicle Investment | Drive-by-wire architectures compress mechanical linkages into firmware-validated control loops. |
| Backward Integration into Sensor Manufacturing | TMR torque sensor captive production eliminates single-source dependency on Japanese encoders. |
| Geographic Manufacturing Footprint | Yangtze River Delta assembly plants capture MIIT mandate-driven domestic OEM volume. |
| Functional-Safety Certification Acceleration | ASIL-D validation pipeline expansion creates first-mover advantage under EU AI Act provisions. |
Study Parameters
A spread of perspectives from Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and KBA type-approval specialists converged on the working assumptions underlying demand quantification. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and ECE R79 regulatory documentation. Bottom-up module shipment estimates triangulated against top-down OEM electrification platform announcements.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from fitted growth curves applied to baseline OEM platform rollout schedules, incorporating EU Green Deal fleet mandate compliance timelines and commercial vehicle retrofit adoption curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in rare-earth magnet pricing, semiconductor availability, or German automotive export demand would shift the trajectory. Forecasts reflect documented assumptions regarding KBA type-approval timeline stability and ECE R79 regulatory continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Automotive Digital Isolators Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market