
 Global Automotive Display System Market | 2026-2036
Global Automotive Display System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Display System Market Analysis
Capital-intensity divergence between display foundry operators and module integrators is bifurcating competitive returns across the value chain. Samsung Display leverages captive OLED wafer capacity to anchor premium supply contracts with luxury OEMs. Continental sustains module-level dominance through deep integration with German vehicle assemblers and their tier-1 procurement frameworks. BOE competes aggressively on LCD cost curves, extending its position in high-volume instrument cluster supply for mass-market brands.
Automotive display systems encompass electronic visualization interfaces engineered with luminance ratings exceeding 800 cd/m², wide color gamut coverage, and operational temperature tolerances spanning -40°C to 85°C for reliable cockpit performance under direct solar loading. Their primary commercial purpose is delivering navigation, vehicle telemetry, entertainment, and advanced driver-assistance visualizations to operators and passengers. Infotainment systems and head-up displays command the dominant share of current value generation, while OLED technology represents the fastest-expanding technology dimension as automakers phase out LCD for curved, high-contrast cockpit surfaces. Touchscreen interfaces concentrate margin pools in projected capacitive architectures, where gesture recognition and haptic feedback integration differentiate supplier offerings.
FCC certification requirements govern electromagnetic emissions from connected display modules in the US market, while ECE R121 in Europe mandates minimum legibility standards for speedometer and tell-tale visualizations. Japan's METI enforces energy efficiency benchmarks that shape backlighting architecture decisions for instrument clusters exported to that market. OEMs and tier-1 suppliers must monitor regulatory fragmentation across these jurisdictions when standardizing platform architectures for multi-region vehicle programs.
Market Dynamics
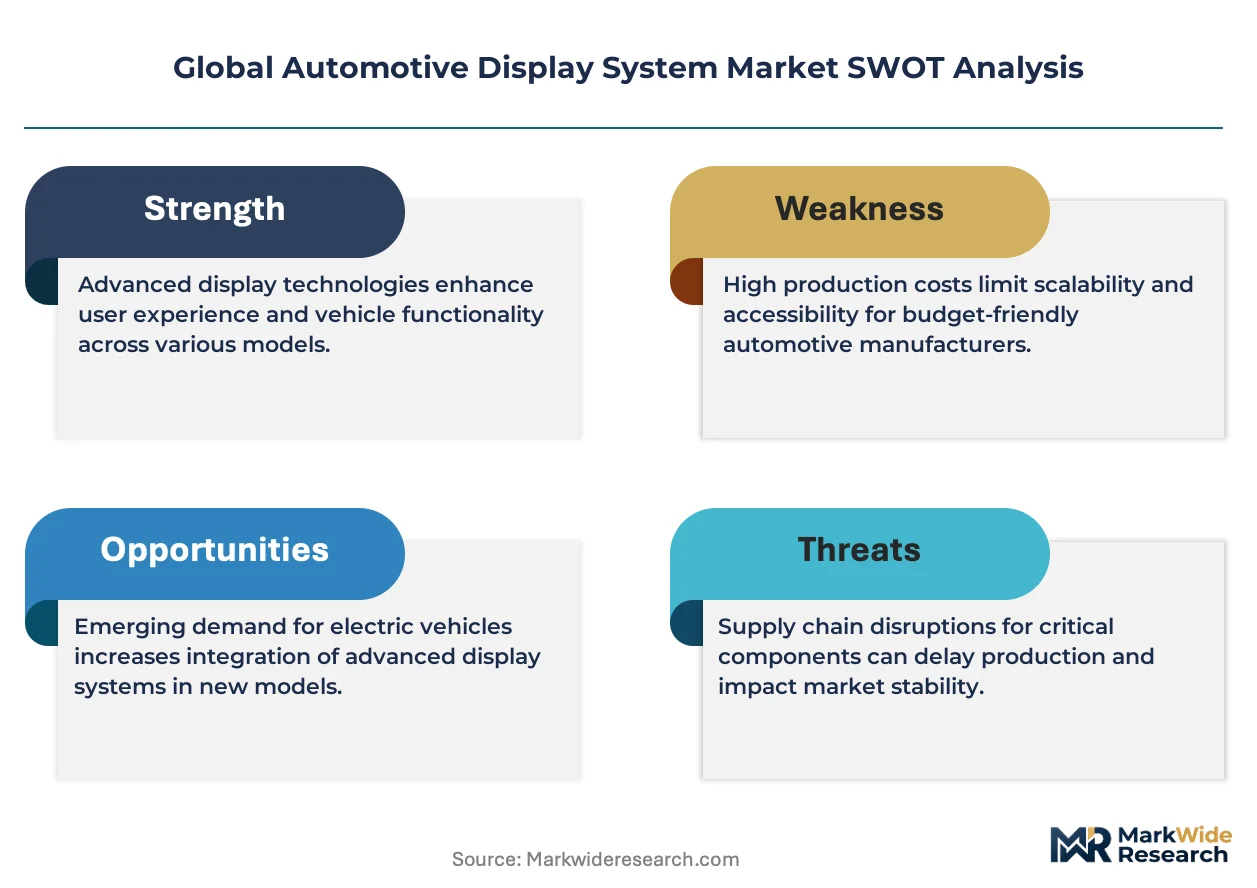
The automotive display system market is being fundamentally reshaped by the forced transition from LCD to OLED panel architectures, as automakers compete on cockpit differentiation and EU safety mandates tighten luminance and contrast requirements for driver monitoring systems.
Growth Catalysts
- EU Driver Monitoring Mandates:ECE R121 and emerging EU AI Act requirements for occupant sensing are compelling OEMs to upgrade to high-contrast, wide-gamut displays capable of reliable performance under variable lighting conditions.
- Curved Surface Integration:Interior design teams at luxury and mass-premium vehicle manufacturers are specifying free-form OLED panels that conform to dashboard topologies previously impossible with rigid LCD substrates.
- Electric Vehicle Cockpit Digitization:EV platforms are eliminating physical gauge clusters entirely, expanding screen real estate per vehicle and prioritizing touch-interface durability for always-on operation.
Market Restraints
- OLED Wafer Supply Concentration:Advanced automotive-grade OLED capacity concentrates among Korean and Chinese foundry operators, creating allocation risk for European and Japanese module integrators without captive supply.
- Thermal Management Material Costs:Displays operating at 800+ cd/m² in direct solar loading require indium tin oxide alternatives and specialized optical films, compressing margins at the module integration tier.
- FCC Certification Timeline:Electromagnetic emissions testing for connected display modules adds 4-6 months to US market entry, disadvantaging smaller suppliers against established tier-1 incumbents with pre-certified architectures.
Strategic Opportunities
- India Automotive Manufacturing:PLI scheme incentives for electric vehicle component localization are attracting display module assembly investments to serve domestic OEMs and export markets.
- Head-Up Display Windshield Integration:Augmented reality HUDs requiring pico-projector and waveguide convergence represent uncontracted white space as German and Japanese luxury brands specify larger field-of-view systems.
- Metallic Oxide Backplane Transition:IGZO and LTPO technologies enabling variable refresh and burn-in mitigation are creating differentiation vectors for suppliers capable of process integration.
Industry Challenges
- Automotive Functional Safety Certification:ISO 26262 ASIL-B and ASIL-C ratings for instrument cluster displays require specialized firmware validation teams scarce among consumer-electronics panel suppliers entering automotive.
- Legacy Vehicle Platform Integration:Module suppliers must maintain dual development tracks for CAN-based architectures in existing vehicle lines and Ethernet-AVB backbones in next-generation platforms, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Display System Market |
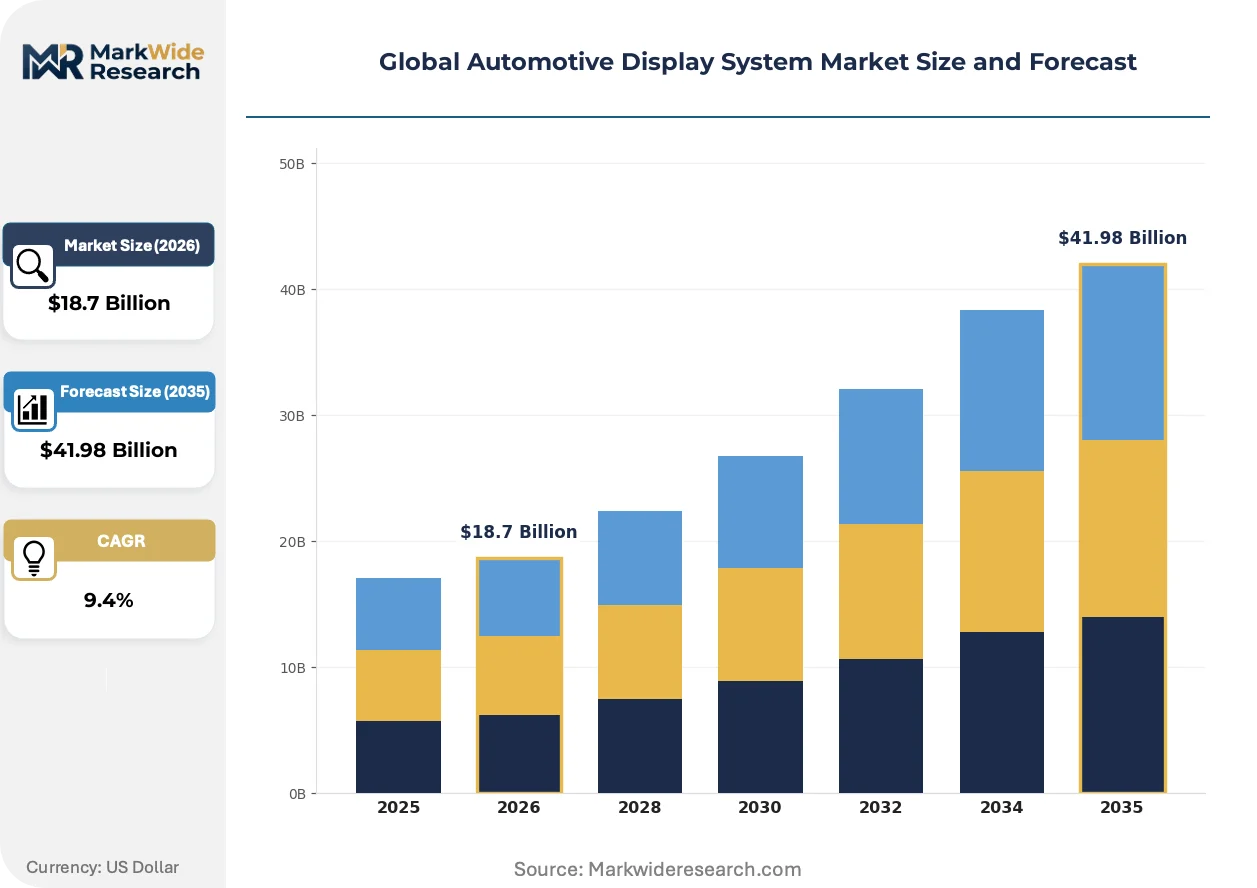
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infotainment Systems, Head-Up Displays, Instrument Clusters, Rear Seat Entertainment Technology: LCD, OLED, Projected Capacitive, Touchscreen End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Feature: Navigation, Connectivity, Entertainment, Safety |
| Companies Covered | Continental, Robert Bosch, LG Display, Alpine Electronics, Visteon Corporation, Samsung Display, Denso Corporation, Delphi Automotive, BOE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Display System Market Emerging Trajectories
OLED technology is actively bifurcating competitive positioning across the value chain, as captive wafer capacity becomes the decisive moat and module integrators without upstream access face margin compression.
LTPO backplane technology enables dynamic refresh rate modulation from 1Hz to 120Hz, preserving panel longevity in always-on instrument cluster applications. German luxury OEMs are specifying LTPO for 2026 platform launches, recognizing burn-in resistance as a warranty cost determinant. This capability is bifurcating supplier tiers between those with in-house oxide TFT deposition and those dependent on external foundry access.
Japan's METI energy efficiency benchmarks for automotive electronics are tightening backlighting power density requirements for instrument clusters exported to that market. Module suppliers are responding with localized dimming algorithms and mini-LED edge arrays that trade optical complexity for regulatory compliance. This regulatory pressure is accelerating design divergence between Japan-bound configurations and other regional variants.
Fleet operators and mobility-as-a-service providers are unbundling display hardware from software maintenance contracts, treating screens as consumable assets with 3-5 year replacement cycles rather than vehicle-life components. Tier-1 suppliers are responding with modular, field-replaceable unit designs and remote diagnostics capability. This consumption-pattern shift is most visible in North American commercial vehicle and ride-hail vehicle segments where uptime economics dominate procurement criteria.
Global Automotive Display System Market Segmentation
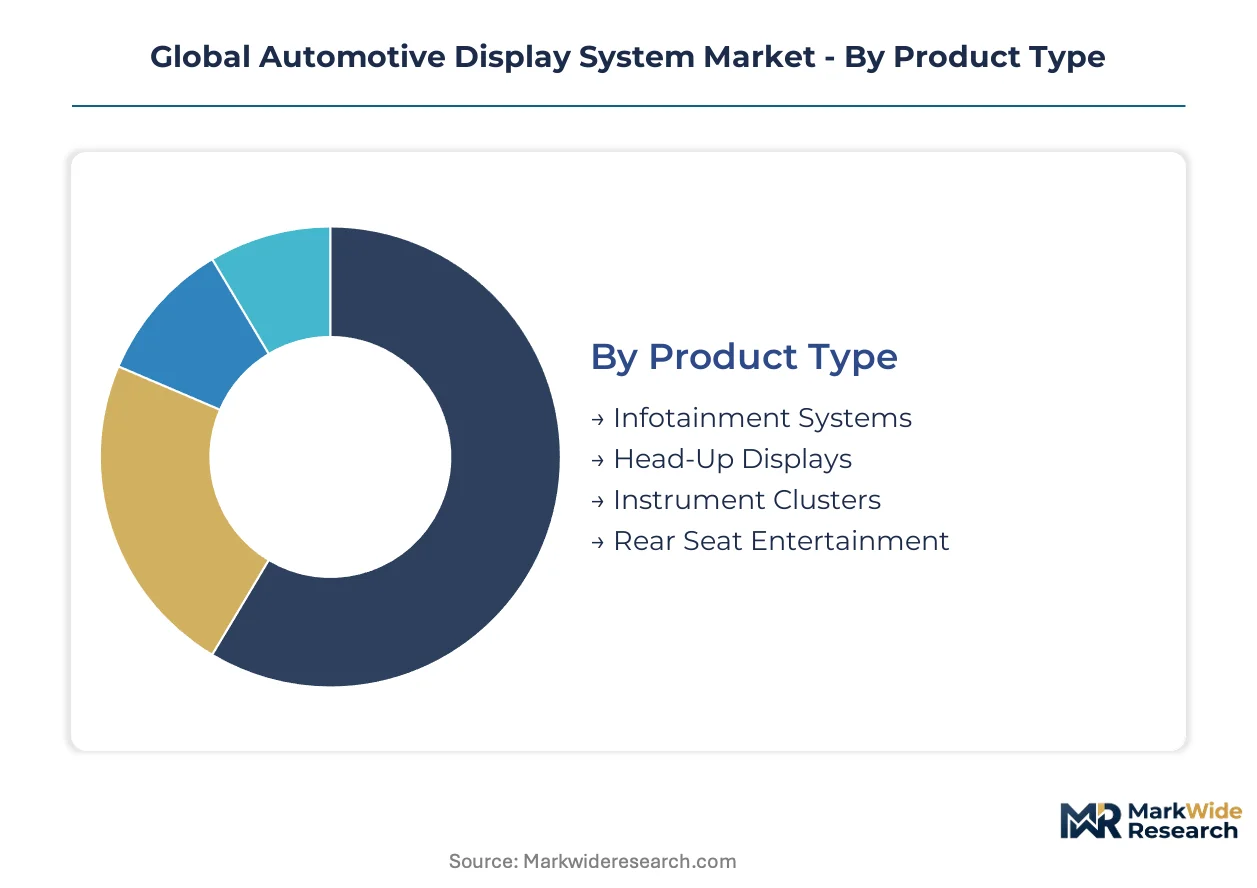
Automotive display procurement splits across four structural dimensions that determine supplier access and margin capture. Product type defines the physical form factor and thermal specification. Technology selection locks in foundry relationships and certification pathways. End-user channel determines contract structure and volume predictability. Feature prioritization shapes software integration requirements and update cadence.
Product Type:
Substitution pressure from free-form OLED surfaces is fragmenting legacy form factors as interior designers consolidate multiple functions into continuous dashboard screens.
- Infotainment Systems:Central touchscreen modules integrating media, climate, and vehicle settings through 10-17 inch diagonal formats. German and Korean OEMs concentrate procurement for curved configurations that eliminate physical buttons, driven by cockpit digitization mandates.
- Head-Up Displays:Windshield-projected information systems requiring pico-projector alignment and specialized optical films. Japanese luxury brands and German premium assemblers dominate demand for augmented reality variants with expanded field-of-view.
- Instrument Clusters:Driver-facing gauge replacements with 12.3-inch standardization across mass-market platforms.
- Rear Seat Entertainment:Ceiling-mounted or headrest-integrated screens for passenger entertainment during transit.
Infotainment Systems retain volume leadership; Head-Up Displays hold the steepest expansion curve.
Technology:
Cost-tier stratification separates premium vehicle specifications from high-volume procurement, with foundry access becoming the decisive competitive moat.
- OLED:Organic light-emitting diode panels delivering infinite contrast ratios and sub-millisecond response times for curved instrument clusters. Korean foundry operators anchor supply for European luxury OEMs, constrained by automotive-grade burn-in validation timelines.
- LCD:Liquid crystal display architectures with mini-LED backlighting for high-luminance instrument clusters. Chinese panel houses and Taiwanese integrators serve mass-market brands through cost-optimized supply chains.
- Projected Capacitive:Touch-sensing layers enabling gesture recognition and multi-point input.
- Touchscreen:Integrated display-plus-sensor modules for simplified procurement.
LCD retains volume leadership; OLED holds the steepest expansion curve.
End User:
Customer-type concentration determines contract duration and technical specification authority across the procurement hierarchy.
- OEMs:Vehicle brand owners specifying display performance requirements and software integration standards. German and Japanese OEMs maintain direct foundry relationships for OLED supply security.
- Tier-1 Suppliers:Module integrators consolidating panel procurement and mechanical integration for multiple OEM programs. Continental and similar suppliers leverage German vehicle assembler relationships.
- Aftermarket Providers:Independent distributors serving vehicle modification and repair channels.
- Vehicle Assemblers:Contract manufacturers building vehicles for OEM brand owners.
Tier-1 Suppliers retain volume leadership; OEMs hold the steepest expansion curve.
Feature:
Application-maturity divergence separates regulated safety functions from discretionary entertainment, with certification requirements fragmenting supplier tiers.
- Safety:Driver monitoring visualizations and ADAS overlays subject to ECE R121 legibility mandates and ISO 26262 functional safety ratings. EU regulatory tightening accelerates specification upgrades for speedometer and tell-tale displays.
- Navigation:Real-time mapping and route guidance with over-the-air update capability. Fleet operators and mobility-as-a-service providers concentrate procurement for commercial vehicle deployment.
- Connectivity:Smartphone integration and vehicle-to-infrastructure communication interfaces.
- Entertainment:Media streaming and gaming functions for passenger consumption.
Navigation retains volume leadership; Safety holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Korean supply corridors while module integrators in Japan and North America absorb margin compression from concentrated OLED wafer sourcing.
China
Domestic EV manufacturers are specifying curved OLED instrument clusters at unprecedented scale, absorbing the largest share of advanced panel procurement worldwide. MIIT's GB standards for vehicle electronics are tightening electromagnetic compatibility requirements for connected cockpit modules. Display foundry investments cluster in the Yangtze River Delta around Suzhou and Hefei, where BOE and local operators are expanding automotive-grade OLED capacity.
Germany
Luxury OEMs are mandating free-form OLED surfaces for 2026 platform launches, prioritizing burn-in resistance and dynamic refresh capabilities. KBA enforcement of ECE R121 legibility standards is accelerating specification upgrades for speedometer and tell-tale displays. Module integration expertise concentrates in Bavaria and Baden-Württemberg, where Continental and Robert Bosch maintain deep assembler relationships.
United States
Fleet operators and mobility-as-a-service providers are treating displays as consumable assets with shortened replacement cycles, favoring modular field-replaceable designs. FCC certification timelines for electromagnetic emissions testing add 4-6 months to market entry for connected modules. Engineering activity clusters in Michigan and California, where tier-1 suppliers are adapting architectures for CAN-based legacy platforms and Ethernet-AVB next-generation backbones.
South Korea
Captive OLED wafer capacity anchors premium supply contracts with European and Japanese luxury OEMs seeking supply security. MFDS and national industrial policy are channeling investment into automotive-grade burn-in validation and functional safety certification capabilities. Samsung Display and LG Display operations in Gyeonggi Province are constraining allocation for module integrators without long-term foundry agreements.
Japan
Domestic luxury brands are specifying augmented reality head-up displays with expanded field-of-view, driving pico-projector and waveguide convergence demand. METI energy efficiency benchmarks are tightening backlighting power density requirements for instrument cluster exports. Alpine Electronics and Denso Corporation engineering centers in Kansai and Chubu regions are developing localized dimming algorithms for regulatory compliance.
Global Automotive Display System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where captive wafer access determines premium positioning. Korean and Chinese foundry operators anchor the technology tier through in-house OLED production, while German and Japanese module integrators dominate mechanical integration and OEM relationship management. Two strategic archetypes predominate: vertically integrated display manufacturers with captive panel supply, and specialized module integrators leveraging assembler proximity. Competitive moves concentrate on foundry capacity expansion for automotive-grade OLED and strategic partnerships to secure allocation in constrained supply environments.
Among Korean display manufacturers, Samsung Display and LG Display occupy positions defined by captive wafer capacity and automotive burn-in validation capabilities. Continental exemplifies the module integrator archetype through its positioning within German vehicle assembler procurement frameworks. BOE represents the cost-optimized challenger, competing aggressively on LCD cost curves for high-volume instrument cluster supply to mass-market brands.
| Leading Market Players |
|---|
| Continental |
| Robert Bosch |
| LG Display |
| Alpine Electronics |
| Visteon Corporation |
| Samsung Display |
| Denso Corporation |
| Delphi Automotive |
| BOE |
| Others |
Supply Flow & Price Mechanics
Fourteen-week automotive-grade OLED wafer lead times compress module integrator margins while Korean foundry operators extract pricing premiums through allocation scarcity. This inventory-to-pricing dynamic concentrates margin capture upstream, forcing downstream suppliers to absorb thermal management material cost inflation or risk contract loss to vertically integrated competitors.
Pricing Analysis
Configured-to-order pricing for curved OLED instrument clusters commands substantial premiums over standard LCD configurations due to automotive burn-in validation timelines and foundry allocation scarcity. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 ASIL-C certified safety displays from infotainment modules and aftermarket replacement units. Cost compression in high-volume LCD instrument clusters is intensifying because Chinese panel houses are expanding 12.3-inch standard-format capacity. Fleet operators and mobility-as-a-service providers exhibit highest price sensitivity, accepting reduced feature sets for field-replaceable unit economics, while German luxury OEMs prioritize burn-in resistance and dynamic refresh capabilities over unit cost.
Supply Chain Analysis
Strategic stockpiling of indium tin oxide alternatives and specialized optical films dominates inventory strategy as module integrators buffer against Korean and Chinese foundry allocation volatility. Geographic supply concentration centers on South Korea for advanced automotive OLED wafers, China for LCD panel and mini-LED backlighting components, and Germany for module integration and OEM relationship management. Raw material dependencies draw from rare earth elements for phosphor deposition, polarizer films from Japanese specialty chemical suppliers, and driver ICs from Taiwanese semiconductor foundries. Single-source vulnerability in automotive-grade OLED wafer supply creates structural risk for European and Japanese module integrators without captive foundry agreements. Distribution runs through tier-1 supplier consolidation networks anchored by Continental and Robert Bosch procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive display procurement is recovering from cyclical trough conditions as EV platform launches accelerate cockpit digitization and EU safety mandates force specification upgrades. This cyclical recovery draws from pent-up OEM platform investment deferred during semiconductor shortage periods.
For Market Incumbents: Shield market position by securing long-term OLED wafer allocation agreements with Korean foundry operators before 2026 platform launch windows intensify competition. Prioritize ISO 26262 ASIL-C certification investment to defend against consumer-electronics panel suppliers entering automotive safety applications. Expand captive thermal management material processing to offset indium tin oxide alternative cost inflation compressing module-tier margins.
For New Entrants and Emerging Players: ISO 26262 functional safety certification fast-track programs offer entry pathway for module integrators targeting instrument cluster safety displays where incumbent certification scarcity creates procurement bottlenecks. White-space targets include India PLI scheme incentivized assembly operations for domestic EV OEMs and augmented reality head-up display pico-projector convergence for German and Japanese luxury brands. Fleet operator consumable-screen procurement models represent most penetrable segment due to shortened replacement cycle economics favoring modular designs.
For Investors and Strategic Acquirers: Long-term, this sits as a foundry-capacity-constrained cyclical play because automotive-grade OLED burn-in validation timelines and EU regulatory tightening create sustained supply inelasticity. Acquisition target archetype: module integrators with established tier-1 supplier relationships and in-process oxide TFT deposition capabilities enabling LTPO backplane transition. Signal to watch is Korean foundry allocation announcements for 2026 platform launches as inflection indicator for pricing power migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade OLED Capacity Expansion | Korean foundry operators anchor premium supply contracts through burn-in validation capabilities. |
| LTPO Backplane Process Integration | Variable refresh rate modulation preserves panel longevity for always-on instrument cluster applications. |
| India Manufacturing Localization | PLI scheme incentives attract display module assembly investments for domestic EV OEM procurement. |
| Augmented Reality HUD Development | Pico-projector and waveguide convergence addresses uncontracted white space in luxury brand specifications. |
| ISO 26262 ASIL-C Certification Investment | Functional safety ratings differentiate suppliers as consumer-electronics entrants target automotive markets. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with automotive industry stakeholders and systematic secondary validation across proprietary and public sources. Primary fieldwork engaged tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and display foundry commercial operations leads. Secondary sources included vehicle production databases, IHS Markit registration data, FCC certification filings for connected display modules, and ECE R121 regulatory documentation. Bottom-up volume modeling triangulated against top-down OEM procurement budget analysis to converge market size estimates.
Across the projection horizon, analytical framework segmented volume and value outputs by product type, technology selection, end-user channel, and feature prioritization dimensions. Vehicle class stratification, propulsion architecture differentiation, and content-per-vehicle trajectories informed segment-level growth rate derivation. CAGRs were computed from production-volume-weighted average selling price evolution, incorporating foundry capacity expansion schedules and regulatory mandate implementation timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EV platform launch cadence and stable OLED wafer allocation agreements; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding EU regulatory enforcement timelines and Korean foundry capacity ramp schedules. Revision becomes warranted when thermal management material cost inflation or foundry allocation disruption crosses thresholds that alter module integrator margin sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market