
 Automotive Gear Position Sensor Market | 2026-2036
Automotive Gear Position Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Gear Position Sensor Market Analysis
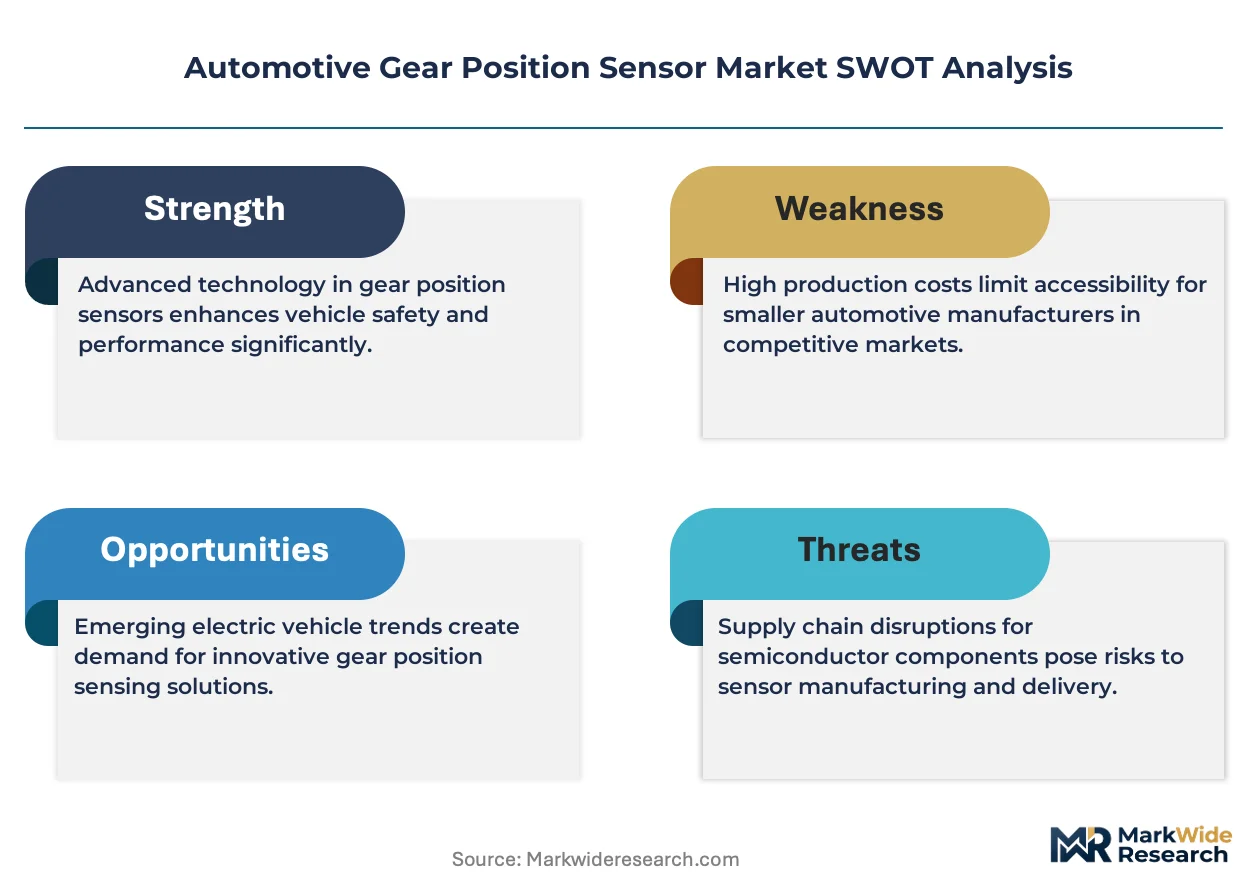
Electromagnetic engineering talent is collapsing across tier-2 supply bases, forcing sensor makers to internalize coil-winding and calibration competencies. Robert Bosch GmbH leverages captive magnetics manufacturing in Germany to insulate its Hall effect sensor lines from contractor scarcity. TE Connectivity anchors North American OEM relationships through vertically integrated potentiometric production in Mexico. Continental AG competes by sustaining dual-source Hall and magnetic sensor architectures across transmission platforms.
An automotive gear position sensor detects and encodes transmission shaft angular position into electrical signals for powertrain control modules, typically resolving 0.1-degree increments across temperature extremes from minus forty to one hundred fifty degrees Celsius. Its primary purpose is enabling clutchless shifting, start-stop coordination, and failsafe neutral detection in manual, automatic, and electrified transmissions. Hall effect sensors dominate OEM specification sheets for their contactless durability and immunity to transmission fluid contamination, while magnetic sensors capture fastest-growing share in wireless-enabled digital architectures that eliminate harness connectors. Potentiometric designs retain aftermarket relevance where cost sensitivity overrides longevity requirements.
NHTSA mandates automatic transmission state reporting for rollover mitigation, while EPA tailpipe rules require precise gear-state feedback to optimize engine mapping during drive cycles. ISO 26262 functional safety grades are gating market access for suppliers serving integrated transmission control units. Stakeholders must weigh analog versus digital technology bets against pending cybersecurity overlays for wireless sensor protocols.
Market Dynamics
Powertrain electrification is fragmenting sensor architectures as OEMs simultaneously serve internal combustion, hybrid, and full-electric platforms with incompatible signal requirements and thermal envelopes.
Growth Catalysts
- EPA tailpipe regulations:Precision gear-state feedback enables real-time engine mapping optimization during standardized drive cycles, mandating higher-resolution angular detection across transmission variants.
- China:Domestic OEM procurement for integrated transmission control units concentrates demand for ISO 26262-compliant sensor modules serving dual-clutch and dedicated hybrid transmissions.
- Hall effect sensing:Contactless durability and immunity to transmission fluid contamination drive specification dominance in automatic and electrified powertrain programs.
Market Restraints
- Electromagnetic engineering scarcity:Collapsing tier-2 coil-winding and calibration talent pools force sensor makers to internalize magnetics competencies or face yield degradation.
- Rare earth magnet cost volatility:Neodymium and samarium price swings compress margin stability for magnetic sensor architectures dependent on high-coercivity permanent magnets.
- Wireless protocol substitution:Elimination of harness connectors through digital radio architectures threatens traditional Hall effect sensor form factors and connector revenue streams.
Strategic Opportunities
- Wireless-enabled digital architectures:Magnetic sensors capturing fastest-growing share in connectorless transmission designs eliminate harness complexity and assembly labor.
- India:PLI scheme incentives for automotive component manufacturing create localized production pathways for export-oriented sensor suppliers serving ASEAN markets.
- ISO 26262 functional safety grades:Certification gating for integrated transmission control unit suppliers creates premium tier access for qualified module vendors.
Industry Challenges
- Calibration engineering talent:Electromagnetic simulation and temperature compensation expertise shortages constrain production ramp rates for precision angular resolution sensors.
- Dual-platform validation:Simultaneous ICE and EV powertrain certification timelines compress development cycles and multiply testing burden for multi-architecture suppliers.
- Cybersecurity overlay integration:Pending wireless sensor protocol hardening requirements demand cryptographic competency acquisitions absent from traditional automotive sensor houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Gear Position Sensor Market |
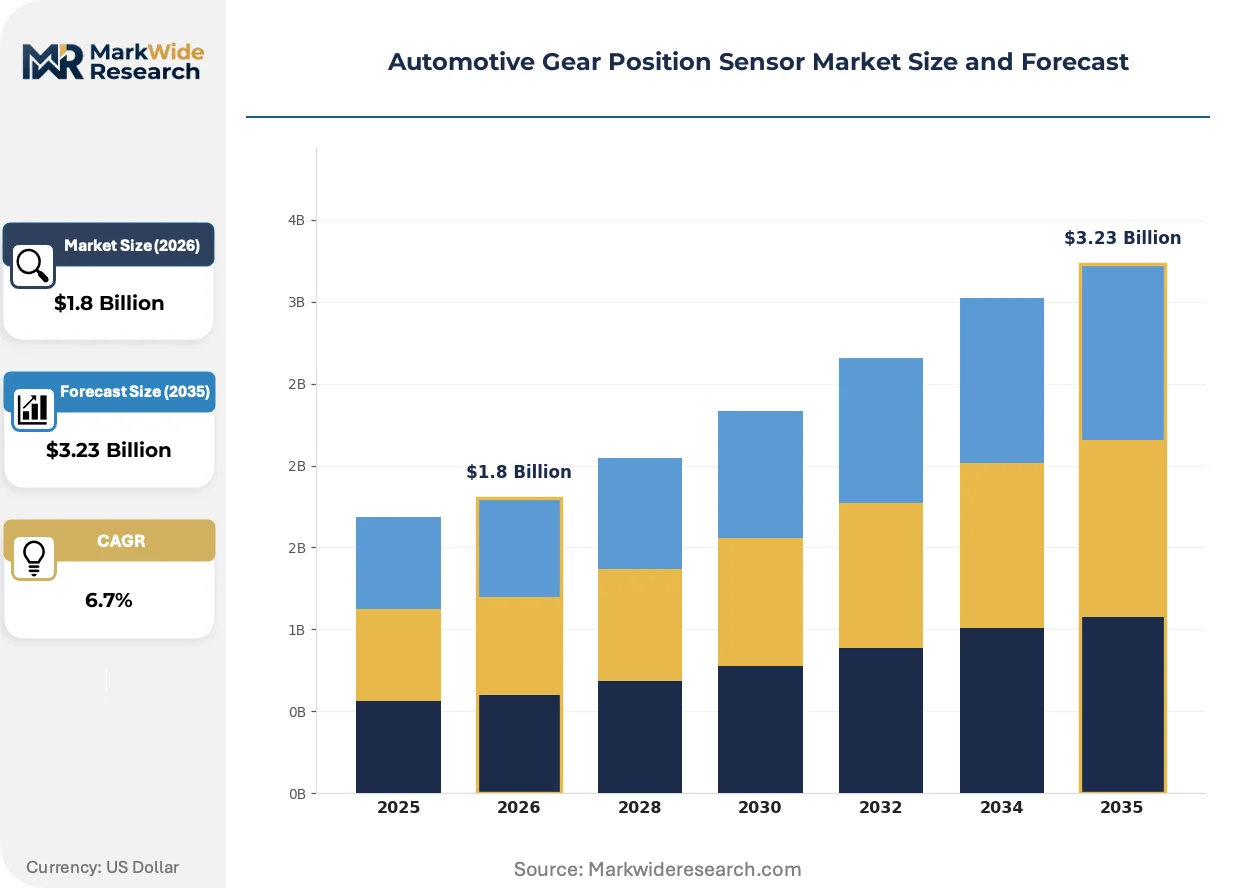
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Sensors, Potentiometric Sensors, Hall Effect Sensors, Optical Sensors End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Analog, Digital, Wireless, Hybrid Application: Transmission Systems, Engine Control Units, Safety Systems, Drive Control |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, Infineon Technologies AG, TE Connectivity, Honeywell International Inc., STMicroelectronics, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Gear Position Sensor Market Emerging Trajectories
Signal processing architectures are diverging between analog legacy compatibility and digital-native wireless implementations, forcing suppliers to maintain parallel development tracks without scale economies.
Hall effect sensing is bifurcating between conventional voltage-output devices for ICE transmissions and SENT-protocol digital variants for electrified powertrains requiring cybersecurity-hardened bus communication. Tier-1 transmission suppliers in Germany and Japan are dual-sourcing both variants to de-risk platform transitions. This technological schism is compressing supplier R&D efficiency as analog and digital competencies demand distinct engineering cultures.
NHTSA rollover mitigation mandates require automatic transmission state reporting with failsafe neutral detection, compelling sensor redundancy and diagnostic coverage upgrades. The regulation forces Hall effect and magnetic sensor architectures toward dual-channel designs with cross-verification logic. Integrated transmission control unit suppliers in the United States face compliance deadlines that accelerate validation spending ahead of production commitments.
Aftermarket procurement is fragmenting as independent repair networks bypass traditional distribution tiers to source potentiometric sensors directly from contract manufacturers. Cost-sensitive vehicle aging populations in Eastern Europe and Latin America sustain demand for lower-longevity designs despite OEM digital migration. Channel disintermediation compresses branded supplier margins while expanding private-label sensor availability through e-commerce platforms.
Automotive Gear Position Sensor Market Segmentation
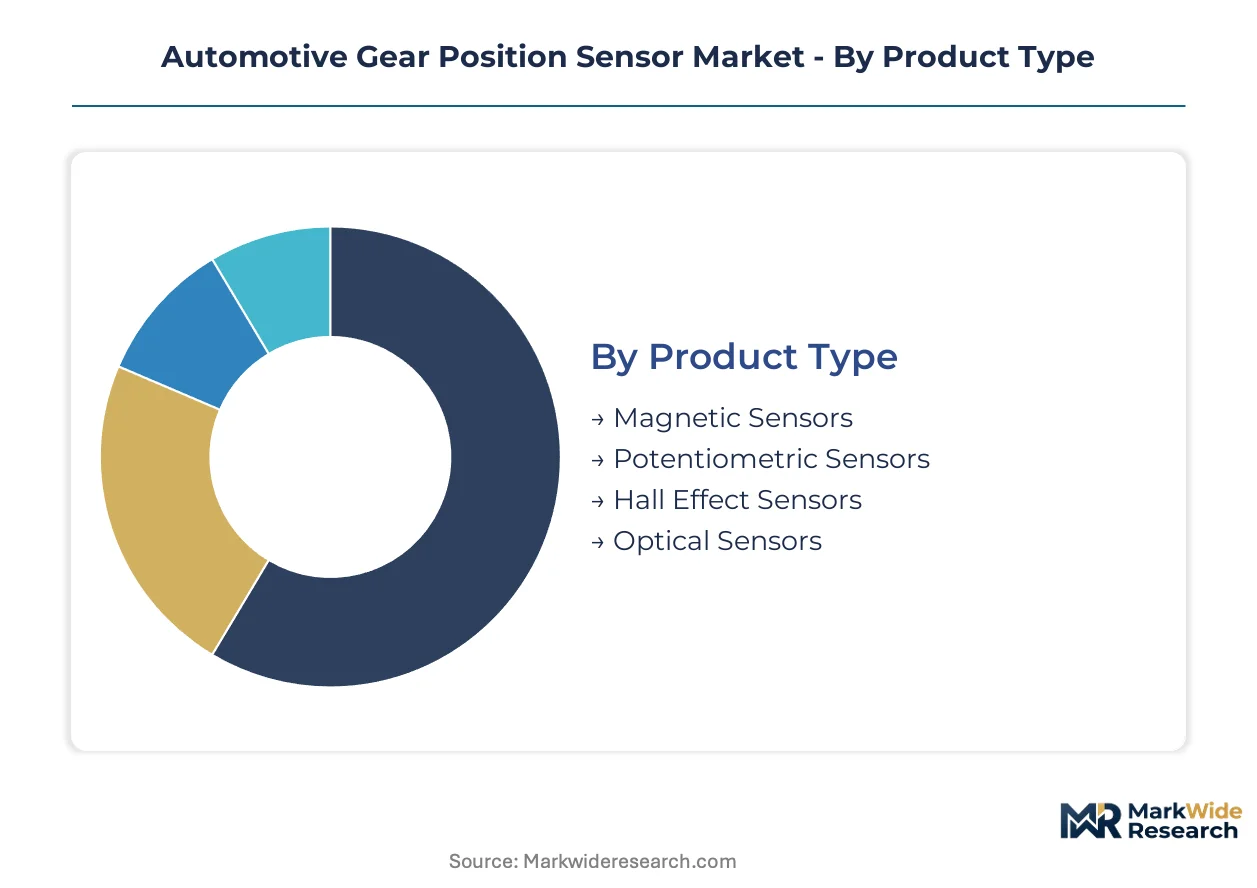
Sensor specification divergence across powertrain electrification tiers forces suppliers to maintain parallel product architectures. Segmentation clarity determines which technology bets align with OEM platform roadmaps versus aftermarket replacement cycles.
Product Type:
Hall effect and magnetic variants dominate export-led procurement from Germany and Japan, while potentiometric sensors serve cost-sensitive domestic aftermarket channels in India and Brazil.
- Hall Effect Sensors:Contactless magnetic field detection delivers immunity to transmission fluid contamination across temperature extremes from minus forty to one hundred fifty degrees Celsius. Procurement concentrates among German and Japanese OEMs for dual-clutch and dedicated hybrid transmissions requiring ISO 26262 functional safety grades.
- Magnetic Sensors:Permanent magnet architectures enable wireless-enabled digital implementations that eliminate harness connectors. Demand is accelerating fastest in connectorless transmission designs from tier-1 suppliers serving electrified vehicle platforms.
- Potentiometric Sensors:Resistive contact-based designs retain relevance in Eastern European and Latin American aftermarket channels where cost sensitivity overrides longevity requirements.
- Optical Sensors:LED-photodiode configurations resolve angular position through coded disc interruption, finding niche application in precision robotics-adjacent transmission testing equipment.
Hall effect sensors hold the largest share; momentum sits with magnetic sensors.
End User:
Cost tier stratification separates safety-critical OEM specifications from price-driven aftermarket procurement.
- OEMs:Integrated transmission control unit procurement demands dual-channel redundant architectures with diagnostic coverage for NHTSA rollover mitigation compliance. Ford and Toyota specify Hall effect variants with SENT-protocol digital outputs for cybersecurity-hardened bus communication.
- Tier-1 Suppliers:ZF Friedrichshafen and Aisin source magnetic sensor modules for wireless-enabled architectures, internalizing calibration competencies to offset collapsing tier-2 electromagnetic engineering talent pools.
- Vehicle Assemblers:Contract manufacturers in Mexico and Thailand integrate potentiometric sensors for regional vehicle platforms with lower functional safety requirements.
- Aftermarket Providers:Independent repair networks in Poland and Brazil bypass distribution tiers to source directly from contract manufacturers, compressing branded supplier margins.
OEMs command premium pricing through safety certification requirements; aftermarket providers expand volume through channel disintermediation.
Technology:
Application maturity separates legacy analog compatibility from digital-native wireless implementations.
- Digital:SENT-protocol and SPI bus interfaces enable cybersecurity-hardened communication for electrified powertrains. Demand concentrates among integrated transmission control unit suppliers facing EPA engine mapping precision mandates.
- Wireless:Radio-frequency architectures eliminate harness connectors and assembly labor, capturing steepest expansion trajectory in magnetic sensor implementations for next-generation transmission designs.
- Analog:Voltage-output devices retain specification for ICE transmission programs requiring backward compatibility with legacy powertrain control modules.
- Hybrid:Mixed-signal designs bridge analog sensor front-ends with digital bus outputs, serving dual-platform suppliers validating simultaneous ICE and EV certification timelines.
Digital technology holds the largest share; wireless architectures gain share fastest.
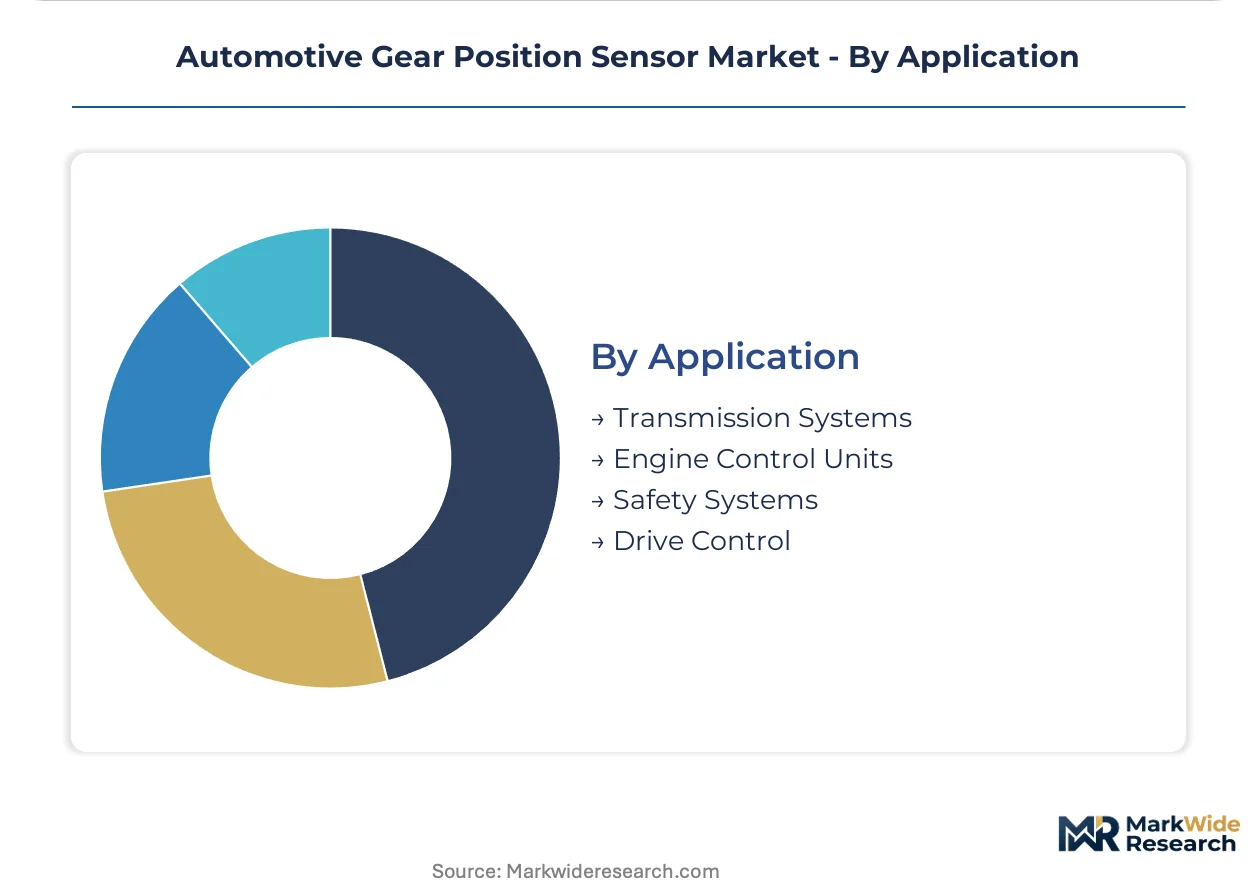
Application:
Volume concentration follows powertrain control integration depth across transmission and engine management systems.
- Transmission Systems:Angular position detection enables clutchless shifting, start-stop coordination, and failsafe neutral detection across manual, automatic, and electrified variants. Procurement from China concentrates for dual-clutch and dedicated hybrid transmission platforms.
- Engine Control Units:Gear-state feedback optimizes engine mapping during standardized EPA drive cycles, requiring higher-resolution angular detection across transmission variants.
- Safety Systems:NHTSA rollover mitigation mandates force automatic transmission state reporting with redundant sensor architectures and cross-verification logic.
- Drive Control:Torque vectoring and all-wheel-drive clutch engagement rely on real-time shaft position data in performance vehicle platforms.
Transmission systems hold the largest share; safety systems drive specification upgrades fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China specify Hall effect sensors for precision transmission control, while India and Brazil sustain potentiometric demand in cost-driven vehicle segments. This consumption-mix differential separates safety-critical OEM procurement from aftermarket replacement cycles across geographies.
United States
NHTSA rollover mitigation mandates drive dual-channel redundant sensor architectures with failsafe neutral detection. EPA tailpipe regulations require precise gear-state feedback for engine mapping optimization during standardized drive cycles. Detroit-area transmission suppliers integrate Hall effect modules with SENT-protocol digital outputs for cybersecurity-hardened bus communication.
Germany
Dual-clutch and dedicated hybrid transmission platforms concentrate procurement for ISO 26262-compliant sensor modules. KBA type-approval processes enforce functional safety grades for integrated transmission control units. Stuttgart and Munich industrial corridors host captive magnetics manufacturing operations that insulate Hall effect sensor lines from contractor scarcity.
China
Domestic OEM procurement for integrated transmission control units accelerates demand for high-resolution angular detection in electrified powertrains. MIIT new energy vehicle mandates prioritize transmission feedback systems with temperature stability across extreme operating envelopes. Shanghai and Beijing clusters concentrate module assembly for dual-clutch transmissions serving both domestic and export markets.
Japan
METI carbon neutrality roadmaps push electrified powertrain adoption requiring incompatible signal architectures for hybrid and full-electric platforms. JIS standards govern sensor durability specifications for automatic transmission state reporting. Nagoya-area tier-1 suppliers dual-source Hall and magnetic sensor architectures to de-risk platform transitions.
India
PLI scheme incentives for automotive component manufacturing create localized production pathways for export-oriented sensor suppliers. Cost-sensitive vehicle aging populations sustain aftermarket demand for potentiometric designs where longevity requirements yield to price pressure. Tamil Nadu and Maharashtra contract manufacturers supply independent repair networks across ASEAN markets through channel disintermediation.
Automotive Gear Position Sensor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Automotive Gear Position Sensor Market. Tier-1 transmission suppliers internalize calibration competencies to offset collapsing electromagnetic engineering talent pools. Three archetypes dominate: diversified automotive electronics conglomerates with captive magnetics operations, connectivity-focused component specialists with vertically integrated potentiometric production, and semiconductor houses supplying sensing elements to module integrators. Competitive moves concentrate on backward integration into coil-winding operations and strategic partnerships for wireless protocol development.
Among diversified automotive electronics conglomerates, Robert Bosch GmbH and Continental AG exemplify integrated market positions. Bosch leverages German-based captive manufacturing to insulate Hall effect sensor lines from contractor scarcity. Continental sustains dual-source architectures across transmission platforms. TE Connectivity anchors North American OEM relationships through in-house potentiometric production in Mexico. These three occupy positions spanning the premium module tier where functional safety certification gates market access.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Infineon Technologies AG |
| TE Connectivity |
| Honeywell International Inc. |
| STMicroelectronics |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Sixty-day coil-winding lead times at tier-2 magnetics suppliers concentrate pricing power among Hall effect sensor manufacturers with captive German operations, while spot-market neodymium volatility feeds cost compression into magnetic sensor architectures lacking long-term offtake coverage.
Pricing Analysis
Long-term offtake agreements dominate procurement between German OEMs and integrated sensor houses, insulating Hall effect module pricing from rare earth magnet spot volatility. Price differentiation separates ISO 26262-certified dual-channel designs for NHTSA rollover compliance from single-channel potentiometric variants serving cost-sensitive aftermarket channels in Brazil and Poland. Pricing pressure intensifies in magnetic sensor tiers exposed to wireless protocol substitution, where connector elimination threatens traditional harness-integrated form factors. Tier-1 transmission suppliers exhibit lowest price sensitivity due to functional safety gating, while independent repair networks sourcing through e-commerce platforms drive hardest bargain.
Supply Chain Analysis
Ninety-day inventory cycles for neodymium magnet feedstock expose magnetic sensor producers to price swings that Hall effect houses with German captive winding avoid. Manufacturing concentrates in Germany, China, and Mexico, with Stuttgart and Munich corridors hosting Bosch and Continental magnetics operations, Shanghai clusters assembling dual-clutch modules, and Mexican facilities serving North American OEM potentiometric demand. Supply chains draw from rare earth processors in China, copper coil suppliers in Germany, and semiconductor foundries in Taiwan. Single-source vulnerability sits with Malaysian connector manufacturers serving legacy Hall effect harness architectures. Distribution runs through tier-1 transmission integrators to OEM assembly plants, bypassing traditional component distribution for wireless-enabled digital variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragments sensor architectures faster than supplier R&D cycles can consolidate, with NHTSA rollover mandates and EPA engine mapping rules forcing simultaneous compliance across incompatible ICE and EV signal requirements.
For Market Incumbents: Secure electromagnetic engineering talent through acquisition of distressed tier-2 coil-winding operations before calibration expertise collapses entirely. Anchor pricing power in ISO 26262 certification moats that gate integrated transmission control unit procurement, while accelerating SENT-protocol digital variants to outpace wireless substitution threats from magnetic sensor entrants.
For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors to capture ASEAN export pathways for cost-optimized potentiometric modules serving aging vehicle populations. Target aftermarket channel disintermediation through direct e-commerce supply to Polish and Brazilian independent repair networks, where branded supplier margins have already compressed. Lead with wireless-enabled magnetic architectures for tier-1 electrified platform procurement where incumbent Hall effect houses lag connectorless design cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electromagnetic engineering scarcity and functional safety certification gating will collapse the viable supplier set to integrated conglomerates with captive magnetics and qualified module operations. Acquisition targets center on tier-2 coil-winding specialists with temperature compensation IP and calibration tooling. Watch NHTSA cybersecurity rulemaking for wireless sensor protocols as the inflection signal that separates qualified digital-native suppliers from analog legacy houses.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Magnetics Integration | Bosch's German coil-winding insulates Hall effect yields from contractor scarcity. |
| ISO 26262 Certification Investment | Functional safety grades gate premium access to integrated transmission control units. |
| Wireless Protocol Development | Magnetic sensor architectures eliminate harness connectors and assembly labor. |
| India PLI Manufacturing Footprint | Localized production creates ASEAN export pathways for cost-optimized modules. |
| SENT-Protocol Digital Migration | Cybersecurity-hardened bus outputs meet EPA engine mapping precision mandates. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and NHTSA regulatory filings preceded structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and electromagnetic engineering specialists. Primary fieldwork combined with secondary validation from customs records and SEC component supplier filings. Bottom-up sensor unit demand modeling triangulated against top-down powertrain production forecasts across the analysis window.
Variance decomposition separated volume drivers by propulsion architecture, vehicle class, and regional production cluster throughout the forecast period. Segmentation modeling captured product type splits, technology migration patterns, and end-user tier stratification. CAGRs derived from unit shipment trajectories weighted by content-per-vehicle assumptions and platform electrification roadmaps. Forecast inputs incorporated NHTSA compliance timelines, EPA drive cycle evolution, and MIIT new energy vehicle mandates without year-specific anchoring.
Material uncertainties — rare earth magnet price volatility, tier-2 engineering talent collapse rates, and pending wireless cybersecurity overlays — sit outside the modeled envelope. Forecasts reflect documented assumptions about powertrain electrification pace and regulatory enforcement consistency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Grade Inductors Market