
 Automotive Cell Contact System Carrier Market | 2026-2036
Automotive Cell Contact System Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cell Contact System Carrier Market Insights
Software-defined battery management features are repositioning the contact system carrier from a passive hardware commodity to a subscription-enabling platform layer. Infineon Technologies leverages its semiconductor-to-connector integration to dominate intelligent carrier architectures. Robert Bosch anchors European supply through its powertrain module specialization. TE Connectivity competes on manufacturing scale across stamping and overmolding process lines.
An automotive cell contact system carrier is a precision-engineered interconnect substrate, typically fabricated from nickel-plated copper alloys or engineered thermoplastics via stamping or injection molding, that mechanically supports and electrically bridges individual battery cells to busbar assemblies. Its primary purpose is to maintain stable current paths across thermal cycling and vibration loads while enabling automated assembly in high-volume battery pack production. Connector carriers and spring clamp carriers currently occupy the largest volume positions, though PCB contact carriers are gaining fastest as battery management systems integrate sensing directly at the cell level. Overmolding technology leads on margin pools due to seal integrity requirements, while laser welding displaces ultrasonic methods in premium electric vehicle platforms demanding finer joint control.
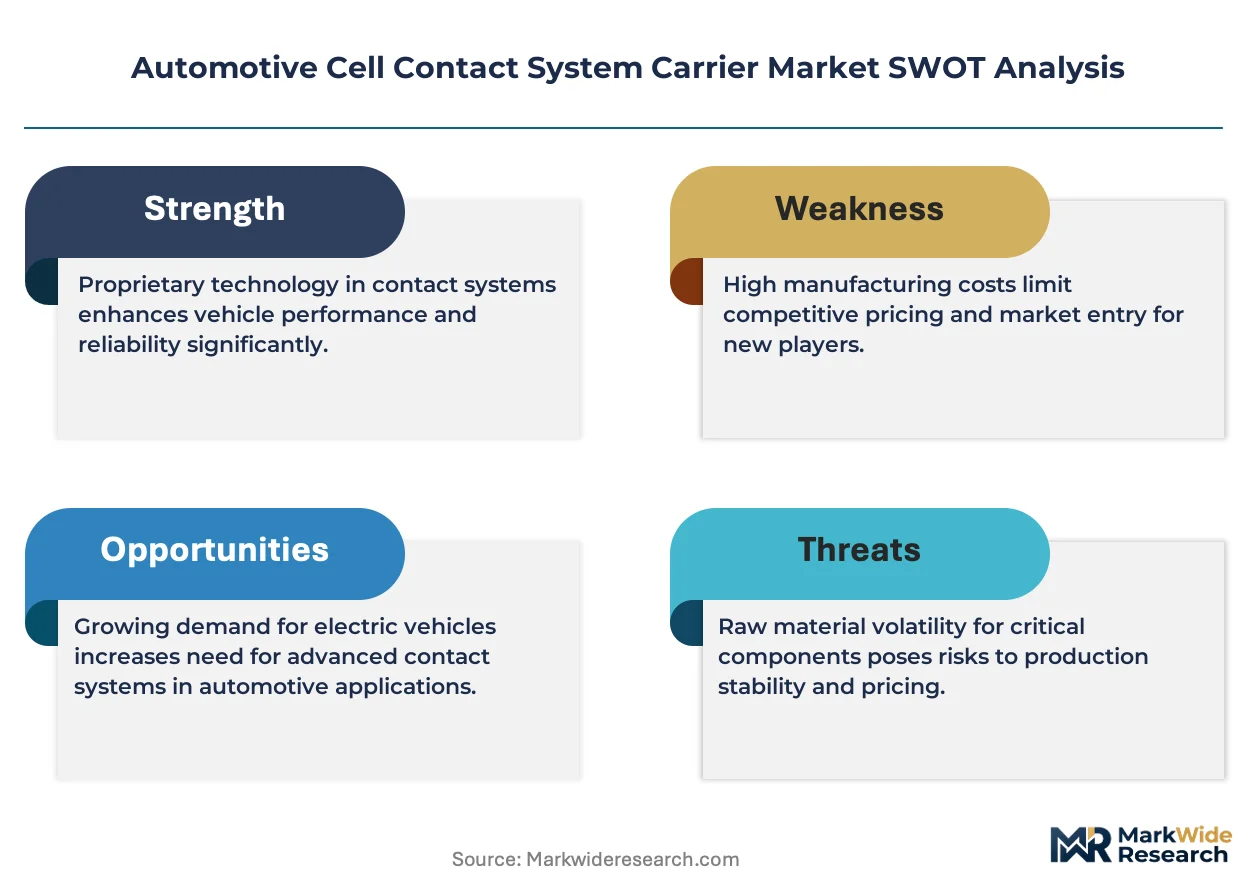
The US NHTSA and EPA shape demand through crashworthiness and thermal runaway containment standards that mandate redundant contact integrity. Europe's ECHA REACH restrictions and Battery Regulation drive material substitution toward halogen-free thermoplastics and recyclable copper alloys. China's GB standards and MIIT NEV technical rules enforce domestic supplier qualification thresholds. Stakeholders must decide whether to absorb certification costs across multiple regulatory regimes or concentrate compliance investment in the geography offering the steepest volume ramp.
Market Dynamics
800V battery architectures are compressing carrier design cycles as OEMs demand integrated current sensing and thermal management within a single stamped substrate. This voltage transition forces simultaneous redesign of nickel-plated copper geometries and polymer overmolding profiles.
Growth Catalysts
- Cell-to-Pack Adoption:Battery pack designs eliminating module housings require precision contact carriers that maintain alignment tolerances across 200+ cells. German automotive engineering clusters drive specification tightening.
- MIIT NEV Technical Rules:China's domestic supplier qualification thresholds accelerate local certification investments by foreign manufacturers seeking access to the world's largest electric vehicle production base.
- Laser Welding Process Control:Premium electric vehicle platforms demand finer joint consistency than ultrasonic methods permit, creating specification premiums for carriers with integrated weld monitoring features.
Market Restraints
- Nickel Price Volatility:Electroplating-grade nickel sulfate concentrates supply risk in Indonesian and Russian mining operations, compressing margin predictability for nickel-plated copper alloy fabricators.
- ECHA REACH Substitution Timelines:Halogen-free thermoplastic mandates force reformulation of established PBT and PA66 compounds, extending qualification cycles by 12-18 months for European-bound production.
- Stamping Tool Capital Intensity:Progressive die sets for high-current carrier geometries require hardened steel investments exceeding typical connector manufacturing equipment by 3-4x, concentrating supply among tool-and-die specialists.
Strategic Opportunities
- India PLI Scheme for ACC:Advanced Cell Chemistry production incentives create first-mover positioning for carriers qualified to BIS standards before domestic battery gigafactory ramp accelerates.
- PCB Contact Carrier Convergence:Integration of battery management system sensing directly at cell terminals enables subscription-enabled diagnostics, repositioning hardware as recurring-revenue platforms.
- Second-Life Battery Repurposing:Contact carriers designed for disassembly and reconditioning capture value from end-of-life electric vehicle packs entering stationary storage applications.
Industry Challenges
- Multi-Regime Certification Burden:Simultaneous NHTSA crashworthiness, ECHA material restrictions, and GB standard compliance forces redundant testing protocols that extend product launch timelines.
- Thermal Runaway Simulation Expertise:Finite element modeling of contact integrity during cell venting events requires specialized fire-safety engineering talent concentrated in automotive battery development centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cell Contact System Carrier Market |
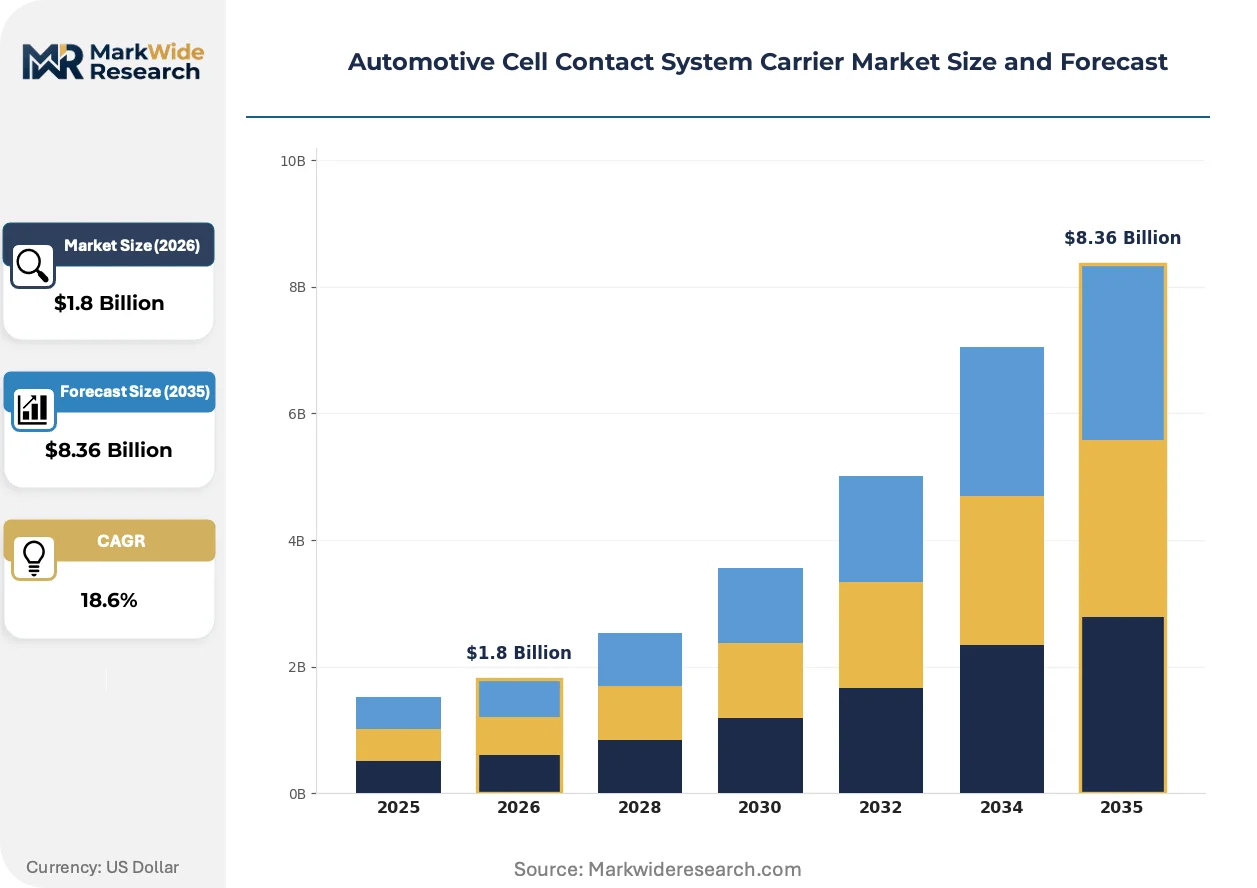
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connector Carrier, Contact Holder, Spring Clamp Carrier, PCB Contact Carrier Technology: Stamping, Injection Molding, Overmolding, Ultrasonic Welding, Laser Welding Application: Electric Vehicles, Hybrid Electric Vehicles, Powertrain Modules, Battery Management Systems End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Infineon Technologies, Robert Bosch, Continental AG, Amphenol, TE Connectivity, Ficosa Internacional, Sensata Technologies, Ennovi, AVL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cell Contact System Carrier Market Trends and Innovations
Contact system carriers are transitioning from stamped metal commodities to intelligent platforms embedding current sensing, thermal monitoring, and firmware-upgradable connectivity. This functional expansion redefines supplier value capture and competitive differentiation.
Overmolded seal architectures with integrated temperature sensors are overtaking basic stamped carriers in premium electric vehicle segments. Battery pack assemblers specify these carriers for 800V platforms where seal integrity failures cascade into warranty exposure. The technology is overtaking conventional designs by compressing the supplier base to firms with simultaneous precision stamping and injection molding capabilities.
Europe's Battery Regulation mandates digital battery passports tracking material provenance and carbon intensity across the value chain. Contact carriers must now incorporate scannable identifiers linking cell-level hardware to upstream mining and smelting records. German automotive OEMs are most affected, pressing suppliers to deploy laser-etched QR codes and encrypted NFC tags before 2027 enforcement deadlines.
Electric vehicle OEMs now specify carriers through long-term framework contracts bundling hardware, firmware updates, and predictive maintenance algorithms. Traditional component distributors lose position to direct OEM-supplier partnerships with dedicated engineering support. This pattern is most visible in South Korea, where Hyundai-Kia's integrated procurement organization consolidates contact system sourcing under single-supplier agreements spanning multiple vehicle platforms.
Automotive Cell Contact System Carrier Market Segmentation
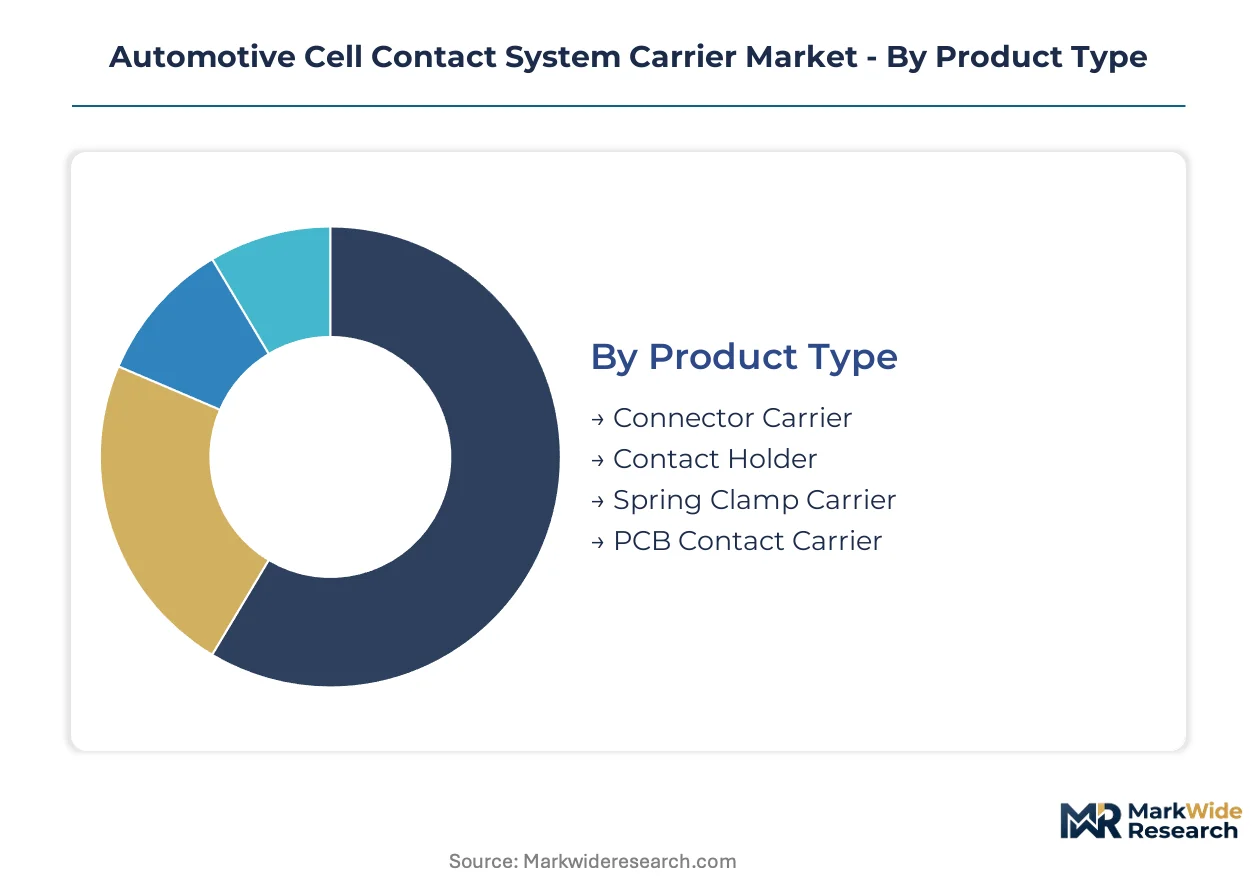
Segmentation in the automotive cell contact system carrier market reveals how integration depth, manufacturing process, and supply chain position determine margin capture. Each dimension exposes distinct competitive dynamics between standalone hardware suppliers and embedded system providers.
Product Type:
Integration depth separates standalone mechanical carriers from platforms embedding sensing and connectivity firmware.
- Connector Carrier:Stamped nickel-plated copper substrates bridge cell terminals to busbar assemblies. German automotive engineering corridors specify these for 800V cell-to-pack architectures where alignment tolerances across 200+ cells are mandatory.
- PCB Contact Carrier:Injection-molded thermoplastic frames integrate printed circuit boards for cell-level voltage and temperature sensing. Hyundai-Kia's integrated procurement organization in South Korea sources these for subscription-enabled battery management diagnostics.
- Contact Holder:Precision-machined retainers secure cylindrical or prismatic cell geometries during automated pack assembly lines.
- Spring Clamp Carrier:Resilient contact mechanisms maintain electrical continuity across thermal cycling and vibration loads in powertrain modules.
Volume placements concentrate in connector carriers; the faster expansion belongs to PCB contact carriers.
Technology:
Cost tier alignment separates high-volume stamping operations from premium overmolding and precision welding methods.
- Overmolding:Multi-shot injection molding of thermoplastic seals around stamped metal inserts achieves IP67+ ingress protection. Premium electric vehicle platforms specify these for 800V systems where seal integrity failures cascade into warranty exposure.
- Laser Welding:Fiber laser joining of copper alloys delivers finer joint control than ultrasonic alternatives. Battery pack assemblers specify laser-welded carriers for premium platforms demanding weld monitoring integration.
- Stamping:Progressive die forming of nickel-plated copper creates high-current geometries at scale for connector carriers.
- Injection Molding:Standalone thermoplastic fabrication serves cost-sensitive applications without metal reinforcement requirements.
- Ultrasonic Welding:Vibration-based metal joining persists in mid-tier electric vehicle platforms where joint precision requirements remain less stringent.
Margin pools favor overmolding due to seal integrity premiums; laser welding climbs fastest as 800V architectures proliferate.
Application:
Customer type stratification separates direct OEM procurement from tiered supplier integration.
- Electric Vehicles:Battery electric platforms demand carriers supporting 400V to 800V transitions with integrated current sensing. China's MIIT NEV technical rules enforce domestic supplier qualification thresholds for these applications.
- Battery Management Systems:Cell-level sensing integration requires carriers embedding PCB interconnects and firmware-upgradable connectivity. Europe's Battery Regulation mandates digital battery passports linking these carriers to upstream material provenance.
- Hybrid Electric Vehicles:Lower-voltage architectures sustain demand for conventional stamped carriers without embedded sensing.
- Powertrain Modules:Integrated motor-inverter-battery units specify vibration-resistant spring clamp carriers.
Procurement volume centers on electric vehicles; battery management systems gain share fastest as software-defined features expand.
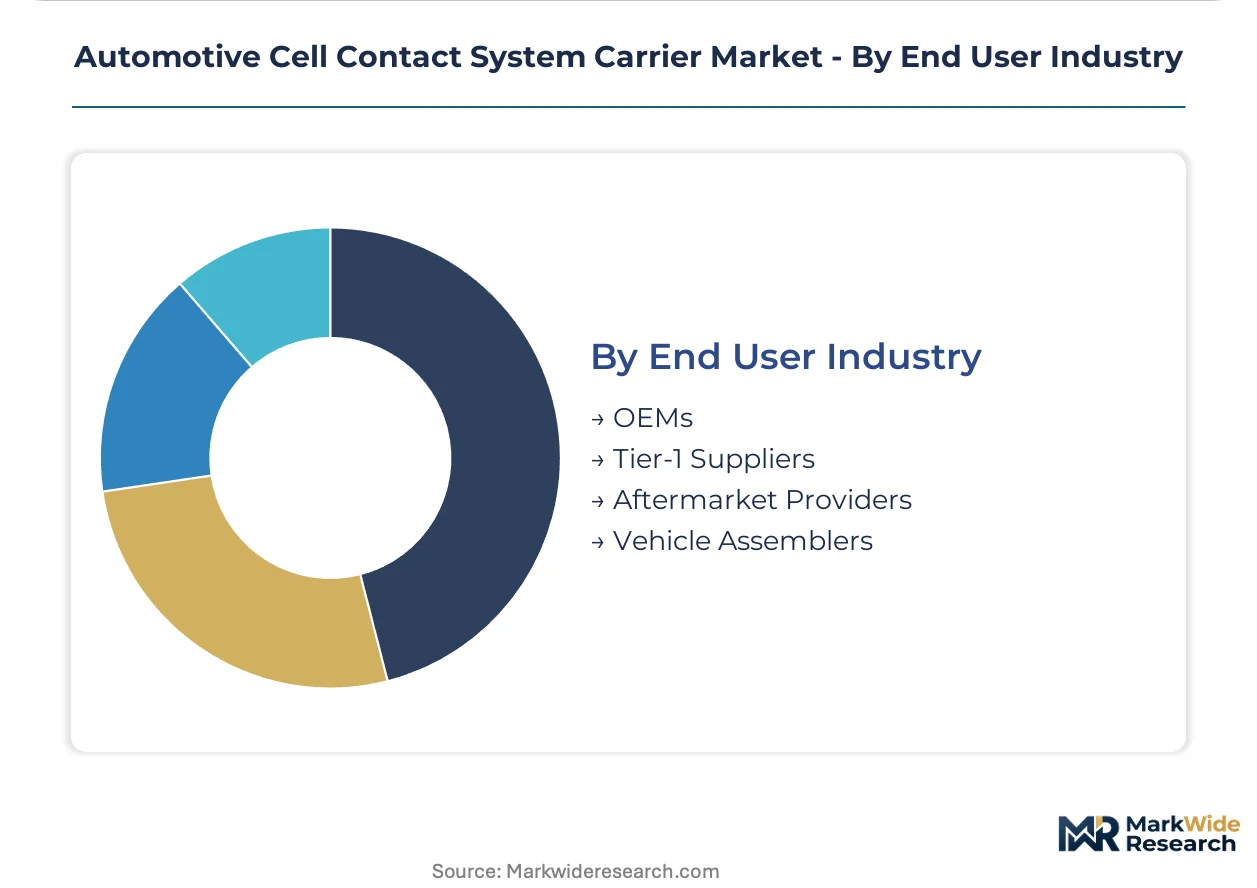
End User Industry:
Supply concentration patterns separate captive OEM engineering from distributed tier-1 manufacturing.
- OEMs:Volkswagen, BMW, and Mercedes-Benz specify carriers through long-term framework contracts bundling hardware, firmware updates, and predictive maintenance algorithms. Direct OEM-supplier partnerships displace traditional component distributors.
- Tier-1 Suppliers:Bosch and Continental procure carrier subassemblies for integration into complete battery pack modules serving multiple OEM customers.
- Vehicle Assemblers:Contract manufacturers in emerging production regions source certified carriers for local battery pack assembly under technology licensing arrangements.
- Aftermarket Providers:Second-life battery repurposing specialists demand carriers designed for disassembly and reconditioning as end-of-life electric vehicle packs enter stationary storage.
Contract flow concentrates with OEMs; aftermarket providers expand most quickly around circular economy regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the industry's engineering gravity, with German automotive OEMs driving precision specification tightening for 800V cell-to-pack architectures across multiple continents.
Germany
Baden-Württemberg's automotive corridor demands alignment tolerances across 200+ cells in module-free battery designs. ECHA REACH restrictions force halogen-free thermoplastic reformulation for European-bound production. Stuttgart and Munich engineering clusters specify integrated current sensing carriers through direct OEM-supplier framework contracts.
China
MIIT NEV technical rules enforce domestic supplier qualification thresholds for the world's largest electric vehicle production base. GB standards compliance accelerates local certification investments by foreign manufacturers. Shanghai and Shenzhen battery gigafactory ramps concentrate demand for nickel-plated copper alloy fabricators.
United States
NHTSA crashworthiness standards mandate redundant contact integrity for thermal runaway containment in premium electric vehicle platforms. EPA regulations shape thermal management integration requirements. Michigan and California automotive development centers drive laser welding specification premiums for 800V architectures.
South Korea
Hyundai-Kia's integrated procurement organization consolidates contact system sourcing under single-supplier agreements spanning multiple vehicle platforms. MFDS battery safety guidelines influence carrier design protocols. Seoul Capital Area battery pack assemblers specify PCB contact carriers for subscription-enabled diagnostics.
India
PLI scheme incentives for Advanced Cell Chemistry production create first-mover positioning for carriers qualified to BIS standards. Domestic battery gigafactory construction accelerates local supply chain development. Tamil Nadu and Gujarat manufacturing corridors attract tier-1 carrier subassembly investments.
Automotive Cell Contact System Carrier Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across stamping tool investments and semiconductor integration capabilities. The market structures around three tiers: integrated electronics-to-connector specialists, precision stamping and overmolding scale manufacturers, and regional tool-and-die fabricators serving certified subassembly niches. Dominant competitive moves include strategic partnerships for 800V platform qualification and geographic expansion to capture India PLI and China MIIT compliance positioning.
Among German-based integrated system providers, Robert Bosch anchors European supply through powertrain module specialization. TE Connectivity exemplifies scale-driven manufacturing across stamping and overmolding process lines. Infineon Technologies occupies the semiconductor-to-connector integration tier, representing the intelligent carrier architecture segment where firmware-upgradable connectivity repositions hardware as recurring-revenue platforms.
| Leading Market Players |
|---|
| Infineon Technologies |
| Robert Bosch |
| Continental AG |
| Amphenol |
| TE Connectivity |
| Ficosa Internacional |
| Sensata Technologies |
| Ennovi |
| AVL |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between 800V-qualified intelligent carriers and commodity stamped substrates splits both pricing power and supplier geography. Premium tiers command position through ECHA REACH-compliant halogen-free thermoplastics and integrated weld monitoring, while cost-sensitive procurement concentrates in high-volume stamping operations across China's MIIT-qualified supplier base.
Pricing Analysis
Margin tightening in overmolded seal architectures reflects nickel-plated copper alloy cost volatility and progressive die capital intensity. Three-tier pricing structure across intelligent carriers, precision-stamped substrates, and basic injection-molded holders tracks certification level and volume scale. Cost-down pressure on commodity connector carriers accelerates because OEMs consolidate sourcing under long-term framework contracts bundling hardware with firmware updates. Tier-1 suppliers exhibit highest price sensitivity; integrated electronics-to-connector specialists defend position through subscription-enabled diagnostics.
Supply Chain Analysis
Freight cost escalation from Indonesian nickel sulfate and German precision tooling hubs compresses margin capture for European-bound production. Supply concentrates in China for high-volume stamping, Germany for overmolding and laser welding integration, and South Korea for PCB contact carrier convergence. Raw material dependencies span electroplating-grade nickel, halogen-free PBT compounds, and hardened steel die sets. Single-source vulnerability sits with Indonesian nickel mining concentration. Distribution runs through direct OEM-supplier partnerships displacing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive cell contact system carrier supply is consolidating around capital-intensive 800V qualification and multi-regime certification burdens that marginalize undifferentiated stamping specialists.
For Market Incumbents: Anchor European supply position through captive halogen-free thermoplastic formulation capabilities ahead of ECHA REACH enforcement timelines. Defend against emerging Asian competitors by deepening laser welding process control expertise and securing direct OEM framework contracts spanning multiple vehicle platforms. Prioritize semiconductor-to-connector integration investments that reposition hardware as recurring-revenue platforms. For New Entrants and Emerging Players: Enter via India's PLI scheme for Advanced Cell Chemistry production before domestic battery gigafactory ramp accelerates BIS qualification requirements. Target second-life battery repurposing carriers designed for disassembly and reconditioning as circular economy regulations expand. Pursue tier-1 subassembly partnerships rather than direct OEM qualification to bypass multi-year certification cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated powertrain module specialists seeking 800V platform credentials. Five-to-ten year viability favors carriers with simultaneous precision stamping and injection molding capabilities plus semiconductor integration partnerships. Watch for MIIT NEV technical rule enforcement tightening as inflection indicator for China-accessible asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| 800V Platform Qualification | Direct OEM framework contracts with Volkswagen and BMW displace distributor channels. |
| Halogen-Free Thermoplastic Transition | ECHA REACH compliance opens premium European supply positions ahead of 2027 deadlines. |
| Laser Welding Process Integration | Fiber laser joint control satisfies Hyundai-Kia specifications for premium electric vehicle architectures. |
| Semiconductor-to-Connector Convergence | Infineon Technologies leverages firmware-upgradable connectivity for subscription revenue capture. |
| India PLI Scheme Positioning | Tamil Nadu and Gujarat manufacturing corridors attract first-mover BIS-qualified carrier investments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs across the automotive cell contact system carrier analysis. Primary interviews with OEM platform engineers, tier-1 supplier procurement leads, and tool-and-die specialists combined with secondary validation from NHTSA crashworthiness databases, ECHA REACH substance restrictions, and MIIT NEV technical rule publications. Bottom-up volume modeling triangulated against top-down battery pack production forecasts.
Granularity-level modeling deployed vehicle class, propulsion architecture, and regional production cluster dimensions at the segment level. CAGRs derived from unit economics analysis of nickel-plated copper alloy input costs and overmolding technology adoption curves across the projection horizon. Forecast inputs incorporated cell-to-pack design penetration rates and 800V architecture rollout timelines by OEM.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price volatility and REACH substitution timeline extensions. Outputs reflect documented assumptions around regulatory enforcement schedules and OEM platform standardization decisions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive Soc Market