
 Automotive Soc Market | 2026-2036
Automotive Soc Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Soc Market Analysis
Market Context
Silicon carbide is broadening power management economics in automotive SoC architectures, enabling higher thermal efficiency and reduced footprint for integrated drive systems. NXP Semiconductors leverages its S32 platform vertical integration to dominate functional safety-grade supply contracts with European OEMs. Qualcomm Technologies anchors premium digital cockpit revenue through Snapdragon Ride deployments across multiple vehicle programs. NVIDIA Corporation leads autonomous compute with Orin and Thor architectures, sustaining R&D intensity above industry norms for AI training and inference workloads.
Technical Definition and Structural Segments
An automotive system-on-chip integrates a CPU, GPU, memory controllers, and specialized accelerators onto a single die, typically fabricated at 7nm or 5nm process nodes, to execute real-time vehicle control, sensor fusion, and infotainment functions. SoCs for autonomous driving and advanced driver assistance command the highest silicon area and thermal design power budgets, reflecting compute intensity that scales with sensor count and algorithm complexity. Microcontrollers and processors retain volume dominance in powertrain and body electronics where deterministic latency requirements favor simpler cores. Machine learning and computer vision technology segments capture the fastest expansion as neural network accelerators become standard IP blocks in new platform designs.
Regulatory Framework
NHTSA in the United States, EMA through CE marking requirements in Europe, and China's MIIT through GB standards each impose distinct functional safety and electromagnetic compatibility obligations on automotive SoC suppliers seeking market access. ISO 26262 ASIL ratings and emerging UN ECE cybersecurity regulations are tightening qualification timelines and forcing silicon vendors to absorb validation costs upstream. Stakeholders must monitor divergence between regional homologation pathways, as fragmented compliance architectures threaten to duplicate engineering spend and compress margin pools for multi-market platform strategies.
Market Dynamics
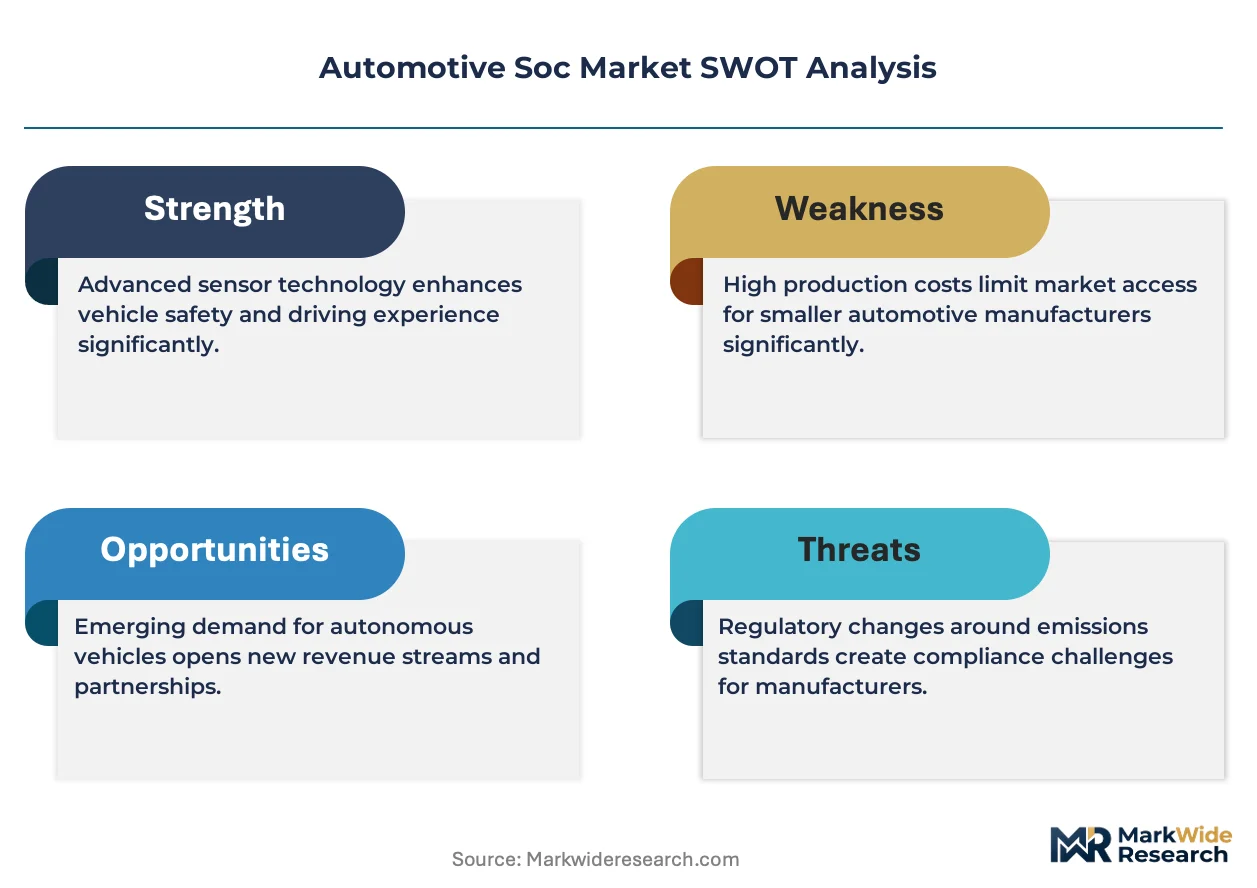
Compute consolidation onto single-die architectures is compressing supplier margins while elevating qualification barriers, as automakers demand ISO 26262 ASIL-D certification for safety-critical functions alongside GB-standard electromagnetic compliance for China market access.
Growth Catalysts
- ADAS Mandate Expansion:NHTSA crash-avoidance regulations in the United States and UN ECE vehicle safety frameworks in Europe are compelling passenger vehicle OEMs to embed sensor-fusion SoCs across model lineups.
- Silicon Carbide Integration:Wide-bandgap semiconductors are reducing thermal management overhead in integrated drive systems, enabling higher power density without liquid cooling infrastructure.
- German Engineering Clusters:Stuttgart and Munich validation centers are concentrating premium SoC specification work, pulling R&D investment toward functional safety-grade silicon architectures.
Market Restraints
- Advanced Node Cost Structure:5nm and 3nm foundry capacity at TSMC and Samsung Foundry commands wafer premiums that compress automotive semiconductor gross margins below industrial averages.
- Geographic Supply Concentration:Taiwan and South Korea dominate leading-edge logic fabrication, creating single-source vulnerability for automotive platforms requiring 7nm or finer process nodes.
- Functional Safety Validation Burden:ISO 26262 fault analysis and ASIL rating documentation extend development cycles by 18-24 months versus consumer-grade silicon.
Strategic Opportunities
- India Production Localization:PLI scheme incentives for semiconductor packaging and testing are attracting automotive SoC back-end investment to offset China-plus-one supply chain strategies.
- Software-Defined Vehicle Convergence:Over-the-air update architectures are merging infotainment and autonomous compute domains, creating unified platform opportunities that displace discrete ECU silos.
- Cybersecurity Mandate Tailwind:UN ECE R155 and R156 regulations are forcing OEMs to upgrade hardware security modules, opening specification windows for suppliers with embedded cryptographic accelerators.
Industry Challenges
- Functional Safety Talent Scarcity:ISO 26262 systems engineering and fault-tree analysis expertise concentrates among German and Japanese supplier workforces, constraining expansion timelines for new market entrants.
- Legacy Architecture Integration:CAN and LIN bus protocols in body electronics domains resist Ethernet migration, forcing bridge SoC designs that add die area without performance benefit.
- Multi-Market Homologation Burden:Divergent electromagnetic compatibility testing between EMA CE marking, NHTSA FMVSS, and MIIT GB standards duplicates validation spend for single-platform global programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Soc Market |
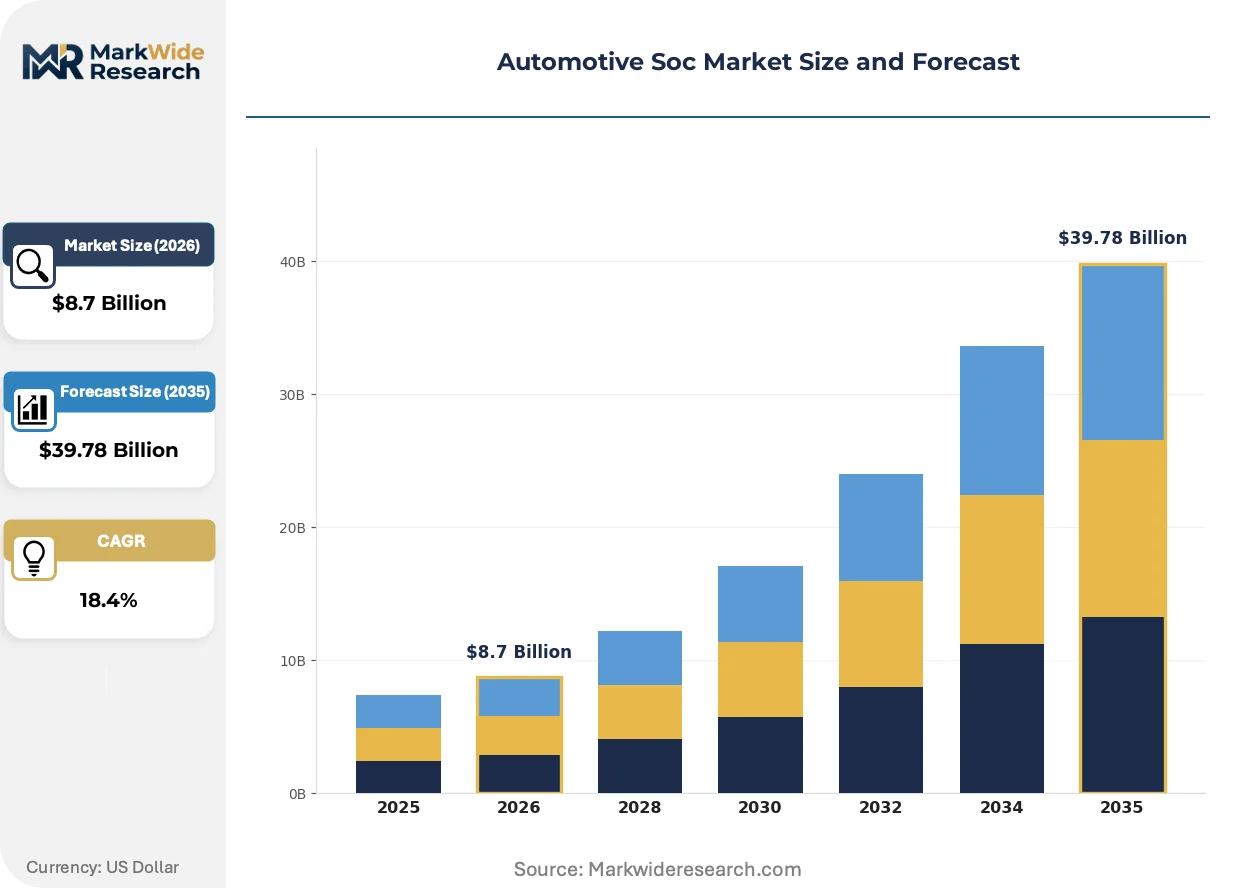
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Processors, SoCs, FPGAs End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Machine Learning, Computer Vision, Connectivity, Infotainment Application: Autonomous Driving, Advanced Driver Assistance, Telematics, Vehicle-to-Everything |
| Companies Covered | NXP Semiconductors, Infineon Technologies AG, STMicroelectronics, Texas Instruments Incorporated, Renesas Electronics Corporation, Qualcomm Technologies, NVIDIA Corporation, Samsung Electronics Co. Ltd., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Soc Market Emerging Trajectories
Neural network acceleration hardware is migrating from discrete add-ons to standard IP blocks, while regulatory fragmentation and procurement centralization are simultaneously compressing supplier margins and elevating platform consolidation economics.
Chiplets are integrating heterogeneous compute elements through die-to-die interconnects, enabling automotive OEMs to mix process nodes within a single package. Tier-1 suppliers in Germany and Japan are adopting chiplet architectures for 2026 platform designs. This modularity is integrating function-specific accelerators without monolithic retooling costs.
EMA cybersecurity regulations through UN ECE R155 are mandating hardware security modules with tamper-resistant key storage for all connected vehicle systems. European OEMs must demonstrate supply chain security management by 2025. Premium SoC suppliers with pre-integrated secure enclaves are capturing specification preference in Stuttgart and Munich engineering centers.
Direct OEM procurement of silicon is displacing tiered supplier mediation for autonomous compute and cockpit domains. German and US automakers are establishing chip design partnerships that bypass traditional tier-1 electronics suppliers. This disintermediation concentrates in programs where software differentiation exceeds hardware commoditization risk.
Automotive Soc Market Segmentation
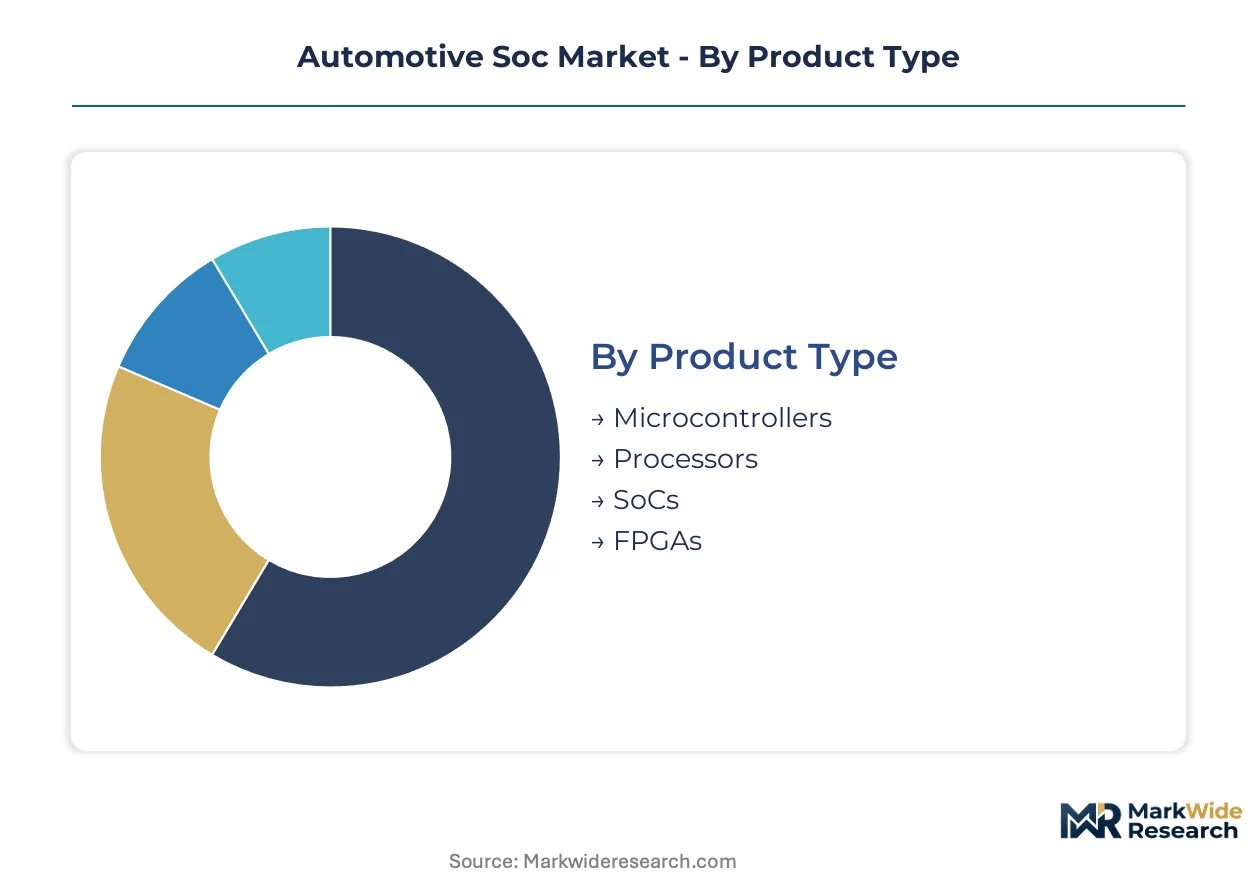
Automotive SoC procurement cycles align with vehicle platform refreshes spanning 5-7 years, creating distinct upgrade windows across product categories. Segmentation reveals where silicon vendors concentrate R&D investment versus where cost optimization dominates supplier selection criteria.
Product Type:
Replacement cycles for automotive compute silicon compress as software-defined architectures shorten platform lifecycles from hardware-centric timelines.
- Microcontrollers:These deterministic cores execute real-time powertrain and body electronics functions at 40nm-90nm process nodes. Demand concentrates with German and Japanese OEMs for engine control modules where ISO 26262 ASIL-D certification gates supplier qualification.
- Processors:Multi-core ARM architectures handle infotainment and gateway aggregation workloads. Stuttgart engineering centers specify these for premium digital cockpit programs where thermal design power budgets exceed 15 watts.
- SoCs:Integrated CPU-GPU-NPU architectures fabricated at 7nm or 5nm nodes fuse sensor fusion and AI inference onto single die.
- FPGAs:Reprogrammable logic enables algorithm updates post-deployment for prototype autonomous fleets and validation vehicles.
Microcontrollers sit at the top of the volume ranking, with SoCs climbing the fastest.
End User:
Procurement authority shifts upstream as direct OEM silicon sourcing displaces traditional tier-1 mediation for compute-intensive domains.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz now negotiate directly with NXP and Qualcomm for cockpit and autonomous compute silicon, bypassing Bosch and Continental for specification control. This disintermediation concentrates where software differentiation exceeds hardware commoditization risk.
- Tier-1 Suppliers:Continental, Bosch, and Denso retain procurement dominance in body electronics and chassis domains where legacy CAN integration requirements favor established module integration expertise.
- Aftermarket Providers:These channels source replacement infotainment modules and telematics retrofit kits for vehicle parc extension programs.
- Dealerships:Authorized retail networks distribute OEM-approved connectivity upgrades and software-enabled feature activations.
Tier-1 suppliers retain volume leadership in established domains, with OEM direct procurement gaining share fastest in autonomous and cockpit segments.
Technology:
Technology adoption curves diverge sharply between safety-critical validation requirements and consumer-electronics heritage.
- Machine Learning:Neural network accelerators now standard IP blocks in new ADAS SoC designs. NVIDIA Orin and Qualcomm Snapdragon Ride deployments across German and US vehicle programs concentrate demand for INT8 and FP16 inference engines.
- Computer Vision:Image signal processors and stereo depth engines execute real-time object detection for camera-centric ADAS architectures.
- Connectivity:5G-V2X modems and DSRC transceivers integrate cellular and direct short-range communication for vehicle-to-infrastructure applications.
- Infotainment:GPU clusters render multi-display dashboards and rear-seat entertainment with consumer-grade Android Automotive integration.
Infotainment commands current volume leadership, with machine learning accelerators expanding most quickly.
Application:
Application prioritization follows regulatory mandate timelines that force sensor-fusion compute into base vehicle configurations.
- Autonomous Driving:L4-ready compute platforms require 500+ TOPS AI performance with redundant execution paths. NVIDIA Thor and Qualcomm Snapdragon Ride Flex architectures target robotaxi and premium consumer programs where German and California regulators shape validation requirements.
- Advanced Driver Assistance:L2+ highway automation mandates under NHTSA and UN ECE frameworks compel sensor-fusion SoC deployment across model lineups. These systems integrate camera, radar, and ultrasonic inputs through ASIL-B/D qualified silicon.
- Telematics:Cellular connectivity modules enable over-the-air updates and usage-based insurance data collection.
- Vehicle-to-Everything:V2X communication processors coordinate with traffic infrastructure and vulnerable road users in pilot deployment zones.
Advanced Driver Assistance sits at the top of the volume ranking, with Autonomous Driving climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Munich engineering clusters concentrate premium SoC specification work for functional safety-grade silicon architectures serving European and export vehicle programs.
Germany
Volkswagen Group, BMW, and Mercedes-Benz drive ADAS SoC procurement through direct silicon sourcing partnerships. KBA homologation requirements under UN ECE vehicle safety frameworks mandate ISO 26262 ASIL-D certification for autonomous compute platforms. Stuttgart validation centers coordinate specification work for next-generation sensor-fusion architectures.
United States
Tesla, Ford, and General Motors accelerate L2+ highway automation deployment across light truck and SUV lineups. NHTSA crash-avoidance regulations compel sensor-fusion SoC integration into base vehicle configurations. California regulators shape validation requirements for L4-ready compute platforms targeting robotaxi programs.
China
BYD, NIO, and XPeng integrate domestic and imported SoC architectures for intelligent cockpit and autonomous driving domains. MIIT GB standards impose electromagnetic compatibility obligations distinct from European and US homologation pathways. Yangtze River Delta manufacturing clusters concentrate vehicle assembly capacity driving silicon demand.
Japan
Toyota, Honda, and Nissan maintain procurement relationships with established semiconductor suppliers for powertrain and body electronics modules. METI industrial policy supports domestic semiconductor packaging investment to offset foundry concentration risk. Nagoya engineering centers specialize in deterministic latency core designs for engine control applications.
South Korea
Hyundai Motor Group and Kia Corporation deploy Snapdragon Ride and domestic alternatives across premium vehicle programs. MFDS coordinates with automotive regulators on emerging cybersecurity mandate implementation. Seoul Capital Area R&D facilities concentrate infotainment and connectivity silicon development.
Automotive Soc Market Vendor Landscape
Global majors compete with regional champions across functional safety certification and foundry access dimensions. The vendor base stratifies between IDM incumbents with captive fabrication and fabless designers dependent on TSMC and Samsung Foundry capacity allocation. Three archetypes dominate: European functional safety specialists, US AI compute architects, and Asian diversified electronics conglomerates. Competitive moves center on strategic partnerships for advanced node access and vertical integration into packaging and testing capabilities.
Within the functional safety specialist tier, NXP Semiconductors and Infineon Technologies AG exemplify European IDM positioning through S32 platform deployments and automotive-grade power management integration. Qualcomm Technologies and NVIDIA Corporation occupy positions at the AI compute frontier, with Snapdragon Ride and Thor architectures respectively representing divergent approaches to autonomous silicon. Among diversified Asian suppliers, Samsung Electronics Co. Ltd. leverages captive foundry capacity to anchor memory and logic integration strategies for cockpit domain consolidation.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Infineon Technologies AG |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Renesas Electronics Corporation |
| Qualcomm Technologies |
| NVIDIA Corporation |
| Samsung Electronics Co. Ltd. |
| Intel Corporation |
| Others |
Supply Flow & Price Mechanics
Automotive OEM direct procurement of autonomous compute silicon is forcing foundry capacity commitments that reshape cost allocation across the supply base. This demand-side consolidation elevates upfront non-recurring engineering charges while compressing unit economics for tier-1 suppliers caught between fixed-price module contracts and variable wafer pricing.
Pricing Analysis
Foundry wafer cost pass-through dominates automotive SoC pricing structures, with TSMC and Samsung Foundry premiums for 5nm and 3nm nodes flowing directly to OEM silicon budgets. Price differentiation separates ASIL-D certified safety-grade silicon from infotainment-grade alternatives, with volume scale and thermal design power specifications as secondary tiering factors. Pricing pressure stems from advanced node cost structures that compress automotive semiconductor gross margins below industrial averages. Tier-1 suppliers exhibit highest price sensitivity due to fixed-price module contracts, while direct OEM procurement shows greater tolerance for premium safety-certified silicon.
Supply Chain Analysis
Freight and logistics costs for specialized semiconductor equipment and precursor chemicals add marginal burden to automotive SoC landed costs relative to the dominant wafer price component. Supply concentrates in Taiwan and South Korea for leading-edge logic fabrication, with Japan and Germany contributing equipment and materials layers. Raw material dependencies include silicon wafers, photoresists, and rare earth elements for advanced lithography. Single-source vulnerability at the foundry level represents the primary structural risk. Distribution runs through direct OEM procurement channels for autonomous and cockpit domains, with traditional tier-1 mediation persisting in body electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage potential through India PLI scheme incentives for semiconductor packaging and testing, offsetting the cost premium of Taiwan and South Korea foundry concentration against European and North American qualification requirements.
For Market Incumbents: Lock in captive foundry capacity through long-term offtake agreements with TSMC and Samsung Foundry to defend against fabless entrant disruption. Deepen backward integration into automotive-grade packaging capabilities in Germany and Japan to capture margin pools escaping to OSAT providers. Prioritize ISO 26262 ASIL-D certification maintenance as regulatory barriers tighten under UN ECE frameworks.
For New Entrants and Emerging Players: Cloud-based EDA tool subscriptions and virtual verification platforms lower capital barriers for chiplet architecture entry into ADAS accelerator segments. Target India packaging and testing back-end investment as the most penetrable geography, leveraging PLI scheme incentives against established German and Japanese incumbents. Pursue direct OEM design partnerships that bypass tier-1 supplier mediation in software-defined vehicle domains.
For Investors and Strategic Acquirers: Asymmetric upside sits with fabless specialists possessing pre-integrated hardware security modules and UN ECE R155-compliant secure enclave IP. Long-term viability favors acquisition targets with demonstrated automotive qualification track records and existing foundry relationships rather than consumer silicon heritage. Monitor direct OEM procurement share gains in autonomous compute as the inflection signal for tier-1 supplier displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces non-recurring engineering costs across Volkswagen Group and BMW vehicle programs. |
| Battery Supply Agreement | Secures silicon carbide power management integration for integrated drive system consolidation. |
| Software-Defined Vehicle Investment | Enables over-the-air update architectures that merge infotainment and autonomous compute domains. |
| Geographic Manufacturing Footprint | India PLI scheme incentives attract automotive SoC back-end investment for China-plus-one strategies. |
| Charging Infrastructure Partnership | V2X communication processor deployment coordinates with traffic infrastructure in German pilot zones. |
Methodological Framework
Coverage spans Germany, United States, China, Japan, and South Korea, with primary inputs from each market cluster combined with secondary validation. Primary research incorporated interviews with OEM platform engineers, Tier 1 supplier procurement leads, foundry account managers, automotive semiconductor R&D directors, and validation center technical staff. Secondary sources included vehicle production databases, IHS Markit registration data, SEC semiconductor filings, and UN ECE regulatory documentation. Bottom-up unit demand modeling triangulated against top-down OEM silicon budget allocations.
Rate-of-change decomposition separated volume growth from value-per-unit evolution across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from fitted growth curves applied to platform refresh cycle timing and regulatory mandate phase-in schedules. Forecast inputs incorporated ADAS penetration curves by vehicle segment and autonomous compute TOPS requirements by automation level.
The model assumes a particular technology adoption path; alternative pathways for chiplet heterogeneous integration would alter the outlook if monolithic retooling costs fall faster than projected. Forecasts reflect assumptions about foundry capacity allocation priorities, regulatory harmonization timelines, and OEM vertical integration appetite. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Automotive Ignition System Market