
 Automotive Touch Screen Control Systems Market | 2026-2036
Automotive Touch Screen Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Touch Screen Control Systems Market Analysis
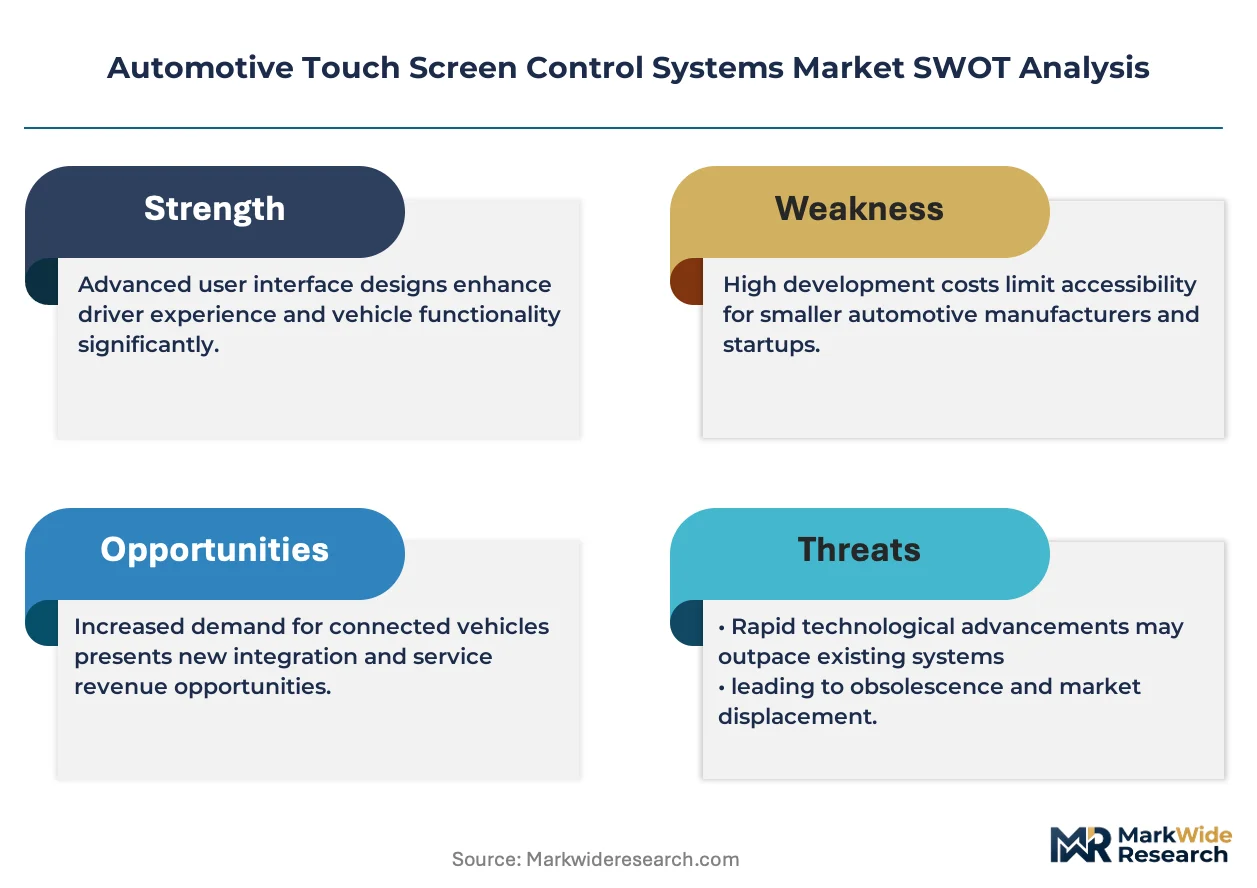
Capacitive-to-multi-touch migration with haptic feedback integration is rewriting how automotive HMI modules are architected. Continental AG leverages its display-integration expertise to anchor premium cockpit contracts across German OEMs. Robert Bosch GmbH sustains R&D intensity in gesture-recognition algorithms for hands-free climate and media control. DENSO Corporation dominates Japanese OEM supply chains with temperature-resistant touch modules engineered for extreme-cabin environments.
Automotive touch screen control systems comprise glass-substrate display panels bonded to capacitive or resistive sensor layers, driven by integrated IC controllers processing multi-point input at sub-100-millisecond latency for real-time vehicle function command. These assemblies consolidate climate, navigation, entertainment, and telematics interfaces into centralized digital surfaces, eliminating mechanical switchgear to reduce component count and enable software-defined cabin updates. Capacitive touch technology leads system-type value capture owing to its dominance in premium central infotainment deployments, while gesture control represents the fastest-expanding technology segment as OEMs pursue eyes-on-road compliance. Electric vehicles within vehicle-type segmentation concentrate disproportionate demand for expanded screen real estate, with battery-electric architectures freeing dashboard space previously occupied by powertrain gauges.
NHTSA guidelines on driver-distraction reduction shape United States product standards by mandating glance-time limits and manual-input complexity caps for in-vehicle interfaces. The EPA's fuel-economy testing protocols indirectly pressure OEMs toward lighter electronic assemblies, favoring bonded-glass touch modules over discrete mechanical controls. ECE R79 in Europe imposes steering-system safety requirements that cascade into touch-based driver-assistance activation protocols. Stakeholders must monitor how software-liability frameworks evolve as over-the-air update capabilities expand the functional scope of touch-screen systems beyond hardware certification baselines.
Market Dynamics
Electric vehicle OEMs are consolidating dashboard functions into single large-format touch surfaces, eliminating mechanical switchgear and forcing Tier-1 suppliers to rearchitect HMI modules around software-defined update cycles rather than fixed hardware certifications.
Growth Catalysts
- NHTSA Distraction-Mitigation Guidelines:United States federal mandates capping driver glance-time at two seconds are accelerating voice and haptic feedback integration into touch interface designs.
- Capacitive Multi-Touch Migration:Automotive display controllers now process ten-point input at sub-100-millisecond latency, enabling pinch-zoom navigation and swipe-based climate control previously reserved for consumer electronics.
- China EV Cabin Architectures:Domestic battery-electric brands prioritize panoramic digital cockpits spanning instrument cluster to passenger entertainment, concentrating procurement demand for bonded-glass touch modules in Shanghai and Shenzhen manufacturing corridors.
Market Restraints
- Indium Tin Oxide Supply Concentration:Transparent conductive oxide deposition relies on refined indium supply chains concentrated in Chinese smelting operations, exposing touch sensor layer costs to geopolitical trade friction.
- Automotive-Grade Certification Timelines:AEC-Q100 qualification for controller ICs demands 12-18 month validation cycles, freezing design iterations and delaying technology refresh rates relative to consumer electronics.
- Mechanical Switch Residual Demand:Commercial vehicle fleets and budget passenger segments retain physical button requirements for glove-compatible operation in cold-climate markets, fragmenting volume across interface technologies.
Strategic Opportunities
- Gesture Recognition Convergence:Time-of-flight sensors fused with capacitive touch layers enable mid-air hand tracking for eyes-on-road media control, opening premium differentiation in German and Korean OEM lineups.
- Indian Domestic EV Production:PLI scheme incentives for local automotive electronics manufacturing are drawing touch module assembly investments toward Chennai and Pune industrial zones.
- Over-the-Air Functional Expansion:Software-defined touch interfaces enable subscription-activated feature unlocking, transforming hardware sales into recurring revenue streams for cockpit system integrators.
Industry Challenges
- Functional Safety Engineer Scarcity:ISO 26262 ASIL-B certification expertise for touch-based driver assistance activation protocols commands premium salaries and extends hiring timelines across European and North American engineering centers.
- Legacy Bus Architecture Integration:CAN and LIN protocol translation layers add latency and failure modes when connecting modern capacitive controllers to decade-old vehicle network backbones in model-refresh programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Touch Screen Control Systems Market |
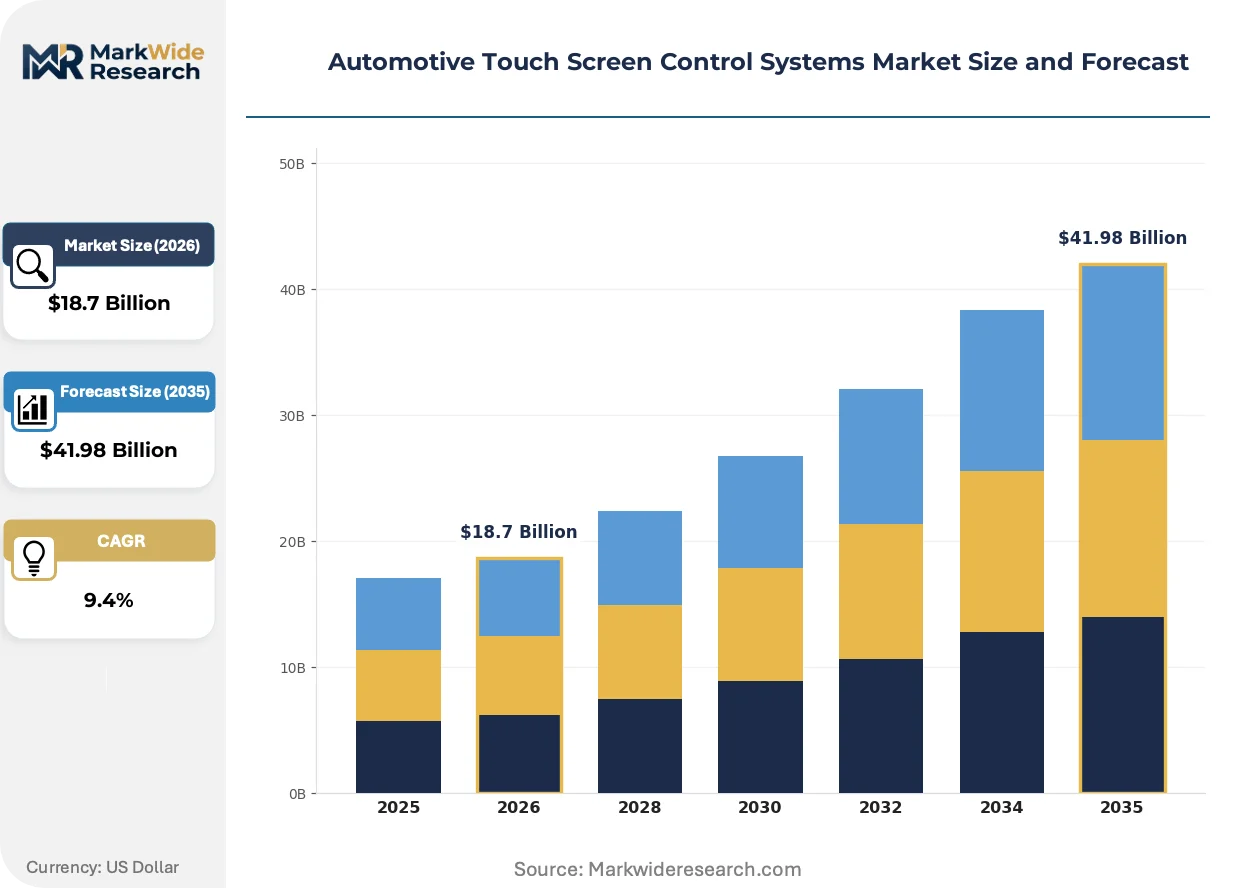
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Central Infotainment, Digital Instrument Cluster, Heads-Up Display, Over-the-Air Updates Technology: Capacitive Touch, Resistive Touch, Multi-Touch, Gesture Control Vehicle Type: Passenger Cars, SUVs, Commercial Vehicles, Electric Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Car Rental Services |
| Companies Covered | Continental AG, Robert Bosch GmbH, DENSO Corporation, Panasonic Holdings Corporation, Samsung Electronics Co. Ltd., Visteon Corporation, Alps Alpine, Fujitsu Ltd., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Touch Screen Control Systems Market Emerging Trajectories
Haptic feedback systems are migrating from simple vibration motors to localized piezoelectric actuators, redefining how drivers confirm touch inputs without visual confirmation and compressing interface design cycles around perceptual psychology rather than pure electronics.
Force-sensitive touch technology is hybridizing pressure-sensing resistor layers with conventional capacitive arrays, enabling differentiated input modes based on press depth. German luxury OEMs are deploying this in 2024-2025 model year central stack controllers to reduce accidental activation during vehicle motion. The structural consequence is a bifurcation in controller IC architectures, with premium tier suppliers integrating analog-to-digital conversion for force channels while economy tier suppliers delay adoption.
ECE R79 steering system safety requirements in Europe are cascading into touch-based driver assistance activation protocols, mandating redundant confirmation pathways for lane-keeping and adaptive cruise engagement. Tier-1 suppliers serving Volkswagen Group and Stellantis are redesigning menu hierarchies to require sustained press-and-hold gestures rather than single taps. This regulatory friction is delaying launch timelines by four to six months for platforms targeting dual US-Europe certification.
Chinese EV buyers are prioritizing passenger-facing entertainment screens as differentiation factors, compressing procurement evaluation cycles from 24 months to 14 months for secondary display modules. Domestic brands including NIO and Xpeng are specifying 15-inch and larger formats with independent Android operating environments, forcing suppliers to pre-integrate content delivery platforms before vehicle program kickoff. This pattern is least visible in Japanese OEM lineups, where conservative HMI philosophies retain centralized driver-focused architectures.
Automotive Touch Screen Control Systems Market Segmentation
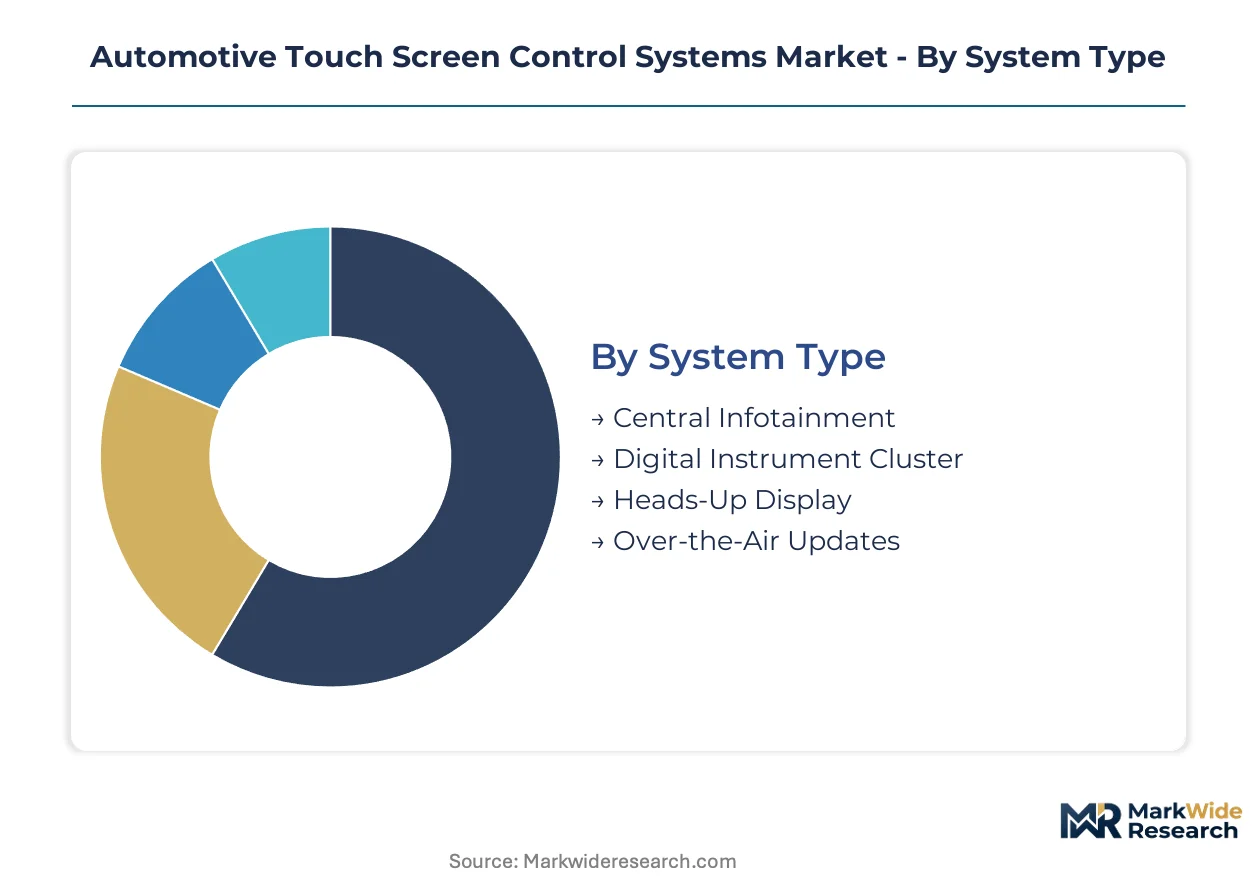
Touch screen control systems fragment across four structural dimensions that determine procurement patterns and margin profiles. System type and technology choices dominate engineering specifications, while vehicle type and end user dictate volume concentration and certification requirements.
System Type:
Mature centralized architectures coexist with emerging distributed screen networks as cabin digitization accelerates.
- Central Infotainment:Consolidated glass-substrate panels bonded to capacitive sensor layers process navigation, media, and climate commands through unified graphical interfaces. German and Korean OEMs concentrate procurement for 10-15 inch formats in premium sedan and SUV lineups, driven by consumer expectation of smartphone-parallel interaction models.
- Digital Instrument Cluster:Reconfigurable TFT-LCD or OLED displays replacing analog gauges require sunlight-readable brightness levels and ASIL-B functional safety certification for speedometer and warning indicator reliability. Electric vehicle platforms in China and the United States prioritize this segment for powertrain information visualization, compressing supplier qualification timelines.
- Heads-Up Display:Windshield-projected interfaces reduce driver glance time by overlaying navigation and speed data within the forward field of view.
- Over-the-Air Updates:Software-defined touch functionality enables remote feature activation and interface redesign without hardware replacement.
Central Infotainment handles the majority of throughput; Over-the-Air Updates is expanding most quickly as subscription revenue models take hold.
Technology:
Cost tier stratification separates premium multi-touch deployments from economy resistive alternatives in emerging market vehicle programs.
- Capacitive Touch:Electric-field disruption detection enables sub-100-millisecond response times and multi-point gesture recognition through indium tin oxide deposition on glass substrates. Premium passenger car and electric vehicle architectures in Germany, Japan, and the United States specify this technology exclusively, accepting higher bill-of-materials costs for optical clarity and durability.
- Gesture Control:Time-of-flight cameras and radar sensors track hand position in three-dimensional space for eyes-on-road media and climate manipulation. Korean and German luxury OEMs are integrating this capability into flagship electric vehicle lineups, responding to NHTSA distraction-mitigation guidelines and European type-approval safety requirements.
- Multi-Touch:Ten-point input controllers enable pinch-zoom navigation and multi-finger swipe commands.
- Resistive Touch:Pressure-activated membrane layers persist in commercial vehicle and budget passenger applications requiring glove-compatible operation.
Capacitive Touch commands the largest installed base; Gesture Control is gaining share fastest as regulatory pressure intensifies.
Vehicle Type:
Application context determines screen size, environmental sealing, and vibration resistance specifications across mobility segments.
- Electric Vehicles:Battery-electric architectures eliminate mechanical gauge clusters and free dashboard real estate for panoramic digital cockpits spanning 15 inches or more. Chinese domestic brands NIO and Xpeng concentrate procurement demand in Shanghai and Shenzhen manufacturing corridors, specifying independent Android operating environments for passenger entertainment screens.
- SUVs:Higher seating positions and expanded cabin volumes accommodate larger-format central stack displays with integrated climate vent controls.
- Passenger Cars:Sedan and hatchback form factors optimize screen integration within constrained dashboard depths.
- Commercial Vehicles:Fleet operators retain physical button requirements for glove-compatible operation in cold-climate markets.
Electric Vehicles absorb the steepest volume expansion; Commercial Vehicles maintains residual mechanical switch demand.
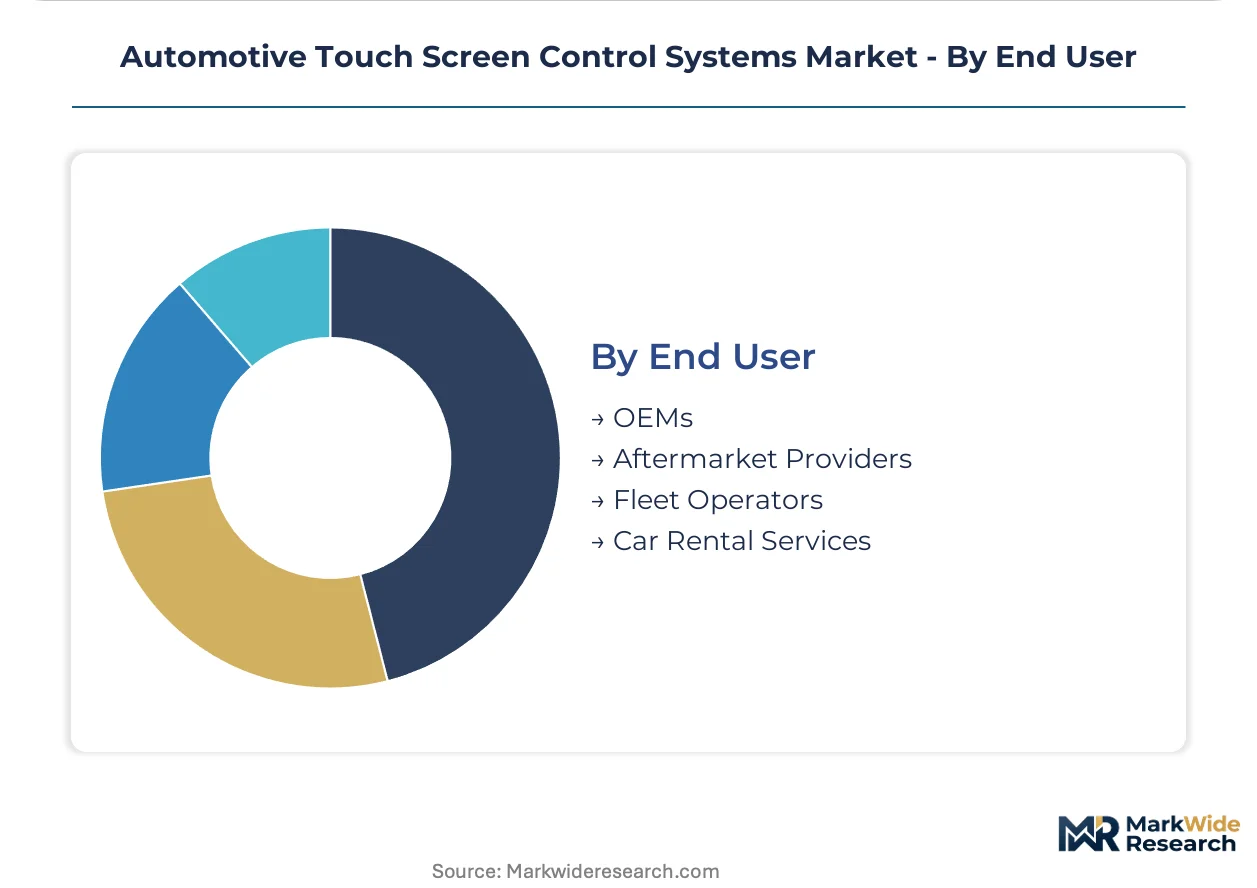
End User:
Customer type dictates certification depth, update frequency, and warranty liability structures.
- OEMs:Original equipment manufacturers specify AEC-Q100 qualified controller ICs and bonded-glass touch modules through 12-18 month validation cycles, locking design architectures for entire model generations. Volkswagen Group, Stellantis, and domestic Chinese electric vehicle producers drive procurement concentration in European and East Asian supply corridors.
- Fleet Operators:Commercial vehicle and car rental fleet managers prioritize durability and standardized interfaces across mixed-vehicle pools.
- Aftermarket Providers:Retrofit touch screen kits serve vehicle owners seeking infotainment upgrades outside factory warranty periods.
- Car Rental Services:Daily rental fleets demand simplified interfaces minimizing customer training requirements.
OEMs dominate absolute procurement volume; Fleet Operators are climbing the fastest on share as electrified commercial vehicle deployment scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle OEMs in China concentrate procurement demand for large-format touch modules, while German and United States automakers navigate divergent regulatory pressures on driver-distraction mitigation.
China
NIO and Xpeng specify 15-inch passenger entertainment screens with independent Android environments, compressing supplier qualification cycles to 14 months. MIIT mandates cybersecurity certification for connected vehicle interfaces. Manufacturing corridors in Shanghai and Shenzhen bond glass substrates to capacitive sensor layers for domestic battery-electric architectures.
Germany
Volkswagen Group and BMW prioritize gesture-recognition integration for eyes-on-road compliance in premium electric lineups. ECE R79 steering-system safety requirements cascade into touch-based driver-assistance activation protocols. Stuttgart and Munich engineering centers redesign menu hierarchies for sustained press-and-hold confirmation gestures.
United States
Tesla and legacy Detroit automakers deploy over-the-air update capabilities to expand touch-screen functionality post-sale. NHTSA caps driver glance-time at two seconds, accelerating voice and haptic feedback integration. Michigan and California development hubs architect software-defined cockpit systems around subscription revenue models.
Japan
Toyota and Honda retain conservative HMI philosophies with centralized driver-focused architectures resisting passenger-screen expansion. METI promotes domestic semiconductor supply chain resilience for automotive controller ICs. Nagoya and Tokyo manufacturing zones engineer temperature-resistant touch modules for extreme-cabin environments.
India
Tata Motors and Mahindra Electric localize touch module assembly for domestic EV production under PLI scheme incentives. BIS certification requirements extend validation timelines for imported controller ICs. Chennai and Pune industrial zones attract bonded-glass touch module investments from multinational Tier-1 suppliers.
Automotive Touch Screen Control Systems Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Tier-1 cockpit system integrators dominate OEM procurement through multi-year platform contracts. Specialized sensor-layer fabricators occupy mid-tier positions supplying standardized capacitive modules. Component-level semiconductor suppliers anchor the technology base with controller IC and haptic driver silicon. Consolidation pressure manifests through strategic partnerships between display integrators and gesture-recognition algorithm developers, alongside vertical integration moves into bonded-glass module assembly.
Within the German engineering-centric tier, Continental AG and Robert Bosch GmbH exemplify platform-scale integrators serving Volkswagen Group and BMW architectures. DENSO Corporation represents the Japanese supply-chain anchor with temperature-hardened module expertise for Toyota and Honda programs. These three entities occupy positions defined by geographic OEM alignment rather than interchangeable global competition.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| DENSO Corporation |
| Panasonic Holdings Corporation |
| Samsung Electronics Co. Ltd. |
| Visteon Corporation |
| Alps Alpine |
| Fujitsu Ltd. |
| Infineon Technologies AG |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Shenzhen express freight corridor carries bonded-glass touch modules from Chinese smelting operations to EV assembly plants, its volatile fuel surcharges amplifying cost-plus contract escalations while compressing margins for European buyers locked into indium-indexed supply agreements.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indium indexation dominate procurement for capacitive sensor layers, separating AEC-Q100 certified premium tiers from economy-grade resistive alternatives. Price differentiation hinges on ASIL-B functional safety certification and bonded-glass optical clarity grades. Cost compression in standard-tier modules intensifies as Chinese domestic brands consolidate procurement volumes. Fleet operators exhibit highest price sensitivity, while German luxury OEMs absorb premium positioning for haptic-integrated gesture systems.
Supply Chain Analysis
Contract manufacturing concentrates at Foxconn and BYD Electronics facilities in Shenzhen, with secondary capacity at Luxshare Precision and Goertek. Raw material flows draw from Chinese indium refining, South Korean display glass, and Japanese controller IC fabrication. Single-source vulnerability in transparent conductive oxide deposition exposes tier-1 suppliers to MIIT export license delays. Distribution runs through OEM-direct platform contracts rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where Android Automotive OS interoperability is displacing proprietary embedded systems, forcing hardware suppliers to architect around software-defined update cycles rather than fixed certifications.
For Market Incumbents: Build switching-cost moats through embedded software-service bundles that lock OEMs into multi-year cockpit platform contracts. Deepen backward integration into force-sensing resistor fabrication to defend margin position against Chinese sensor-layer specialists. Counter the threat of domestic Chinese EV brands verticalizing touch module assembly by accelerating Chennai and Pune capacity investments ahead of PLI scheme maturation. For New Entrants and Emerging Players: Pursue white-space opportunity in commercial vehicle retrofit kits serving cold-climate fleet operators with glove-compatible resistive interfaces. Target Indian domestic EV production corridors where multinational tier-1 presence remains thin. Penetrate through aftermarket channel partnerships with dealership networks seeking subscription-enabled feature unlocking revenue streams. For Investors and Strategic Acquirers: Gesture-recognition algorithm developers with automotive-grade time-of-flight integration sit as priority acquisition targets, capturing the fastest-expanding technology segment. Long-term viability centers on software-liability frameworks evolving beyond hardware certification baselines. Watch NHTSA rulemaking on over-the-air functional expansion as the signal for regulatory acceptance of recurring revenue cockpit architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables subscription-activated feature unlocking for Continental AG and Robert Bosch GmbH cockpit platforms. |
| Battery Supply Agreement | Secures indium-tin-oxide precursor chemicals for DENSO Corporation's temperature-resistant module production. |
| Geographic Manufacturing Footprint | Localizes bonded-glass assembly in Chennai and Pune corridors under India's PLI scheme incentives. |
| Platform Standardization | Consolidates Android Automotive OS interoperability across NIO and Xpeng passenger entertainment architectures. |
| Charging Infrastructure Partnership | Integrates touch-based charging station locators into Volkswagen Group and BMW central infotainment hierarchies. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of NHTSA regulatory filings, MIIT cybersecurity certifications, and OEM production databases. Conversations with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads informed demand-side validation. Bottom-up unit economics triangulate against top-down vehicle production forecasts from IHS Markit registration data and customs trade records.
Forecast inputs incorporate vehicle class stratification, propulsion architecture differentiation, content-per-vehicle trajectories, OEM tier positioning, and regional production cluster dynamics across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macro vehicle sales assumptions. Industry-specific inputs include AEC-Q100 qualification timeline compression and ECE R79 regulatory cascade effects on driver assistance activation protocols.
Macroeconomic conditions sit as an overlay; deviation in battery-electric vehicle penetration rates or indium spot pricing volatility would shift the trajectory. Forecasts reflect documented assumptions on software-liability framework evolution and NHTSA distraction-mitigation enforcement intensity. Quarterly review of OEM platform award announcements and MIIT connected vehicle certification queues is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market