
 Automotive Graphic Display Controller Market | 2026-2036
Automotive Graphic Display Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Graphic Display Controller Market Analysis
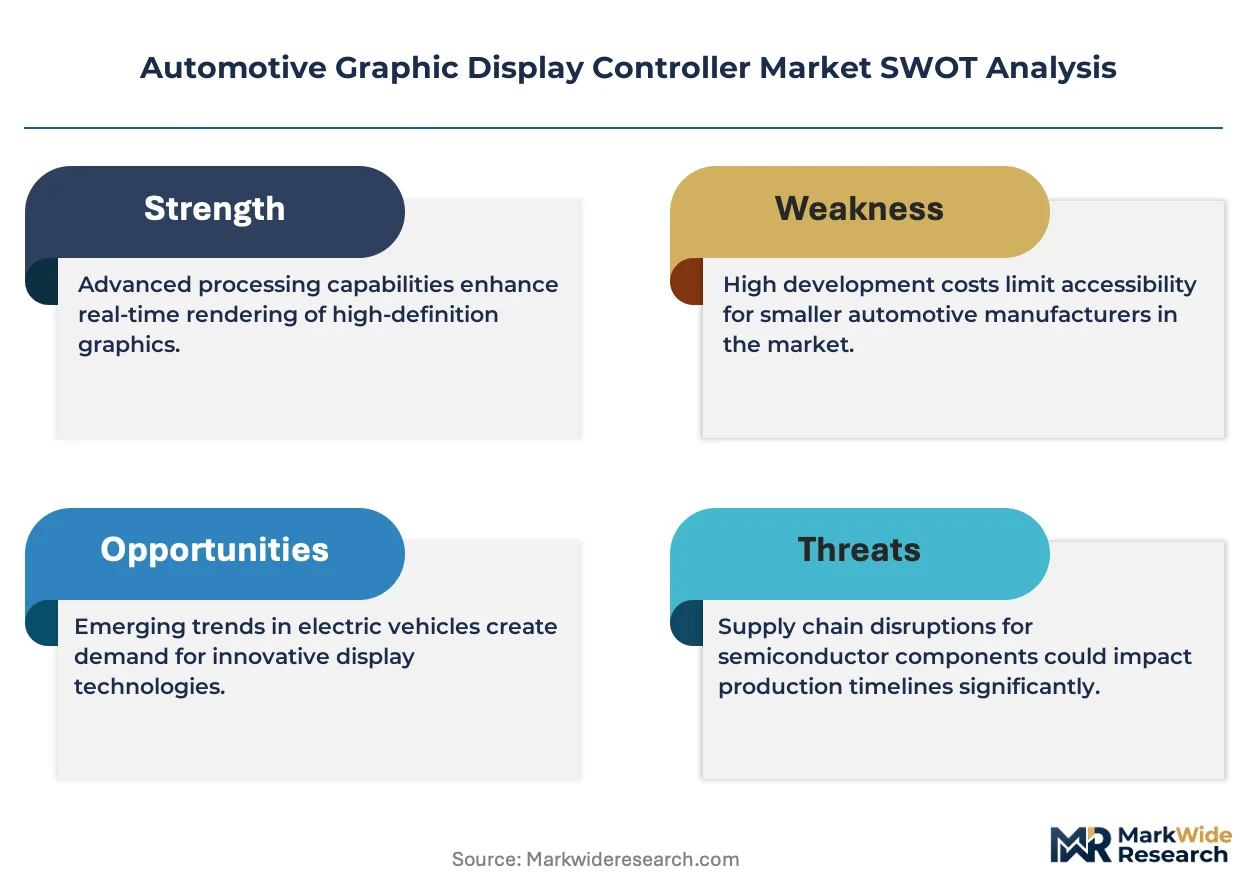
Asset-light foundry partnerships and fabless financing models are fragmenting competitive boundaries in automotive semiconductor supply. Texas Instruments sustains captive wafer capacity for high-reliability controller production. Renesas Electronics specializes in multi-domain integration for instrument cluster SoCs. Qualcomm dominates advanced infotainment graphics with its Snapdragon Digital Chassis platform.
An automotive graphic display controller is a dedicated semiconductor device that manages pixel rendering, frame buffering, and interface timing for vehicle displays, typically operating across temperature ranges from minus 40 to 85 degrees Celsius and supporting MIPI DSI or LVDS protocols for panel connectivity. Its primary purpose is to generate real-time visual output for safety-critical and comfort-oriented human-machine interfaces. TFT controllers anchor the largest installed base across instrument clusters and center-stack displays due to mature cost structures. OLED interfaces represent the fastest-growing segment in head-up display and premium infotainment applications where contrast ratio and form-factor flexibility command margin premiums. Embedded technology architectures are displacing analog controller designs in next-generation cockpit consolidation platforms.
NHTSA in the United States enforces distraction-minimization standards that dictate display response latency and animation complexity limits for in-vehicle screens. ECHA REACH restrictions and EU Green Deal material-compliance mandates are altering substrate and solder composition requirements for controller packaging. Stakeholders must monitor how cybersecurity certification requirements from UNECE WP.29 and regional homologation bodies reshape firmware validation costs and time-to-market thresholds for new controller designs.
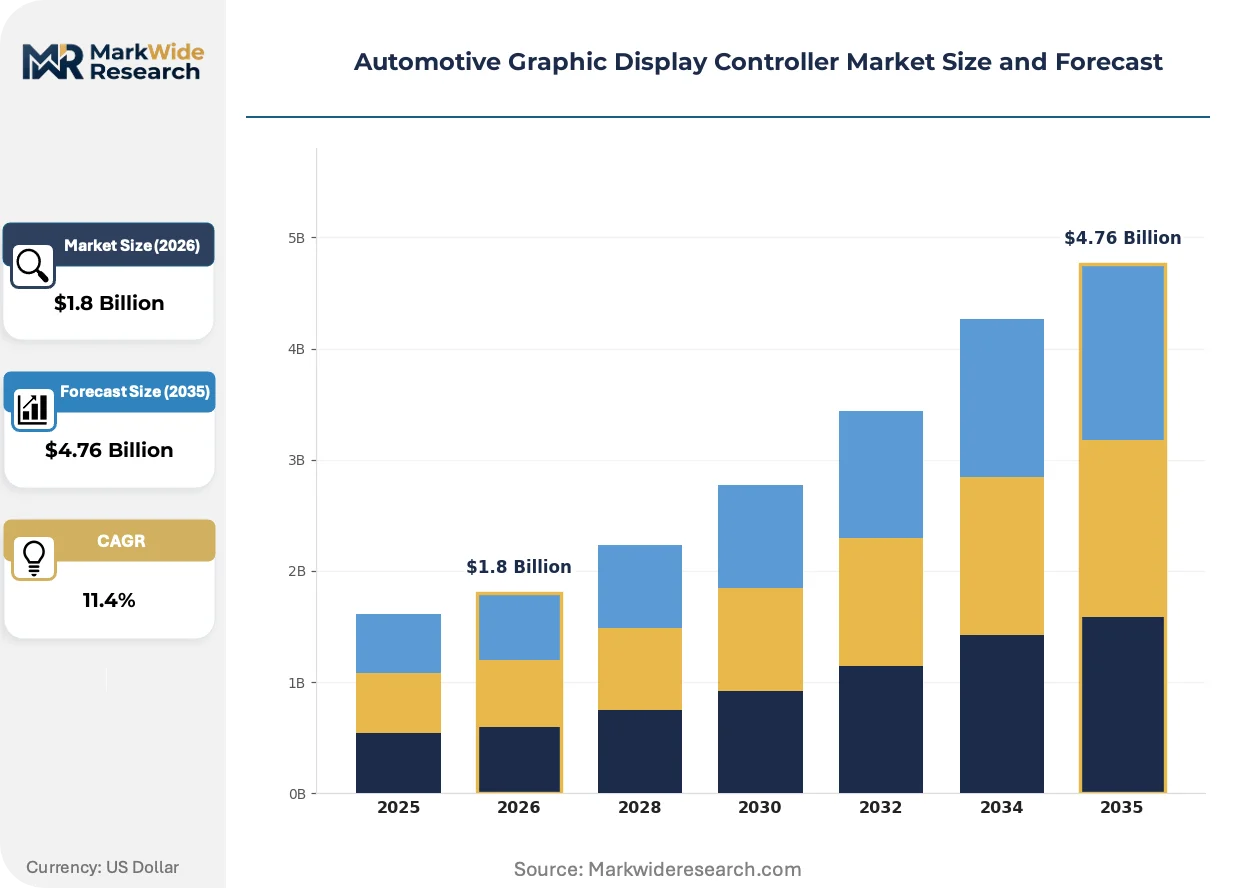
Market Dynamics
Cockpit consolidation architectures are compressing discrete controller BOMs into single-SoC platforms, forcing specialized display controller vendors to defend attach rates through firmware differentiation and functional safety certification stacking.
Growth Catalysts
- EU AI Act compliance mandates:Safety-critical HMI classification requirements are accelerating certified controller procurement for Level 2+ automated driving interfaces.
- Head-up display penetration:Windshield-projection systems in premium electric vehicle segments are pulling high-brightness OLED controller demand.
- MIPI DSI-2 protocol migration:Automakers in Germany and South Korea are specifying next-generation interface standards that obsolete legacy LVDS-based controller inventories.
Market Restraints
- 300mm wafer supply concentration:Taiwan-based foundry capacity allocation for automotive-grade silicon limits controller output expansion during demand spikes.
- ECHA REACH substrate restrictions:Lead-free solder and halogen-free laminate mandates are elevating packaging costs and qualifying new material sets.
- Functional safety certification friction:ISO 26262 ASIL-B/D validation timelines extend 18-24 months, freezing design wins for emerging suppliers.
Strategic Opportunities
- India domestic manufacturing incentives:PLI scheme subsidies for automotive electronics are attracting controller assembly and test investments.
- Rear-seat entertainment unbundling:Ride-hail fleet operators are specifying modular display controllers as standalone SKU purchases separate from OEM infotainment systems.
- Software-defined vehicle convergence:Hypervisor-ready controllers that partition safety-critical and comfort graphics are opening attach-rate expansion in consolidated cockpit domains.
Industry Challenges
- Functional safety firmware talent scarcity:ASIL-certified software engineering capacity constrains controller vendor R&D throughput.
- UNECE WP.29 cybersecurity homologation:Firmware validation documentation requirements are extending time-to-revenue for new controller releases.
- Legacy instrument cluster integration:Analog-to-digital display controller swaps in vehicle refresh programs face harness and mounting incompatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Graphic Display Controller Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, TFT, CRT Application: Infotainment Systems, Navigation Systems, Instrument Clusters, Head-Up Displays End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Analog, Digital, Mixed Signal, Embedded |
| Companies Covered | Texas Instruments, Renesas Electronics, Samsung Electronics Co., Ltd., LG Display Co., Ltd., Socionext Inc., NXP Semiconductors, Toshiba Corporation, Qualcomm Inc., Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Graphic Display Controller Market Emerging Trajectories
Real-time rendering pipelines and zone-based electronic architectures are dissolving the boundary between discrete display controllers and central compute silicon, compressing supplier business models toward firmware and certification services.
Local dimming controller IP is collapsing the hardware distinction between conventional TFT backlight drivers and per-pixel luminance management. Tier 1 suppliers in Germany are integrating these controllers directly into panel source boards for curved instrument clusters. This compression eliminates standalone controller margin pools and shifts value capture toward calibration software and thermal management firmware.
REACH substance restrictions are forcing laminate and underfill material substitutions that alter controller thermal cycling reliability. Packaging engineers must revalidate solder joint integrity across the minus 40 to 85 degrees Celsius automotive range using new halogen-free substrates. European OEMs are pushing these requirements upstream through JEDEC-style qualification mandates that extend supplier onboarding cycles.
Fleet procurement managers are unbundling display controller specifications from turnkey infotainment contracts, creating direct component sourcing channels. Commercial vehicle operators in the United States are issuing standalone RFQs for controller modules to secure second-source supply and accelerate repair turnaround. This disintermediation pressures traditional Tier 1 margins while opening volume contracts for qualified semiconductor vendors.
Automotive Graphic Display Controller Market Segmentation
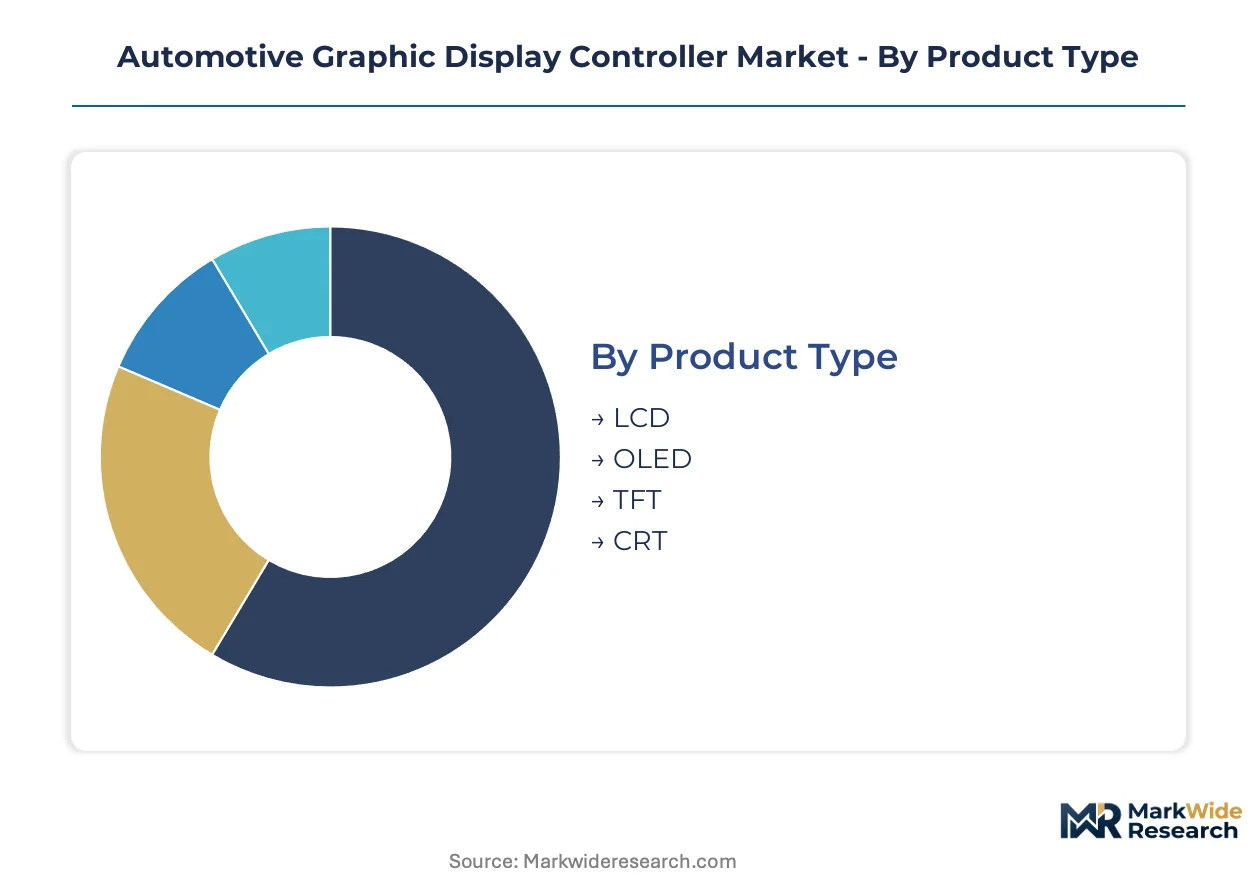
Segmentation reveals how controller architectures diverge across safety-critical and comfort-oriented applications. Each dimension exposes distinct procurement patterns, certification requirements, and margin structures that reshape vendor positioning.
Product Type:
After-sales service intensity varies sharply across display technologies, with OLED controllers requiring specialized calibration tools and TFT demanding higher field-replacement volumes.
- TFT:Thin-film transistor architectures dominate instrument clusters and center-stack displays through mature cost structures and established supply chains. German automakers specify these controllers for high-volume electric vehicle platforms where reliability data spans multiple model generations.
- OLED:Organic light-emitting diode controllers manage per-pixel luminance with microsecond response times essential for head-up display applications. South Korean panel manufacturers are pulling premium controller demand for curved cockpit implementations where contrast ratio commands specification premiums.
- LCD:Liquid crystal display controllers retain substantial installed base in commercial vehicle segments where backlight driver integration reduces discrete component counts.
- CRT:Cathode ray tube controllers persist in legacy military and specialty vehicle retrofit programs with minimal new design activity.
By volume, TFT leads. By growth pace, OLED is ahead.
Application:
Cost tier stratification separates safety-critical applications requiring ASIL certification from comfort systems with shorter validation cycles.
- Instrument Clusters:Safety-critical display controllers must meet ISO 26262 ASIL-B or ASIL-D ratings for speedometer and warning indicator rendering. United States-based electric vehicle OEMs are consolidating these controllers into single-SoC architectures with hypervisor partitioning.
- Head-Up Displays:Windshield-projection systems demand high-brightness controllers capable of 10,000+ candela-per-square-meter output for daylight visibility. German premium manufacturers specify these for Level 2+ automated driving interfaces where latency below 16 milliseconds is mandatory.
- Infotainment Systems:Center-stack controllers prioritize graphics throughput over functional safety, enabling faster procurement cycles and software-defined update paths.
- Navigation Systems:Map-rendering controllers balance GPS synchronization timing with 3D visualization pipelines in integrated cockpit domains.
Instrument clusters generate the highest certification revenue per unit. Head-up displays are expanding most quickly.
End User:
Customer type determines whether controllers ship as pre-qualified modules or require downstream integration and validation.
- OEMs:Original equipment manufacturers procure controllers through multi-year platform contracts with direct firmware customization rights. Electric vehicle specialists in the United States are bringing display controller specification in-house to accelerate cockpit software iteration cycles.
- Tier-1 Suppliers:System integrators aggregate controllers from semiconductor vendors into panel-source assemblies for German and South Korean automakers. These suppliers absorb certification costs and maintain buffer inventory against foundry allocation constraints.
- Aftermarket Providers:Independent distributors serve vehicle refresh programs and collision repair channels with legacy protocol controllers.
- Vehicle Assemblers:Contract manufacturers in India leverage PLI scheme subsidies to localize controller test and assembly operations for export markets.
Tier-1 suppliers move the highest unit volumes. OEM direct procurement is gaining share fastest.
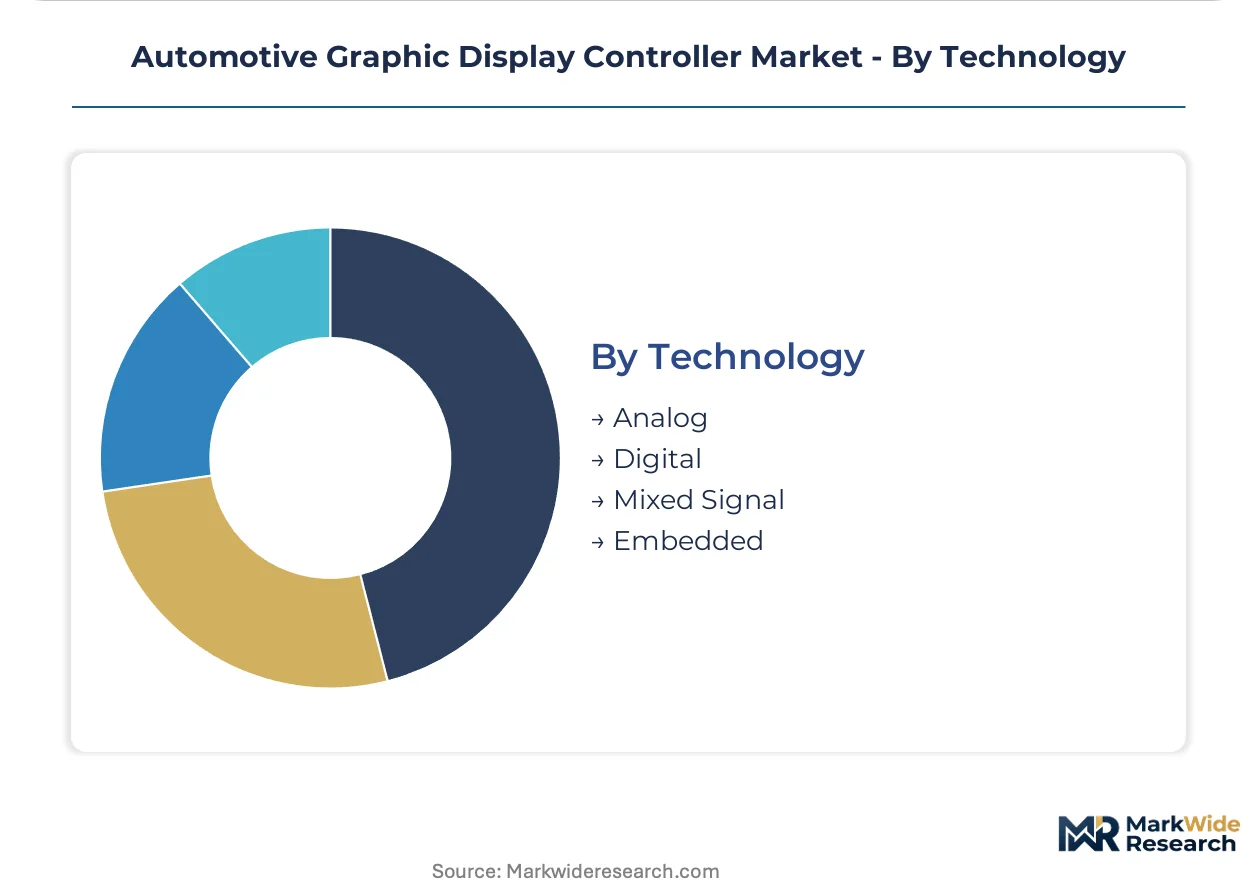
Technology:
Maturity curves separate legacy analog designs from embedded architectures enabling software-defined vehicle convergence.
- Embedded:System-on-chip controllers integrate CPU, GPU, and display pipeline on single die for consolidated cockpit platforms. Qualcomm and Renesas dominate this segment with hypervisor-ready solutions partitioning safety-critical and comfort graphics.
- Digital:Pure digital controllers handle MIPI DSI-2 protocol migration in next-generation German and South Korean vehicle programs.
- Mixed Signal:Hybrid architectures bridge analog sensor inputs with digital display outputs in transitional instrument cluster designs.
- Analog:Legacy voltage-controlled architectures persist in commercial vehicle segments with extended model lifecycles.
Embedded technology commands the steepest expansion trajectory. Analog is contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in automotive-grade display controllers favor manufacturing clusters with captive foundry access and stringent homologation regimes. Net exporters concentrate in East Asia and Western Europe, while import-dependent markets accelerate local assembly through subsidy programs.
Germany
Premium electric vehicle platforms from Munich and Stuttgart automakers pull MIPI DSI-2 certified controllers for curved instrument clusters. The KBA enforces UNECE WP.29 cybersecurity validation for all connected cockpit modules. Dresden's semiconductor corridor hosts back-end test facilities for automotive-grade silicon qualification.
South Korea
OLED panel manufacturers in Gyeonggi Province drive demand for high-brightness controllers in head-up display applications. The MFDS-aligned national standards body mandates electromagnetic compatibility certification for vehicle-integrated screens. Seoul's design houses specialize in hypervisor-ready SoC architectures for consolidated cockpits.
United States
Electric vehicle OEMs in California and Texas bring display controller specification in-house to accelerate software iteration cycles. NHTSA enforces distraction-minimization standards that cap display response latency for in-vehicle screens. Arizona's semiconductor packaging corridor qualifies lead-free solder alternatives under REACH-aligned customer mandates.
India
Commercial vehicle assemblers in Tamil Nadu and Maharashtra source controllers for fleet telematics and modular infotainment retrofits. The PLI scheme subsidizes automotive electronics test and assembly investments for export markets. Karnataka's electronics manufacturing clusters attract controller backend operations from East Asian vendors.
Japan
Instrument cluster SoC integration for heritage automakers sustains demand for ASIL-certified embedded controllers. METI coordinates domestic semiconductor resilience programs that prioritize automotive-grade silicon capacity. Nagoya's industrial corridor maintains legacy analog controller production for commercial vehicle segments with extended lifecycles.
Automotive Graphic Display Controller Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: captive foundry operators with in-house wafer capacity, fabless specialists licensing certified IP blocks, and diversified semiconductor conglomerates leveraging consumer electronics scale. Archetypes include functional safety certification leaders, MIPI protocol migration specialists, and hypervisor-ready platform integrators. Dominant competitive moves involve strategic partnerships for 300mm automotive wafer allocation and portfolio diversification into zone-based electronic architectures.
Within the diversified semiconductor tier, Texas Instruments and Renesas Electronics exemplify contrasting capacity strategies. Texas Instruments sustains captive wafer fabrication for high-reliability controller production. Renesas Electronics occupies a position specializing in multi-domain integration for instrument cluster SoCs. Qualcomm anchors the premium infotainment vector through its Snapdragon Digital Chassis platform architecture.
| Leading Market Players |
|---|
| Texas Instruments |
| Renesas Electronics |
| Samsung Electronics Co., Ltd. |
| LG Display Co., Ltd. |
| Socionext Inc. |
| NXP Semiconductors |
| Toshiba Corporation |
| Qualcomm Inc. |
| Seiko Epson Corporation |
| Others |
Supply Flow & Price Mechanics
300mm wafer foundry concentration in Taiwan anchors margin distribution across automotive-grade controller tiers, with captive capacity holders capturing premium pricing on ASIL-certified silicon while fabless vendors absorb volatility through contract structures. Tier 1 suppliers in Germany and South Korea translate foundry allocation scarcity into tiered procurement terms that stratify pricing by certification grade and volume commitment.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy controller tiers, with ASIL-D certification and hypervisor-ready firmware commanding substantial premiums over baseline TFT controllers. Price differentiation rests on ISO 26262 functional safety grade and MIPI DSI-2 protocol compliance, with German automakers showing lowest price sensitivity for safety-critical instrument cluster silicon. Cost compression in standard-tier TFT controllers is intensifying as South Korean panel manufacturers consolidate sourcing volumes. Aftermarket distributors exhibit highest price sensitivity due to inventory risk and shorter contract cycles.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant 300mm automotive wafer capacity, with back-end test and assembly concentrating in Malaysia, Vietnam, and Mexico. Raw material dependencies include high-purity silicon wafers, halogen-free laminate substrates, and lead-free solder alloys compliant with ECHA REACH mandates. Single-source vulnerability around Taiwan-based foundry allocation creates supply chain risk during demand spikes for electric vehicle platform ramps. Distribution runs through Tier 1 system integrators in Germany and South Korea who maintain buffer inventory against foundry allocation constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat, where ISO 26262 certification timelines and UNECE WP.29 cybersecurity validation create switching costs that freeze out unqualified competitors. Established vendors leverage accumulated functional safety firmware libraries to extend platform attach rates.
For Market Incumbents: Pre-empt emerging fabless competitors by locking multi-year wafer allocation contracts with Taiwan-based foundries before capacity constraints intensify. Accelerate hypervisor-ready controller roadmaps to capture cockpit consolidation attach-rate expansion. Defensive patent positioning around local dimming IP blocks emerging from Tier 1 panel integration in Germany. For New Entrants and Emerging Players: Pursue modular display controller white space in Indian commercial vehicle fleet telematics, where PLI scheme subsidies reduce capital barriers and domestic assembly requirements favor new supplier onboarding. Target rear-seat entertainment unbundling opportunities with ride-hail operators in the United States seeking standalone SKU procurement. Lead with software-defined vehicle hypervisor compatibility as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fabless controller specialists holding MIPI DSI-2 certified IP blocks but lacking foundry allocation security. Long-term viability over a 5-10 year window favors targets with accumulated ASIL-certified firmware libraries and established German OEM qualification status. Monitor Taiwan foundry capacity expansion announcements as inflection indicator for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Functional Safety Certification Stacking | ASIL-D validation for instrument cluster controllers locks in multi-platform design wins with German premium OEMs. |
| Hypervisor-Ready SoC Platform Investment | Qualcomm and Renesas hypervisor architectures partition safety-critical and comfort graphics in consolidated cockpits. |
| 300mm Automotive Wafer Allocation Lock | Texas Instruments captive fabrication secures high-reliability controller output independent of foundry spot markets. |
| MIPI DSI-2 Protocol Migration | German and South Korean automakers specify next-generation interface standards obsoleting legacy LVDS inventories. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Karnataka electronics clusters attract controller test and assembly for export market access. |
Methodological Framework
The analysis maps TFT, OLED, and LCD controller sub-sectors, each validated through Tier 1 supplier procurement leads, OEM platform engineers, semiconductor foundry planning officers, and aftermarket distribution channel managers. Primary interview intelligence triangulates against vehicle production databases, IHS Markit registration data, SEC semiconductor filings, and customs trade records. Bottom-up unit demand estimates reconcile with top-down OEM platform content assumptions across propulsion architectures and vehicle classes.
Assumptions held fixed include ECHA REACH material compliance mandates and UNECE WP.29 cybersecurity homologation timelines, while variables included electric vehicle adoption curves and cockpit consolidation penetration rates. Segmentation modeling spans display technology, application safety criticality, end-user procurement type, and embedded versus analog architecture maturity. CAGRs derive from fitted growth curves calibrated to OEM platform launch schedules and foundry capacity expansion announcements. Industry-specific inputs capture MIPI DSI-2 protocol migration velocity and ASIL certification backlog durations.
Sensitivities concentrate around Taiwan foundry allocation shocks, EU AI Act enforcement intensity on HMI classification, and fleet operator unbundling acceleration. Forecasts embed these assumptions without contingency scenarios for trade policy disruptions or raw material substitution failures. Quarterly review of foundry utilization rates, German KBA homologation queues, and Indian PLI scheme beneficiary announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive X-By-Wire System Market