
 Automotive LED Light Market | 2026-2036
Automotive LED Light Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive LED Light Market Outlook
Silicon carbide substrates is restructuring thermal management economics in high-power automotive LED modules, replacing traditional aluminum-based architectures in premium headlamp assemblies. Nichia Corporation leverages its vertical grip on gallium nitride epitaxy to sustain cost advantages in chip fabrication. HELLA GmbH & Co. KGaA anchors European supply relationships through specialized adaptive-beam calibration centers. Stanley Electric Co. Ltd. dominates Japanese OEM channels with precision optical design capabilities.
Automotive LED light denotes semiconductor-based solid-state illumination devices engineered from indium gallium nitride compounds, operating at forward voltages between 2.8 and 3.6 volts with luminous efficacy exceeding 120 lumens per watt, designed to replace incandescent and halogen sources in vehicle exterior and interior lighting functions. Matrix lighting configurations now command disproportionate engineering investment as OEMs pursue glare-free high-beam functionality without mechanical shutter mechanisms. Headlamp assemblies absorb the largest share of value across product categories due to complexity in thermal dissipation, optical precision, and regulatory homologation requirements. Electric vehicle applications within the application dimension represent the most dynamic demand vector, driven by battery-range sensitivity to electrical load optimization.
FDA oversight applies to photobiological safety testing for interior cabin LEDs, while NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance and beam pattern compliance for US-market vehicles. ECE Regulation 48 in Europe mandates automatic leveling and cleaning systems for high-intensity discharge and LED headlamps, directly shaping product architecture and cost structures. OEM procurement teams must weigh regional homologation divergence against platform standardization economics when specifying lighting system architectures for multi-market vehicle programs.
Market Dynamics
Silicon carbide thermal substrates are restructuring cost economics in premium headlamp modules, forcing aluminum-based architectures into lower-tier vehicle segments while OEMs recalibrate platform standardization strategies.
Growth Catalysts
- ECE Regulation 48:European mandates for automatic leveling and cleaning systems in LED headlamps are accelerating module complexity and supplier specialization across German and French OEM supply chains.
- Electric vehicle platforms:Battery-range sensitivity to electrical load optimization is pulling LED adoption into exterior and cabin illumination systems as standard equipment rather than premium option.
- Indium gallium nitride epitaxy:Advances in wafer-scale fabrication are compressing chip costs while maintaining luminous efficacy above 120 lumens per watt in volume production.
Market Restraints
- Homologation divergence:NHTSA Federal Motor Vehicle Safety Standard 108 beam-pattern requirements conflict with ECE photometric rules, fragmenting tooling investments for multi-market vehicle programs.
- Rare earth supply concentration:Gallium and indium refining capacity concentrates in Chinese processing facilities, exposing chip fabricators to input cost volatility and export control risk.
- Thermal management capex:High-power LED modules require precision-machined silicon carbide substrates and active cooling systems that inflate bill-of-material costs versus halogen alternatives.
Strategic Opportunities
- Matrix beam calibration services:Adaptive glare-free high-beam functionality without mechanical shutters is creating aftermarket and tier-one service revenue pools around optical alignment and software tuning.
- Interior photobiological safety testing:FDA oversight of cabin LED circadian impact is opening specialized certification and design-consulting niches for human-centric illumination engineering.
- Two-wheeler electrification:Scooter and motorcycle LED headlamp retrofits in India and Southeast Asia represent underpenetrated volume segments with lower regulatory barrier to entry.
Industry Challenges
- Optical design talent scarcity:Precision lens and reflector engineering for adaptive beam systems requires rare cross-training in illumination physics and CAD simulation, constraining supplier expansion.
- Legacy vehicle integration:Retrofitting LED modules into existing halogen electrical architectures without CAN-bus reprogramming creates warranty liability and dealer resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive LED Light Market |
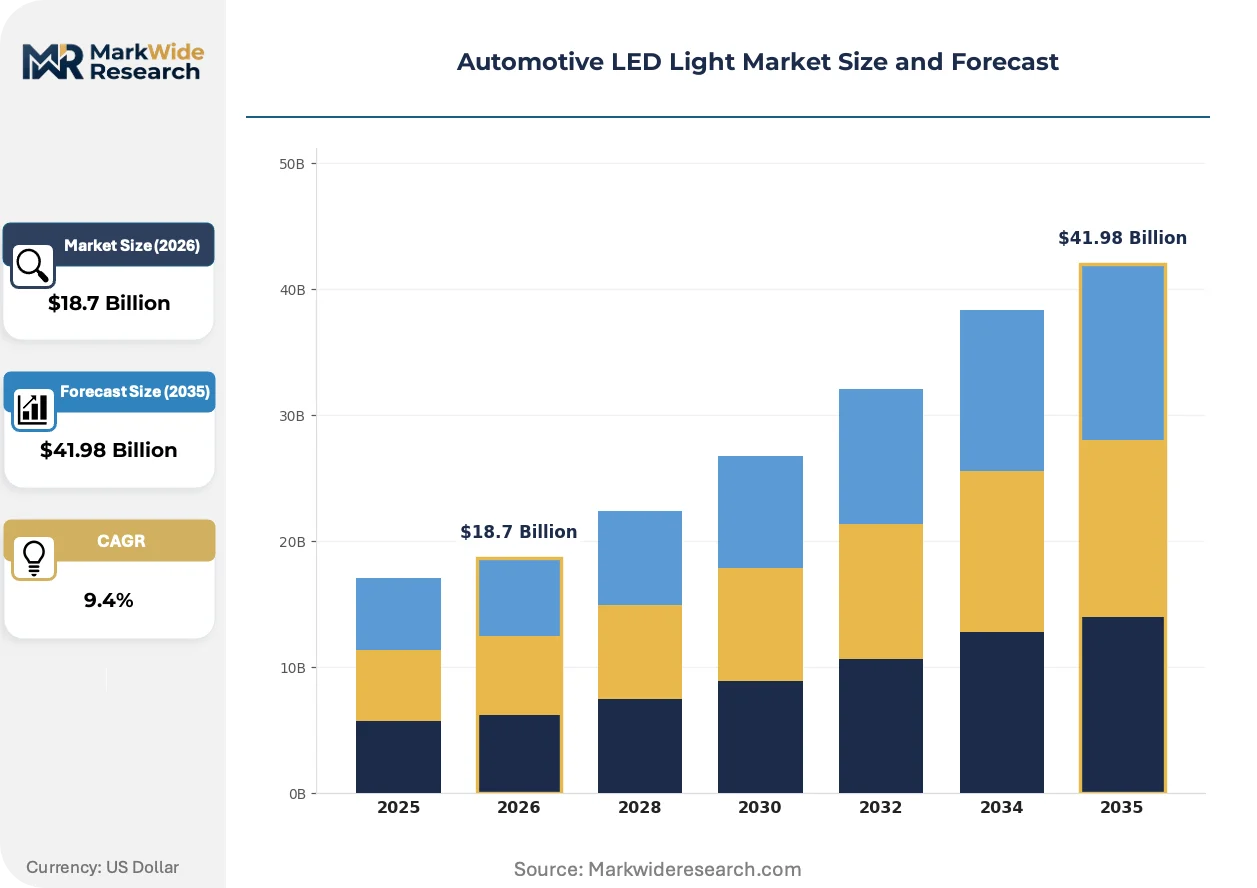
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlamps, Taillights, Fog Lights, Interior Lighting Technology: Smart Lighting, Adaptive Lighting, Matrix Lighting, Daytime Running Lights End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | Stanley Electric Co. Ltd., Valeo, HELLA GmbH & Co. KGaA, Hyundai Mobis Co. Ltd., ZKW Group, Koito Manufacturing Co. Ltd., Marelli Holdings Co. Ltd., Nichia Corporation, Osram GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive LED Light Market Strategic Shifts
Active matrix LED arrays are displacing static headlamp designs across premium and mass-market vehicle segments, reshaping competitive advantage around software-defined beam control rather than mechanical hardware.
Micro-LED pixel arrays are absorbing the engineering investment previously directed toward mechanical shutter mechanisms in adaptive driving beam systems. German and Japanese OEMs are adopting 10,000-plus pixel densities in flagship sedan launches. This technology is absorbing margin from traditional projector-lens suppliers while transferring value to semiconductor foundries and optical software developers.
China's GB standards for intelligent vehicle lighting are mandating communication between headlamp control units and autonomous driving sensor arrays. MIIT certification timelines now require functional safety documentation to ISO 26262 for matrix beam controllers. Domestic EV manufacturers are responding by insourcing lighting electronics development rather than relying on tier-one module suppliers.
Fleet procurement teams at ride-hailing operators are unbundling lighting system warranties from vehicle purchase contracts, negotiating separate service agreements with specialized aftermarket providers. This behavior compresses switching costs and accelerates replacement-cycle velocity in high-utilization vehicle pools. The pattern is most visible in California and Texas commercial EV deployments where total cost-per-mile metrics dominate supplier selection.
Automotive LED Light Market Segmentation
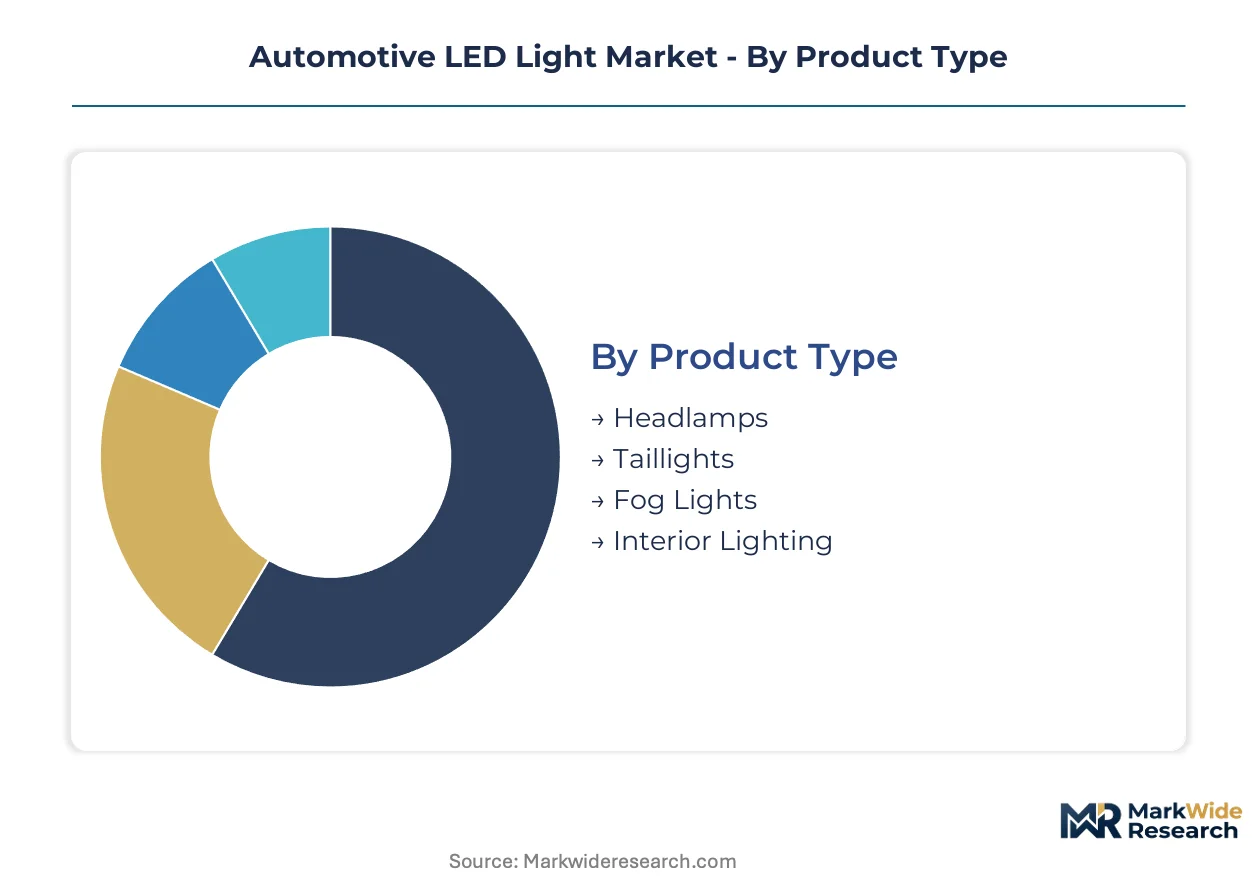
Automotive LED light segmentation reflects divergent technical requirements across exterior safety systems and cabin comfort functions. Procurement patterns vary sharply between OEM platform specifications and aftermarket retrofit channels. Each dimension carries distinct margin structures and regulatory compliance burdens.
Product Type:
Thermal management complexity and optical precision requirements separate high-value exterior assemblies from standardized interior modules.
- Headlamps:Silicon carbide substrates and active cooling systems dominate thermal architecture for high-lumen output. German OEMs mandate automatic leveling systems per ECE Regulation 48, inflating module cost versus halogen alternatives. Matrix beam configurations now absorb disproportionate engineering investment for glare-free functionality.
- Taillights:Sequential indicator designs and OLED-integrated signature lighting differentiate premium vehicle platforms. Chinese EV manufacturers deploy full-width light bars as brand recognition elements, compressing assembly cycles through modular LED strip integration.
- Fog Lights:Compact auxiliary modules with beam cutoff requirements for low-visibility conditions. NHTSA photometric testing governs US-market compliance for supplemental forward illumination.
- Interior Lighting:Circadian-tuned cabin illumination faces FDA photobiological safety oversight. Ambient lighting systems span 64-color programmable zones in luxury configurations.
Mature deployment sits with headlamps. Newer deployment is concentrated in interior lighting.
Technology:
Software-defined beam control is displacing mechanical hardware across premium and mass-market vehicle segments.
- Smart Lighting:Vehicle-to-infrastructure communication enables predictive beam adjustment based on navigation data. MIIT certification timelines in China require ISO 26262 functional safety documentation for intelligent controllers.
- Adaptive Lighting:Steering-angle sensors and yaw-rate inputs modulate beam direction during cornering. European OEMs embed camera-based predictive algorithms in flagship sedan platforms.
- Matrix Lighting:Micro-LED pixel arrays exceeding 10,000 elements enable selective dimming of oncoming traffic zones without mechanical shutters. Semiconductor foundries capture value previously directed to projector-lens suppliers.
- Daytime Running Lights:Mandated visibility systems with minimal thermal load requirements. Regulatory homologation spans ECE, NHTSA, and GB standards with divergent intensity specifications.
Established penetration centers on daytime running lights. Steepest expansion trajectory belongs to matrix lighting.
End User:
Procurement authority and warranty liability allocation determine channel economics across the supply chain.
- OEMs:Platform standardization strategies weigh regional homologation divergence against volume scale. German and Japanese manufacturers maintain captive lighting electronics development for flagship programs.
- Aftermarket Providers:Fleet procurement teams at ride-hailing operators unbundle lighting warranties from vehicle purchase contracts. California and Texas commercial EV deployments drive separate service agreement negotiation.
- Vehicle Assemblers:Final integration responsibility for headlamp aiming and beam pattern calibration. Assembly line tooling accommodates multiple regulatory variants for multi-market programs.
- Tier-1 Suppliers:Module-level responsibility for thermal management, optical design, and regulatory compliance. HELLA and Stanley Electric anchor European and Japanese supply relationships respectively.
Volume concentration rests with OEMs. Margin expansion is shifting toward tier-1 suppliers.
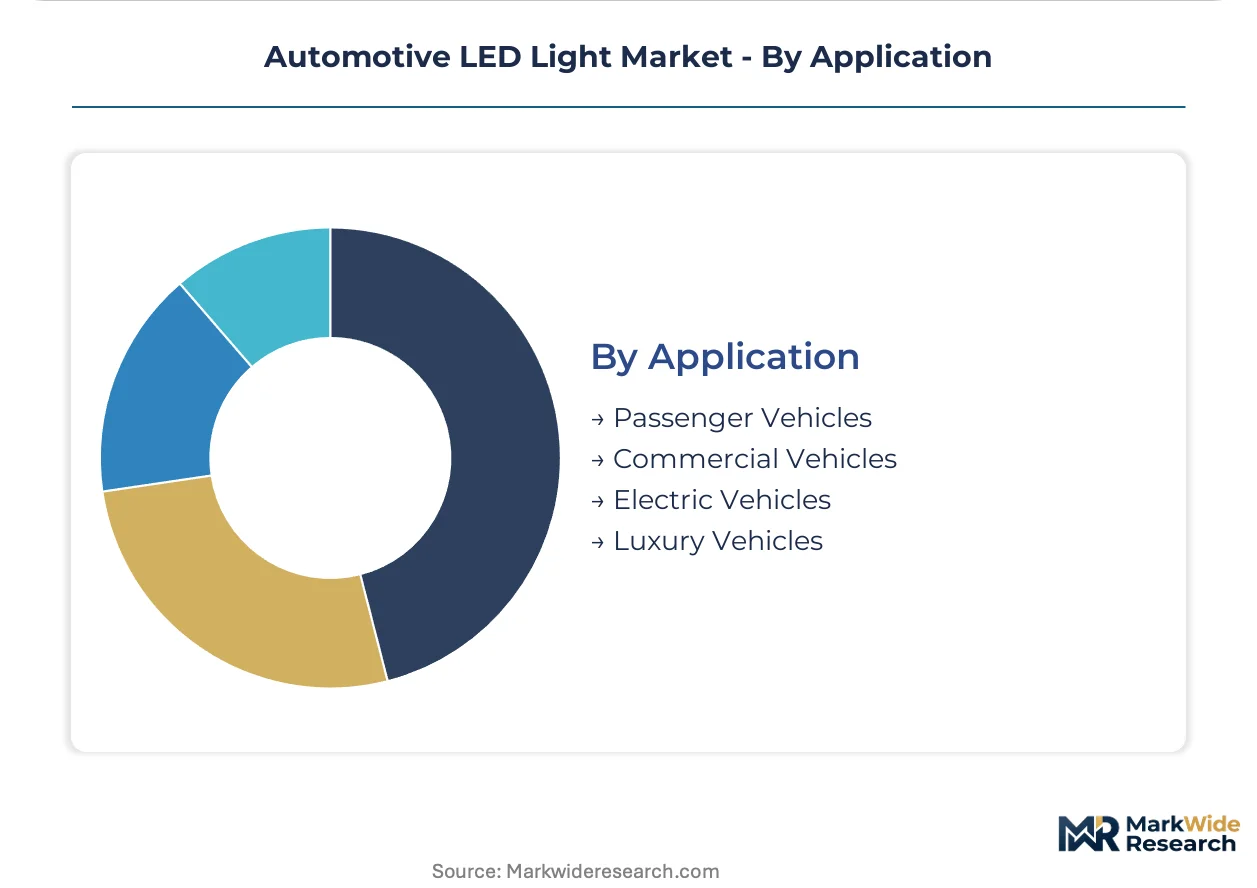
Application:
Battery-range sensitivity to electrical load optimization creates divergent LED adoption urgency across powertrain categories.
- Passenger Vehicles:Matrix headlamp penetration accelerates in premium segments while mass-market platforms retain projector architectures. European ECE regulations mandate automatic cleaning systems for LED headlamp-equipped vehicles.
- Commercial Vehicles:Durability requirements favor sealed LED modules over filament sources in heavy-duty cycles. Fleet operators prioritize total cost-per-mile metrics in lighting system specification.
- Electric Vehicles:Electrical load optimization pulls LED adoption into standard equipment status rather than premium option. Chinese domestic manufacturers insource lighting electronics development to protect battery range claims.
- Luxury Vehicles:Brand differentiation through programmable light signatures and interior ambient choreography. German OEMs deploy 10,000-plus pixel densities in flagship sedan launches.
Current installation density peaks in luxury vehicles. Gaining share fastest are electric vehicle applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive LED light demand concentrates in vehicle manufacturing clusters where regulatory mandates and electrification timelines intersect most aggressively. OEM procurement authority and tier-one supplier density determine regional competitive intensity.
Germany
Matrix headlamp adoption accelerates across BMW, Mercedes-Benz, and Audi flagship programs. ECE Regulation 48 mandates automatic leveling and cleaning systems, inflating module complexity for domestic suppliers. Stuttgart and Munich anchor adaptive-beam calibration centers serving European OEM supply chains.
China
Domestic EV manufacturers insource lighting electronics to protect battery-range claims in competitive segments. MIIT certification timelines require ISO 26262 functional safety documentation for intelligent controllers. Yangtze River Delta clusters around Shanghai and Suzhou concentrate module assembly capacity for BYD, NIO, and XPeng.
United States
Fleet operators in California and Texas unbundle lighting warranties from vehicle purchase contracts, accelerating aftermarket service velocity. NHTSA Federal Motor Vehicle Safety Standard 108 beam-pattern requirements conflict with ECE rules, fragmenting tooling for multi-market programs. Detroit maintains captive lighting electronics development for domestic OEM flagship trucks.
Japan
Precision optical design capabilities sustain tier-one relationships with Toyota, Honda, and Nissan. METI industrial policy supports gallium nitride epitaxy investments for domestic chip fabricators. Nagoya and Tokyo metropolitan areas concentrate headlamp assembly lines with integrated thermal management specialization.
South Korea
Hyundai Motor Group and Kia electrification platforms standardize LED exterior illumination to optimize electrical load. Domestic semiconductor foundries capture value from micro-LED pixel array sourcing previously directed to Japanese suppliers. Seoul Capital Area hosts module integration facilities serving both captive OEM demand and export programs.
Automotive LED Light Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium headlamp assemblies favoring captive tier-one relationships while standardized interior modules attract scale-driven fabricators. Market structure tilts toward consolidation in exterior safety systems and fragmentation in cabin comfort functions. Three archetypes dominate: vertically integrated chip-to-module specialists, optical design-led system integrators, and electronics-focused platform suppliers. Competitive moves center on backward integration into gallium nitride epitaxy and geographic expansion through adaptive-beam calibration service networks.
Among Japanese precision optical specialists, Stanley Electric Co. Ltd. and Koito Manufacturing Co. Ltd. occupy positions anchored in domestic OEM channel relationships. HELLA GmbH & Co. KGaA exemplifies the European system integrator archetype with specialized calibration infrastructure. Nichia Corporation represents vertical control over compound semiconductor fabrication, sustaining cost advantages in volume chip production.
| Leading Market Players |
|---|
| Stanley Electric Co. Ltd. |
| Valeo |
| HELLA GmbH & Co. KGaA |
| Hyundai Mobis Co. Ltd. |
| ZKW Group |
| Koito Manufacturing Co. Ltd. |
| Marelli Holdings Co. Ltd. |
| Nichia Corporation |
| Osram GmbH |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal compliance gates qualified supply and premium-tier pricing access, as carbon-border adjustments and conflict-mineral disclosure requirements filter out uncertified gallium nitride substrate suppliers from European OEM procurement lists. Tier-one module manufacturers with verified upstream traceability command price premiums of 15-25% over non-compliant competitors, while mass-market vehicle segments absorb cost compression from standardized aluminum-based thermal architectures.
Pricing Analysis
Volume concentration in daytime running lights and interior modules trades margin for scale, while headlamp assemblies retain pricing power through matrix beam complexity and ECE homologation barriers. Price differentiation rests on ISO 26262 functional safety certification and silicon carbide substrate integration, with premium tiers anchored by adaptive-beam calibration services. Cost compression in mass-market exterior lighting intensifies as Chinese EV manufacturers insource electronics development. Fleet procurement teams at commercial operators exhibit highest price sensitivity, while luxury OEMs prioritize optical performance over unit economics.
Supply Chain Analysis
China's domestic-content mandates under MIIT certification timelines are reshaping sourcing patterns, compelling foreign tier-one suppliers to localize gallium nitride epitaxy partnerships or surrender share to domestic integrators. Raw material dependencies center on gallium and indium refining capacity concentrated in Chinese processing facilities, silicon carbide substrates sourced from Japanese and American wafer manufacturers, and precision optical polymers from German specialty chemical producers. Single-source vulnerability in rare earth processing exposes chip fabricators to export control risk. Distribution runs through captive OEM supply chains in Germany and Japan, with modular assembly clusters concentrated in China's Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive LED lighting sits in a technology-transition phase where micro-LED pixel arrays displace mechanical shutter mechanisms, transferring value from optical hardware to semiconductor foundries and software developers.
For Market Incumbents: Anticipate margin erosion in projector-lens assemblies as micro-LED densities exceed 10,000 pixels, and respond by deepening backward integration into gallium nitride epitaxy or acquiring optical software calibration capabilities. ECE Regulation 48 mandates for automatic leveling systems threaten non-compliant suppliers with exclusion from German OEM platforms. Priority defensive lever: captive supply of silicon carbide thermal substrates to lock in premium headlamp module contracts. For New Entrants and Emerging Players: China's GB standards for intelligent vehicle lighting open a window for domestic electronics specialists to bypass tier-one incumbents by delivering ISO 26262-certified matrix beam controllers directly to BYD, NIO, and XPeng. Two-wheeler electrification in India and Southeast Asia represents the most penetrable white space, with lower regulatory barriers and unmet demand for LED headlamp retrofits. Go-to-market angle: fleet service agreements with ride-hailing operators unbundling lighting warranties from vehicle purchase contracts. For Investors and Strategic Acquirers: Domestic EV manufacturers insourcing lighting electronics development is the leading indicator that vertical integration pressure will consolidate tier-two module suppliers. Long-term viability favors specialists with compound semiconductor fabrication capabilities or precision optical design IP rather than assembly-only players. Acquisition target archetype: mid-tier calibration service providers with established relationships to German adaptive-beam certification centers. Signal to watch: MIIT certification timeline acceleration forcing foreign tier-one suppliers into joint venture structures with Chinese partners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gallium Nitride Epitaxy | Nichia Corporation's captive wafer production sustains cost advantages against fabless competitors in volume chip fabrication. |
| Matrix Beam Calibration Service Network Expansion | HELLA's Stuttgart and Munich centers anchor European OEM supply relationships through specialized adaptive-beam homologation support. |
| Domestic Content Partnership Structuring | Foreign tier-one suppliers forming joint ventures with Chinese wafer processors secure MIIT certification access for intelligent controller sales. |
| Silicon Carbide Substrate Manufacturing Scale-Up | Premium headlamp thermal management shifts from aluminum to SiC architectures, favoring suppliers with precision-machining capabilities. |
| Optical Software Development Investment | Semiconductor foundries and software developers capture value previously directed to mechanical shutter suppliers in adaptive driving beam systems. |
Study Parameters
SEC filings, ECE regulatory homologation databases, and vehicle production data from IHS Markit formed the secondary backbone, supplemented by customs records tracking gallium nitride substrate trade flows. Primary interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations heads validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation cross-checked segment-level projections against aggregate market sizing derived from regulatory filing analysis and production volume reconciliation.
Bottom-up modeling built forecasts from content-per-vehicle assumptions across passenger, commercial, electric, and luxury vehicle classes, while top-down approaches anchored on regulatory mandate timelines and OEM electrification commitments across the analysis window. Segmentation dimensions included product type, technology tier, end-user channel, and application category, with propulsion architecture and regional production cluster as cross-cutting variables. CAGRs derived from regression analysis of historical adoption curves adjusted for technology substitution rates and regulatory compliance deadlines.
The model assumes a particular technology adoption path; alternative pathways for micro-LED pixel density scaling or silicon carbide substrate cost reduction would alter the outlook for premium headlamp module penetration. Forecasts reflect assumptions about ECE and NHTSA regulatory convergence timelines, rare earth supply chain stability, and EV platform standardization strategies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Ethernet Switches Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market