
 Steering Wheel Armature Market | 2026-2036
Steering Wheel Armature Market Size, Share, and Industry Trends Forecast 2026-2036
Steering Wheel Armature Market Intelligence
The direct supply channel from specialized armature producers to automotive OEMs is narrowing as vehicle platform consolidation accelerates. This shift favors larger, integrated suppliers capable of handling high-volume contracts across multiple models. GSK InTek Co., Ltd. leverages its expertise in advanced materials to meet demand for lightweighting in electric vehicles. Nihon Plast Co., Ltd. sustains its market position through its established relationships as a broad interior systems provider. Lunt Manufacturing specializes in high-precision magnesium die-casting, a critical capability for complex, feature-rich armature designs.
A steering wheel armature is the internal structural frame of a steering wheel, providing rigidity and mounting points for the airbag module, electronic controls, and horn assembly. These components are typically manufactured using high-pressure die-casting of aluminum or magnesium alloys to achieve a high strength-to-weight ratio. Demand for composite materials is increasing for premium applications seeking further weight reduction. Collapsible armatures, which are designed to deform in a controlled manner during a frontal collision, represent the dominant product type, while fixed designs are relegated to specialty, off-highway, or aftermarket segments.
Regulatory frameworks are a primary influence on armature design and material selection. In the United States, the NHTSA's Federal Motor Vehicle Safety Standards (FMVSS) mandate specific performance criteria for occupant crash protection, directly impacting armature collapsibility. Similarly, components sold in Europe must comply with CE marking and vehicle type-approval standards that govern material integrity and safety performance. The key decision for manufacturers involves balancing the rising cost of lightweight materials and complex geometries with the stringent safety and functional requirements of next-generation vehicles.
Market Dynamics
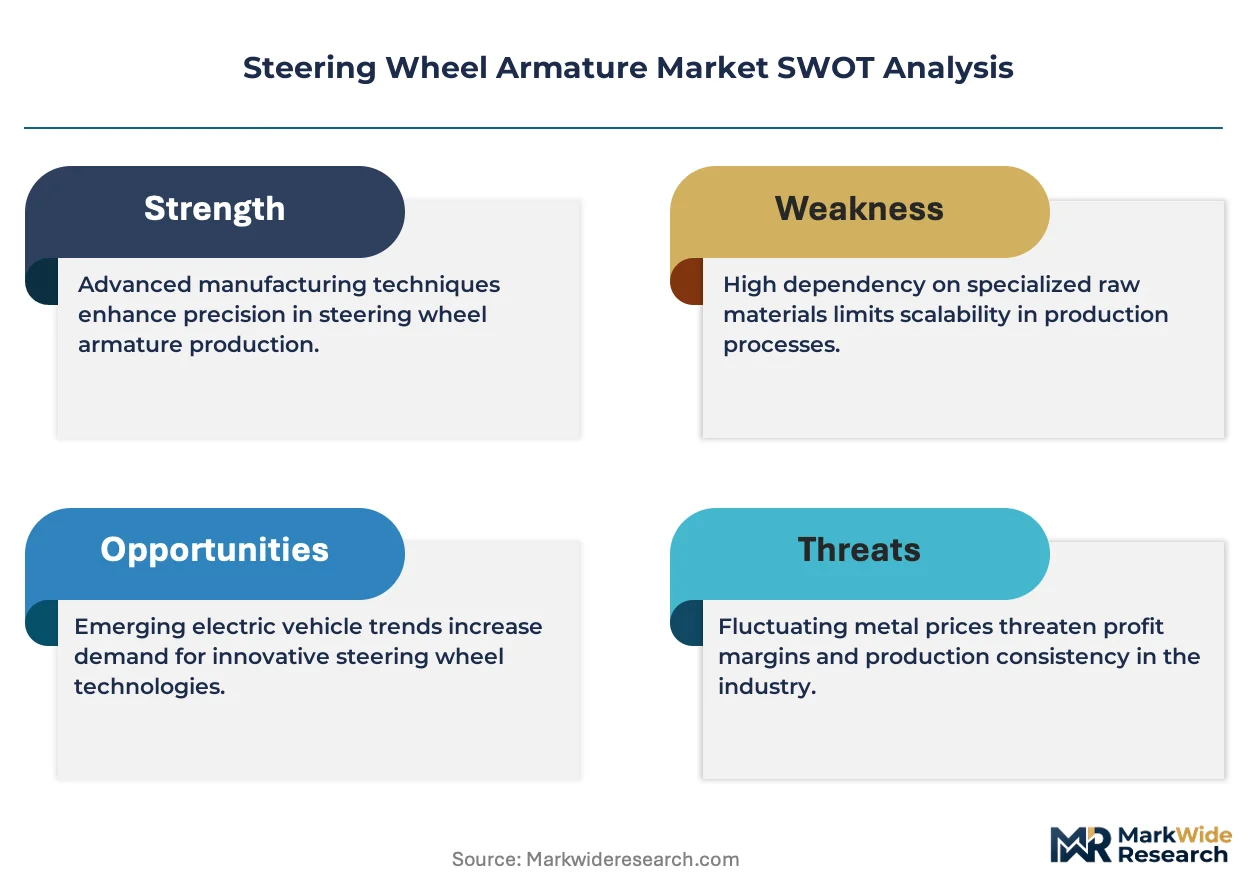
The central force shaping the steering wheel armature market is the dual pressure from electric vehicle lightweighting imperatives and the integration of ADAS functions. This combination demands a fundamental shift toward advanced materials and complex, feature-rich geometries for structural components.
Growth Catalysts
- Advanced Material Adoption:The push for weight reduction in electric vehicles to extend battery range drives the adoption of magnesium alloys and composite materials, which offer superior strength-to-weight ratios compared to traditional aluminum or steel.
- Stringent Safety Regulations:Mandates such as the NHTSA's Federal Motor Vehicle Safety Standards in the United States require specific crash performance, sustaining demand for sophisticated collapsible armature designs that absorb impact energy in a controlled manner.
- Automotive Production Volume:The sheer scale of vehicle manufacturing in hubs like China provides a massive, consistent demand base for armature suppliers, enabling economies of scale in high-pressure die-casting operations.
Market Restraints
- High Material Costs:The elevated price of lightweight materials, particularly magnesium alloys and carbon fiber composites, restricts their application primarily to premium vehicle segments, limiting widespread adoption in mass-market models.
- Specialized Manufacturing Processes:The market relies on a limited number of suppliers with the high-pressure die-casting expertise and equipment necessary for complex armature production, creating potential capacity bottlenecks.
- Design and Integration Complexity:Embedding sensors, heating elements, and haptic feedback systems directly into the armature structure increases engineering complexity, lengthens validation cycles, and elevates tooling costs for OEMs.
Strategic Opportunities
- Hybrid Material Armatures:Developing armatures that strategically combine metals like aluminum with composite inserts presents an opportunity to create a cost-effective lightweight solution for mid-range and mass-market electric vehicles.
- Aftermarket Customization:The performance and vehicle modification aftermarket represents a niche for high-margin, specialized armature designs, including those for smaller diameter or custom-finished steering wheels.
- Emerging Market Manufacturing:Establishing production or finishing facilities in burgeoning automotive regions like Southeast Asia allows suppliers to serve new OEM assembly plants locally, reducing logistics costs and lead times.
Industry Challenges
- Engineering Talent Scarcity:A shortage of engineers with dual expertise in mechanical design for die-casting and embedded electronics integration hinders the rapid development of next-generation smart armatures.
- Intensive Capital Investment:Upgrading foundries with larger tonnage die-casting machines and sophisticated CNC tooling to produce complex, thin-walled armatures requires significant capital expenditure.
- Prolonged Certification Cycles:Meeting the distinct performance, material, and safety specifications of multiple global OEMs, alongside regional standards like CE marking, extends product validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steering Wheel Armature Market |
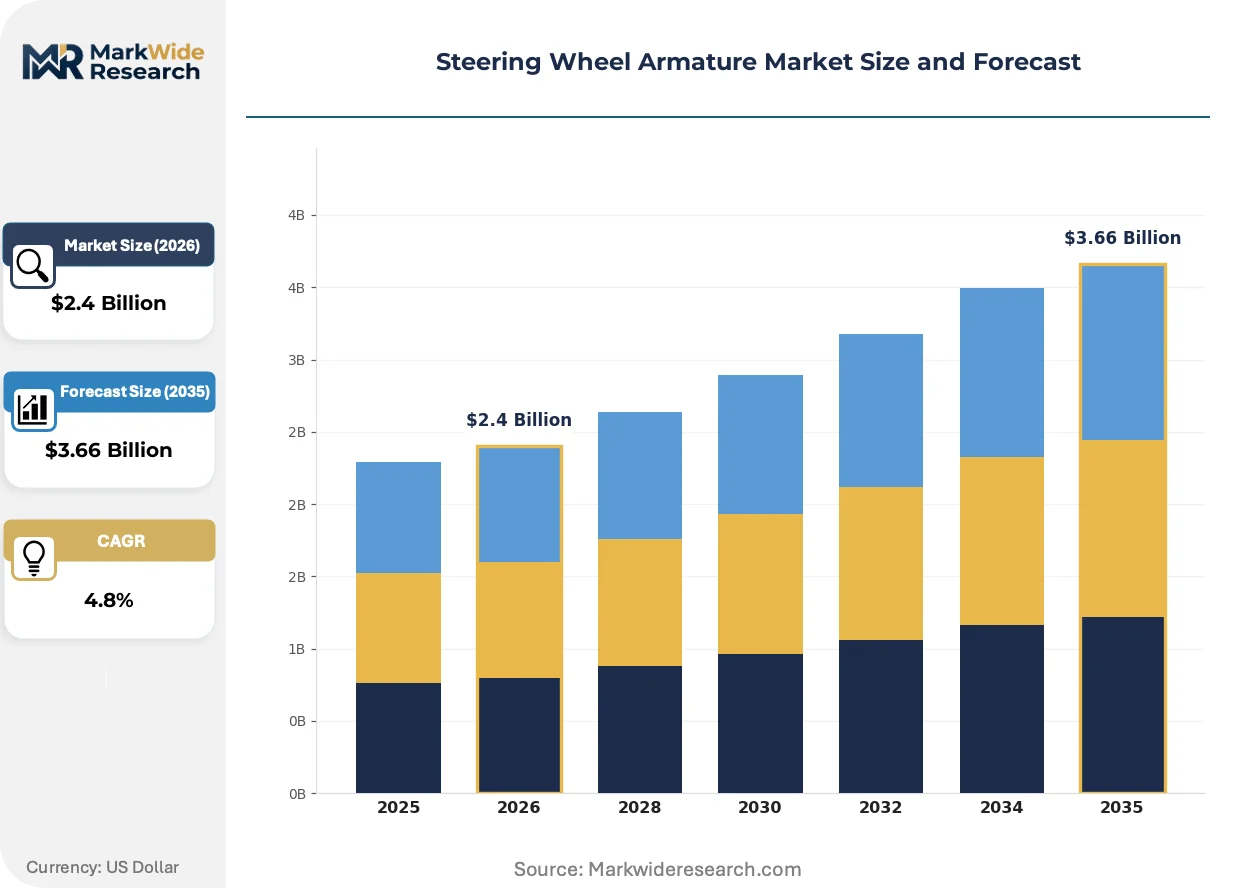
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collapsible, Non-Collapsible, Tilt, Fixed Material: Aluminum, Steel, Plastic, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Hydraulic, Electric, Pneumatic, Mechanical |
| Companies Covered | GSK InTek Co., Ltd., STARION CO., LTD, Getac Technology Corporation, Magpulse Technologies Pvt. Ltd., Summit Steering Wheel Co., Ltd., Tianjin Liuhe Magnesium Product Co., Ltd., ROS INDUSTRIE SRL, Lunt Manufacturing, Nihon Plast Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steering Wheel Armature Market Strategic Shifts & Innovations
Component evolution is redefining the armature's role within the vehicle cockpit. The shift is away from a simple structural frame toward a multi-functional chassis that supports advanced driver interaction and passive safety systems, integrating electronics and safety features directly.
Smart armatures incorporate integrated capacitive sensors, heating elements, and haptic actuators. Premium and electric vehicle OEMs are the primary adopters, using these features to enable sophisticated ADAS and driver monitoring functions. The core function of the armature is migrating from providing simple structural rigidity to acting as a central hub for human-machine interface controls.
European vehicle type-approval standards and the Corporate Sustainability Reporting Directive (CSRD) are directly influencing material selection. These regulations compel manufacturers to document material lifecycle impacts and ensure component integrity, favoring suppliers with strong process controls. The entire supply chain is impacted, but producers of aluminum and magnesium alloys face the most direct pressure to provide verifiable sustainability data.
Automotive OEMs are increasingly standardizing vehicle platforms to reduce development costs and streamline production. This model disrupts the traditional approach of sourcing unique armatures for every vehicle, favoring large suppliers capable of delivering configurable designs for high-volume, multi-model contracts. This platform consolidation is most visible among major global automakers based in North America and Europe.
Steering Wheel Armature Market Segmentation
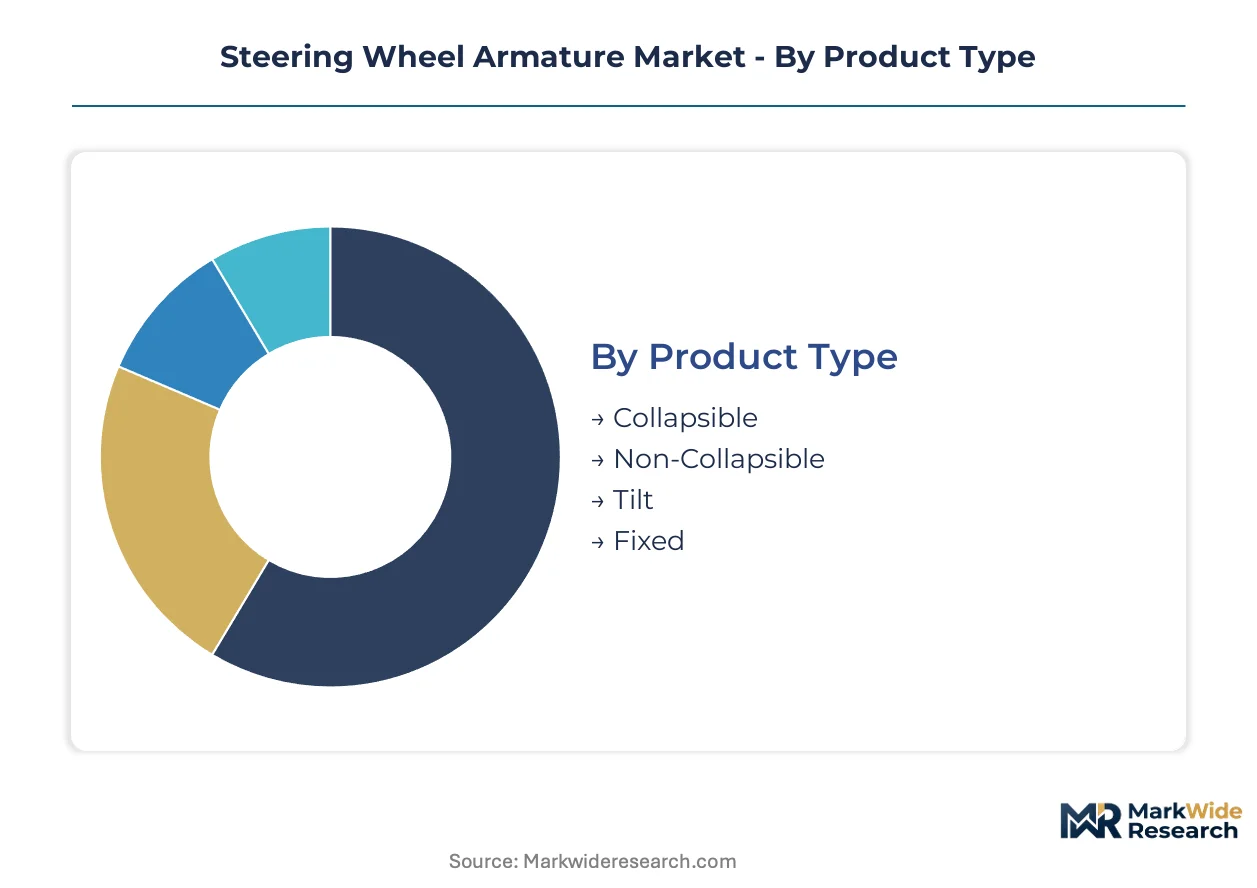
The steering wheel armature market exhibits distinct structural divisions influencing design, material choice, and manufacturing processes. These segments reflect diverse functional requirements and end-use applications across the automotive industry. Understanding these differentiators is critical for strategic market positioning.
Product Type:
The product type segmentation highlights the diverse functional requirements armatures fulfill across various vehicle applications, from standard passenger cars to specialized off-highway machinery.
- Collapsible:These armatures are engineered to deform in a controlled manner during frontal collisions, absorbing impact energy to enhance occupant safety. Demand concentrates in passenger vehicle OEMs globally, driven by stringent safety regulations like the NHTSA's FMVSS in the United States.
- Fixed:Fixed armatures provide rigid structural support without controlled deformation capabilities, primarily utilized in specialty vehicles, off-highway equipment, or certain aftermarket modifications. Demand for these designs often originates from industrial equipment manufacturers or niche vehicle builders.
- Non-Collapsible:This product type offers structural integrity without the controlled deformation mechanisms found in safety-critical passenger vehicle applications.
- Tilt:Tilt armatures incorporate mechanisms allowing the steering wheel angle to be adjusted, enhancing driver ergonomics and comfort across various vehicle platforms.
Established volume favors Collapsible armatures; emerging adoption favors Tilt designs for enhanced driver comfort.
Material:
Material composition and performance characteristics dictate the weight, strength, and cost profile of steering wheel armatures, significantly impacting vehicle efficiency and manufacturing complexity.
- Aluminum:Aluminum armatures are widely produced via high-pressure die-casting, offering a favorable strength-to-weight ratio for a broad range of automotive applications. Demand is strong across mainstream OEM vehicle platforms seeking a balance between performance and cost efficiency.
- Composite:These armatures utilize advanced materials like carbon fiber reinforced polymers to achieve superior weight reduction and structural rigidity for premium and electric vehicle applications. Demand for composite solutions is expanding most quickly in high-performance EV segments.
- Steel:Steel armatures provide robust structural support at a lower cost, often found in heavy-duty vehicles or older vehicle designs where weight is less critical.
- Plastic:Plastic armatures are typically employed in non-structural components or for specific interior trim applications, prioritizing cost efficiency and design flexibility.
Aluminum remains a high-volume material choice; composite materials are gaining share fastest for lightweighting initiatives.
End User:
End-user segmentation reflects the diverse procurement channels and integration points within the automotive supply chain, from direct manufacturing to aftermarket service providers.
- OEMs:Original Equipment Manufacturers directly integrate armatures into new vehicle production lines, demanding high-volume, custom-engineered components compliant with stringent safety and performance standards. Their procurement patterns are increasingly favoring large, integrated suppliers.
- Tier-1 Suppliers:These suppliers often act as intermediaries, procuring armatures from specialized producers and integrating them into larger steering system modules before supplying to OEMs. They manage complex supply chains and deliver integrated solutions.
- Aftermarket Providers:Aftermarket providers distribute replacement armatures or specialized upgrade components for vehicles already in service, catering to repair and customization needs.
- Vehicle Assemblers:Vehicle assemblers integrate pre-manufactured components, including steering wheel armatures, into the final vehicle structure, focusing on efficient assembly processes.
Demand originates primarily from OEMs and Tier-1 Suppliers, who collectively drive the bulk of armature procurement.
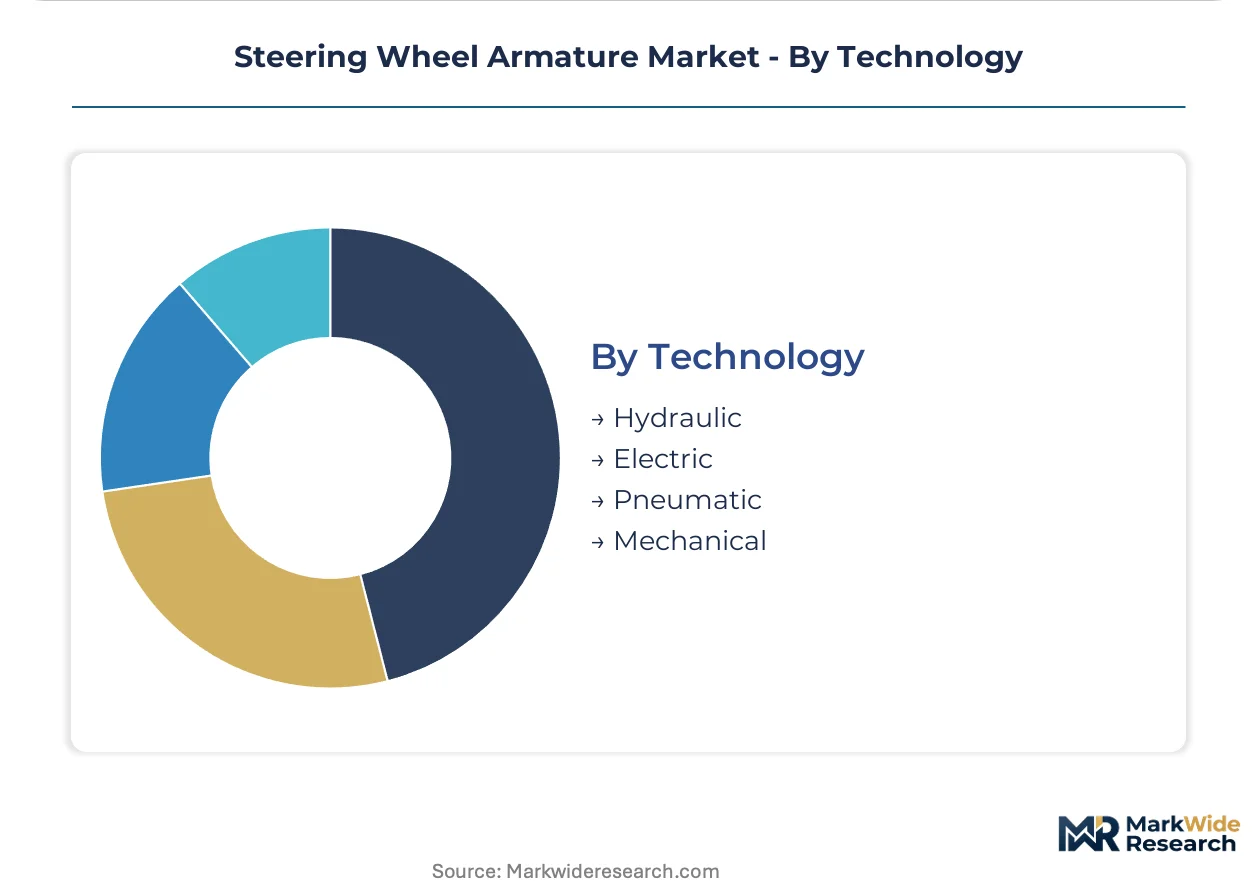
Technology:
Technology segmentation differentiates armatures based on their operational mechanisms, influencing steering feel, driver feedback, and integration with advanced vehicle systems.
- Electric:Electric armatures integrate with electronic power steering systems, enabling advanced driver-assistance features, haptic feedback, and precise control for modern vehicles. Demand for electric systems is concentrated in new vehicle platforms, especially electric vehicles.
- Mechanical:Mechanical armatures represent the foundational technology, providing direct physical connection and structural integrity without complex power assistance or electronic integration. These designs are common in simpler vehicles or specialized industrial applications.
- Hydraulic:Hydraulic armatures are part of hydraulic power steering systems, using fluid pressure to assist steering effort, primarily found in older vehicle models or heavy-duty applications.
- Pneumatic:Pneumatic technology in steering armatures is rare, typically limited to specific industrial or heavy machinery applications where compressed air systems are already present.
Modern vehicle designs increasingly adopt Electric technology; traditional applications still rely on Mechanical systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast network of high-speed rail and integrated port facilities underpins its dominant role in automotive manufacturing. This infrastructure supports large-scale production and efficient distribution of components like steering wheel armatures. Global automotive supply chains leverage these well-established logistics corridors for high-volume component sourcing.
China
China's automotive production volume, particularly for electric vehicles, drives substantial demand for steering wheel armatures. Components must comply with national GB standards that govern material integrity and safety performance. The Yangtze River Delta region, including cities like Shanghai and Suzhou, hosts a dense cluster of automotive component manufacturers and assembly plants.
Germany
Germany's automotive sector emphasizes premium vehicle production and advanced driver-assistance systems, requiring complex armature designs. Components sold in Europe must comply with CE marking and vehicle type-approval standards, ensuring safety and quality. Bavaria and Baden-Württemberg host significant automotive R&D centers and manufacturing plants, driving innovation in armature design and materials.
United States
The United States market demands armatures that meet stringent occupant crash protection requirements, particularly the NHTSA's Federal Motor Vehicle Safety Standards. Demand is fueled by a large domestic automotive production base and the ongoing transition to electric vehicles. Michigan, particularly the Detroit metropolitan area, remains a critical hub for automotive assembly and component suppliers, including armature producers.
Japan
Japan's export-oriented automotive industry and focus on advanced vehicle technologies create consistent demand for high-quality steering wheel armatures. Manufacturers adhere to JIS standards for material quality and production processes. The Chubu region, centered around Nagoya, is a major automotive manufacturing cluster, home to large OEMs and their extensive supplier networks.
India
India's growing domestic vehicle sales and government initiatives promoting local manufacturing, such as the PLI scheme, contribute to increasing armature demand. The country's expanding automotive sector requires armatures that balance cost-efficiency with functional requirements. Tamil Nadu, with its capital Chennai, serves as a significant automotive manufacturing hub, attracting both domestic and international component suppliers.
Steering Wheel Armature Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with specialized component manufacturers supplying larger integrated system providers. This configuration allows for both high-volume standardized production and niche advanced material development. Strategic archetypes include precision die-casters, composite material specialists, and broad interior system integrators. Capacity expansion and strategic partnerships remain dominant competitive moves across these segments.
Specialists in advanced materials and precision manufacturing anchor key segments of the market. GSK InTek Co., Ltd. exemplifies expertise in lightweighting solutions, crucial for electric vehicle applications, and leverages its material science capabilities. Lunt Manufacturing focuses on high-precision magnesium die-casting, supporting complex and feature-rich armature designs for next-generation vehicles. Nihon Plast Co., Ltd. represents established relationships as a broad interior systems provider, integrating armatures into larger cockpit assemblies and sustaining its market position through comprehensive offerings.
| Leading Market Players |
|---|
| GSK InTek Co., Ltd. |
| STARION CO., LTD |
| Getac Technology Corporation |
| Magpulse Technologies Pvt. Ltd. |
| Summit Steering Wheel Co., Ltd. |
| Tianjin Liuhe Magnesium Product Co., Ltd. |
| ROS INDUSTRIE SRL |
| Lunt Manufacturing |
| Nihon Plast Co., Ltd. |
| Others |
Cost & Logistics Intelligence
China's established logistics corridors, including its vast network of high-speed rail and integrated port facilities, directly influence cost dynamics for steering wheel armatures. This infrastructure supports high-volume manufacturing concentration, enabling economies of scale that impact downstream price differentiation across global automotive supply chains.
Pricing Analysis
Volume-discount tiering structures dominate armature procurement, particularly for large automotive OEMs and Tier-1 suppliers. Price differentiation stems from material choice, with composite armatures commanding a premium over aluminum, and compliance with stringent safety certifications like NHTSA's FMVSS. Pricing pressure intensifies due to OEM platform consolidation, which favors suppliers offering cost-effective, high-volume solutions. Mass-market vehicle segments exhibit the highest price sensitivity, while premium electric vehicle manufacturers prioritize performance and advanced features.
Supply Chain Analysis
Upstream feedstock for steering wheel armatures, primarily aluminum and magnesium alloys, draws heavily from global mining and refining operations, with significant processing concentrated in China, Germany, and Japan. The supply chain relies on specialized high-pressure die-casting expertise, creating potential capacity bottlenecks among a limited number of advanced manufacturers. Commodity price volatility for these lightweight metals presents a structural risk to supplier margins. Distribution runs through a tiered structure, from specialized component producers to integrated interior system providers, before reaching automotive assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steering wheel armature market is experiencing an early-cycle expansion, driven by the accelerating penetration of electric vehicles and the integration of advanced driver-assistance systems into cockpit designs.
For Market Incumbents:Insulate core market share by investing heavily in advanced die-casting machinery capable of producing complex, thin-walled designs. Focus R&D on hybrid material armatures to address the cost-performance balance required for mass-market electric vehicles. Deepen vertical integration into specialized material processing or embedded electronics to mitigate supply chain risks and counter OEM platform consolidation pressures. Maintain rigorous compliance with global safety standards like CE marking to protect established relationships.
For New Entrants and Emerging Players:Underpenetration in emerging automotive regions like Southeast Asia presents a strategic entry point for specialized armature manufacturers. Target the growing aftermarket customization segment with high-margin, specialized designs for smaller diameter or custom-finished steering wheels. A focused go-to-market strategy can involve offering cost-effective hybrid material solutions for mid-range electric vehicle platforms. Develop expertise in integrating specific haptic feedback or capacitive sensor technologies for niche applications.
For Investors and Strategic Acquirers:NHTSA's FMVSS and European type-approval standards reshape the acquisition landscape, favoring companies with proven safety compliance and advanced material expertise. The long-term viability of the armature market is anchored in the transition to software-defined vehicles and the need for multi-functional cockpit components. Target precision die-casters specializing in magnesium or composite material processing, or firms with strong embedded electronics integration capabilities. A key signal to watch is the volume and duration of long-term supply agreements secured by specialized armature producers with major global OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering costs for OEMs, driving demand for configurable armature designs across multiple vehicle models. |
| Advanced Material R&D | Enables superior lightweighting solutions, crucial for extending electric vehicle battery range and performance. |
| Die-Casting Capacity Expansion | Addresses potential supply bottlenecks for complex, high-volume armature production, ensuring market responsiveness. |
| ADAS Integration Expertise | Positions suppliers as essential partners for next-generation smart cockpits, embedding critical driver interaction features. |
| Localized Manufacturing Footprint | Reduces logistics costs and lead times for OEMs in burgeoning automotive production hubs like Southeast Asia. |
Research Approach
Initial hypotheses were tested against primary input from automotive OEM engineers, Tier-1 procurement managers, material scientists, and specialized die-casting specialists, and refined through iterative analysis. This involved extensive interviews with industry participants, complemented by secondary validation from vehicle production databases, regulatory filings with NHTSA and for CE marking, material science journals, and financial reports of key market players. A rigorous bottom-up and top-down triangulation approach ensured comprehensive data coverage.
The analytical framework employed an integrated demand-supply-balance model across the projection horizon. Segmentation dimensions modeled included product type, material, end-user, technology, and vehicle class (electric vehicle versus internal combustion engine). Compound annual growth rates were derived from historical trends and future projections, incorporating key industry-specific forecast inputs such as electric vehicle production forecasts and ADAS feature penetration rates.
Macroeconomic conditions sit as an overlay; deviation in global automotive sales or raw material commodity prices would shift the trajectory of the market. Forecasts reflect assumptions documented through expert consensus and quantitative modeling, acknowledging geopolitical shifts and rapid technological disruption as potential risk factors. Cross-checking against industry association production forecasts and OEM financial guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Tire Mold Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Small Engine Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Thailand Automotive Lubricants Market