
 Automotive Integrated Control Panel Market | 2026-2036
Automotive Integrated Control Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Integrated Control Panel Market Outlook
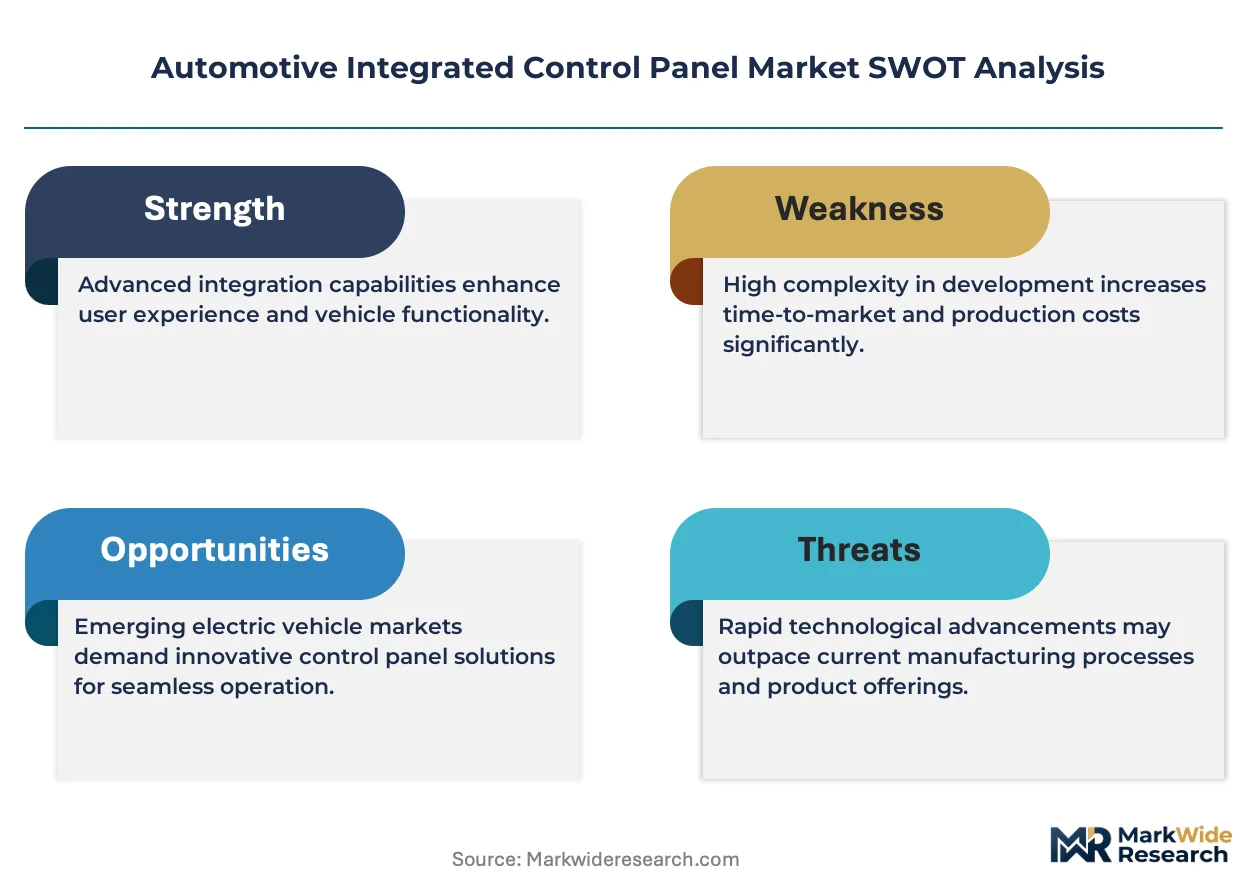
ISO 26262 functional safety certification is reorganizing supplier eligibility across the automotive integrated control panel value chain. Continental AG leverages captive semiconductor sourcing to sustain delivery commitments for safety-critical display modules. Robert Bosch GmbH anchors its position through R&D intensity in haptic feedback systems for premium cockpits. Denso Corporation specializes in thermal management integration for large-format curved panels bound for Asian OEM platforms.
An automotive integrated control panel is a centralized human-machine interface combining climate, infotainment, and vehicle dynamics controls into a unified electromechanical or fully electronic module, typically featuring capacitive touch layers bonded to TFT-LCD or OLED substrates with controller area network backbone communication. Its primary commercial purpose is reducing driver cognitive load while consolidating dozens of discrete switches into scalable, software-definable surfaces. Touchscreen panels now capture the dominant share of new program awards as OEMs eliminate physical knobs, while OLED technology segments command premium positioning due to contrast ratios and form-factor flexibility for curved dashboard architectures. Digital dashboards represent the fastest-growing application as full-digital instrument clusters merge with center-stack interfaces.
NHTSA guidelines on driver distraction in the United States, EU cybersecurity certification under UNECE R155, and China's MIIT connected-vehicle data security standards collectively reshape product specifications and market access requirements for integrated panel suppliers. These frameworks force redesign cycles for gaze-tracking integration, over-the-air update architectures, and localized data processing capabilities. Stakeholders must monitor evolving type-approval timelines across multiple jurisdictions to align platform development with regulatory enforcement waves.
Market Dynamics
Touchscreen consolidation is compressing electromechanical switch volumes while forcing Tier 1 suppliers to restructure manufacturing footprints around bonded display module capabilities.
Growth Catalysts
- UNECE R155 cybersecurity certification:European OEMs are accelerating procurement of connected cockpits with localized data processing architectures to meet type-approval deadlines.
- Haptic feedback integration:Premium EV platforms in Germany and China are specifying force-feedback layers to reduce driver gaze duration during climate adjustments.
- Curved OLED form factors:Dashboard designers are specifying flexible substrates that conform to swept interior surfaces previously impossible with flat TFT-LCD modules.
Market Restraints
- Indium tin oxide supply concentration:Capacitive touch layer production depends on refined indium supply chains centered in East Asian smelting operations.
- ISO 26262 ASIL-D certification costs:Functional safety validation for safety-critical display modules imposes multi-year development timelines and specialized engineering headcount.
- Physical knob retention in commercial vehicles:Fleet operators continue specifying tactile climate controls for glove-compatible operation, limiting full-touch penetration in heavy-duty segments.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Localized panel assembly for export-oriented compact car platforms can capture duty advantages and OEM nearshoring mandates.
- Over-the-air update architectures:Software-definable HMI surfaces enable recurring revenue streams through feature subscription models post-vehicle delivery.
- Photovoltaic-integrated roof displays:Transparent OLED layers bonded to glass roof modules create new information surfaces without additional dashboard cutlines.
Industry Challenges
- Automotive UI/UX talent scarcity:Human factors engineering for gaze-compliant interface design requires specialized skill sets concentrated in Stuttgart, Tokyo, and Silicon Valley labor pools.
- Legacy CAN-FD migration:Backward compatibility with existing vehicle network architectures complicates bandwidth scaling for high-resolution display streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Integrated Control Panel Market |
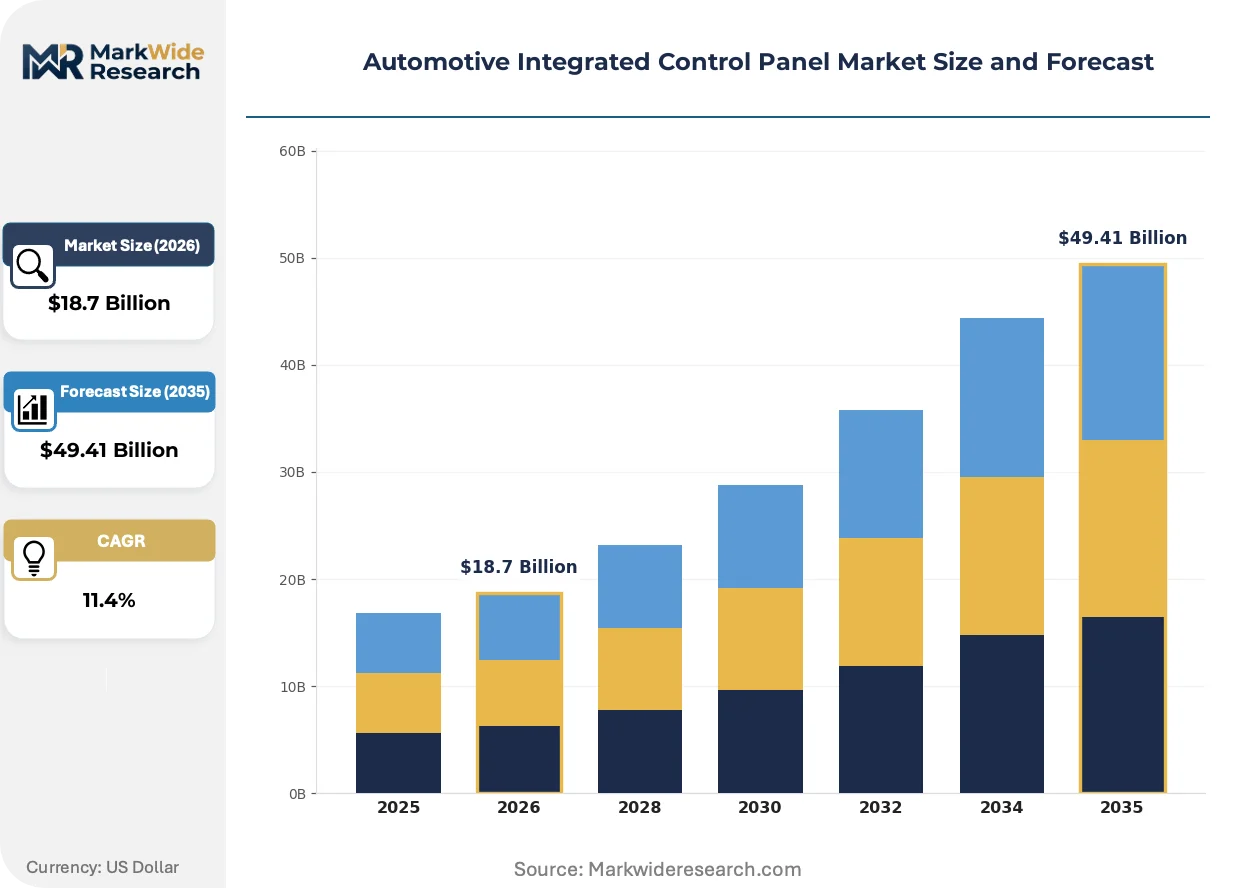
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Panels, Analog Panels, Digital Dashboards, Switch Panels Technology: LCD, LED, OLED, TFT End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Embedded Systems, Standalone Units, Modular Interfaces, Integrated Solutions |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Hyundai Mobis Co., Ltd., Faurecia SE, Valeo SA, ZF Friedrichshafen AG, Visteon Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Integrated Control Panel Market Strategic Shifts
Interface hardware is converging with software-defined vehicle architectures, creating new competitive battlegrounds around update velocity and ecosystem integration rather than static component specifications.
Micro-LED backlighting is fragmenting premium cockpit illumination strategies by enabling pixel-level dimming without the burn-in susceptibility of OLED emitters. Luxury German OEMs are specifying micro-LED arrays for instrument clusters with 10,000+ zone local dimming. This technology is fragmenting the incumbent OLED-TFT duopoly in high-contrast applications.
NHTSA distraction-reduction guidelines are forcing redesign cycles for gaze-tracking integration and touch-response latency thresholds in United States-bound vehicles. Tier 1 suppliers must validate that climate control adjustments complete within specified eye-off-road time budgets. Center-stack interface programs for North American OEM platforms are absorbing the largest compliance engineering headcount.
Subscription-enabled feature unlocking is altering how buyers interact with HMI capability tiers, replacing one-time hardware specification with post-purchase software activation. Premium German and Chinese OEMs are deploying heated-seat and massage controls behind paywall interfaces. This behavioral shift concentrates most visibly in connected-vehicle platforms with persistent cellular connectivity.
Automotive Integrated Control Panel Market Segmentation
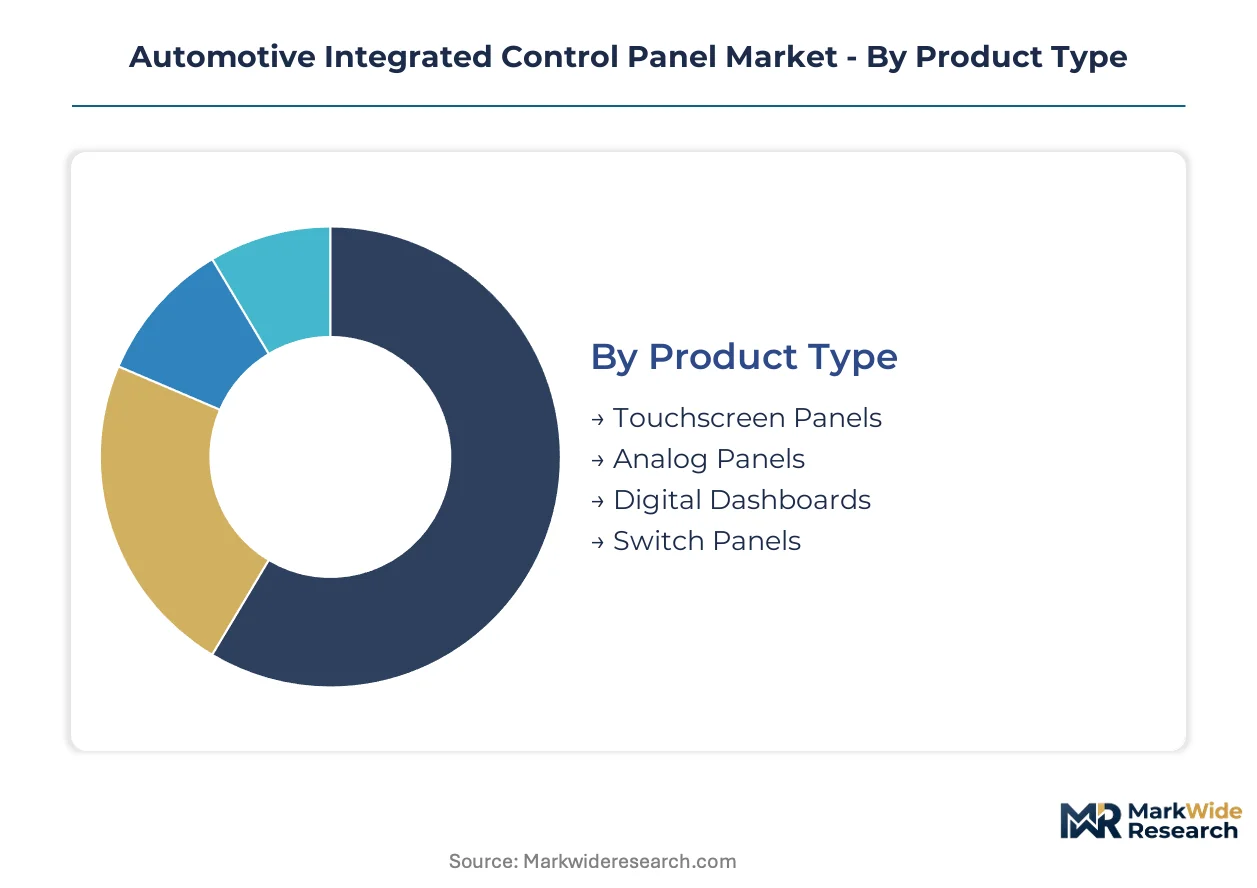
Segmentation in automotive integrated control panels reveals how technology migration, procurement hierarchy, and installation architecture reshape supplier economics. Understanding these divides exposes where margin concentrates and which specifications command premium positioning across diverging OEM programs.
Product Type:
Domestic assembly programs in Germany and Japan favor embedded touchscreen architectures, while export-oriented platforms in Mexico and Thailand retain analog and switch-based configurations for cost-sensitive variants.
- Touchscreen Panels:Capacitive touch layers bonded to TFT-LCD or OLED substrates consolidate climate, infotainment, and vehicle dynamics into software-definable surfaces. German luxury EV platforms specify haptic feedback layers to reduce driver gaze duration during secondary adjustments.
- Digital Dashboards:Full-digital instrument clusters merging with center-stack interfaces enable reconfigurable gauge layouts and over-the-air graphic updates. Asian OEM platforms in China and South Korea are expanding procurement of curved OLED variants for swept dashboard architectures.
- Analog Panels:Electromechanical gauge clusters with physical needles persist in commercial vehicle segments and emerging-market compact cars.
- Switch Panels:Discrete tactile controls for climate and lighting functions retain specification in heavy-duty fleet vehicles requiring glove-compatible operation.
Touchscreen panels command the established base. The steepest expansion runs through digital dashboards.
Technology:
Cost tiering separates premium OLED deployments from volume LCD programs, with LED and TFT occupying intermediate positions based on brightness requirements and burn-in tolerance.
- OLED:Self-emissive organic compounds enable infinite contrast ratios and flexible substrates conforming to curved interior surfaces. Luxury German OEMs specify micro-LED-backed OLED arrays for instrument clusters requiring 10,000+ zone local dimming without emitter degradation.
- LCD:Transmissive liquid crystal modules with LED edge-lighting dominate mid-range passenger vehicle programs. TFT-LCD variants with in-cell touch integration capture the largest volume share in compact and mid-size platforms across Japanese and American OEM portfolios.
- LED:Direct-lit LED backlights with local dimming zones bridge performance gaps for premium standard-tier vehicles.
- TFT:Thin-film transistor active-matrix addressing enables high refresh rates for animated instrument cluster graphics.
LCD retains volume leadership across cost-optimized platforms. OLED climbs the fastest as curved cockpit architectures proliferate.
End User:
Procurement authority concentrates with OEMs for safety-critical display modules, while Tier-1 suppliers and aftermarket channels fragment across non-certified replacement and upgrade segments.
- OEMs:Vehicle manufacturers specify integrated panel architectures during platform development, controlling software-defined HMI roadmaps and over-the-air update cadences. NHTSA distraction-reduction guidelines and UNECE R155 cybersecurity certification force direct OEM engagement with display module suppliers for type-approval compliance.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH manufacture bonded display modules under captive semiconductor sourcing arrangements to sustain delivery commitments for ASIL-D safety-critical programs.
- Aftermarket Providers:Retrofit touchscreen units for vehicle personalization operate outside functional safety certification requirements.
- Vehicle Assemblers:Contract manufacturing operations in India and Mexico integrate panels into CKD/SKD kits for localized final assembly.
OEMs command the established base. Aftermarket providers gain share fastest through subscription-enabled feature unlocking retrofits.
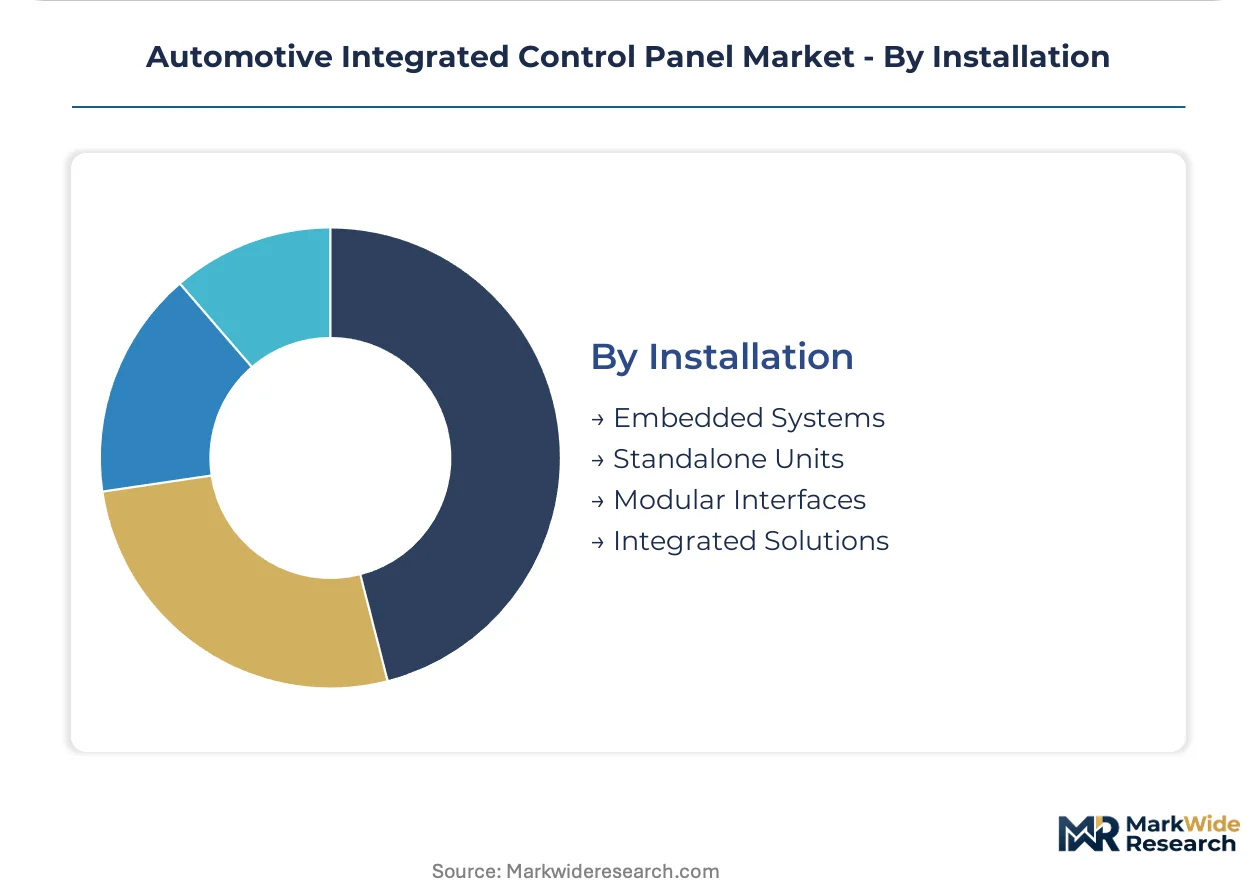
Installation:
Supply concentration favors embedded system architectures, while standalone and modular formats serve lower-volume specialty vehicle and aftermarket applications.
- Embedded Systems:Display modules fused into dashboard structural elements with shared controller area network backbone communication. Denso Corporation specializes in thermal management integration for large-format curved panels bound for Asian OEM platforms requiring sustained brightness in high-ambient conditions.
- Integrated Solutions:Unified electromechanical modules combining display, touch layer, and haptic actuator in single supplier responsibility. German premium EV platforms specify force-feedback integration to meet NHTSA gaze-tracking compliance thresholds.
- Standalone Units:Aftermarket head-unit replacements with proprietary mounting brackets and wiring harness adapters.
- Modular Interfaces:Swappable control surface elements enabling trim-level differentiation without full dashboard redesign.
Embedded systems command the established base. Integrated solutions expand most quickly as software-defined vehicle architectures consolidate supplier responsibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium OEM procurement authority concentrates in Germany, China, and the United States, with secondary demand clusters forming in Japan and South Korea as EV platform development accelerates.
Germany
Luxury electric vehicle platforms from BMW, Mercedes-Benz, and Audi drive haptic-enabled interface procurement. UNECE R155 cybersecurity certification mandates localized data processing architectures for connected cockpits. Stuttgart and Munich anchor supplier engineering clusters where Continental AG and Robert Bosch GmbH maintain captive semiconductor sourcing for ASIL-D safety-critical display modules.
China
Domestic EV brands BYD, NIO, and Xpeng expand curved OLED dashboard specifications for premium cockpit differentiation. MIIT connected-vehicle data security standards require localized data processing and over-the-air update compliance. Shanghai and Shenzhen house display module assembly operations serving both domestic OEMs and export-oriented joint ventures.
United States
General Motors, Ford, and Tesla integrate full-digital instrument clusters with center-stack touchscreens for light-duty truck and SUV platforms. NHTSA distraction-reduction guidelines enforce gaze-tracking integration and touch-response latency thresholds. Michigan and California concentrate Tier 1 supplier engineering operations for North American OEM compliance programs.
Japan
Toyota, Honda, and Nissan specify thermal-managed large-format panels for hybrid and battery-electric architectures. METI standards govern automotive electronics reliability and electromagnetic compatibility. Nagoya and Tokyo metropolitan areas host Denso Corporation's specialized operations for curved panel thermal integration bound for Asian OEM platforms.
South Korea
Hyundai Motor Group and Kia accelerate digital dashboard procurement for E-GMP platform derivatives. MFDS automotive electronics guidelines align with international functional safety benchmarks. Seoul and Ulsan concentrate display bonding operations where Hyundai Mobis Co., Ltd. coordinates captive supply chains for integrated cockpit modules.
Automotive Integrated Control Panel Market Competitive Environment
Player mix skews toward diversified Tier 1 automotive suppliers with captive electronics capabilities, creating a consolidated structure around safety-critical display module production. Continental AG, Robert Bosch GmbH, and Denso Corporation anchor the top tier through ASIL-D certification depth and semiconductor sourcing security. Three archetypes dominate: diversified Tier 1s with captive chip supply, specialized thermal management integrators, and Korean chaebol-affiliated component divisions. Competitive moves center on backward integration into semiconductor sourcing and geographic expansion into India's PLI-subsidized assembly corridors.
Within the diversified Tier 1 tier, Continental AG and Robert Bosch GmbH exemplify suppliers leveraging captive semiconductor arrangements to sustain delivery commitments for safety-critical programs. Denso Corporation occupies a position among thermal management specialists, anchoring curved panel integration for high-ambient Asian OEM applications. Hyundai Mobis Co., Ltd. represents the Korean chaebol-affiliated archetype, coordinating integrated cockpit module supply within the Hyundai Motor Group ecosystem.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Hyundai Mobis Co., Ltd. |
| Faurecia SE |
| Valeo SA |
| ZF Friedrichshafen AG |
| Visteon Corporation |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety day lead times for bonded display modules from East Asian foundries concentrate pricing power with semiconductor-integrated Tier 1 suppliers while forcing cost-plus indexation to indium and driver IC spot markets. Continental AG and Robert Bosch GmbH exploit captive chip sourcing to buffer OEM customers from volatility, whereas smaller integrators absorb margin compression when substrate costs spike.
Pricing Analysis
Cost-plus contracts with quarterly indexation to London Metal Exchange indium pricing and Taiwan Semiconductor Manufacturing spot rates dominate procurement arrangements between OEMs and Tier 1 suppliers. Price differentiation separates ASIL-D certified safety-critical modules from non-certified infotainment panels, with certification tier commanding substantial premiums. Cost compression in standard TFT-LCD programs is intensifying because Chinese panel makers are expanding bonded module capacity for domestic EV platforms. Fleet operators specifying physical knob retention in commercial vehicles exhibit highest price sensitivity, while German luxury OEMs purchasing curved OLED architectures demonstrate lowest sensitivity due to form-factor exclusivity requirements.
Supply Chain Analysis
Inventory cycles stretching eighty-five to one hundred twenty days for specialized driver ICs and touch controller semiconductors expose panel assemblers to demand-supply mismatches during OEM platform ramp-ups. Manufacturing concentrates in China, South Korea, and Japan for display glass and semiconductor fabrication, with Mexico and Thailand hosting final bonding operations for North American OEM programs. Raw material dependencies center on refined indium from Chinese smelters, polarizer films from Japanese chemical suppliers, and OLED emitter materials from German specialty chemical producers. Single-source vulnerability for 12-inch wafer capacity at leading foundries represents the dominant structural risk. Distribution runs through OEM-directed Tier 1 supply agreements rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with software-defined vehicle architectures fragmenting incumbent supplier relationships and creating entry points for specialized haptic and thermal management integrators. Subscription-enabled feature unlocking is redistributing value capture toward post-sale software providers.
For Market Incumbents: Compound defensive positioning through backward integration into driver IC design partnerships and captive OLED emitter material sourcing. Threat from Chinese display panel makers expanding bonded module capabilities for domestic EV platforms demands counter-moves. Priority lever rests with ASIL-D certification depth that new entrants cannot replicate within development cycle windows. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized automotive electronics corridors where localized assembly captures duty advantages for export-oriented compact car platforms. Most penetrable segment is thermal management integration for large-format curved panels serving Asian OEM high-ambient specifications. Go-to-market angle emphasizes software-definable HMI surfaces with over-the-air update architectures enabling recurring revenue streams. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because captive semiconductor sourcing and functional safety certification depth create durable moats around display module supply. Acquisition target archetype includes thermal management specialists with curved panel integration capabilities and existing Asian OEM relationships. Signal to watch is MIIT data security standard enforcement accelerating localized data processing architecture mandates in China.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Sourcing | Secures driver IC supply continuity for ASIL-D programs against foundry allocation volatility. |
| Haptic Feedback Integration | Addresses NHTSA gaze-tracking compliance thresholds for premium German EV platforms. |
| Curved OLED Thermal Management | Enables sustained brightness in high-ambient Asian OEM cockpit specifications. |
| Software-Defined Vehicle Investment | Positions suppliers for subscription-enabled feature unlocking revenue streams. |
| India PLI Corridor Expansion | Captures duty advantages and nearshoring mandates for export-oriented compact car platforms. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, thermal management specialists, and aftermarket distributors and refined through secondary validation. Regulatory filings from NHTSA, UNECE, and China's MIIT provided compliance timeline benchmarks. Vehicle production databases, IHS Markit registration data, and customs records supplied volume triangulation. Bottom-up segment builds and top-down macro constraint checks converged on market sizing.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster shaped the analytical framework. CAGRs derived from segment-level unit economics and technology migration curves. Forecast inputs included curved OLED penetration rates in premium cockpits and haptic feedback adoption timelines tied to NHTSA guideline enforcement waves. Outputs reflect modeled trajectories across the projection horizon without claiming precision to specific periods.
Material uncertainties — indium supply disruptions, ASIL-D certification timeline extensions, and cybersecurity standard enforcement delays — sit outside the modeled envelope. Forecasts reflect assumptions about technology cost curves and regulatory adherence schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive 48V System Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market