
 Middle East and Africa Automotive LED Lighting Market | 2026-2036
Middle East and Africa Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Automotive LED Lighting Market Insights
Fleet operators and premium SUV buyers is reorganizing demand patterns across the Middle East and Africa Automotive LED Lighting Market. OSRAM GmbH anchors its position through captive chip sourcing and backward integration into epitaxy operations. HELLA GmbH & Co. KGaA (FORVIA) differentiates via modular headlamp platforms that reduce OEM tooling costs across multiple vehicle architectures. HYUNDAI MOBIS competes by leveraging its captive supply relationship with Hyundai-Kia assembly plants in the region.
The Middle East and Africa Automotive LED Lighting comprises solid-state semiconductor devices emitting visible light through electroluminescence in gallium nitride junctions, typically operating at 2-3 volts DC with luminous efficacy exceeding 100 lumens per watt, engineered for exterior and interior vehicular illumination. These devices replace incandescent and halogen sources to reduce power draw, extend service life beyond 15,000 hours, and enable precise beam pattern control for safety compliance. Headlights and adaptive LED configurations capture the dominant share of OEM value pools as luxury and safety specifications tighten across SUV and sedan platforms. The aftermarket channel sustains higher volume throughput for tail lights and fog lights, where replacement frequency and price sensitivity favor standardized LED modules over smart or RGB variants.
South Africa's National Regulator for Compulsory Specifications enforces SABS automotive lighting standards that align with UN ECE regulations, while the UAE's Emirates Authority for Standardization and Metrology mandates ESMA certification for LED headlamp assemblies sold through regional distribution hubs. Saudi Arabia's Saudi Standards, Metrology and Quality Organization (SASO) implements energy-efficiency labeling that directly shapes product qualification for OEM tenders and government fleet contracts. Stakeholders must monitor divergence between Gulf Cooperation Council harmonization timelines and South Africa's alignment with European type-approval frameworks when configuring regional product portfolios and compliance investments.
Market Dynamics
Fleet operators across Saudi Arabia and the UAE are accelerating LED retrofits as national energy-efficiency mandates tighten, compressing replacement cycles and reshaping supplier relationships across commercial logistics corridors.
Growth Catalysts
- SASO energy-efficiency labeling:Saudi Arabia's mandatory labeling scheme for LED headlamp assemblies directly shapes product qualification for government fleet tenders, forcing OEMs to prioritize certified suppliers.
- Adaptive beam technology:Smart LED configurations with dynamic range adjustment are capturing premium SUV assemblies as safety specifications tighten across GCC markets.
- Commercial logistics corridors:Long-haul freight operators from Dubai to Jeddah are retrofitting entire fleets to reduce fuel draw and maintenance downtime.
Market Restraints
- Epitaxy wafer supply concentration:Captive chip sourcing from East Asian foundries creates vulnerability for regional assemblers lacking backward integration into gallium nitride substrate production.
- UN ECE alignment gaps:South Africa's SABS standards maintain partial divergence from Gulf Cooperation Council harmonization timelines, forcing dual certification investments.
- Halogen residual stock:Aftermarket channels in price-sensitive segments continue pushing discounted conventional inventory, delaying LED penetration in entry-level vehicle pools.
Strategic Opportunities
- RGB interior ambient systems:Untapped demand for programmable cabin lighting in luxury electric vehicle platforms offers margin expansion beyond functional exterior applications.
- ESMA certification acceleration:The UAE's streamlined approval pathways for smart headlamp assemblies create first-mover advantage for suppliers pre-qualifying modular platforms.
- Connected lighting infrastructure:Vehicle-to-infrastructure communication protocols are converging with adaptive LED controls to enable predictive beam adjustment on smart highway corridors.
Industry Challenges
- Optical engineering talent scarcity:Regional universities produce limited graduates in photonics and thermal management, forcing suppliers to import specialized workforce or delay R&D timelines.
- Dual-homologation complexity:OEMs serving both South African and GCC markets must maintain parallel testing protocols for ESMA and SABS certifications, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Automotive LED Lighting Market |
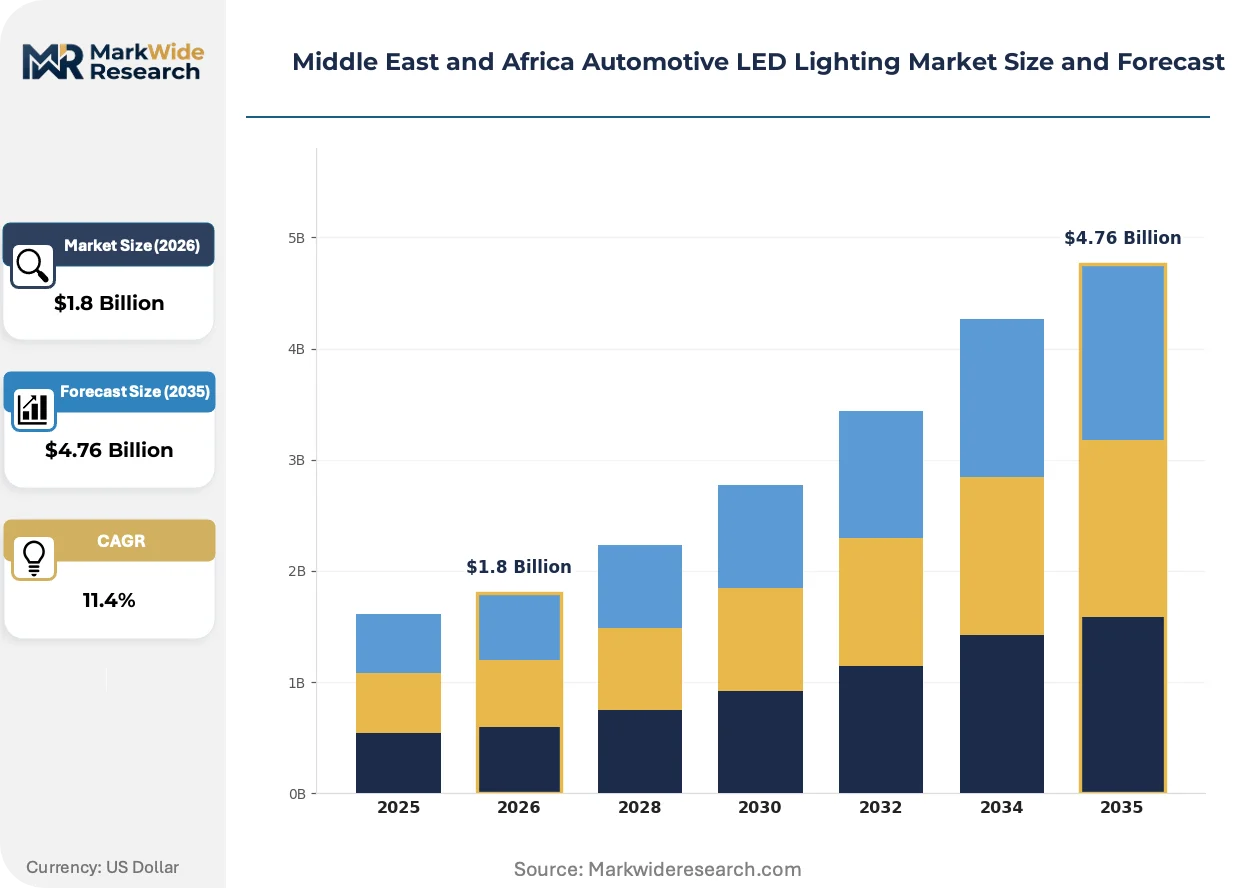
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Tail Lights, Fog Lights, Interior Lights Vehicle Type: Sedans, SUVs, Trucks, Commercial Vehicles Distribution Channel: OEMs, Aftermarket, Retailers, Distributors Technology: Standard LED, Smart LED, Adaptive LED, RGB LED |
| Companies Covered | OSRAM GmbH, HELLA GmbH & Co. KGaA (FORVIA), HYUNDAI MOBIS, Marelli Holdings Co., Ltd., GRUPO ANTOLIN IRAUSA, S.A., Auxbeam Lighting, Valeo, Signify (Philips), Koito Manufacturing Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Automotive LED Lighting Market Trends and Innovations
Digital light processing and solid-state beam shaping are compressing development cycles while regulatory pressure on energy consumption intensifies across Middle East and Africa automotive markets.
Matrix LED technology with individually addressable pixels is fragmenting competitive positioning in the premium headlamp segment. German and Korean OEMs serving Saudi Arabian and UAE assembly plants are adopting chip-on-board architectures faster than regional tier suppliers can match. This capability gap is fragmenting the supplier base into chip-integrated module specialists versus legacy reflector housing assemblers.
Saudi Standards, Metrology and Quality Organization (SASO) energy-efficiency labeling is tightening minimum luminous efficacy thresholds for OEM headlamp assemblies. The regulation compresses qualification windows for imported modules while favoring suppliers with captive epitaxy operations. Premium SUV and electric vehicle platforms face the steepest compliance costs, accelerating consolidation among certified tier-one lighting system integrators.
Aftermarket procurement is gravitating toward direct-sourced LED modules via e-commerce platforms, bypassing traditional distributor networks in South Africa and Nigeria. Independent repair shops and fleet maintenance depots now specify part numbers directly from regional fulfillment hubs rather than through branded channel partners. This disintermediation concentrates price pressure on standardized tail-light and fog-light segments where smart features add limited value.
Middle East and Africa Automotive LED Lighting Market Segmentation
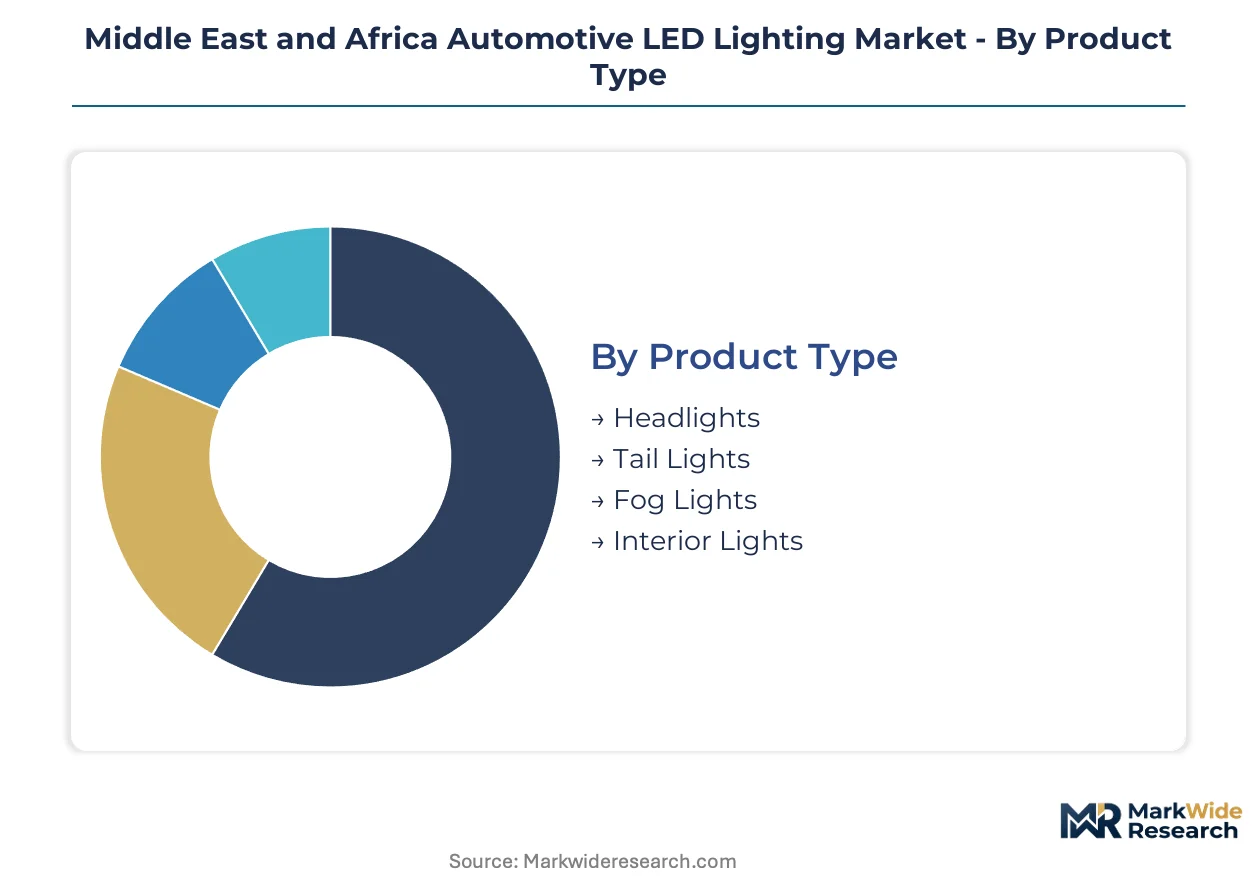
LED lighting configurations across Middle East and Africa automotive markets fragment sharply between OEM specification tiers and aftermarket replacement cycles. Each segmentation axis reveals distinct procurement patterns shaped by regulatory compliance requirements and vehicle platform strategies.
Product Type:
Headlamp assemblies concentrate manufacturing investment in the UAE and Saudi Arabia for regional OEM supply, while tail-light modules flow through South African export channels serving sub-Saharan aftermarket depots.
- Headlights:High-luminosity LED arrays with precision beam control dominate OEM specifications for premium SUV and sedan platforms. Saudi Arabian government fleet tenders under SASO energy-efficiency labeling mandate certified headlamp assemblies, compressing supplier qualification windows.
- Tail Lights:Sequential and animated LED configurations serve both safety compliance and brand differentiation functions. South African assembly plants export standardized tail-light modules to Common Market for Eastern and Southern Africa trade partners, where replacement cycles run shorter than GCC markets.
- Fog Lights:Compact auxiliary LED modules with wide-beam dispersion patterns address dust and sandstorm visibility requirements across Arabian Peninsula logistics corridors.
- Interior Lights:Cabin illumination modules span dome, map, and ambient applications with lower technical barriers to entry than exterior lighting systems.
Headlights hold the largest share; momentum sits with interior ambient systems as electric vehicle platforms expand programmable cabin lighting specifications.
Vehicle Type:
Commercial vehicle segments prioritize retrofit economics and durability under severe thermal cycling, while passenger categories split between mass-market standardization and premium feature differentiation.
- Sedans:Mid-size and compact passenger cars represent volume concentration for standardized LED headlamp and tail-light configurations, with procurement patterns favoring cost-optimized chip-on-board architectures over matrix beam systems.
- SUVs:Sport utility vehicles command the steepest technology specifications across GCC markets, where adaptive LED and matrix beam configurations serve safety mandates and luxury positioning simultaneously. Dubai and Riyadh showrooms drive specification escalation for this segment.
- Trucks:Heavy-duty freight platforms prioritize luminous efficacy and thermal management for continuous operation across desert corridor routes from Jeddah to Dubai.
- Commercial Vehicles:Fleet operators in Saudi Arabia and the UAE accelerate LED retrofits to meet tightening national energy-efficiency mandates, reshaping supplier relationships across logistics networks.
SUVs capture the dominant value pool; commercial vehicles are expanding most quickly as fleet retrofit mandates compress replacement timelines.
Distribution Channel:
OEM integration rates diverge between Gulf Cooperation Council assembly plants with captive tier-one relationships and African markets where aftermarket channels dominate procurement.
- OEMs:Original equipment manufacturers specify LED lighting systems at vehicle design phase, with Hyundai-Kia assembly plants in the region leveraging captive supply relationships for integrated headlamp modules.
- Aftermarket:Replacement and upgrade channels sustain higher volume throughput for tail-light and fog-light segments, where standardized LED modules displace halogen residual stock in price-sensitive vehicle pools.
- Retailers:Branded automotive parts chains in South Africa and Nigeria maintain physical inventory for immediate replacement needs, though e-commerce platforms are disintermediating traditional networks.
- Distributors:Regional fulfillment hubs in Dubai and Johannesburg consolidate procurement for independent repair shops and fleet maintenance depots specifying part numbers directly from import channels.
Aftermarket channels hold the largest share; momentum sits with direct-sourced LED modules via e-commerce platforms as procurement disintermediation accelerates.
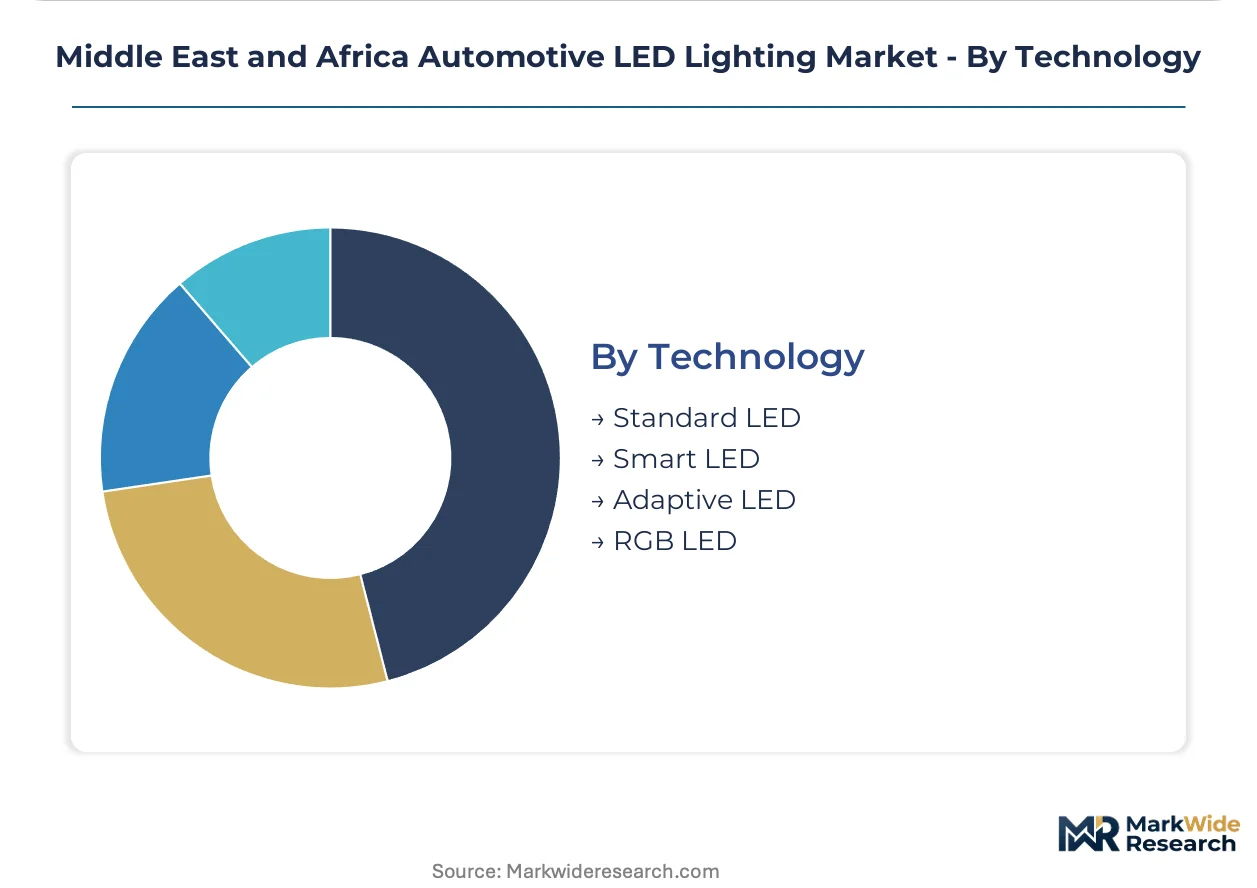
Technology:
Technology tiers stratify across functional performance, with premium configurations requiring captive epitaxy operations and standard variants commoditizing through open-market chip sourcing.
- Standard LED:Conventional solid-state devices with fixed luminous output serve cost-optimized vehicle platforms and high-volume aftermarket replacement, with procurement concentrating in Chinese-sourced chip modules.
- Smart LED:Digitally controlled illumination systems with vehicle-network integration enable predictive beam adjustment and diagnostic feedback, capturing specification slots in connected vehicle architectures.
- Adaptive LED:Dynamic range adjustment with camera-fed beam shaping addresses safety specifications tightening across GCC markets, with German and Korean OEMs adopting chip-on-board architectures faster than regional tier suppliers.
- RGB LED:Programmable multi-color interior ambient systems offer margin expansion beyond functional exterior applications, particularly in luxury electric vehicle platforms targeting Saudi Arabian and UAE showrooms.
Standard LED holds the largest share; adaptive LED is gaining share fastest as matrix beam specifications penetrate premium SUV assemblies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jeddah Islamic Port and the Al-Furjan logistics corridor anchor Saudi Arabia's position as the Gulf's primary automotive LED distribution hub, while the Trans-African Highway network channels South African assembly output into sub-Saharan aftermarket depots.
Saudi Arabia
Government fleet tenders and luxury SUV assembly lines drive LED specification escalation in Riyadh and Jeddah. SASO energy-efficiency labeling mandates certified headlamp assemblies for all OEM supply contracts, compressing supplier qualification windows. The King Abdullah Economic City automotive cluster hosts tier-one lighting module integrators serving Hyundai-Kia and Toyota regional assembly plants.
United Arab Emirates
Dubai's luxury vehicle showrooms and Abu Dhabi's government procurement offices generate concentrated demand for adaptive LED and matrix beam configurations. ESMA certification pathways for smart headlamp assemblies have streamlined approval timelines, creating first-mover positioning for modular platform suppliers. Jebel Ali Free Zone fulfillment hubs consolidate re-export volumes to Iran, Pakistan, and East African markets.
South Africa
Sub-Saharan aftermarket distribution and domestic OEM supply sustain dual-channel LED procurement through Durban and Port Elizabeth. SABS automotive lighting standards maintain partial divergence from GCC harmonization timelines, forcing parallel certification investments for suppliers serving both markets. The Eastern Cape automotive cluster exports standardized tail-light modules to Common Market for Eastern and Southern Africa trade partners.
Egypt
Suez Canal transit corridors and domestic commercial vehicle assembly generate baseline LED demand for freight and passenger transport applications. The country's national standards body maintains alignment with UN ECE regulations for headlamp type-approval, though enforcement capacity varies across informal aftermarket channels. Cairo-Alexandria industrial zones concentrate localized LED module assembly for price-sensitive vehicle pools.
Nigeria
Lagos port throughput and northern haulage routes sustain aftermarket LED replacement cycles for aging commercial fleets. Import duty structures favor complete lamp assemblies over discrete chip sourcing, shaping procurement patterns among independent repair shops. Onitsha and Aba manufacturing clusters produce localized LED housing and reflector components for regional assembly.
Middle East and Africa Automotive LED Lighting Market Competitive Landscape
Listed lighting conglomerates compete with private component specialists across certification access and captive supply relationships. The supplier base stratifies into three tiers: integrated chip-module specialists with backward integration into epitaxy operations, modular platform assemblers serving multiple OEM architectures, and regional distributors capturing aftermarket volume through price-optimized standardized offerings. Competitive moves concentrate on ESMA and SASO pre-qualification investments, plus strategic partnerships with Gulf-based tier-one system integrators.
Within the integrated tier, OSRAM GmbH anchors German-origin positioning through captive chip sourcing capabilities. HELLA GmbH & Co. KGaA occupies the modular platform specialist archetype, while HYUNDAI MOBIS represents the captive supply model through its structural relationship with Hyundai-Kia assembly networks. These three exemplify divergent strategic paths: upstream control over semiconductor inputs, architectural flexibility across vehicle programs, and exclusive OEM alignment respectively.
| Leading Market Players |
|---|
| OSRAM GmbH |
| HELLA GmbH & Co. KGaA (FORVIA) |
| HYUNDAI MOBIS |
| Marelli Holdings Co., Ltd. |
| GRUPO ANTOLIN IRAUSA, S.A. |
| Auxbeam Lighting |
| Valeo |
| Signify (Philips) |
| Koito Manufacturing Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Chip-on-board LED architectures displacing discrete packaged emitters simultaneously concentrate sourcing leverage in East Asian foundries and compress module-level pricing premiums across GCC procurement offices. This substitution dynamic redraws supplier power maps as Saudi Arabian fleet tenders and UAE luxury OEMs negotiate from divergent volume positions.
Pricing Analysis
Volume-discount tiering structures separate government fleet contracts exceeding ten thousand units from aftermarket single-module purchases. Pricing stratifies across SASO-certified premium assemblies, ESMA-compliant standard modules, and uncertified economy imports for price-sensitive African depots. Cost compression in the economy tier intensifies as Chinese chip vendors bypass branded distributors through direct e-commerce channels. Government procurement offices in Riyadh and Abu Dhabi exhibit lowest price sensitivity; independent repair shops in Lagos and Nairobi face acute margin pressure.
Supply Chain Analysis
Inventory lead times for gallium nitride epitaxy wafers stretch from twelve to twenty weeks depending on foundry loading at Taiwanese and South Korean suppliers. The supply chain draws from East Asian substrate production, German optical component specialists, and Chinese module assembly operations. Single-source vulnerability concentrates in III-V semiconductor wafer supply where three foundries control ninety percent of merchant output. Distribution runs through Dubai's Jebel Ali Free Zone for GCC markets and Johannesburg's industrial corridors for sub-Saharan aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where smart LED modules must integrate with vehicle-network protocols and infrastructure communication standards. The interoperability shift toward connected lighting architectures favors suppliers pre-qualifying modular platforms across multiple OEM electrical systems.
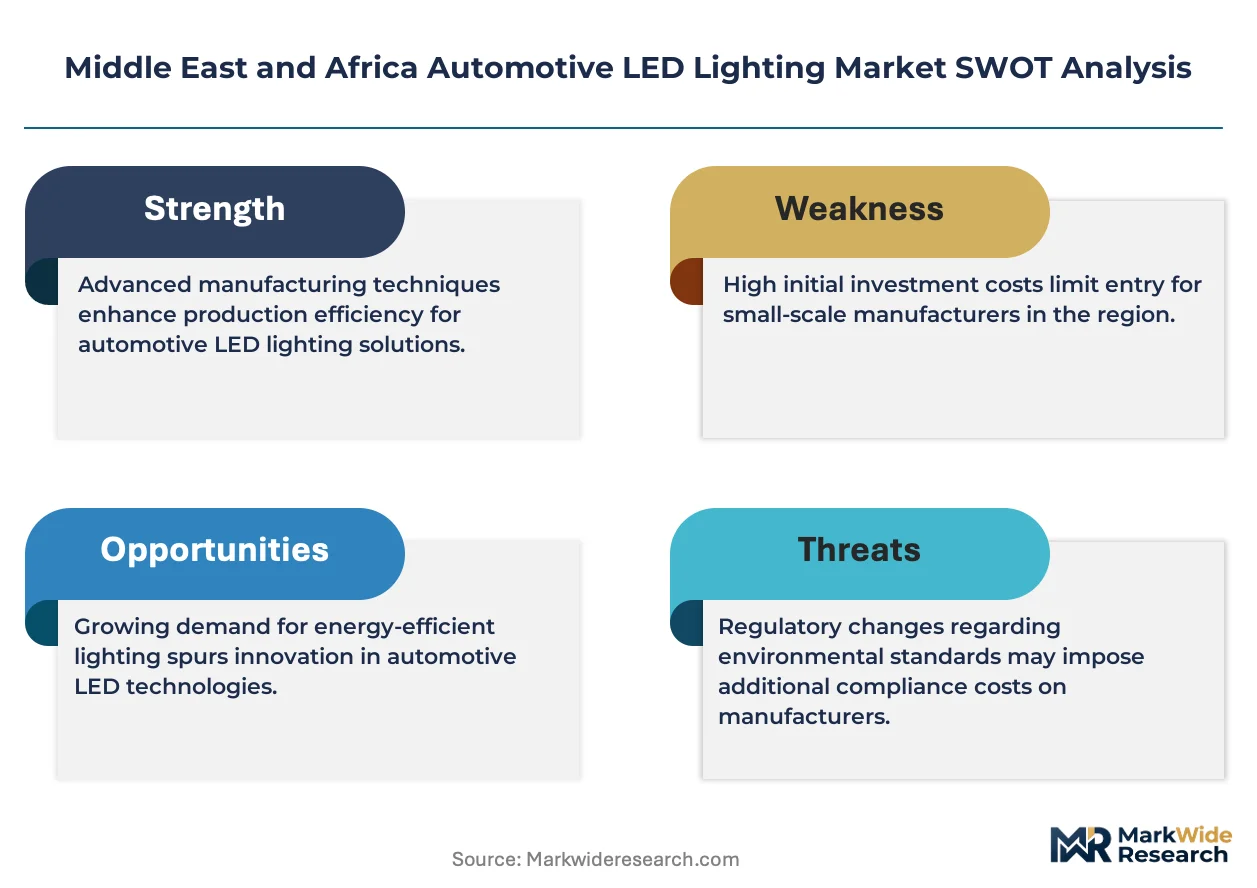
For Market Incumbents: Secure captive chip sourcing relationships or backward integration into epitaxy operations before SASO efficacy thresholds tighten further. Defend OEM specification slots by accelerating ESMA pre-qualification for matrix beam platforms, as Korean and German competitors expand regional assembly plant relationships. Capacity addition in the King Abdullah Economic City cluster offers proximity leverage for Saudi government tenders. For New Entrants and Emerging Players: Lead with RGB interior ambient systems for luxury electric vehicle platforms where programmable cabin specifications outpace incumbent R&D cycles. The most penetrable white space sits in aftermarket direct-sourced modules via e-commerce platforms, bypassing traditional distributor networks in South Africa and Nigeria. A go-to-market angle anchored on ESMA certification acceleration creates first-mover positioning before GCC harmonization completes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed modular platform assemblers lacking captive chip supply. The five-to-ten year viability window favors targets with backward integration into gallium nitride substrate production or exclusive OEM alignment with expanding regional assembly networks. The signal to watch is divergence between Gulf Cooperation Council harmonization timelines and South Africa's European alignment trajectory, which would force dual-homologation investments and consolidate supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxy Operations | Captive wafer supply secures SASO certification pathways against East Asian foundry concentration. |
| ESMA Pre-Qualification Acceleration | Streamlined UAE approval timelines create first-mover positioning for smart headlamp modular platforms. |
| RGB Interior Ambient System Development | Programmable cabin lighting captures margin expansion beyond commoditized exterior LED applications. |
| E-Commerce Channel Bypass Strategy | Direct-sourced modules disintermediate traditional distributor networks in price-sensitive African markets. |
| Dual-Certification Infrastructure Investment | Parallel SABS and ESMA testing protocols extend product launch cycles but lock in cross-regional supply contracts. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors in Dubai and Johannesburg, and regulatory affairs specialists at SASO and ESMA converged on the working assumptions. These primary inputs combined with secondary validation from vehicle production databases, customs and trade flow records, IHS Markit registration data, and national standards body certification rosters. Bottom-up module shipment estimates and top-down OEM content-per-vehicle calculations triangulated on volume figures.
Segmentation dimensions modeled span product type, vehicle class, distribution channel, and technology tier across the projection horizon. The analytical framework derives CAGRs from regression against macroeconomic drivers, regulatory mandate implementation schedules, and OEM platform rollout timelines. Forecast inputs include gallium nitride wafer supply constraints, GCC energy-efficiency labeling phase-ins, and electric vehicle platform penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained SASO enforcement capacity or East Asian foundry supply continuity would require recalibration. Forecasts reflect documented assumptions about regulatory harmonization trajectories and OEM sourcing consolidation patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Europe Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Global Automotive Engine Management System Market