
 Automotive Body Control Module Market | 2026-2036
Automotive Body Control Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Body Control Module Market Analysis
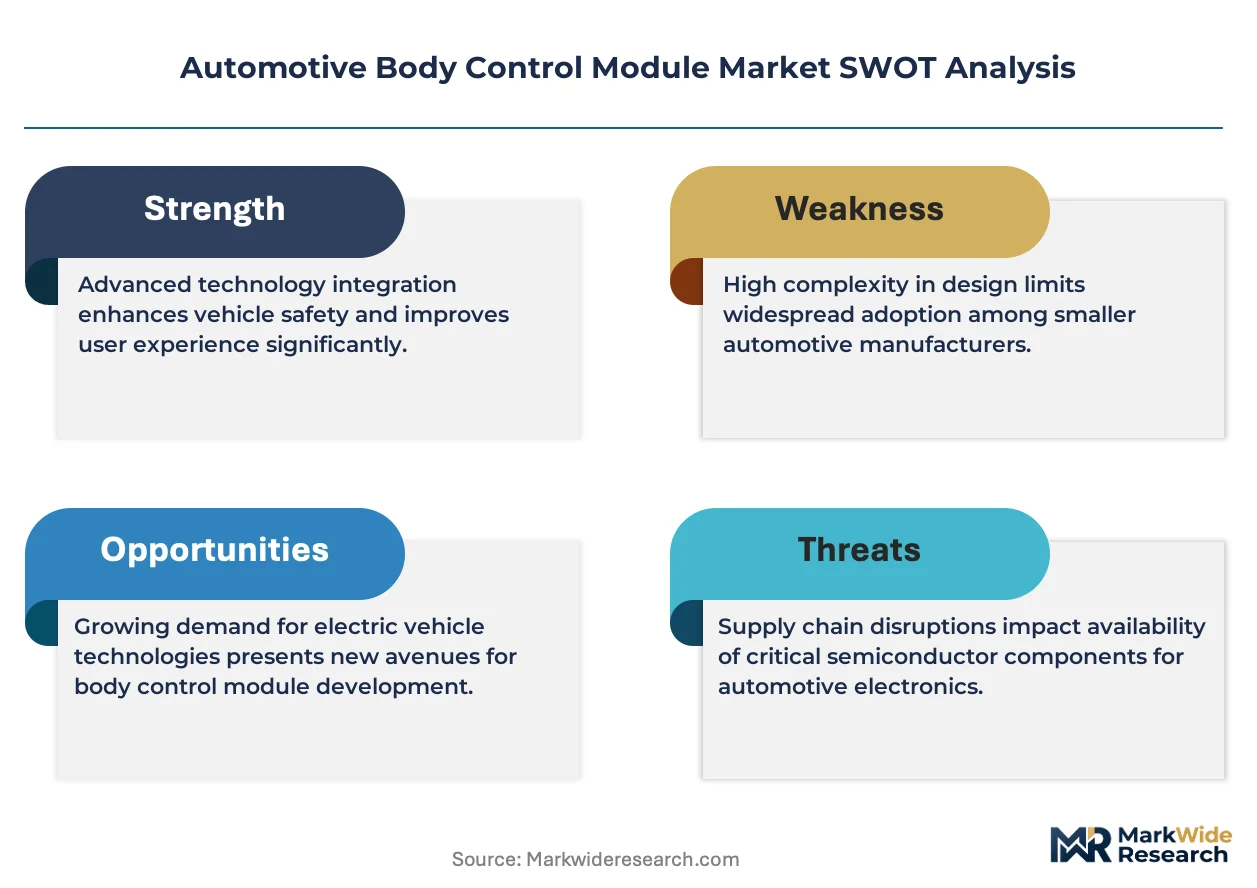
Module bundling into domain-centralized architectures is repositioning buyer choice away from discrete body electronics toward integrated cockpit-body platforms. Robert Bosch GmbH leverages its manufacturing scale to supply bundled power-management and lighting-control modules to European OEMs. Continental AG anchors its position through in-house semiconductor sourcing for smart module production. ZF Friedrichshafen AG competes by specializing in security-system integration for premium vehicle lines.
An automotive body control module is an embedded electronic controller that manages vehicle body functions through microprocessor-based switching, typically operating at 12V or 48V and communicating via multiple in-vehicle network protocols. It consolidates control of lighting, power distribution, access, and thermal comfort subsystems to reduce wiring harness complexity and enable software-defined feature updates. Distributed modules retain the largest installed base due to legacy vehicle program continuity, though smart modules are capturing the fastest growth as automakers pursue zonal E/E architectures. Ethernet-based technology segments are expanding fastest for high-bandwidth camera and sensor fusion backbones, while CAN dominates current production volume across mass-market OEM programs.
The EU's Cyber Resilience Act and UNECE WP.29 R155 regulations are mandating over-the-air update capability and cybersecurity management systems for all connected vehicle electronics sold in Europe. Japan's METI is aligning domestic type approval with these standards, creating a dual-compliance burden for suppliers serving both markets. Stakeholders must monitor whether zonal architecture adoption outpaces the amortization schedules of existing distributed module tooling investments.
Market Dynamics
Zonal E/E architecture migration is compressing the addressable market for discrete body control modules while expanding value capture for integrated domain controllers. This structural shift forces suppliers to recalibrate R&D allocation between legacy distributed platforms and centralized compute-intensive designs.
Growth Catalysts
- EU Cyber Resilience Act:Mandated over-the-air update capability for connected vehicle electronics creates retrofit demand across existing vehicle fleets and accelerates module replacement cycles.
- 48V electrical systems:Premium electric vehicle platforms are expanding adoption of multi-domain body control modules capable of managing higher-voltage subsystems alongside traditional 12V loads.
- Stuttgart-Munich corridor:Germany's automotive engineering concentration generates clustered demand for advanced module validation and rapid prototyping services.
Market Restraints
- Semiconductor supply concentration:Foundry capacity constraints in Taiwan and South Korea create input volatility for smart module production.
- UNECE WP.29 R155 compliance costs:Cybersecurity management system certification adds fixed overhead that disproportionately burdens lower-volume module variants.
- Legacy vehicle program continuity:Distributed module tooling amortization schedules extend 7-10 years, delaying zonal architecture penetration in mass-market segments.
Strategic Opportunities
- Software-defined vehicle platforms:Convergence of body control functions with cockpit domain controllers enables feature subscription revenue models.
- Japan METI alignment:Dual-compliance burden with EU cybersecurity standards creates first-mover advantage for suppliers with certified European platforms.
- Ethernet backbone adoption:High-bandwidth camera and sensor fusion requirements in premium segments open module upgrade pathways.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among Tier-1 suppliers, constraining module development timelines.
- Multi-protocol integration complexity:Simultaneous support for CAN, LIN, and Ethernet within single modules expands validation matrices and defect surface area.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Body Control Module Market |
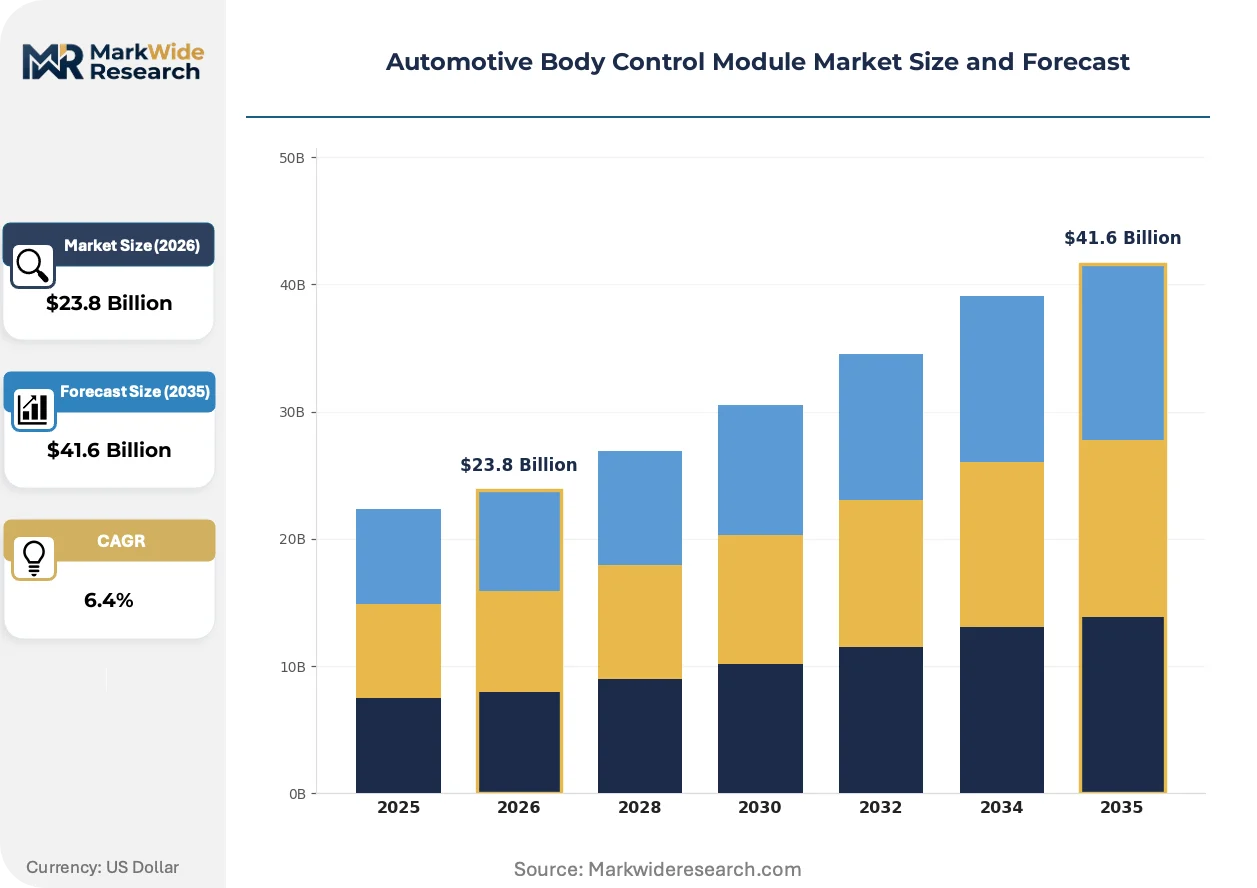
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized Module, Distributed Module, Smart Module, Hybrid Module Technology: CAN, LIN, FlexRay, Ethernet End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Functionality: Lighting Control, Power Management, Security Systems, Comfort Features |
| Companies Covered | Aptiv PLC, ZF Friedrichshafen AG, Robert Bosch GmbH, Lear Corporation, Delphi Technologies, Continental AG, HELLA GmbH & Co. KGaA, Mitsubishi Electric Corporation, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Body Control Module Market Emerging Trajectories
Vehicle electrical architecture consolidation is redrawing competitive boundaries between traditional body electronics suppliers and cockpit-domain specialists. This transformation favors players with software stack depth over hardware-centric incumbents.
Smart body control modules with embedded edge computing capabilities are integrating machine learning inference for predictive load management and anomaly detection. Premium OEMs in Germany and California are deploying these modules in 2024-2026 vehicle programs. The technology is integrating sensor fusion preprocessing that previously required separate domain controllers, compressing bill-of-materials count.
REACH and RoHS substance restrictions are tightening material specifications for module housings and connector plating across European supply chains. Suppliers must reformulate flame-retardant compounds and validate alternative metallization processes. High-temperature under-hood applications face the steepest compliance cost escalation.
Fleet operators and mobility service providers are consolidating module procurement through vehicle-as-a-service contracts that bundle hardware, software updates, and predictive maintenance. This arrangement displaces traditional aftermarket part sales with performance-guarantee agreements. North American commercial vehicle segments show the fastest contract restructuring.
Automotive Body Control Module Market Segmentation
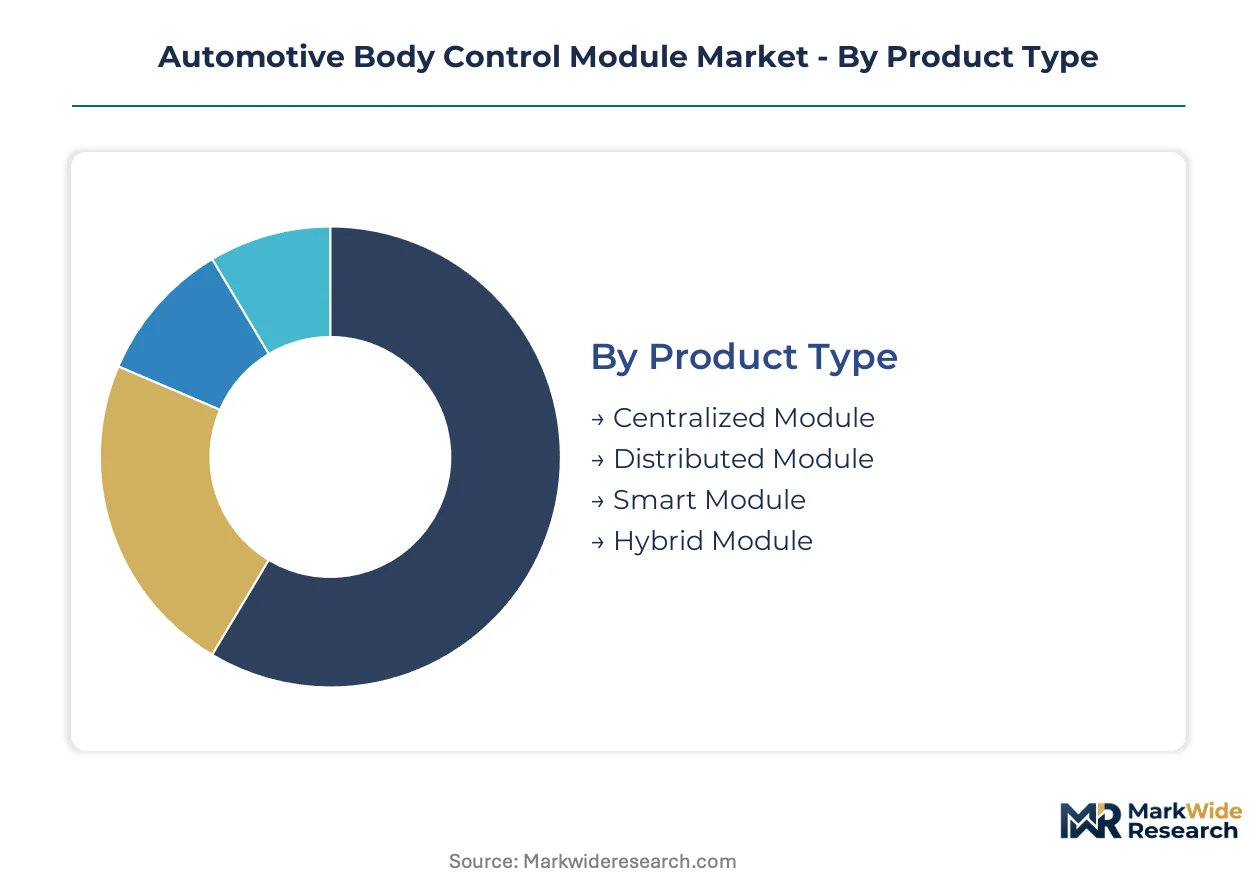
Automotive body control module segmentation reveals how capital allocation, protocol standards, and functional integration shape supplier competitiveness. Understanding these dimensions clarifies where engineering investment concentrates and which configurations command pricing power across vehicle programs.
Product Type:
Capital intensity varies sharply across module architectures, with semiconductor content and software development cycles driving upfront investment requirements.
- Distributed Module:Legacy architecture with discrete controllers per vehicle zone, requiring lower initial tooling but higher wiring harness complexity. Demand persists in mass-market vehicle programs across Germany and Japan where platform continuity extends amortization schedules. Legacy tooling investments delay zonal migration in cost-sensitive segments.
- Smart Module:Embedded edge computing with machine learning inference for predictive load management. Premium electric vehicle platforms in Stuttgart and California deploy these for sensor fusion preprocessing. Zonal E/E architecture adoption compresses bill-of-materials while expanding software-defined feature scope.
- Centralized Module:Domain-consolidated controllers aggregating multiple body functions into single compute units.
- Hybrid Module:Transitional architecture bridging distributed legacy systems with centralized compute platforms.
Distributed modules absorb the bulk of installed capacity; smart modules are expanding most quickly.
Technology:
Protocol selection determines validation burden and silicon sourcing strategy, with bandwidth requirements separating premium from mass-market applications.
- Ethernet:High-bandwidth backbone supporting camera and sensor fusion for advanced driver assistance systems. Premium OEMs in Germany and California specify Ethernet for zonal gateway modules connecting body domains to central compute. Bandwidth scalability enables over-the-air update pipelines mandated by EU Cyber Resilience Act compliance.
- CAN:Dominant protocol across current production volume, with proven reliability for power management and lighting control. Mass-market OEM programs in Japan and Germany standardize on CAN for cost-optimized module variants. Mature ecosystem reduces certification timeline for new vehicle launches.
- LIN:Low-cost serial network for door modules, seat controls, and simple sensor clusters.
- FlexRay:Deterministic protocol reserved for chassis-safety critical functions with hard real-time requirements.
CAN carries the highest shipment volumes; Ethernet is climbing the fastest as zonal architectures proliferate.
End User:
Procurement authority and technical specification control vary significantly across the supply chain hierarchy.
- OEMs:Direct module specification for flagship vehicle platforms, particularly in Germany where engineering teams co-develop software stacks with Tier-1 partners. OEMs retain architecture decisions for domain-centralized designs while outsourcing distributed module production.
- Tier-1 Suppliers:System integration responsibility spanning hardware design, software development, and validation services. Bosch and Continental anchor European supply through manufacturing scale and in-house semiconductor sourcing capabilities.
- Aftermarket Providers:Replacement module distribution for vehicle service life extension.
- Vehicle Assemblers:Contract manufacturing arrangements for regional market adaptation.
OEMs and Tier-1 suppliers dominate value capture; aftermarket providers are gaining share in fleet-heavy segments.
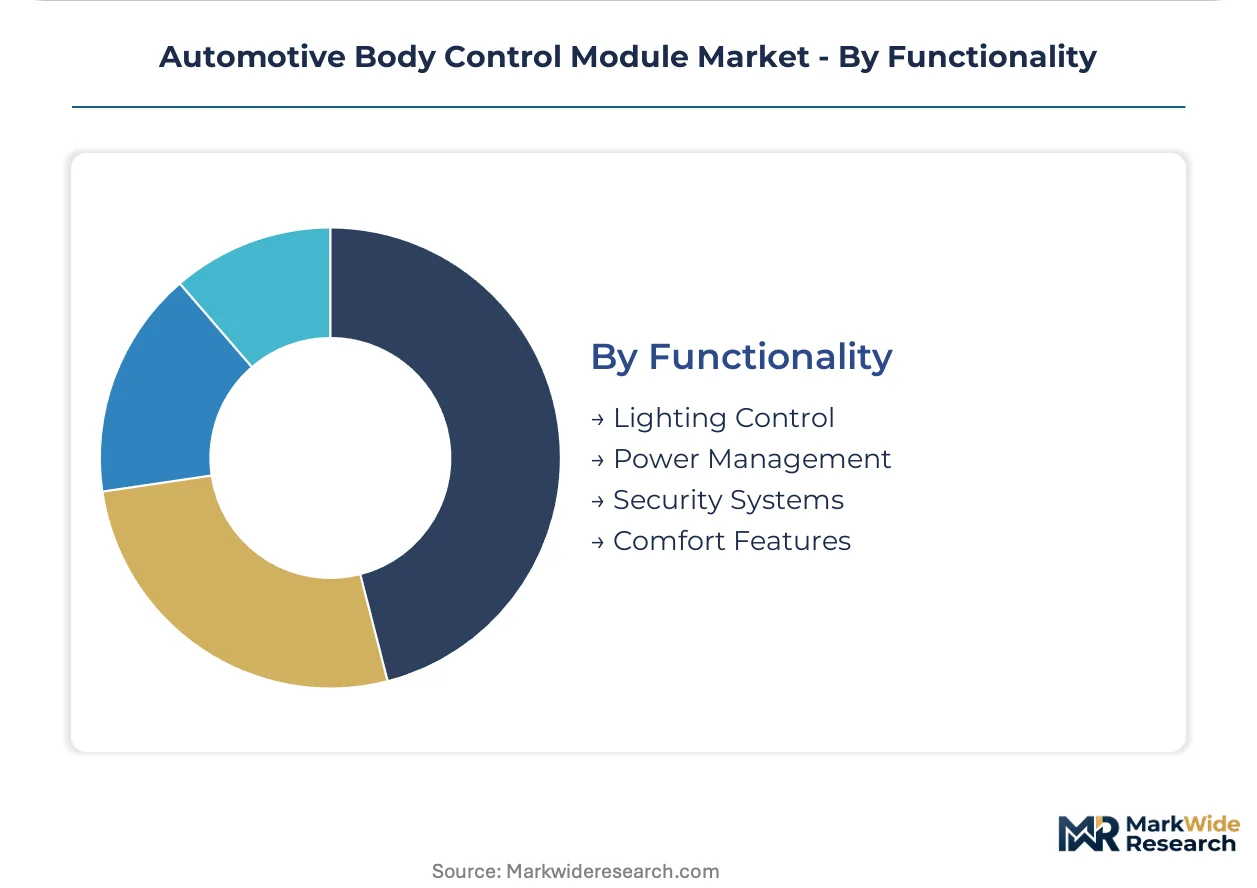
Functionality:
Functional scope determines ASIL safety rating requirements and software complexity, with safety-critical applications commanding engineering premium.
- Power Management:Voltage regulation and load balancing across 12V and 48V electrical systems. Electric vehicle platforms in Germany and Japan require sophisticated multi-domain controllers managing battery thermal integration. 48V subsystem adoption expands module content per vehicle.
- Security Systems:Access control, immobilization, and intrusion detection with UNECE WP.29 R155 cybersecurity compliance. ZF Friedrichshafen specializes in this segment for premium vehicle lines, integrating hardware security modules and secure boot architectures.
- Lighting Control:Adaptive headlamp and interior illumination management.
- Comfort Features:Climate control, seat adjustment, and ambient lighting automation.
Power management commands the largest engineering allocation; security systems are gaining share fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the most sophisticated body control modules while the United States and China consume the largest absolute volumes. Production capacity concentrates near Stuttgart and Munich where engineering talent density supports validation-intensive development cycles.
Germany
The Stuttgart-Munich corridor generates clustered demand for advanced module prototyping and zonal architecture validation. KBA vehicle type approval processes enforce UNECE WP.29 R155 cybersecurity certification before market entry. Engineering teams in Baden-Württemberg co-develop software stacks with Tier-1 partners for flagship electric vehicle platforms.
United States
Detroit-area OEMs specify multi-domain controllers for full-size electric truck programs launching through 2026. NHTSA Federal Motor Vehicle Safety Standards govern lighting and access control system compliance. Michigan-based engineering centers prototype Ethernet-backbone modules for premium pickup segments.
China
Domestic electric vehicle manufacturers source smart modules for zonal E/E architectures at volume scale. MIIT new energy vehicle regulations mandate cybersecurity management systems mirroring European standards. Yangtze River Delta manufacturing clusters produce distributed modules for export to Southeast Asian assembly plants.
Japan
Automakers in Aichi Prefecture integrate body control functions with thermal management for hybrid powertrains. METI alignment with EU Cyber Resilience Act creates dual-compliance requirements for suppliers serving both markets. Nagoya-area engineering teams specialize in CAN-protocol optimization for cost-sensitive mass-market programs.
South Korea
Hyundai Motor Group accelerates centralized module adoption for Genesis luxury electric vehicle lines. MFDS automotive electronics guidelines incorporate ISO 26262 functional safety requirements. Seoul Capital Area semiconductor design houses supply custom ASICs for smart module edge computing.
Automotive Body Control Module Market Vendor Landscape
The competitive structure tilts toward diversified automotive electronics conglomerates with captive semiconductor sourcing capabilities. Tier-1 suppliers anchor European supply through manufacturing scale and in-house chip procurement. Three archetypes dominate: full-stack integrators controlling silicon-to-software pipelines; security-system specialists capturing premium vehicle cybersecurity mandates; and diversified conglomerates leveraging cross-divisional R&D. Dominant competitive moves include backward integration into semiconductor design and strategic partnerships for zonal architecture co-development.
Among German-based diversified suppliers, Robert Bosch GmbH, Continental AG, and ZF Friedrichshafen AG occupy positions spanning the full module architecture spectrum. Bosch exemplifies the scale-driven archetype through bundled power-management and lighting-control offerings. Continental represents silicon-sourcing integration with in-house semiconductor capabilities for smart production. ZF anchors the security-specialist tier through hardware security module integration for premium lines. Japanese players DENSO Corporation and Mitsubishi Electric Corporation sit within the Asia-Pacific supply tier serving hybrid and electric vehicle programs. Aptiv PLC and Lear Corporation represent North American engineering presence with Detroit-area customer proximity.
| Leading Market Players |
|---|
| Aptiv PLC |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Lear Corporation |
| Delphi Technologies |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Mitsubishi Electric Corporation |
| DENSO Corporation |
| Others |
Supply Flow & Price Mechanics
Semiconductor wafer costs cascade through three distinct pricing tiers as modules progress from raw silicon through packaged controllers to validated automotive-grade units. German Tier-1 suppliers absorb foundry premiums for automotive-qualified chips, passing differential costs to OEMs based on ASIL certification levels and volume commitments.
Pricing Analysis
Margin tightening in distributed module tiers reflects legacy tooling amortization schedules extending seven to ten years. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified smart modules from CAN-protocol distributed variants and LIN-based economy units. Cost-down pressure on mass-market segments accelerates because OEMs consolidate procurement through vehicle-as-a-service contracts. Fleet operators exhibit highest price sensitivity; premium electric vehicle platforms show lowest sensitivity to module cost escalation.
Supply Chain Analysis
Dual-sourcing mandates from European OEMs require qualified suppliers in both Taiwan and South Korea for automotive microcontroller production. Foundry capacity draws from TSMC and Samsung facilities, with packaging and testing anchored in Malaysia and Vietnam. Single-source vulnerability concentrates in advanced node semiconductor production. Distribution runs through Tier-1 system integrators co-located with Stuttgart and Munich engineering corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive body control module competition has become a vertical-integration race, with captive semiconductor sourcing separating viable suppliers from margin-squeezed assemblers. Control over silicon-to-software pipelines determines who captures value as zonal architectures consolidate functional scope.
For Market Incumbents: To counter zonal architecture compression of discrete module addressable markets, Bosch and Continental should deepen backward integration into automotive-qualified semiconductor design while adding validation capacity in Baden-Württemberg. ISO 26262 ASIL-D certification investment creates switching costs that lock in OEM platform engineering relationships. For New Entrants and Emerging Players: Begin with aftermarket fleet retrofit opportunities where cybersecurity update mandates create replacement demand outside OEM captive supply chains. Vehicle-as-a-service contract penetration in North American commercial segments offers the most penetrable entry point. Target predictive maintenance bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor security-system specialists with UNECE WP.29 R155 certification in Germany and Japan, where dual-compliance burdens constrain supplier capacity expansion. Long-term viability hinges on software stack depth rather than hardware assembly scale. Watch Ethernet backbone adoption rates in premium vehicle programs as the inflection signal for smart module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Backward Integration | Captive wafer supply secures allocation priority during Taiwan foundry constraints. |
| Zonal Architecture Co-Development | OEM-Tier-1 partnerships for domain-centralized designs capture cockpit-body convergence value. |
| Cybersecurity Certification Investment | UNECE WP.29 R155 compliance creates defensible positioning for European and Japanese markets. |
| Software-Defined Vehicle Platform Investment | Feature subscription revenue models displace one-time hardware sales in premium segments. |
| Geographic Manufacturing Footprint Expansion | Yangtze River Delta proximity captures Chinese electric vehicle platform sourcing decisions. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement executives, and semiconductor foundry account managers underwrites the qualitative findings. Primary interviews with vehicle-as-a-service fleet operators and aftermarket distributors supplemented secondary validation through vehicle production databases, IHS Markit registration data, KBA type approval records, and SEC filings from listed automotive electronics suppliers. Bottom-up module shipment estimates triangulated against top-down vehicle production forecasts.
Comparable-period anchoring to historical distributed module adoption curves calibrated the projection horizon for zonal architecture penetration rates. Segmentation modeling spanned product architecture, protocol technology, OEM tier, vehicle propulsion type, and regional production cluster. CAGRs derived from segment-level growth rate distributions weighted by installed base transition dynamics. Forecast inputs incorporated foundry capacity expansion announcements and EU Cyber Resilience Act implementation timelines.
Underlying measurement precision varies by segment; Ethernet-based smart modules carry tighter precision than legacy distributed variants given visible OEM platform commitments. Forecasts reflect assumptions regarding zonal architecture adoption speed and semiconductor supply normalization. Deviation in UNECE WP.29 R155 enforcement intensity or Taiwan foundry allocation priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market