
 Automotive 48V System Market | 2026-2036
Automotive 48V System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive 48V System Market Intelligence
Modular 48V mild-hybrid packaging is repositioning buyer choice away from discrete component sourcing toward integrated belt-starter-generator kits. Continental AG leverages its power electronics depth to anchor full-system contracts with European OEMs. BorgWarner Inc. competes through turbocharger-48V bundling that sustains margin capture across powertrain tiers. Robert Bosch GmbH dominates control-unit firmware, extending its position through proprietary battery-management algorithms.
An automotive 48V system operates at a nominal DC voltage between 36V and 52V, employing lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate chemistries, belt-integrated starter-generators, and DC-DC converters to enable recuperation and torque assist below full-hybrid cost thresholds. Its primary industrial purpose is to reduce CO2 emissions and fuel consumption in internal-combustion vehicles without the wiring mass and semiconductor expense of high-voltage architectures. Battery and control-unit segments concentrate margin pools where cell balancing and thermal runaway protection command engineering premiums. Start-stop and regenerative-braking technologies lead volume deployment, while hybrid-system configurations represent the fastest-growing technology tier as OEMs phase in electric power assist across C-segment and D-segment platforms.
The EU Green Deal and CO2 fleet standards enforced by the European Commission are mandating 48V adoption across mass-market vehicle lines, while EPA fuel-economy benchmarks in the United States push domestic OEMs toward mild-hybrid architectures. China's MIIT dual carbon goals and GB/T standards for low-voltage electrification are reshaping supplier qualification requirements for access to the country's passenger-vehicle market. Stakeholders must monitor regulatory calibration timelines across Brussels, Washington, and Beijing to align R&D allocation with compliance-driven procurement cycles.
Market Dynamics
Passenger vehicle electrification is accelerating adoption as OEMs seek cost-efficient hybridization paths that avoid the wiring mass and semiconductor expense of high-voltage architectures.
Growth Catalysts
- EU Green Deal mandates:CO2 fleet standards enforced by the European Commission compel powertrain upgrades across Germany, France, and Italy, anchoring procurement cycles to compliance timelines.
- Regenerative braking integration:Belt-integrated starter-generators enable fuel recovery during deceleration, delivering emission reductions below full-hybrid cost thresholds for C-segment and D-segment platforms.
- China's MIIT dual carbon goals:GB/T standards for low-voltage electrification reshape supplier qualification requirements, opening volume production access to qualified battery-management and DC-DC converter vendors.
Market Restraints
- Lithium-ion cell cost volatility:Nickel-manganese-cobalt and lithium-iron-phosphate chemistries face raw material price swings that compress module margins and destabilize long-term supply contracts.
- Tier-one supplier concentration:Germany's automotive manufacturing corridor concentrates 48V module production, creating geographic vulnerability to regional logistics disruptions or energy cost spikes.
- High-voltage hybrid substitution:Full-hybrid and battery-electric architectures above 60V threaten mild-hybrid relevance as battery costs decline and charging infrastructure expands.
Strategic Opportunities
- Underpenetrated commercial vehicle electrification:Light commercial and medium-duty truck segments in India present white space for 48V start-stop and torque-assist configurations as BIS standards tighten.
- Turbocharger-48V bundling:Integration of electric compressors with mild-hybrid systems creates margin capture opportunities across powertrain tiers for suppliers with power electronics depth.
- EPA fuel-economy benchmarks:United States domestic OEM procurement cycles are pivoting toward mild-hybrid architectures, opening qualification windows for European and Asian component vendors.
Industry Challenges
- Battery-management firmware talent scarcity:Cell balancing and thermal runaway protection algorithms require specialized embedded systems engineers, constraining control-unit development timelines.
- Multi-standard certification complexity:OEMs must simultaneously validate systems against EU safety protocols, EPA emissions testing, and China's GB/T electromagnetic compatibility requirements.
- Legacy 12V electrical architecture integration:DC-DC converter design must accommodate existing body electronics without full platform redesign, extending engineering validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive 48V System Market |
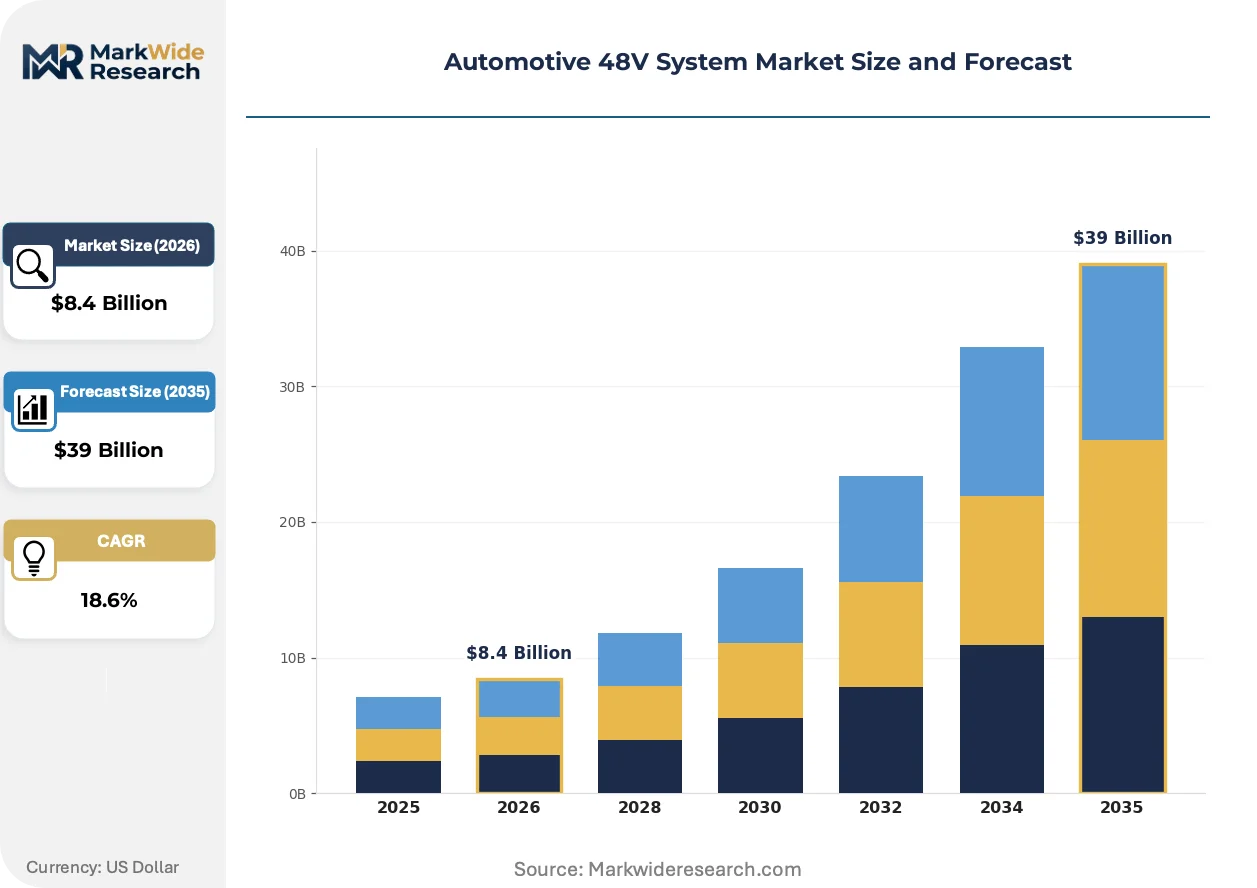
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery, Alternator, Electric Motor, Control Unit Technology: Start-Stop Systems, Regenerative Braking, Electric Power Assist, Hybrid Systems End User: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Electric Vehicles Application: Powertrain, Interior Lighting, Climate Control, Safety Systems |
| Companies Covered | ZF Friedrichshafen AG, BorgWarner Inc., Robert Bosch GmbH, Magna International Inc., Infineon Technologies AG, Continental AG, Valeo, MAHLE GmbH, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive 48V System Market Strategic Shifts & Innovations
Modular 48V mild-hybrid packaging is repositioning buyer choice away from discrete component sourcing toward integrated belt-starter-generator kits that compress procurement complexity.
Silicon carbide power semiconductors are replacing silicon MOSFETs in DC-DC converters to reduce switching losses and thermal management mass. European tier-one suppliers are adopting these devices for 2026 platform launches. This transition is expanding into volume production contracts as cell balancing demands intensify.
REACH substance restrictions and RoHS amendments are tightening material compliance for battery enclosures and cable insulation compounds. Suppliers must reformulate flame-retardant additives to maintain thermal runaway protection while eliminating restricted halogenated compounds. Control-unit manufacturers in Germany and France are accelerating alternative material qualification to lock in homologation timelines.
Fleet procurement departments are consolidating supplier relationships around full-system integrators capable of delivering belt-starter-generator, battery module, and control unit as a single contract. This behavior compresses the addressable market for discrete component vendors. The shift is most visible in Germany's volume passenger vehicle platforms, where OEMs prioritize single-source accountability over multi-vendor assembly.
Automotive 48V System Market Segmentation
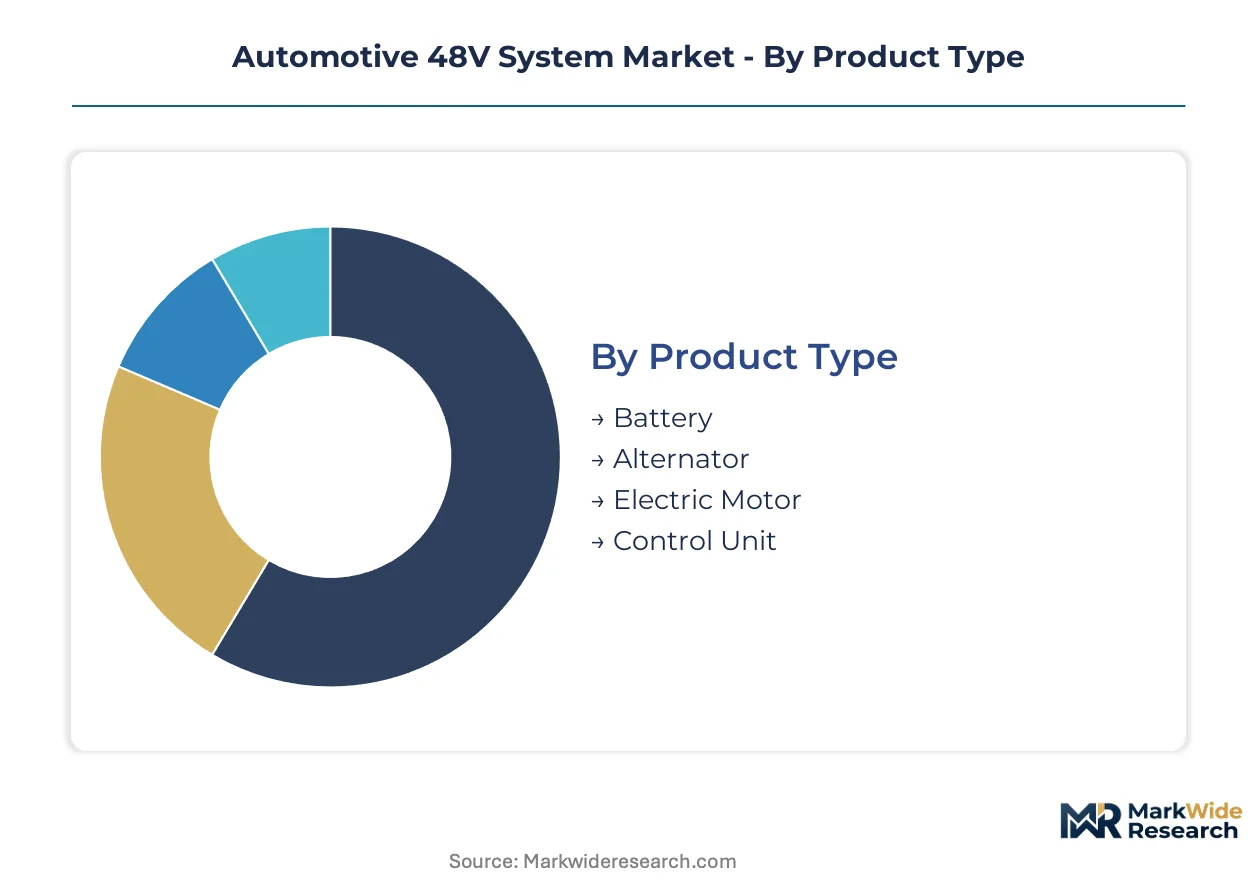
48V system segmentation reveals where margin pools concentrate versus where volumes scale. Component-level versus integrated-system purchasing decisions split procurement patterns across OEM tiers and regional supply bases.
Product Type:
Standalone battery modules command premium engineering validation, while embedded alternator and motor units ship as pre-integrated kits to reduce OEM assembly complexity.
- Battery:Lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate chemistries form the energy storage core. German OEMs in Stuttgart and Munich anchor demand for modules with cell-balancing firmware and thermal runaway protection that meets ECE R100 safety protocols.
- Alternator:Belt-integrated starter-generators convert mechanical rotation to electrical energy during coasting. French and Italian volume manufacturers prioritize compact packaging that fits existing accessory drive layouts without hood redesign.
- Electric Motor:Permanent-magnet synchronous machines deliver torque assist up to 20 kW for mild-hybrid acceleration support.
- Control Unit:Embedded battery-management algorithms govern charge cycling and fault detection across DC-DC converter interfaces.
Battery and control unit segments capture the deepest margins; alternator volumes scale fastest with belt-starter-generator kit adoption.
Technology:
Cost tier separates entry-level start-stop implementations from full hybrid-system architectures that layer multiple electrification functions.
- Start-Stop Systems:Engine shutdown at idle cuts urban fuel consumption. European A-segment and B-segment platforms in Spain and Poland deploy this baseline technology to meet EU fleet CO2 thresholds without full powertrain redesign.
- Regenerative Braking:Deceleration energy recovery feeds the 48V battery through the belt-starter-generator. China's MIIT dual carbon compliance timeline accelerates procurement from qualified DC-DC converter vendors in Jiangsu and Zhejiang provinces.
- Electric Power Assist:Torque fill during turbocharger lag improves drivability in downsized engines.
- Hybrid Systems:Combined start-stop, recuperation, and e-boost functions approach full-hybrid efficiency at lower voltage cost.
Start-stop systems dominate installed base; hybrid configurations are climbing the fastest as C-segment and D-segment platforms layer functions.
End User:
Volume concentration varies sharply between mass-market passenger lines where pennies per watt matter and luxury segments that absorb technology premiums.
- Passenger Vehicles:C-segment sedans and crossovers represent the primary deployment channel. German, French, and Italian OEMs integrate 48V modules across high-volume nameplates to satisfy European Commission fleet emission mandates without full platform electrification.
- Commercial Vehicles:Light-duty delivery vans and medium trucks in India face tightening BIS emission standards that favor 48V torque assist for loaded acceleration. This segment remains underpenetrated relative to passenger applications.
- Luxury Vehicles:Premium brands deploy 48V for active anti-roll systems and advanced climate functions beyond powertrain efficiency.
- Electric Vehicles:Native high-voltage architectures rarely incorporate 48V subsystems except for legacy accessory support.
Passenger vehicles lead volumes today; commercial vehicles are gaining share fastest as Indian and Southeast Asian regulators tighten standards.
Application:
Powertrain electrification absorbs the majority of 48V system value, while body and cabin functions exploit available bus capacity for incremental features.
- Powertrain:Crankshaft-integrated starter-generators and electric compressors deliver fuel economy gains. OEM engineering centers in Wolfsburg, Rüsselsheim, and Turin validate these configurations against WLTP test cycles for homologation compliance.
- Interior Lighting:LED matrix headlights and adaptive driving beam systems draw from the 48V bus to reduce copper gauge requirements versus 12V alternatives.
- Climate Control:Electric air conditioning compressors maintain cabin cooling during engine-off coasting phases.
- Safety Systems:Active suspension and electric power steering redundancy leverage 48V capacity for faster response.
Powertrain applications lead volumes today; climate control is gaining share fastest as thermal management electrifies across mild-hybrid platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive 48V system commercialization through Stuttgart and Munich engineering centers that validated belt-starter-generator architectures for mass-market deployment. This technical lineage now diffuses across multiple production geographies as regulatory pressure mounts.
Germany
Stuttgart and Wolfsburg anchor European 48V module demand as Volkswagen Group and Mercedes-Benz integrate mild-hybrid systems across C-segment and D-segment platforms. The KBA enforces EU fleet CO2 standards that compel powertrain electrification without full hybrid cost structures. Tier-one suppliers in Baden-Württemberg concentrate control-unit firmware development and battery-management algorithm production for export across the continent.
China
Jiangsu and Zhejiang provinces drive procurement acceleration for DC-DC converters and cell-balancing systems as domestic OEMs electrify volume nameplates. MIIT dual carbon goals and GB/T low-voltage electrification standards reshape supplier qualification requirements for market access. Engineering centers in Shanghai and Shenzhen validate 48V configurations against domestic homologation timelines that outpace European adoption curves.
United States
Michigan and Ohio manufacturing corridors absorb EPA fuel-economy compliance pressure through mild-hybrid retrofits of existing truck and SUV platforms. The EPA benchmarks push domestic OEM procurement toward integrated belt-starter-generator kits that avoid high-voltage architecture redesign. Detroit engineering centers validate systems against federal emissions testing protocols while qualifying European and Asian component vendors for volume contracts.
India
Maharashtra and Tamil Nadu industrial zones face tightening BIS emission standards that favor 48V torque assist for light commercial vehicles and compact passenger cars. The BIS regulatory trajectory opens white space for start-stop and recuperation configurations in underpenetrated truck segments. Pune and Chennai supplier parks attract battery-management and DC-DC converter vendors seeking qualification for domestic OEM procurement cycles.
Japan
Aichi and Kanagawa prefectures sustain hybrid technology leadership through incremental 48V layering on existing powertrain architectures. METI energy efficiency guidelines and JIS standards for low-voltage electrification shape supplier technical requirements for domestic and export markets. Toyota City and Yokohama engineering centers optimize belt-integrated starter-generators for integration with downsized turbocharged engines.
Automotive 48V System Market Key Industry Players
The competitive structure tilts toward full-system integrators capable of delivering battery module, control unit, and belt-starter-generator as unified contracts. Continental AG and Robert Bosch GmbH anchor this tier through power electronics depth and proprietary firmware ecosystems. Three archetypes populate the vendor landscape: diversified automotive suppliers with cross-powertrain portfolios, semiconductor specialists supplying switching components for DC-DC converters, and regional fabricators serving single-market qualification requirements. Dominant competitive moves include strategic partnerships for silicon carbide semiconductor sourcing and geographic expansion into Indian and Southeast Asian qualification windows.
Within the diversified supplier tier, Continental AG, Robert Bosch GmbH, and BorgWarner Inc. occupy positions defined by powertrain integration depth and European OEM relationship density. These GmbH- and AG-structured entities exemplify the full-system archetype that fleet procurement departments increasingly favor. Among semiconductor specialists, Infineon Technologies AG anchors the power switching segment with silicon carbide device portfolios that enable next-generation DC-DC converter efficiency. Denso Corporation represents the Asia-Pacific integration model, sitting within Japanese OEM supply hierarchies that prioritize single-source accountability across hybrid technology tiers.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| Magna International Inc. |
| Infineon Technologies AG |
| Continental AG |
| Valeo |
| MAHLE GmbH |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Embedded systems engineering talent scarcity in Baden-Württemberg and Bavaria widens pricing spreads between premium firmware-integrated modules and commodity battery packs, compressing margins for suppliers lacking proprietary cell-balancing algorithms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies 48V system procurement, with ECE R100-certified modules commanding substantial premiums over baseline start-stop configurations. Price differentiation hinges on thermal runaway protection sophistication and DC-DC converter efficiency ratings. Cost compression in economy-tier alternators is intensifying because Chinese vendors are qualifying against GB/T standards at scale. Fleet procurement departments at German OEMs show lowest price sensitivity for control units with proprietary battery-management firmware, while Indian commercial vehicle OEMs prioritize per-watt economics.
Supply Chain Analysis
Single-source vulnerability sits with lithium-ion cell cathode active material production concentrated in China, South Korea, and Indonesia. Raw material dependencies span nickel-manganese-cobalt chemistries, lithium carbonate, and silicon carbide wafers for power semiconductors. Tariff exposure on processed cathode materials threatens module margin stability as trade policy shifts. Distribution runs through tier-one integrators in Stuttgart, Wolfsburg, and Shanghai who bundle battery, control unit, and belt-starter-generator into single-source contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive 48V system procurement has entered a late-cycle quality phase as OEMs prioritize firmware-integrated modules over discrete component sourcing, with premium specifications for cell-balancing algorithms and thermal runaway protection now table stakes for European volume platform awards.
For Market Incumbents: Anticipate high-voltage hybrid substitution above 60V architectures by locking in multi-year silicon carbide supply agreements and deepening backward integration into battery-management firmware development. Prioritize certification investment for China's GB/T electromagnetic compatibility requirements before domestic OEMs close qualification windows to European vendors.
For New Entrants and Emerging Players: Direct-to-OEM digital sales channels for aftermarket battery replacement modules bypass tier-one bundling power and open margin capture in Europe's aging 48V installed base. Target India's light commercial vehicle segment for torque-assist configurations as BIS emission standards tighten, using Pune and Chennai supplier park partnerships as qualification accelerants.
For Investors and Strategic Acquirers: Power electronics conglomerates with existing inverter and converter portfolios are the most active acquirer in this space, seeking 48V control unit specialists to complete full-system integration capabilities. Focus acquisition screening on embedded firmware firms with automotive-grade ASIL-D certification and established European OEM relationships. Watch silicon carbide device pricing inflection as the signal for DC-DC converter margin expansion or compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Sourcing Agreement | Reduces switching losses in DC-DC converters for 2026 European platform launches. |
| GB/T Electromagnetic Compatibility Certification | Unlocks qualification for Chinese OEM procurement cycles under MIIT dual carbon mandates. |
| Belt-Starter-Generator Platform Standardization | Compresses OEM assembly complexity and anchors multi-year full-system contracts. |
| Battery-Management Firmware Acquisition | Captures margin pools where cell balancing and thermal runaway protection command premiums. |
| Indian Supplier Park Joint Venture | Positions for BIS-compliant commercial vehicle electrification in underpenetrated truck segments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and EU regulatory compliance disclosures. Bottom-up component demand modeling and top-down OEM platform electrification timelines were cross-referenced for triangulation.
Historical reference periods anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from installed base growth curves and replacement cycle dynamics, incorporating silicon carbide adoption rates and GB/T qualification timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for high-voltage hybrid architectures above 60V would alter the outlook if battery cost declines accelerate beyond projected trajectories. Forecasts reflect assumptions about regulatory calibration timelines across Brussels, Washington, and Beijing, with lithium-ion raw material price volatility and tier-one supplier geographic concentration representing specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Global Automotive Engine Management System Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market