
 Vehicle Cargo Box Market | 2026-2036
Vehicle Cargo Box Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Cargo Box Market Analytics
Market Context
Composite manufacturing expertise is rotating toward thermoformed polymer expertise as brands compete for lighter, aerodynamic designs. Thule leverages European design heritage and captive distribution to sustain premium positioning across North American and European retail channels. Yakima dominates specialty outdoor retailers with bike-and-ski crossover bundling that extends average transaction values. SportRack anchors value-tier penetration through mass-market retail partnerships with controlled cost structures.
Technical Definition and Segments
A vehicle cargo box is an enclosed rooftop storage container, typically vacuum-formed from ABS or impact-modified acrylic, engineered to withstand highway-speed aerodynamic loads while maintaining waterproof seals rated to IP55 or higher. Hard shell configurations lead unit volumes due to structural rigidity and theft resistance, while modular systems represent the fastest-growing type as consumers seek expandable capacity for seasonal use patterns. Plastic materials occupy the largest share by tonnage, though aluminum skins command margin pools in premium tiers where weight reduction justifies unit cost premiums.
Regulatory Frame and Outlook
NHTSA roof load standards in the United States, ECE R14 mounting point regulations in Europe, and China's GB/T vehicle exterior accessory standards collectively shape product certification requirements and market access barriers. These frameworks force manufacturers to engineer region-specific mounting hardware and conduct localized crash-adjacent testing, adding fixed cost layers that favor scaled producers. Stakeholders must monitor evolving load-rating harmonization between NHTSA and ECE frameworks, as alignment would unlock cross-regional SKU consolidation and margin recovery.
Market Dynamics
Thermoformed polymer manufacturing is displacing legacy ABS vacuum-forming as brands compete for lighter, more aerodynamic cargo box designs that reduce fuel penalty and extend electric vehicle range compatibility.
Growth Catalysts
- NHTSA Roof Load Standards:Certification requirements under United States federal motor vehicle safety regulations create consumer trust premiums for tested products, accelerating replacement cycles among safety-conscious SUV owners.
- Overlanding Culture:National park visitation patterns in the United States sustain demand for modular expandable systems that accommodate seasonal gear shifts from ski to camping equipment.
- Thermoformed Polymer Expertise:Composite manufacturing rotation toward impact-modified acrylic and advanced thermoplastics enables weight reduction without sacrificing structural rigidity at highway speeds.
Market Restraints
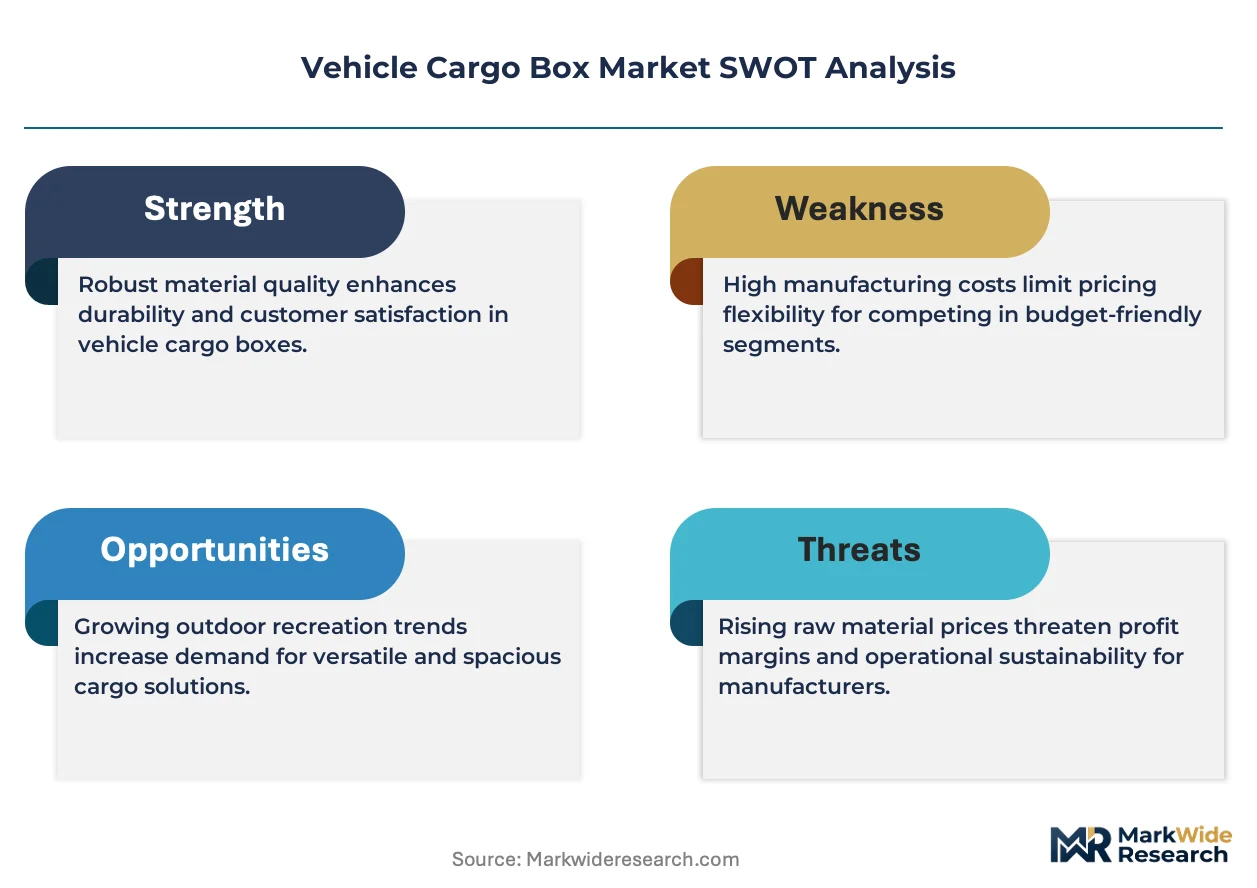
- Petrochemical Input Volatility:ABS and acrylic resin prices fluctuate with crude oil derivatives, compressing margin pools for value-tier manufacturers dependent on mass-market retail partnerships.
- Mounting Hardware Fragmentation:Region-specific engineering requirements under ECE R14 in Europe versus NHTSA standards in the United States prevent SKU consolidation and inflate fixed testing costs.
- Rooftop Tent Substitution:Integrated sleep systems for overlanding applications capture discretionary spending from traditional cargo box buyers seeking multi-function outdoor equipment.
Strategic Opportunities
- Electric Vehicle Compatibility:Aerodynamic optimization for reduced drag coefficient addresses range anxiety concerns among Tesla, Rivian, and Ford Lightning owners in premium segments.
- Specialty Outdoor Retail Expansion:Bike-and-ski crossover bundling at REI, Backcountry, and regional chains extends average transaction values through seasonal accessory attachments.
- GB/T Standard Alignment:China's vehicle exterior accessory certification framework offers pathway for harmonized mounting hardware if technical specifications converge with ECE R14 protocols.
Industry Challenges
- Crash-Adjacent Testing Timelines:NHTSA roof load rating validation and ECE R14 mounting point certification require 18-24 month development cycles that delay product launches and freeze working capital.
- Aerodynamic Engineering Talent Scarcity:Computational fluid dynamics expertise for low-drag cargo box design concentrates among automotive suppliers, forcing outdoor equipment brands to compete for limited specialist labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Cargo Box Market |
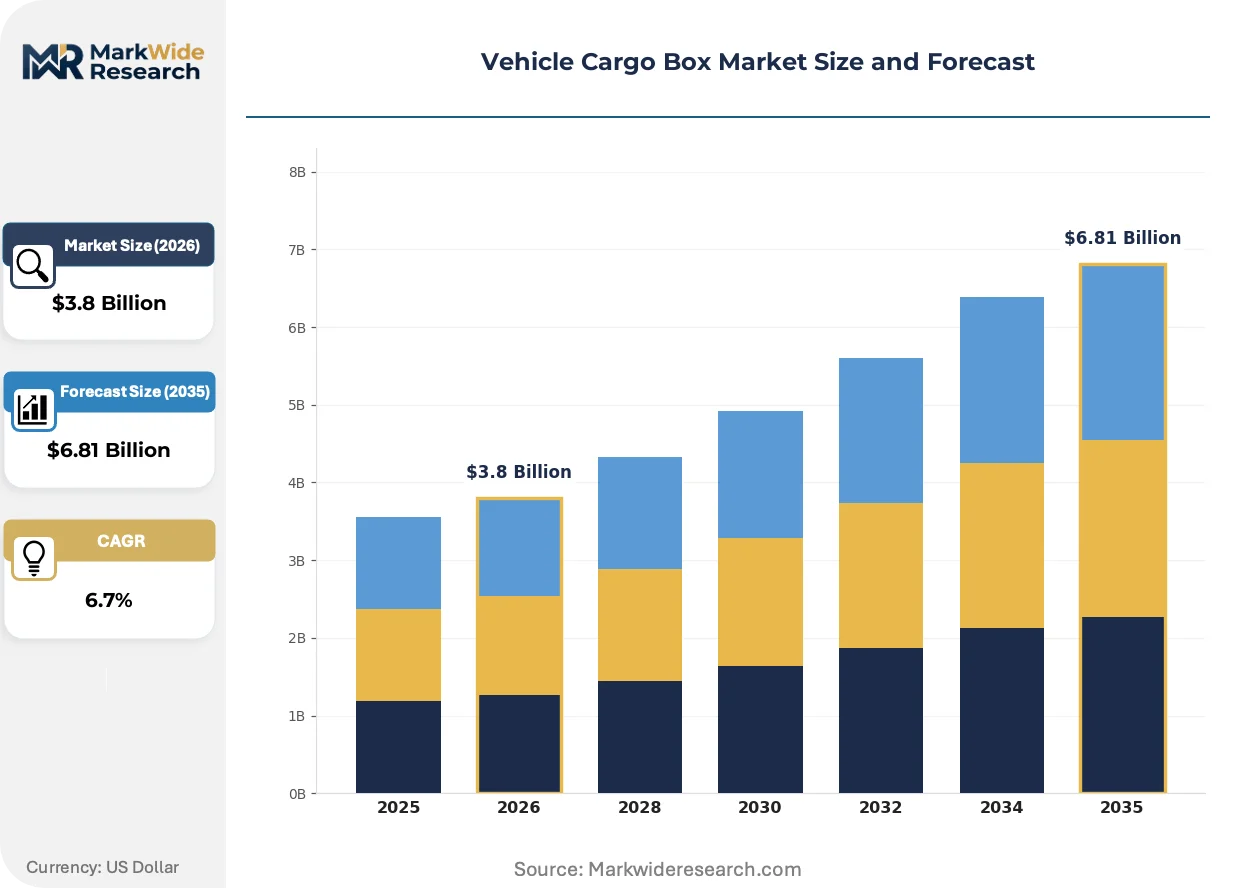
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hard Shell, Soft Shell, Expandable, Modular Material: Aluminum, Steel, Plastic, Composite Size: Compact, Mid-Size, Full-Size, Oversized Installation: Permanently Mounted, Removable, Quick-Release, Integrated |
| Companies Covered | SportRack, Flated, Yakima, Pelican, MeeFar, Thule, Rightline Gear, Enthuze, Inno, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Cargo Box Market Evolving Landscape
Material science breakthroughs and regulatory harmonization pressures are simultaneously compressing traditional manufacturing methods while opening premium positioning opportunities for brands that master certification complexity.
Modular cargo box architecture is decomposing the traditional single-volume paradigm into expandable seasonal configurations. Overlanding enthusiasts and national park visitors in the United States are adopting clip-on capacity extensions at accelerating rates. This technology is decomposing the replacement cycle logic that previously treated cargo boxes as decade-long durable goods purchases.
REACH substance restrictions in Europe are forcing reformulation of adhesives and sealants used in waterproof gasket manufacturing. Industrial consequence includes accelerated supplier qualification timelines and migration toward silicone-free alternatives. Premium cargo box manufacturers serving German and Nordic markets are responding with captive compound development and vertical control over polymer supply chains.
Direct-to-consumer configuration tools now allow buyers to spec mounting hardware, interior divider systems, and color-matched shells through brand-owned digital channels. Specialty outdoor retailers face disintermediation pressure as manufacturers capture first-party data and margin recovery from bypassed wholesale tiers. This shift concentrates in the United States where REI and Backcountry have historically controlled premium cargo box distribution.
Vehicle Cargo Box Market Segmentation
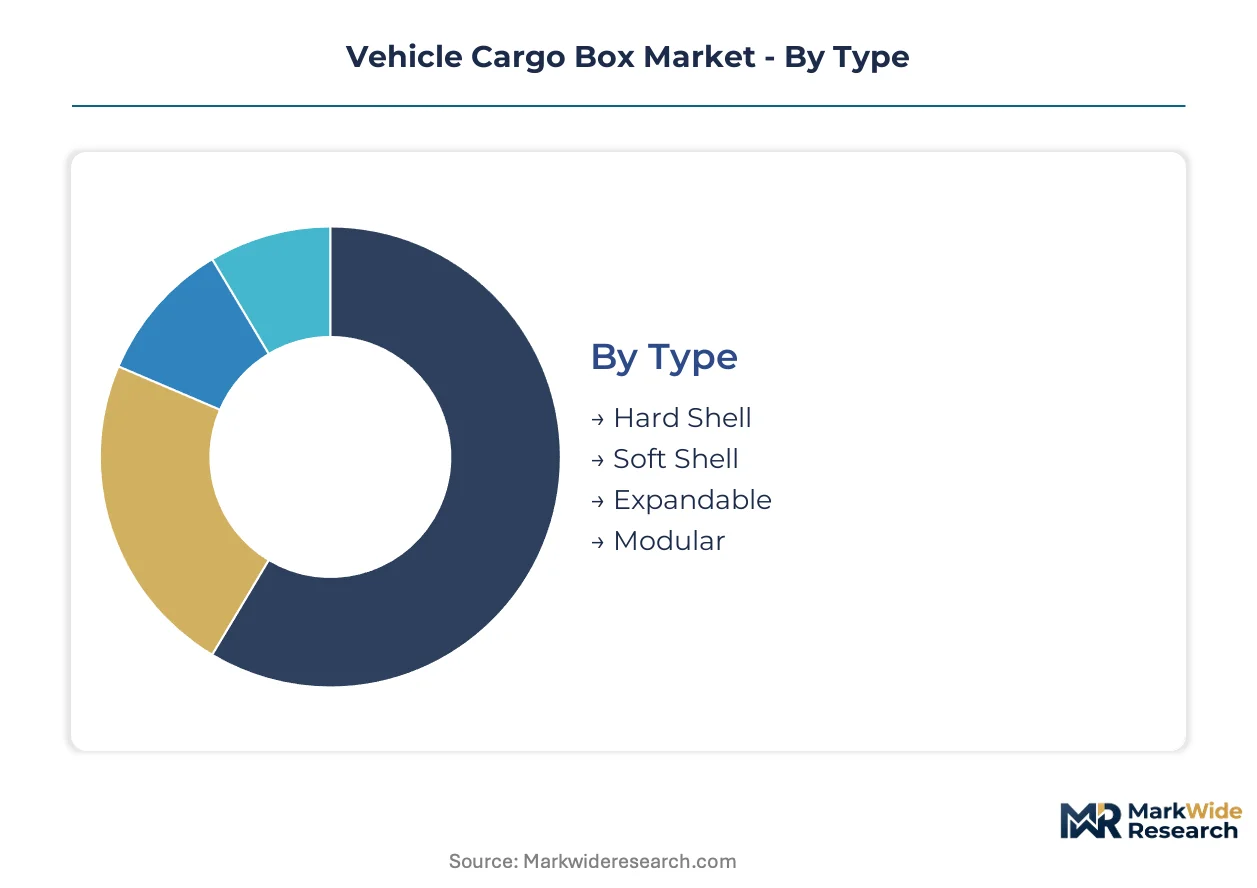
Vehicle cargo box segmentation reveals how manufacturers balance aerodynamic engineering against cost structures and regional regulatory compliance. Distinct margin pools emerge across material tiers and installation complexity, with premium positioning concentrated where NHTSA certification and lightweight construction intersect.
Type:
Margin pools concentrate in configurations that command theft-resistance premiums and seasonal adaptability.
- Hard Shell:Vacuum-formed ABS or impact-modified acrylic construction delivers structural rigidity at highway speeds and IP55 waterproof sealing. Demand concentrates among United States SUV owners visiting national parks, where theft resistance and weatherproofing justify replacement cycles over soft alternatives.
- Modular:Clip-on capacity extensions enable seasonal reconfiguration from ski to camping gear. Overlanding enthusiasts in Colorado and Utah are adopting these systems fastest, decomposing traditional decade-long purchase cycles into expandable hardware ecosystems.
- Soft Shell:Fabric-based collapsible designs occupy value-tier positioning for occasional recreational users.
- Expandable:Telescoping volume adjustments address electric vehicle range concerns through reduced drag when collapsed.
The dominant share belongs to Hard Shell, while Modular is closing the gap fastest.
Material:
Cost tier stratification separates premium weight-reduction plays from mass-market petrochemical dependence.
- Plastic:Thermoformed polymers occupy the largest tonnage position due to vacuum-forming scalability and color-matching flexibility. Mass-market retail partnerships in the United States depend on ABS and acrylic resin cost stability, though crude oil derivative volatility compresses margin pools for value-tier manufacturers.
- Aluminum:Skin-and-frame construction commands premium positioning where Tesla, Rivian, and Ford Lightning owners prioritize range preservation. German and Nordic markets under REACH substance restrictions favor aluminum for silicone-free gasket compatibility.
- Composite:Carbon fiber hybrid laminates serve hyper-premium overlanding segments in the Pacific Northwest.
- Steel:Legacy stamped construction persists in commercial fleet applications requiring maximum load ratings.
Plastic retains volume leadership, though Aluminum is expanding most quickly in premium electric vehicle-compatible lines.
Size:
Application-driven demand patterns correlate with vehicle class ownership and trip duration profiles.
- Full-Size:18-22 cubic foot capacity dominates family overlanding configurations for week-long national park excursions. United States crossover owners with third-row seating deletion choose this segment for maximum gear-to-vehicle integration.
- Mid-Size:14-17 cubic foot designs balance aerodynamic penalty against weekend trip utility. Ski-and-bike crossover buyers at specialty outdoor retailers favor this segment for seasonal rotation flexibility.
- Compact:Sub-14 cubic foot positioning serves urban apartment dwellers with limited storage.
- Oversized:23+ cubic foot extreme capacity targets expedition-grade overlanding with roof tent compatibility.
Full-Size captures the dominant share, while Mid-Size is gaining share fastest through bike-ski bundling at specialty retailers.
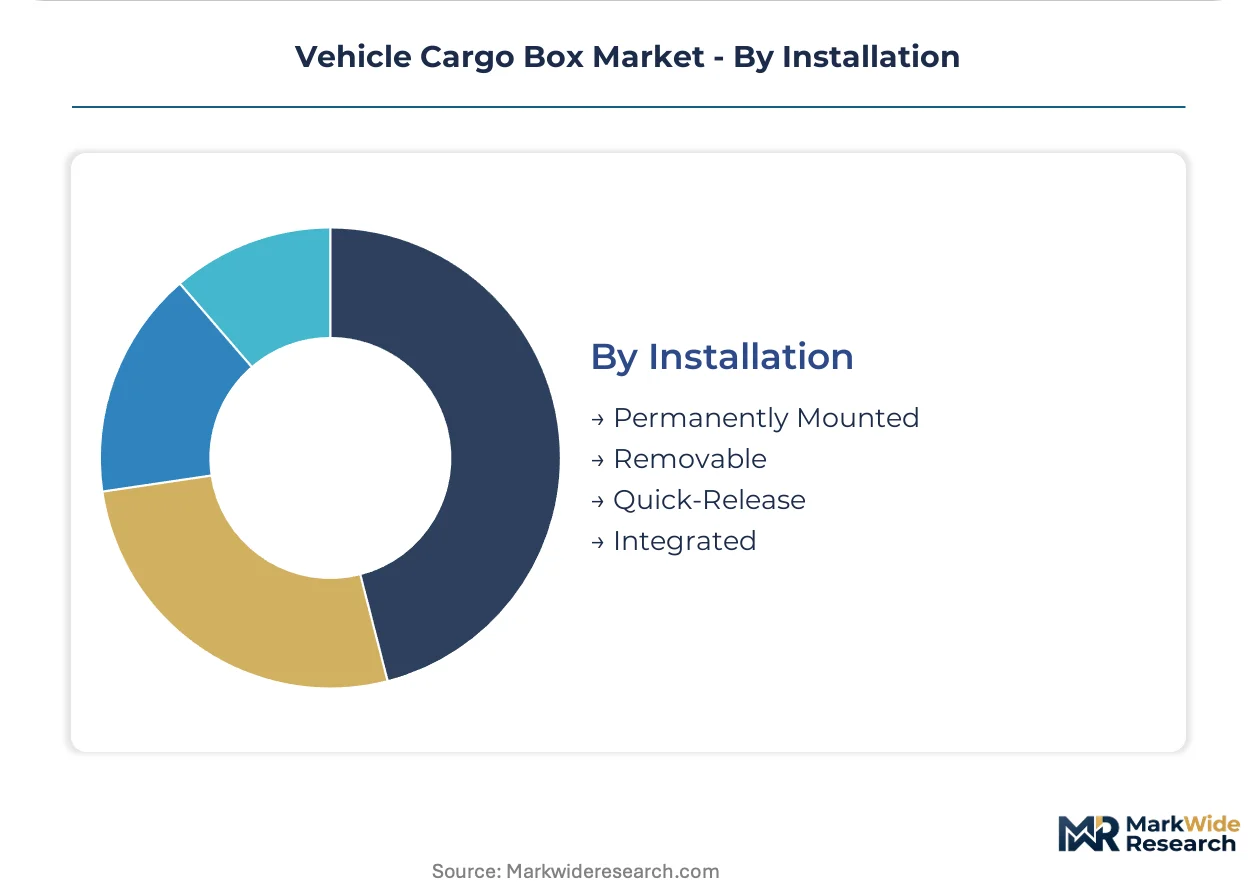
Installation:
Customer type differentiation separates permanent fleet operators from seasonal recreational users seeking garage clearance.
- Removable:Tool-free detachment systems dominate United States consumer preferences where garage height restrictions and seasonal use patterns predominate. REI and Backcountry bundling strategies emphasize quick removal for bike rack substitution.
- Quick-Release:Lever-actuated mounting hardware addresses electric vehicle owner concerns about charging port access and automated car wash compatibility.
- Permanently Mounted:Commercial fleet applications and overland build-outs prioritize theft elimination.
- Integrated:Factory-installed roof rail systems from automotive OEMs capture first-fit positioning in premium SUV trims.
Removable systems hold the dominant share, while Quick-Release is climbing the fastest among electric vehicle owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA roof load rating standards anchor United States demand, while ECE R14 mounting regulations and China's GB/T framework shape certification requirements across their respective markets. National park visitation patterns and overlanding culture concentrate premium uptake in specific geographic clusters.
United States
Overlanding enthusiasts in Colorado and Utah drive modular cargo box adoption for seasonal ski-to-camping transitions. NHTSA Federal Motor Vehicle Safety Standard 110 governs roof load ratings and consumer trust premiums. Denver and Salt Lake City anchor specialty outdoor retail distribution networks serving Rocky Mountain national park corridors.
Germany
REACH substance restrictions accelerate silicone-free gasket reformulation among premium manufacturers serving Nordic markets. ECE R14 mounting point regulations force region-specific hardware engineering distinct from NHTSA protocols. Stuttgart and Munich industrial clusters concentrate automotive supplier expertise transferable to aerodynamic cargo box design.
China
GB/T vehicle exterior accessory standards create certification pathways for domestic manufacturers expanding into export markets. MIIT oversight of automotive component quality shapes product testing requirements. Yangtze River Delta manufacturing hubs around Shanghai and Suzhou dominate thermoformed polymer production capacity for value-tier export lines.
Canada
Cross-border outdoor recreation patterns mirror United States overlanding demand with concentrated uptake in British Columbia and Alberta. Transport Canada aligns with NHTSA roof load standards while maintaining distinct CMVSS certification requirements. Vancouver and Calgary anchor specialty retail networks serving Pacific Northwest and Rocky Mountain tourism corridors.
Australia
Remote-area touring culture sustains demand for expedition-grade cargo capacity in Western Australia and Northern Territory. ADR vehicle standards govern roof rack mounting integrity for outback highway conditions. Perth and Darwin serve as distribution nodes for remote-area overlanding equipment serving mining and tourism sectors.
Vehicle Cargo Box Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market structure. Premium positioning concentrates among European heritage brands with captive distribution networks, while value-tier penetration depends on mass-market retail partnerships with controlled cost structures. Two strategic archetypes dominate: design-forward integrated manufacturers and specialty outdoor bundlers. Competitive moves center on aerodynamic engineering talent acquisition and direct-to-consumer channel expansion that bypasses wholesale tiers.
Within the heritage-brand archetype, Thule Group AB and SportRack represent distinct positioning approaches—one leveraging European design pedigree, the other anchoring value-tier mass-market penetration. Yakima Products, Inc. exemplifies the specialty outdoor bundler model through bike-and-ski crossover strategies. These three companies occupy positions that span the vertical tier structure, with each representing a different route to margin capture in a market shaped by certification complexity and seasonal demand patterns.
| Leading Market Players |
|---|
| SportRack |
| Flated |
| Yakima |
| Pelican |
| MeeFar |
| Thule |
| Rightline Gear |
| Enthuze |
| Inno |
| Others |
Value Network & Pricing Analysis
NHTSA roof load certification gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb fixed testing costs that stratify margin pools across scaled and emerging producers while petrochemical volatility compresses value-tier positioning.
Pricing Analysis
Long-term offtake contracts between ABS resin processors and thermoforming specialists anchor cost predictability for scaled manufacturers, while spot-market exposure punishes value-tier brands. Pricing stratifies across premium, standard, and economy tiers based on certification grade and aerodynamic engineering investment. Cost compression in economy lines intensifies because crude derivative volatility feeds directly into margin pressure. Fleet procurement managers show highest price sensitivity, whereas overlanding enthusiasts prioritize theft-resistance premiums.
Supply Chain Analysis
China and the United States dominate thermoformed polymer production, with Yangtze River Delta hubs feeding export lines and Michigan-Ohio industrial corridors serving domestic certification requirements. Raw material flows draw from Saudi Arabian petrochemical feedstock, German automotive-grade resin compounding, and Taiwanese precision molding equipment. Single-source vulnerability concentrates in impact-modified acrylic supply where three compounders control specialty grades. Distribution runs through captive direct-to-consumer channels, specialty outdoor retail partnerships, and mass-market big-box placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle compatibility requirements fragment demand into aerodynamic-optimized niches that reward specialist engineering over commodity scale, creating entry points for focused competitors.
For Market Incumbents: Shield premium positioning by deepening captive control over thermoformed polymer supply chains and accelerating NHTSA-ECE harmonization lobbying to unlock SKU consolidation. Rooftop tent substitution threatens traditional cargo box attachment rates, demanding defensive bundling with sleep-system partnerships. Aerodynamic engineering talent scarcity in computational fluid dynamics warrants targeted acquisition of automotive supplier specialists. For New Entrants and Emerging Players: Quick-release mounting hardware for electric vehicle owners represents a service-layer gap where incumbents under-serve charging-port access concerns. Target Pacific Northwest overlanding communities through direct-to-consumer configuration tools that bypass REI and Backcountry wholesale capture. Go-to-market leverage rests on range-anxiety messaging paired with drag-coefficient validation data. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermoformed polymer tooling as REACH-compliant silicone-free gasket development demands captive R&D infrastructure. Long-term viability favors vertically integrated manufacturers with regional certification breadth rather than pure-brand plays. Acquisition targets should demonstrate ECE R14 and NHTSA dual-certification capability. Watch GB-T standard alignment negotiations as inflection signal for China export pathway economics.| Strategic Initiative | Industry Significance |
|---|---|
| Aerodynamic Engineering Talent Acquisition | Computational fluid dynamics expertise from automotive suppliers enables low-drag designs for Rivian and Tesla owners. |
| Direct-to-Consumer Channel Expansion | Brand-owned digital configuration tools capture first-party data and margin recovery from bypassed wholesale tiers. |
| REACH-Compliant Gasket Development | Silicone-free sealant reformulation opens German and Nordic premium positioning under substance restrictions. |
| Modular Capacity Extension Systems | Clip-on seasonal reconfigurations decompose decade-long purchase cycles into recurring hardware ecosystem spending. |
| Electric Vehicle Drag Optimization | Reduced coefficient designs address range anxiety among Ford Lightning and Rivian R1S overlanding buyers. |
Research Methodology
Operator-level perspectives from thermoforming plant managers, specialty outdoor retail category buyers, automotive OEM accessory integration engineers, and NHTSA certification consultants anchored the qualitative base. Secondary validation drew from customs trade data, SEC 10-K filings of publicly traded equipment manufacturers, vehicle production databases, and national park visitation statistics. Bottom-up SKU-level shipment analysis triangulated against top-down consumer spending estimates across the analysis window.
Sensitivity analysis tested forecast outputs against petrochemical price volatility scenarios, regulatory harmonization timing assumptions, and electric vehicle adoption curve variations. Segmentation modeling spanned type configuration, material grade tier, installation complexity, and regional certification cluster. CAGRs derived from historical shipment trajectories, replacement cycle compression indicators, and seasonal demand pattern elasticity. Industry-specific inputs included roof load rating compliance timelines and aerodynamic engineering labor market tightness indices.
Forecasts assume regulatory continuity in NHTSA, ECE R14, and GB-T regimes; material policy shifts would require re-modeling. Specific risks include REACH substance restriction expansion, rooftop tent technology substitution acceleration, and petrochemical supply disruption. Recalibration cycles align with material shifts in electric vehicle platform architectures and national park visitation trend inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Transmission Components Market
Vehicle Components
Bicycle Lights Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Rear Axle Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
EGR Coolers Market