
 Global Automotive Side Turn Indicator Market | 2026-2036
Global Automotive Side Turn Indicator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Side Turn Indicator Market Intelligence
The distinction between OEM-spec and premium aftermarket dynamic indicators is collapsing, creating new competition based on features rather than just fitment. Valeo leverages its deep integration with European automakers to lead in advanced systems. Meanwhile, Hella GmbH & Co. KGaA differentiates through its focus on modular LED components, while Koito Manufacturing sustains a dominant position in the Asian OEM supply chain.
An automotive side turn indicator is a lighting assembly, typically mounted on a vehicle's fender or integrated into the side-view mirror housing. It functions to signal lane changes and turns to other road users, operating at a specific flash frequency and amber color spectrum defined by regulations. LED indicators are rapidly displacing older halogen units due to superior longevity and energy efficiency. Within the technology segment, sequential lighting represents a high-margin feature increasingly common in new passenger vehicles.
Product design and market access are governed by a matrix of international and national standards. Key frameworks include the U.S. National Highway Traffic Safety Administration's (NHTSA) FMVSS 108, UNECE regulations prevalent in Europe and Japan, and China's GB standards. These rules dictate minimum photometric performance, visibility angles, and material durability. Suppliers must navigate the convergence of these standards as vehicle platforms become more unified.
Market Dynamics
The market's primary dynamic is the regulatory push for enhanced vehicle conspicuity converging with the technological shift toward feature-rich LED systems. This interplay forces a re-evaluation of lighting as a safety-critical system rather than a simple commodity component, influencing both design and supply chain strategies.
Growth Catalysts
- UNECE Regulations:Mandates on photometric performance and visibility angles, particularly for dynamic turn signals, compel automakers in Europe and other adopting markets to upgrade from static halogen or LED units.
- Passenger Vehicle Aesthetics:The adoption of sequential and dynamic lighting as a brand differentiator in new passenger vehicle models creates strong pull-through demand for advanced indicator modules from OEMs.
- LED Technology Maturation:The superior energy efficiency, extended operational lifespan, and design flexibility of light-emitting diodes are accelerating the phase-out of legacy halogen bulb-based indicators across all vehicle segments.
Market Restraints
- Higher Unit Cost:The upfront cost for dynamic LED indicator assemblies, including control electronics, remains significantly higher than for traditional halogen units, limiting adoption in economy vehicle segments and some commercial fleets.
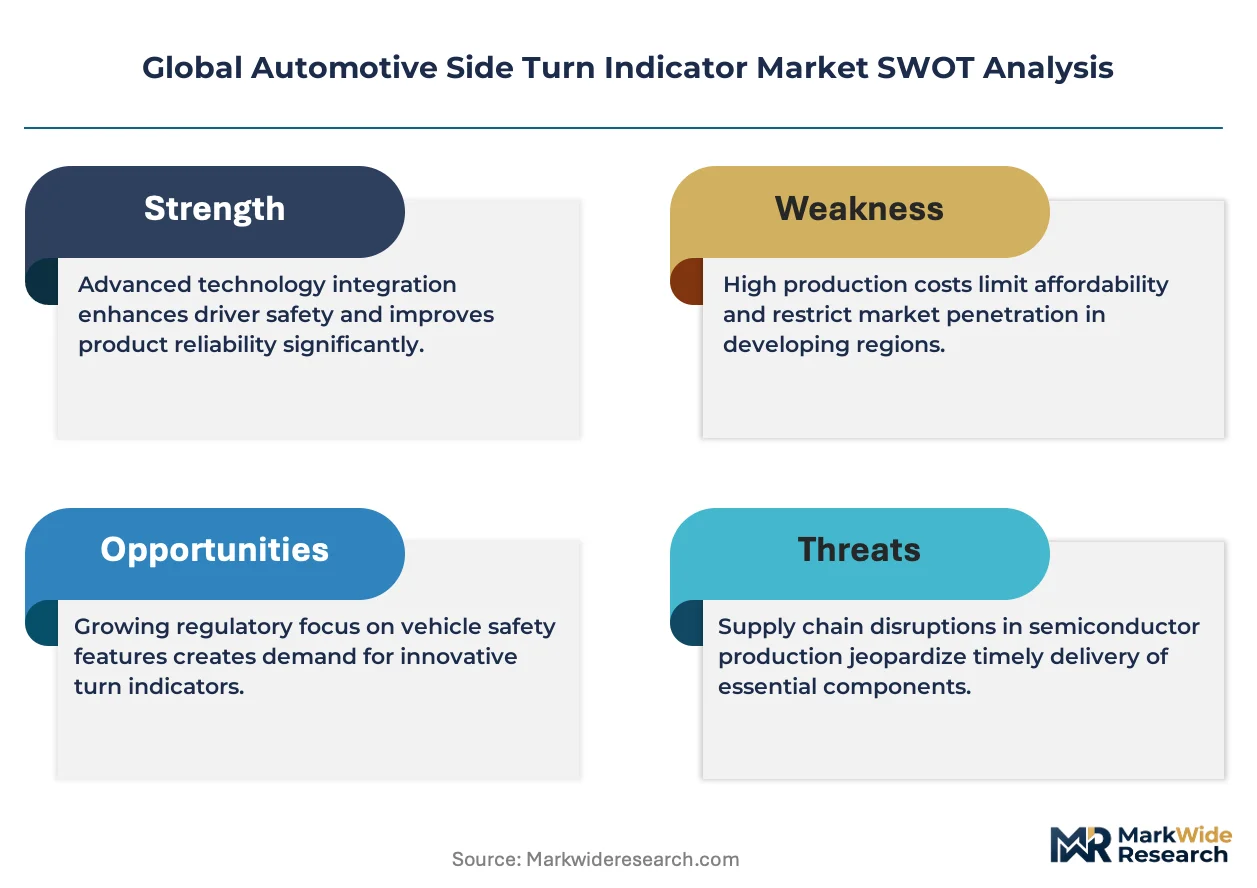
- Semiconductor Dependencies:Advanced sequential indicators rely on specific microcontrollers and driver ICs, exposing the supply chain to the volatility and allocation challenges of the broader semiconductor market.
- Standardization Gaps:Divergence between key regulatory frameworks like NHTSA's FMVSS 108 and UNECE rules creates design and testing complexities for automakers aiming to use single-part solutions on global vehicle platforms.
Strategic Opportunities
- Commercial Vehicle Upgrades:The large, existing global fleet of commercial trucks and buses represents an underpenetrated segment for LED side indicator retrofits, driven by fleet operator interest in reducing maintenance costs and improving safety.
- Lighting and Sensor Fusion:Integrating side indicator functions into smart modules that also house blind-spot monitoring radar or camera systems offers a pathway to higher-value assemblies and deeper integration into vehicle ADAS architecture.
- Aftermarket Customization:A growing market exists for plug-and-play aftermarket sequential indicator kits, allowing owners of older vehicles to upgrade to modern lighting aesthetics, creating a new direct-to-consumer channel.
Industry Challenges
- Multi-Standard Compliance Burden:Suppliers face long and costly validation processes to certify a single product design against the distinct photometric, material, and environmental testing requirements of US, European, and Chinese standards.
- Software Integration Complexity:Ensuring flawless communication between dynamic indicator modules and a vehicle's central body control module (BCM) requires sophisticated software development and testing to prevent errors or latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Side Turn Indicator Market |
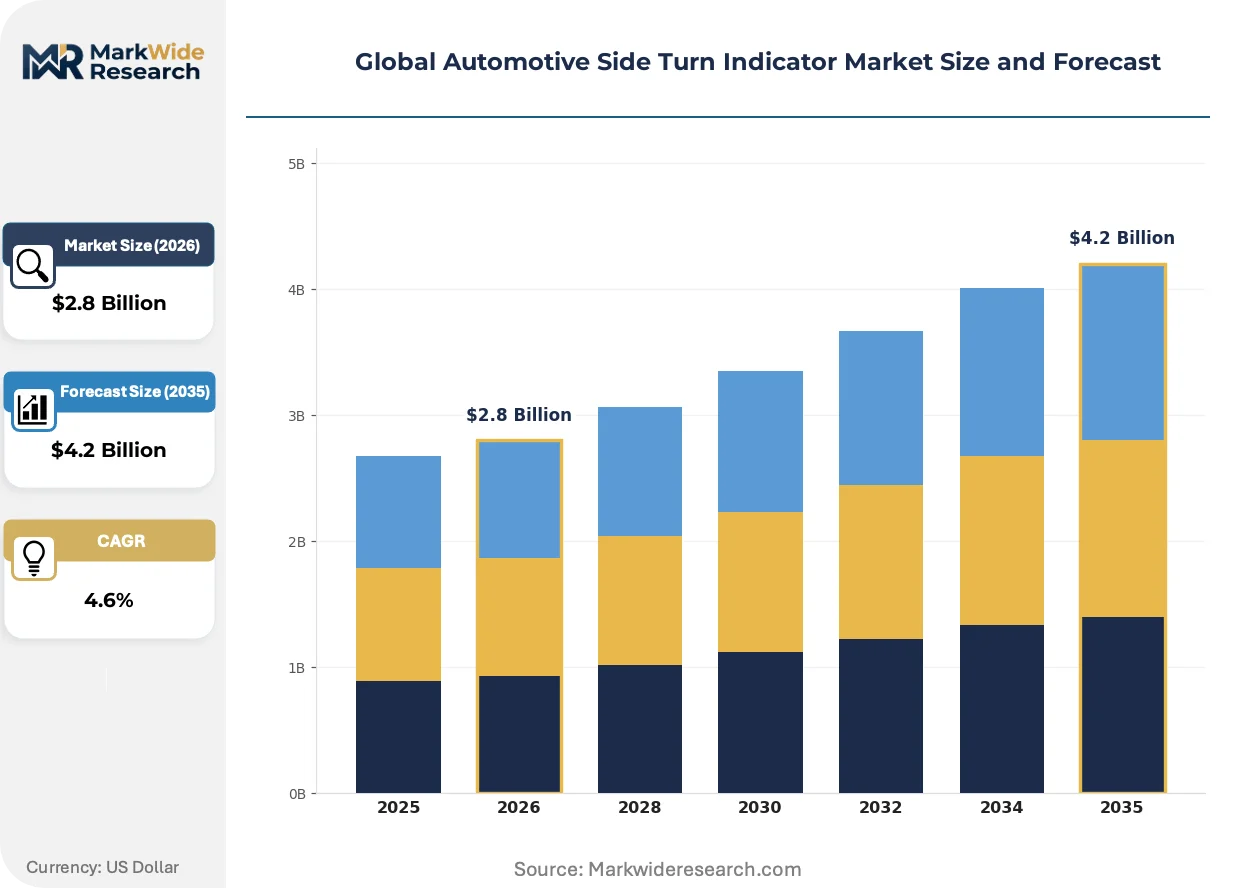
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Indicators, Halogen Indicators, Xenon Indicators, OLED Indicators Technology: Sequential Lighting, Conventional Flashing, Adaptive Lighting, Integrated Signaling, Wireless Indicators Application: Passenger Vehicles, Commercial Transport, Two-Wheelers, Off-Road Vehicles, Agricultural Machinery End User: OEMs, Tier-1 Manufacturers, Aftermarket Suppliers, Fleet Operators |
| Companies Covered | Valeo, Hella GmbH & Co. KGaA, Koito Manufacturing, Stanley Electric, Osram, Magneti Marelli, Mitsuba Corporation, TYC Brother, Federal-Mogul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Side Turn Indicator Market Strategic Shifts & Innovations
The evolution from simple functional lighting to communicative, style-defining components is the dominant theme. This shift is driven by technological advancements in light sources and electronics, creating new possibilities for vehicle design and on-road safety signaling.
Advanced LED modules are the core enabling technology for modern indicator designs. These components package high-intensity light sources and optics into compact, efficient units. Automakers in the premium and mid-range passenger vehicle segments are rapidly adopting them to create signature lighting elements. This technology is miniaturizing the entire indicator assembly, which allows designers to integrate sleek, aerodynamic lighting strips directly into mirror housings and fender lines.
China's GB standards for vehicle lighting are becoming a critical compliance checkpoint for global automakers. These regulations increasingly align with UNECE principles but often include unique requirements for performance and durability tailored to the domestic market. Consequently, suppliers must now treat GB certification as a distinct development gate, often requiring platform-specific adjustments to lighting hardware or control software for vehicles sold in China.
Consumer demand for aesthetic customization is reshaping the aftermarket parts channel. A clear preference is emerging for plug-and-play dynamic indicator kits that replicate the visual effects of high-end OEM systems. This trend disrupts traditional distribution by favoring specialist e-commerce retailers over generalist parts stores. The pattern is most pronounced in North America and Europe, where a robust car culture supports a vibrant vehicle modification scene.
Global Automotive Side Turn Indicator Market Segmentation
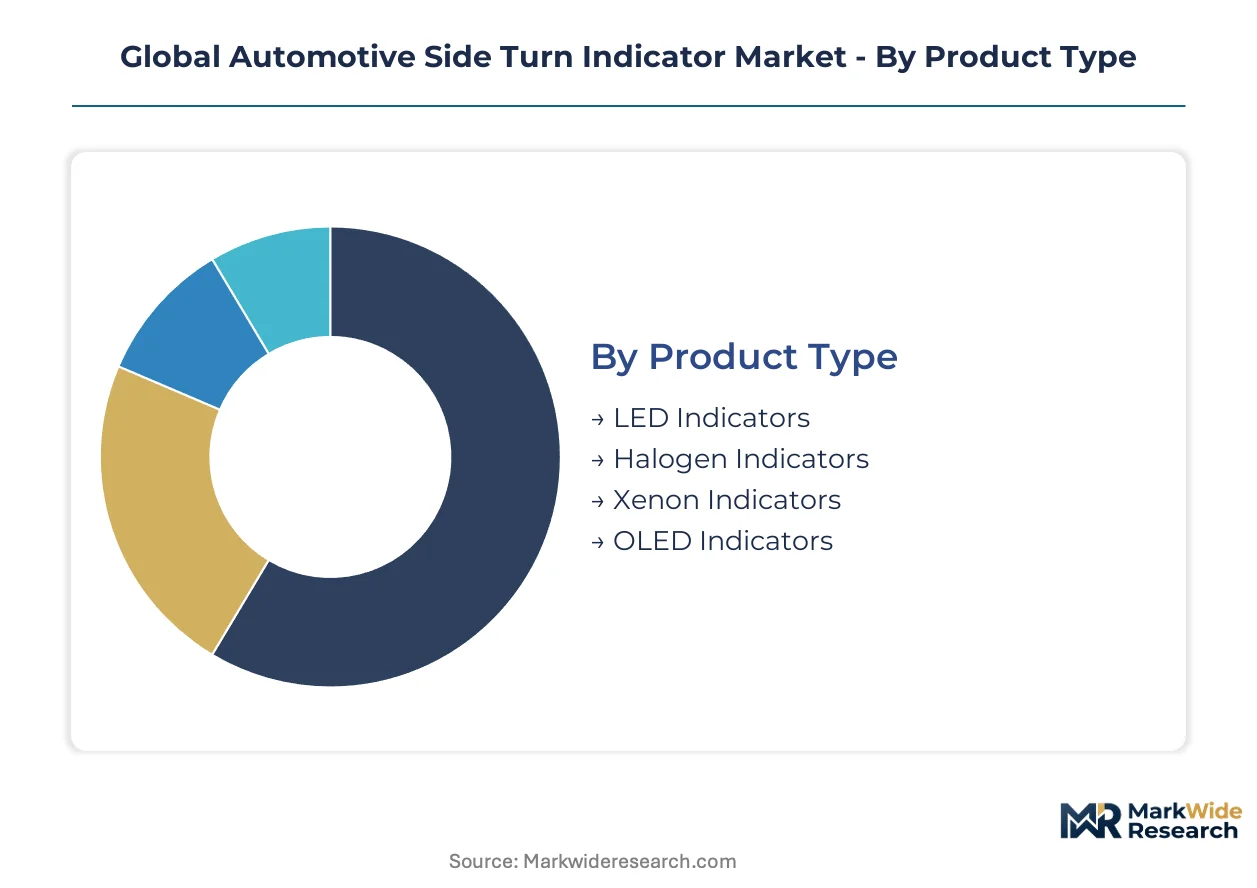
The global automotive side turn indicator market differentiates across several key dimensions, reflecting diverse technological adoption, vehicle applications, and end-user requirements. Understanding these segments is critical for manufacturers to align product development with specific demand pockets and regulatory landscapes.
Product Type:
Margin pools within the product type category heavily favor advanced lighting technologies that offer superior performance and design flexibility. These innovations allow for greater aesthetic integration and functional differentiation in modern vehicles.
- LED Indicators:These units utilize light-emitting diodes, providing superior energy efficiency, extended operational lifespan, and compact form factors compared to traditional bulbs. Demand concentrates in Europe and China, driven by stringent energy efficiency standards and consumer preference for modern vehicle aesthetics.
- OLED Indicators:Organic light-emitting diode indicators offer ultra-thin, flexible, and homogeneously lit surfaces, enabling innovative design possibilities and advanced signaling patterns. Adoption is primarily concentrating in premium passenger vehicle segments, particularly in Germany, for high-end aesthetic differentiation.
- Halogen Indicators:These traditional incandescent bulbs represent the legacy technology, characterized by lower upfront cost and simpler electrical integration.
- Xenon Indicators:High-intensity discharge (HID) lamps, while brighter than halogen, are less common for turn signals due to warm-up times and complex ballast requirements.
The dominant share belongs to LED Indicators, while OLED Indicators are closing the gap fastest.
Technology:
Cost tiering within side turn indicator technology varies significantly, with advanced sequential and adaptive systems commanding higher price points due to their complex control electronics and software integration. Simpler conventional flashing units occupy the economy segment.
- Sequential Lighting:These systems illuminate individual LEDs in a progressive, outward-sweeping pattern, enhancing visual prominence and signaling clarity for lane changes. Demand is concentrating in new passenger vehicle models across North America and Europe, serving as a premium aesthetic feature.
- Adaptive Lighting:Integrating with vehicle sensors, adaptive indicators can adjust brightness or flash patterns based on ambient conditions or driver input, improving visibility. This technology is gaining traction in luxury and semi-autonomous vehicles, particularly in Japan, for enhanced safety features.
- Conventional Flashing:This standard technology involves all indicator lights flashing simultaneously, representing the most basic and widely adopted form of turn signaling.
- Integrated Signaling:This refers to turn indicators seamlessly incorporated into other lighting assemblies or body panels, reducing component count and improving vehicle aerodynamics.
- Wireless Indicators:These are conceptual or niche applications, potentially involving short-range communication for external signaling devices, but face regulatory and reliability hurdles.
Sequential Lighting currently holds the largest share, with Integrated Signaling expanding most quickly.
Application:
The application landscape for side turn indicators is heavily weighted towards passenger vehicles, where aesthetic integration and dynamic features are pivotal. Commercial vehicles prioritize durability and regulatory compliance, while other segments focus on basic functionality.
- Passenger Vehicles:This segment includes sedans, SUVs, and hatchbacks, where side turn indicators are increasingly integrated into mirror housings or fender lines as LED-based, dynamic lighting elements. Demand concentrates in China's rapidly expanding automotive manufacturing sector, driven by new model introductions.
- Commercial Transport:This category encompasses trucks, buses, and vans, where robust and highly visible side indicators are essential for safety and compliance with heavy vehicle regulations. Fleet operators in Germany are increasingly upgrading to LED units for improved longevity and reduced maintenance.
- Two-Wheelers:Motorcycles and scooters utilize compact side indicators, often integrated into handlebars or fairings, to signal directional changes.
- Off-Road Vehicles:ATVs, UTVs, and other specialized off-road machinery require durable and weather-resistant indicators for signaling in challenging environments.
- Agricultural Machinery:Tractors and other farm equipment employ highly visible, often larger, side indicators to ensure safety during road travel and field operations.
Passenger Vehicles command the largest volume, driven by aesthetic integration and regulatory mandates.
End User:
Customer type influences procurement strategies, with OEMs demanding high-volume, custom-engineered solutions for new vehicle platforms, while aftermarket suppliers cater to replacement and upgrade needs for existing vehicles.
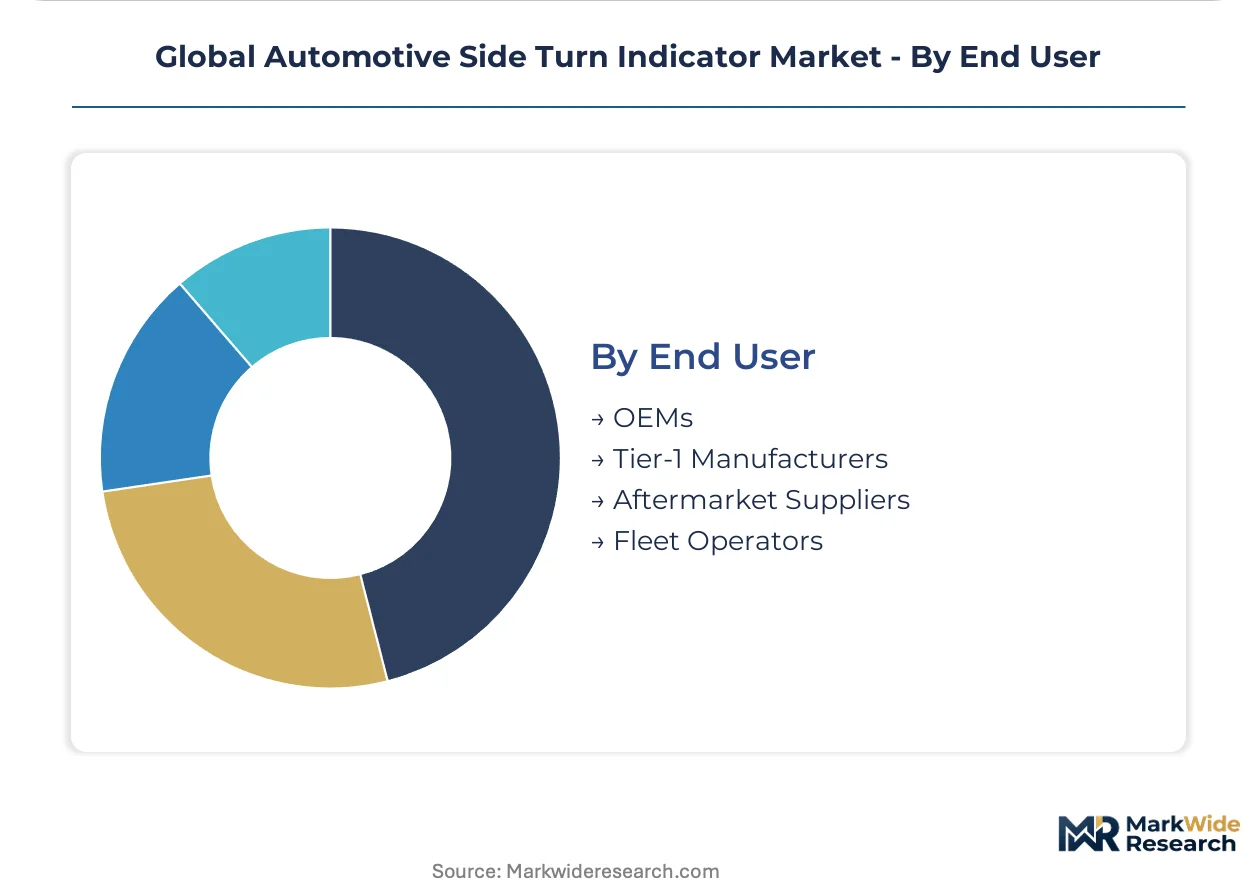
- OEMs:Original Equipment Manufacturers integrate side turn indicators directly into their vehicle production lines, requiring high levels of customization, quality assurance, and long-term supply agreements. Automakers in Japan prioritize seamless integration and long-term reliability for their vehicle platforms.
- Tier-1 Manufacturers:These suppliers develop and produce complete lighting modules or sub-assemblies for OEMs, often incorporating advanced technologies and handling complex integration challenges.
- Aftermarket Suppliers:Companies in this segment provide replacement parts and upgrade kits for vehicles already in operation, catering to repair needs and aesthetic customization trends. Demand for aftermarket customization is particularly strong in North America.
- Fleet Operators:Businesses managing large vehicle fleets, such as logistics companies or public transport agencies, procure indicators for maintenance, repair, and upgrades to ensure operational safety and compliance.
OEMs represent the foundational demand, while the aftermarket channel continues to diversify its offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive side turn indicator market exhibits a complex interplay between exporting manufacturing hubs and importing consumer markets. High-volume production in specific countries often supplies diverse end-user demands worldwide. This dynamic shapes regional investment in advanced lighting technologies and regulatory compliance.
China
Demand for dynamic LED indicators strongly concentrates in China's rapidly expanding automotive manufacturing sector. China's GB standards increasingly align with UNECE principles, requiring distinct performance and durability for domestic vehicles. Automakers in cities like Shanghai and Guangzhou prioritize advanced lighting for new model introductions.
Germany
German fleet operators increasingly upgrade commercial vehicles to LED units for improved longevity and reduced maintenance costs. UNECE regulations, prevalent in Germany, mandate photometric performance and visibility angles for dynamic turn signals. The automotive cluster in Stuttgart focuses on integrating advanced systems into premium passenger vehicles.
Japan
Japanese automakers prioritize seamless integration and long-term reliability for OEM side turn indicator platforms. METI guidelines and JIS standards influence the adoption of adaptive lighting technology in luxury and semi-autonomous vehicles. Manufacturing hubs in Aichi Prefecture focus on high-quality component production for global supply chains.
United States
Aftermarket customization for side turn indicators shows strong demand in North America, particularly the United States. NHTSA's FMVSS 108 standards dictate minimum photometric performance and visibility angles for all vehicle lighting. The Detroit automotive cluster drives innovation in both OEM and aftermarket lighting solutions.
South Korea
South Korea's robust automotive manufacturing sector drives significant demand for advanced LED indicator modules. The Korean Agency for Technology and Standards (KATS) influences vehicle component specifications and quality. Major automotive production facilities near Seoul and Ulsan integrate feature-rich lighting into new vehicle platforms.
Global Automotive Side Turn Indicator Market Key Industry Players
Listed leaders compete with private specialists across technology development and global market access. The automotive side turn indicator market exhibits a tiered structure, with established OEMs and Tier-1 suppliers driving innovation in integrated lighting systems. Key archetypes include vertically integrated full-system providers and specialized modular component manufacturers. Strategic partnerships for ADAS integration and portfolio diversification into aftermarket solutions represent dominant competitive moves.
Specialists in advanced lighting systems include Valeo, a French automotive supplier known for its deep integration with European automakers and advanced system development. German-based Hella GmbH & Co. KGaA exemplifies a modular LED component manufacturer, focusing on differentiation through flexible and customizable solutions for various vehicle platforms. Koito Manufacturing, a Japanese company, maintains a dominant position within the Asian OEM supply chain, particularly for its reliability and scale in lighting components. These entities collectively anchor the market's premium and mid-tier segments, influencing technology adoption and supply chain dynamics globally.
| Leading Market Players |
|---|
| Valeo |
| Hella GmbH & Co. KGaA |
| Koito Manufacturing |
| Stanley Electric |
| Osram |
| Magneti Marelli |
| Mitsuba Corporation |
| TYC Brother |
| Federal-Mogul |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements in the automotive sector lock in both component availability and price visibility for OEM buyers. This contract structure mitigates volatility for both suppliers and vehicle manufacturers over production cycles.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for side turn indicators. Price differentiation stems from UNECE certification levels, advanced feature sets like sequential lighting, and customization requirements. Pricing pressure intensifies for basic LED units due to increasing competition among Tier-1 suppliers. Economy vehicle segments exhibit the highest price sensitivity, while premium passenger vehicle manufacturers prioritize feature integration over marginal cost reductions.
Supply Chain Analysis
Semiconductor allocation challenges underwrite volatility within the automotive side turn indicator supply chain, impacting production in China, Japan, and Germany. The industry heavily relies on microcontrollers, driver ICs, and specialized LED dies. Single-source vulnerability for advanced electronic components presents a structural risk to global vehicle platforms. Distribution primarily runs through Tier-1 manufacturers supplying OEMs, with a growing aftermarket channel catering directly to consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive side turn indicator market is experiencing a buyer-power shift, driven by increasing OEM consolidation into global vehicle platforms. This dynamic forces suppliers to adapt product strategies for broader market reach.
For Market Incumbents: Compound existing OEM relationships by deepening software integration capabilities for advanced dynamic systems. Invest in R&D to mitigate semiconductor dependencies, a persistent threat to production stability. Strengthen multi-standard compliance expertise for UNECE, NHTSA, and GB regulations to reduce validation costs. Vertical integration into control electronics can secure critical component supply.
For New Entrants and Emerging Players: Lead with plug-and-play aftermarket sequential indicator kits, targeting the aesthetic customization segment in North America and Europe. Commercial vehicle upgrades represent another penetrable segment, offering retrofit LED units for improved longevity. A direct-to-consumer e-commerce model can bypass traditional distribution channels. Focus on ease of installation and regulatory compliance for these specific markets.
For Investors and Strategic Acquirers: Capital is best deployed toward modular LED component manufacturers and software integration specialists poised for long-term growth over the next 5-10 years. These archetypes will benefit from the ongoing transition to advanced dynamic lighting and ADAS integration. Acquisitions should target firms with strong intellectual property in lighting and sensor fusion. The signal to watch is increasing standardization of global vehicle lighting regulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Integration for Dynamic Lighting | Enhances communication between indicator modules and vehicle body control systems. |
| Global Platform Standardization | Reduces multi-standard compliance burden for OEMs and Tier-1 suppliers. |
| Localized Manufacturing Expansion | Optimizes supply chain resilience and reduces lead times in key automotive regions. |
| Advanced LED Module Licensing | Accelerates adoption of high-margin sequential and adaptive lighting features across vehicle segments. |
| ADAS Lighting Integration Partnerships | Creates higher-value assemblies by combining indicators with blind-spot monitoring systems. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings. This involved discussions with OEM procurement managers, Tier-1 R&D directors, aftermarket distributors, and fleet operators. Secondary validation drew from vehicle production databases, UNECE regulations, NHTSA FMVSS 108, and company annual filings. A combined bottom-up and top-down triangulation approach ensured data accuracy.
Sensitivity analysis formed a core component of the forecast framework across the analysis window. The quantitative model segmented the market by product type, technology, application, end-user, and key regional production clusters. Compound annual growth rates were derived through historical data extrapolation and regression analysis. New vehicle model introductions and evolving regulatory mandates served as critical forecast inputs.
Forecasts assume regulatory continuity in UNECE, NHTSA, and GB regimes; material policy shifts would require re-modeling. The projections reflect current market dynamics and geopolitical trade tensions. Practitioners should keep alternative scenarios live as semiconductor supply chain conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Digital Isolators Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Automotive Cell Contact System Carrier Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market