
 Automotive X-By-Wire System Market | 2026-2036
Automotive X-By-Wire System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive X-By-Wire System Market Insights
Copper-dense wiring harnesses are recalibrating cost structures as fiber-optic and high-speed Ethernet backbones replace legacy copper in x-by-wire architectures. Continental AG leverages its integrated sensor-actuator platforms to sustain design wins across European OEM programs. ZF Friedrichshafen AG anchors brake-by-wire production through its IBC platform, while Infineon Technologies AG dominates silicon carbide gate driver supply for electric actuator modules.
Automotive x-by-wire systems replace mechanical linkages with electronic interfaces that transmit driver inputs via electric actuators, sensors, and control units communicating over deterministic protocols such as FlexRay and automotive Ethernet with sub-10 millisecond latency requirements. Brake control and steering control command the largest installed bases, though shift control is displacing conventional cable mechanisms fastest in electric vehicle platforms where park-by-wire integration simplifies cabin packaging. OEMs capture the deepest margin pools through captive software stacks, while tier-1 suppliers compete hardest on actuator hardware commoditization.
NHTSA FMVSS 126 stability control mandates and UNECE R79 steer-by-wire provisions are forcing redundant electronic architectures with dual-channel fail-operational designs. EPA tailpipe rules and the EU Green Deal's fleet CO2 targets are accelerating electric vehicle penetration, which in turn expands addressable volume for x-by-wire systems that enable modular skateboard platforms. Stakeholders must monitor functional safety certification timelines and semiconductor supply allocation as determinants of contract positioning.
Market Dynamics
Electric vehicle skateboard platforms are dissolving mechanical linkages and forcing redundant electronic architectures with deterministic sub-10 millisecond latency requirements across brake, steer, and shift domains.
Growth Catalysts
- NHTSA FMVSS 126 mandates:Stability control requirements compel dual-channel fail-operational brake-by-wire designs in US-bound vehicle programs.
- Silicon carbide gate drivers:Wide-bandgap semiconductors slash switching losses in electric actuator modules, enabling higher power density in steer-by-wire columns.
- Germany's production clusters:Tier-1 supplier concentration around Stuttgart and Munich accelerates design-to-production cycles for European OEM platforms.
Market Restraints
- Copper price volatility:Legacy wiring harnesses still anchor cost structures while fiber-optic and automotive Ethernet transitions require parallel capital deployment.
- Semiconductor foundry concentration:Automotive-grade microcontroller supply allocates disproportionately to consumer electronics, constraining actuator module volumes.
- Functional safety certification timelines:ISO 26262 ASIL-D validation cycles extend 18-24 months, gating program launches irrespective of hardware readiness.
Strategic Opportunities
- Japan's keiretsu supply chains:Vertical integration opportunities exist for foreign entrants partnering with METI-backed mobility consortia on steer-by-wire development.
- Park-by-wire integration:Electric vehicle cabin packaging demands are displacing mechanical parking brakes fastest in premium SUV segments.
- EU Green Deal fleet CO2 targets:Binding emission reduction mandates expand addressable volume for x-by-wire systems that enable modular platform standardization.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineers with AUTOSAR and deterministic networking expertise command premium compensation, constraining tier-2 supplier scaling.
- Legacy vehicle integration friction:Retrofitting x-by-wire architectures into internal combustion platforms with existing hydraulic brake systems creates validation complexity.
- Patent thickets around steer-by-wire:Incumbent suppliers hold blocking positions on torque feedback algorithms, complicating new entrant freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive X-By-Wire System Market |
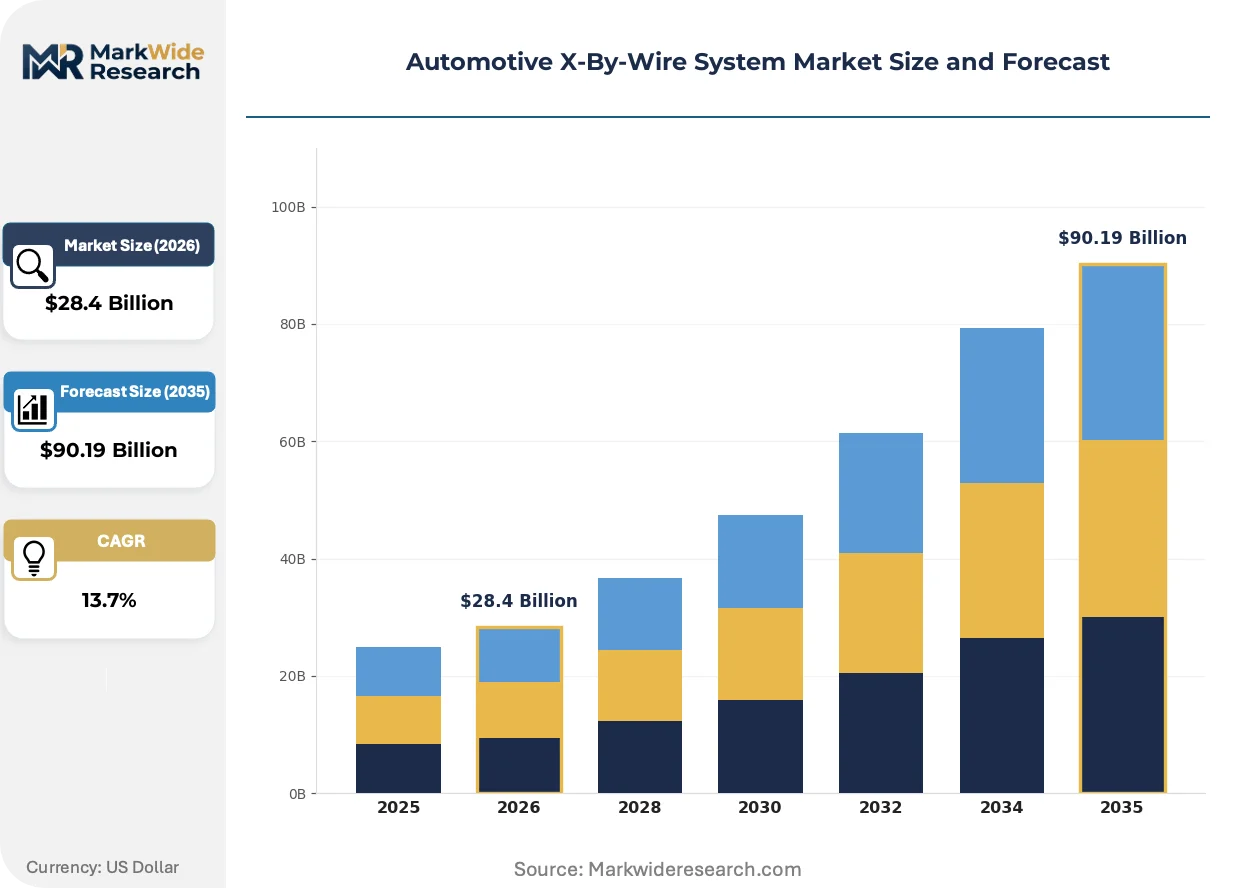
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $90.19 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steering Control, Throttle Control, Brake Control, Shift Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electric Actuators, Sensors, Control Units, Communication Protocols Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Hyundai Mobis, Denso Corporation, PHINIA Inc., Infineon Technologies AG, JTEKT Corporation, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive X-By-Wire System Market Trends and Innovations
Deterministic networking protocols and wide-bandgap power electronics are compressing control loop latencies while regulatory mandates harden redundancy requirements across all actuation domains.
Automotive Ethernet with Time-Sensitive Networking is rewriting the backbone architecture for x-by-wire systems, replacing FlexRay and CAN-FD in next-generation domain controllers. Premium electric vehicle platforms from German and US OEMs are adopting gigabit-speed deterministic networking for steer-by-wire and brake-by-wire integration. This convergence is collapsing the traditional separation between powertrain and chassis control domains into unified zonal compute architectures.
UNECE R79 steer-by-wire provisions are mandating redundant electronic architectures with independent power supplies and dual-channel sensor validation for European type approval. The regulation forces hardware design patterns that propagate into US and Asia-Pacific export programs through platform commonization strategies. Brake-by-wire and steer-by-wire suppliers are responding by pre-certifying actuator modules across multiple geographies to compress OEM integration timelines.
Buyer concentration among electric vehicle pure-plays is consolidating procurement decisions around integrated sensor-actuator platforms rather than discrete component sourcing. Tier-1 suppliers are disintermediating traditional wiring harness vendors by offering complete domain control modules with embedded power electronics. This pattern is most visible in California and Shanghai, where vertically integrated OEMs specify black-box subsystems that internalize software stack development.
Automotive X-By-Wire System Market Segmentation
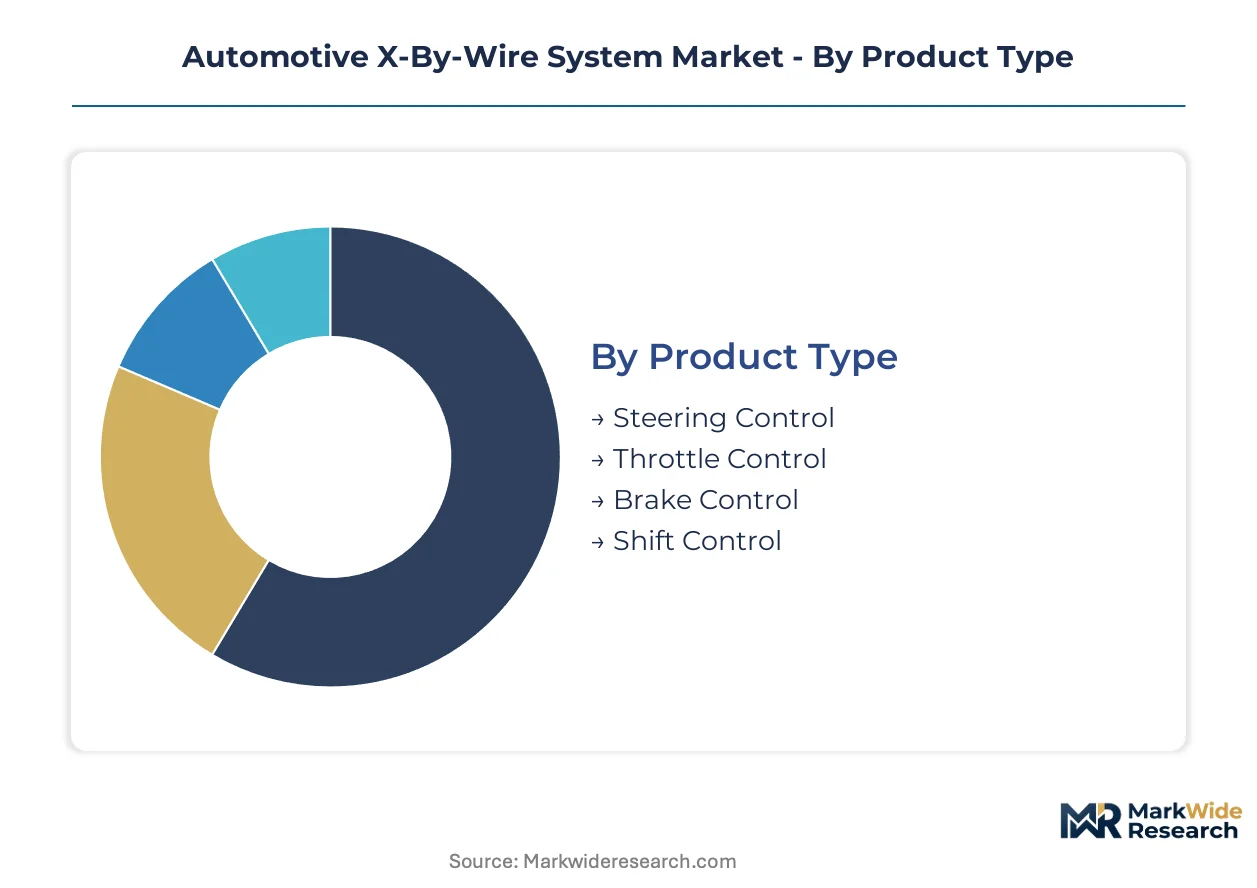
X-by-wire architectures fragment across multiple technical and commercial dimensions that determine integration complexity and margin capture. Each segmentation axis reveals distinct competitive dynamics between standalone module suppliers and embedded system providers.
Product Type:
Standalone brake and steer modules command premium positioning against embedded shift and throttle systems that integrate into broader domain controllers.
- Steering Control:Torque feedback motors and redundant angle sensors replace mechanical columns with dual-channel fail-operational designs. Demand concentrates in German premium OEM programs where steer-by-wire enables cabin packaging flexibility and autonomous-ready architectures.
- Brake Control:Electro-hydraulic and fully electric actuators eliminate vacuum boost dependencies for regenerative braking integration. US-bound vehicle programs under NHTSA FMVSS 126 mandates anchor the largest procurement volumes for dual-channel redundant systems.
- Throttle Control:Drive-by-wire pedal modules with Hall-effect sensors represent mature embedded technology with compressed margins.
- Shift Control:Park-by-wire actuators displace mechanical cables fastest in electric vehicle platforms where space constraints dominate design priorities.
Brake control leads volumes today; shift control is gaining share fastest.
End User:
Margin capture varies sharply across the value chain based on software stack ownership and hardware commoditization pressures.
- OEMs:Captive development of domain control software and zonal compute architectures internalizes the highest-margin layers of x-by-wire integration. Vertical integration into actuator specification is accelerating among electric vehicle pure-plays in California and Shanghai.
- Tier-1 Suppliers:Integrated sensor-actuator platforms from Continental AG and ZF Friedrichshafen AG compete on hardware cost while ceding software differentiation to OEMs. Germany's production clusters around Stuttgart and Munich anchor the most concentrated supplier engineering capabilities.
- Aftermarket Providers:Limited addressable volume given functional safety certification requirements and warranty liability constraints.
- Vehicle Assemblers:Contract manufacturing relationships in emerging production hubs source pre-certified module kits for final integration.
Tier-1 suppliers dominate hardware shipments today; OEM captive development is climbing the fastest.
Technology:
Technology segmentation separates power electronics and sensing hardware from the deterministic networking infrastructure that enables distributed control.
- Electric Actuators:Brushless DC motors with silicon carbide gate drivers achieve sub-10 millisecond response times for safety-critical steering and braking functions. Infineon Technologies AG dominates wide-bandgap semiconductor supply for high-power density modules.
- Sensors:Redundant resolver and optical encoder configurations satisfy ISO 26262 ASIL-D diagnostic coverage requirements.
- Control Units:Automotive-grade microcontrollers with lockstep cores execute deterministic control loops under strict latency budgets.
- Communication Protocols:Automotive Ethernet with Time-Sensitive Networking is displacing FlexRay in next-generation domain controllers.
Electric actuators lead component value today; communication protocol upgrades are expanding most quickly.
Application:
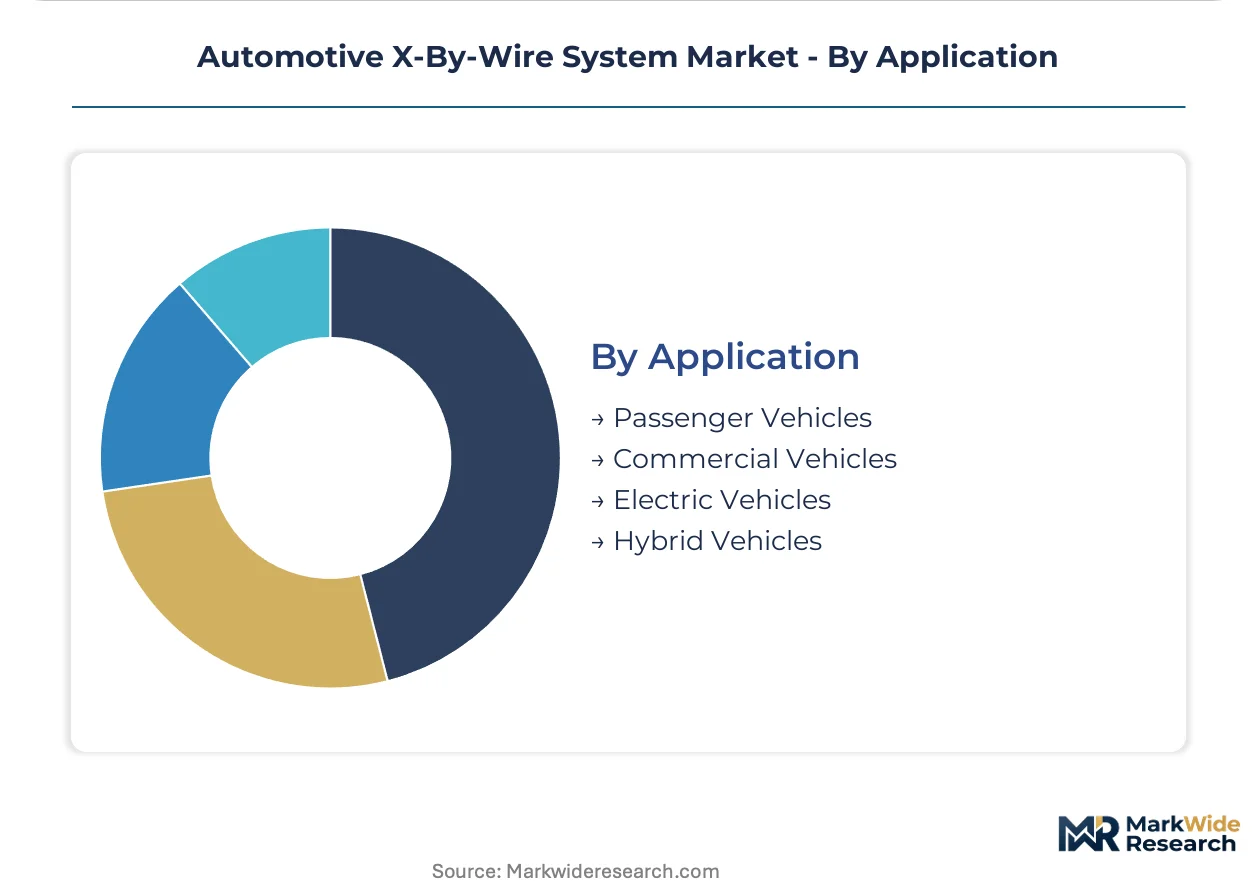
Application segmentation tracks divergent technical requirements between passenger comfort priorities and commercial vehicle durability demands.
- Passenger Vehicles:Premium SUV and sedan segments prioritize steer-by-wire steering feel calibration and park-by-wire cabin packaging. German and Japanese OEM programs specify the most stringent torque feedback fidelity requirements.
- Electric Vehicles:Skateboard platform standardization multiplies x-by-wire content per vehicle through brake-by-wire, steer-by-wire, and shift-by-wire integration. US and Chinese electric vehicle pure-plays are consolidating procurement around black-box subsystem specifications.
- Commercial Vehicles:Heavy-duty brake-by-wire faces extended validation cycles for durability and thermal management under sustained load conditions.
- Hybrid Vehicles:Transitional architectures blending hydraulic and electric actuation create legacy integration friction and validation complexity.
Passenger vehicles anchor installed base today; electric vehicles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart-Munich corridor anchors the densest concentration of tier-1 engineering capabilities for x-by-wire systems. NHTSA mandates in the United States and UNECE provisions in Europe are synchronizing redundant architecture requirements across export programs. Procurement patterns cluster around three distinct production geographies where electric vehicle platform launches concentrate.
United States
NHTSA FMVSS 126 stability control mandates compel dual-channel fail-operational brake-by-wire designs for all US-bound vehicle programs. EPA tailpipe regulations and IRA clean vehicle incentives are accelerating electric vehicle penetration, expanding actuator module demand. Michigan and California anchor the largest procurement volumes, with Detroit-area suppliers feeding traditional OEMs and Silicon Valley-adjacent operations serving electric vehicle pure-plays.
Germany
UNECE R79 steer-by-wire provisions mandate redundant electronic architectures with independent power supplies for European type approval. EU Green Deal fleet CO2 targets bind OEMs to modular skateboard platforms that multiply x-by-wire content per vehicle. Stuttgart and Munich production clusters host Continental AG and ZF Friedrichshafen AG engineering centers that compress design-to-production cycles for premium OEM programs.
Japan
METI-backed mobility consortia are coordinating steer-by-wire development through keiretsu supply chains with vertical integration opportunities for foreign partners. JIS standards and domestic functional safety requirements shape certification timelines for export programs. Nagoya and Tokyo metropolitan areas concentrate Denso Corporation and JTEKT Corporation engineering resources alongside semiconductor packaging operations for automotive-grade microcontrollers.
China
MIIT new energy vehicle mandates and dual carbon goals are driving skateboard platform standardization across domestic OEM portfolios. GB standards for functional safety are converging with ISO 26262 frameworks for export market access. Shanghai and Yangtze River Delta production hubs are consolidating procurement decisions around black-box subsystem specifications from vertically integrated electric vehicle pure-plays.
South Korea
Hyundai Motor Group platform consolidation is internalizing x-by-wire specification authority while maintaining external actuator sourcing relationships. MFDS automotive safety guidelines and domestic semiconductor foundry investments are reshaping supply allocation for electric vehicle programs. Seoul Capital Area and Busan-Ulsan corridors anchor the production footprint with captive development of domain control software stacks.
Automotive X-By-Wire System Market Competitive Landscape
Global majors compete with regional champions across hardware commoditization and software differentiation dimensions. The vendor base organizes into three tiers: integrated sensor-actuator platform providers, semiconductor specialists supplying gate drivers and microcontrollers, and captive OEM development operations internalizing high-margin control software. Dominant competitive moves include pre-certification of actuator modules across multiple geographies and backward integration into silicon carbide power electronics.
Within the integrated platform tier, Continental AG and ZF Friedrichshafen AG exemplify European engineering-centric positioning that competes on hardware cost while ceding software stacks to OEMs. Infineon Technologies AG anchors the semiconductor specialist archetype from its German base. Hyundai Mobis represents the Asia-Pacific tier-1 model with keiretsu-linked supply relationships. Robert Bosch GmbH occupies a position spanning multiple archetypes through its diversified automotive electronics portfolio.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Hyundai Mobis |
| Denso Corporation |
| PHINIA Inc. |
| Infineon Technologies AG |
| JTEKT Corporation |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Copper futures volatility on the London Metal Exchange cascades through automotive wiring harness costs into tiered actuator module pricing, with fiber-optic transition investments compressing margins for legacy suppliers while rewarding semiconductor-integrated platform providers.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer prices and automotive-grade microcontroller supply constraints shapes contract pricing across brake-by-wire and steer-by-wire modules. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified redundant architectures from single-channel designs and aftermarket replacement units. Cost compression in standard-tier brake modules is intensifying because tier-1 suppliers compete on hardware commoditization while ceding software stacks to OEMs. Electric vehicle pure-plays in California and Shanghai exhibit the lowest price sensitivity due to captive specification authority, while traditional OEM procurement teams in Michigan remain most sensitive to per-unit actuator costs.
Supply Chain Analysis
Ocean freight rate fluctuations from Asia-Pacific to North American assembly plants directly influence landed costs for silicon carbide gate drivers and resolver sensor modules. Manufacturing concentration centers on Germany, Japan, and China, with Stuttgart-Munich engineering clusters feeding European OEM programs and Yangtze River Delta operations serving domestic Chinese electric vehicle platforms. Raw material dependencies draw from copper concentrate for legacy harnesses, rare earth elements for torque feedback motors, and 300mm silicon wafers for automotive microcontrollers. Single-source vulnerability around Infineon Technologies AG's silicon carbide supply creates procurement risk for tier-2 actuator assemblers. Distribution runs through just-in-time module delivery to OEM final assembly lines, with pre-certified kit sourcing dominating emerging production hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where functional safety certification timelines extend 18-24 months in Europe under UNECE R79 compared to accelerated GB standard convergence in China, creating cost-structure differentials for platform launches.
For Market Incumbents: Extend pre-certification investments across multiple geographies to compress OEM integration timelines and defend against emerging semiconductor suppliers from South Korea. Backward integration into silicon carbide power electronics secures gate driver supply allocation, while capacity addition in China's Yangtze River Delta captures procurement decisions from vertically integrated electric vehicle pure-plays. Patent thickets around steer-by-wire torque feedback algorithms remain a defensible moat against new entrant freedom-to-operate assessments.
For New Entrants and Emerging Players: Direct-to-OEM digital sales channels bypass traditional tier-1 supplier relationships for aftermarket park-by-wire modules in premium SUV segments. White-space targets include keiretsu partnership opportunities with METI-backed mobility consortia in Japan and embedded software development for zonal compute architectures in European premium programs. The most penetrable segment is shift-by-wire actuators for electric vehicle platforms where mechanical cable displacement creates specification openings.
For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor specialists supplying wide-bandgap gate drivers and deterministic networking PHYs, where automotive-grade qualification creates supply scarcity premiums. Long-term viability over the projection horizon favors acquisition targets with ISO 26262 ASIL-D certification capabilities and embedded AUTOSAR expertise. The signal to watch is NHTSA rulemaking on steer-by-wire redundancy requirements, which would expand addressable volume for dual-channel fail-operational designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Skateboard architectures multiply x-by-wire content per vehicle across brake, steer, and shift domains. |
| Silicon Carbide Supply Agreement | Long-term offtake contracts with Infineon Technologies AG secure gate driver allocation for high-power actuator modules. |
| Software-Defined Vehicle Investment | Captive development of domain control software internalizes highest-margin layers from tier-1 suppliers. |
| Geographic Manufacturing Footprint | Production clusters around Stuttgart, Munich, and Shanghai compress design-to-production cycles for regional OEM programs. |
| Functional Safety Certification Program | Pre-certification across UNECE R79, NHTSA FMVSS 126, and GB standards accelerates program launch timelines. |
Research Methodology
Bottom-up electric vehicle platform modeling reconciled against top-down tier-1 supplier production tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-1 supplier procurement leads, semiconductor foundry planning officers, and functional safety certification specialists combined with secondary validation from NHTSA rulemaking dockets, UNECE working party submissions, MIIT new energy vehicle production databases, and IHS Markit vehicle registration data. Triangulation between demand-side adoption curves and supply-side capacity announcements ensures consistency across the projection horizon.
The input-output matrix framing connects silicon carbide wafer supply, automotive-grade microcontroller foundry allocation, and copper wiring harness cost indices to actuator module production volumes across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from segment-level adoption curves applied to OEM platform launch schedules, with electric vehicle penetration rates and skateboard platform standardization serving as primary forecast drivers alongside regulatory mandate compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for fiber-optic backbone displacement of copper harnesses would alter the outlook for legacy supplier margin structures. Forecasts reflect assumptions about semiconductor supply allocation prioritization, functional safety certification timeline compression, and electric vehicle platform commonization strategies across export programs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Automotive Touch Screen Control Systems Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Automotive Fault Circuit Controllers Market
Automotive Circuit Systems
Driveline Control Systems and Devices Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Automotive Horn Systems Market