
 Automotive Battery Frames Market | 2026-2036
Automotive Battery Frames Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Frames Market Outlook
Modular frame-to-pack integration is recalibrating how OEMs evaluate battery enclosure procurement. Continental AG leverages its systems integration heritage to bundle thermal management with frame structures. CATL anchors its competitive stance through captive aluminum extrusion capacity for frame production. Robert Bosch GmbH competes on smart sensor integration within frame architectures for state-of-health monitoring.
Automotive battery frames are structural enclosures that house electrochemical cells, typically fabricated from extruded aluminum profiles or stamped steel assemblies with integrated cooling channels and crash-absorption zones, serving to protect cells from mechanical stress while managing thermal loads during charge and discharge cycles. Lithium-ion frames dominate current procurement volumes due to their compatibility with high-energy-density cell formats requiring precise dimensional stability. Solid-state frames represent the fastest-growing material category as next-generation cell architectures demand modified thermal expansion tolerances and hermetic sealing interfaces. Steel frames retain cost-sensitive applications in commercial vehicle segments where payload capacity constraints favor higher-strength alloys over aluminum weight savings.
The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations that frame manufacturers must document through supply chain audits. China's NMPA enforces GB standards for battery system mechanical abuse testing, including frame penetration resistance protocols. The EPA's emerging vehicle battery end-of-life guidelines in the US will shape frame disassembly requirements and material recovery economics. Stakeholders must monitor how divergent national recycling mandates reshape frame material specifications and regional manufacturing footprints.
Market Dynamics
Electric vehicle platform consolidation is compressing battery frame development cycles as OEMs demand structural enclosures that integrate crash management, thermal regulation, and cell protection into single-source procurement packages.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Frame manufacturers investing in closed-loop aluminum recovery systems capture preferential supplier status with German automotive OEMs pursuing carbon-neutral vehicle certification.
- Cell-to-pack architecture adoption:Elimination of module housings shifts structural load directly to frame sidewalls, expanding addressable content per vehicle for specialized enclosure producers.
- China's dual carbon policy enforcement:Domestic EV manufacturers accelerate localization of frame supply chains to satisfy MIIT carbon intensity audits for production subsidies.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting operations in Yunnan and Quebec face electricity cost fluctuations that transmit directly to extruded profile input costs.
- High-purity alloy supply concentration:Aerospace-grade 6xxx series aluminum billet production concentrates among three Asian smelters, creating single-source vulnerability for crash-rated frame programs.
- GB standards mechanical abuse testing:China's NMPA penetration resistance protocols require redundant material thickness that conflicts with lightweighting targets, forcing design trade-offs.
Strategic Opportunities
- Commercial vehicle electrification in India:Bus and last-mile delivery chassis manufacturers seek steel-intensive frame solutions where payload economics override aluminum weight premiums.
- Battery passport traceability requirements:EU digital product passport mandates create service revenue streams for frame producers offering blockchain-integrated material provenance systems.
- Solid-state cell interface standardization:Hermetic sealing and thermal expansion coefficient matching for sulfide electrolyte cells opens specialist engineering contracts outside incumbent lithium-ion supply relationships.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled thermal-structural-electrochemical modeling for frame optimization requires expertise spanning automotive crash engineering and electrochemistry.
- Cell supplier qualification timelines:OEMs demand frame-to-cell interface validation cycles exceeding eighteen months, compressing supplier development budgets before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Frames Market |
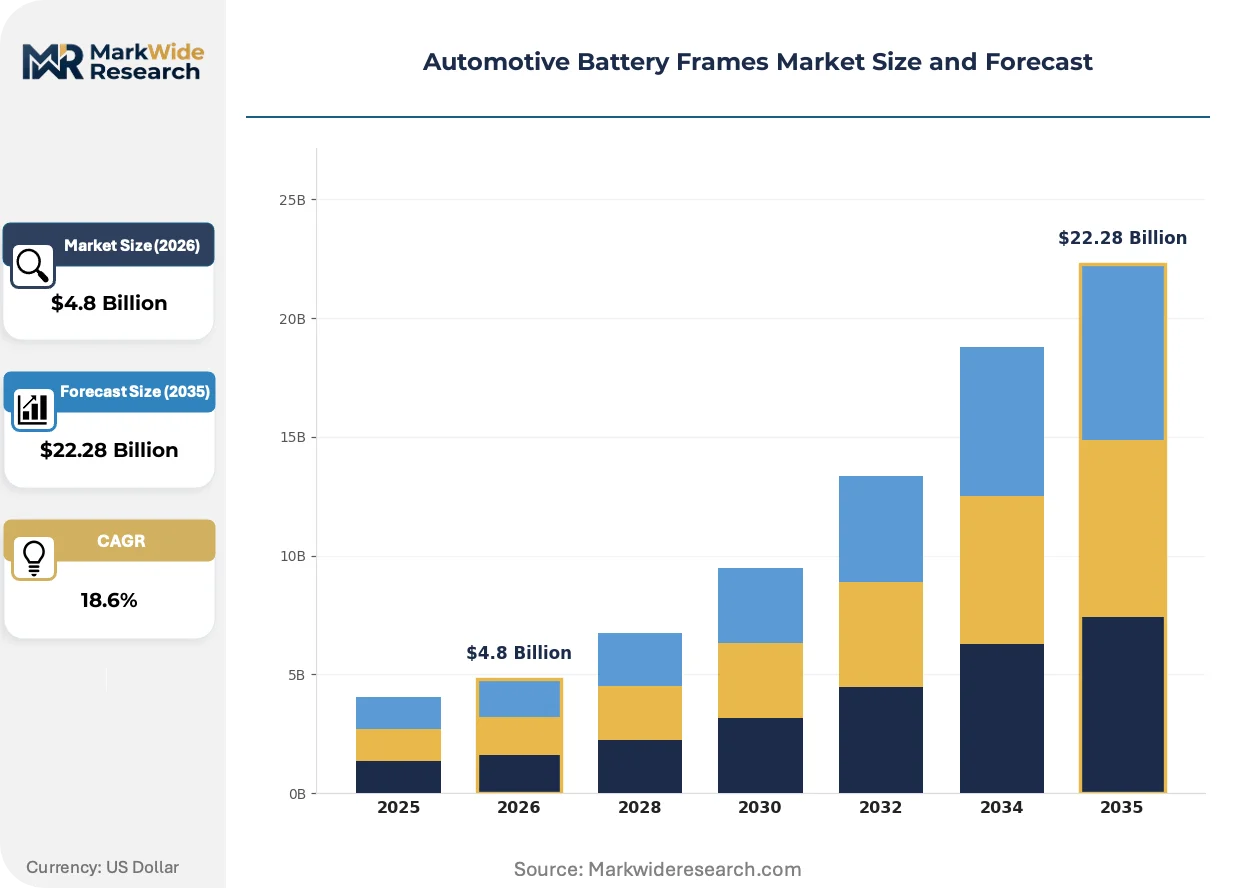
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Solid-State End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Material: Steel, Aluminum, Composites, Plastic Technology: Smart Battery, Ultrafast Charging, Wireless Monitoring, Renewable Energy Integration |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Sensata Technologies, LG Energy Solution, CATL, Panasonic, AVL, Ficosa Internacional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Frames Market Strategic Shifts
Structural battery integration is dissolving the boundary between chassis and energy storage, forcing frame producers to master vehicle-level crash simulation and thermal management system design.
Aluminum-steel hybrid extrusion bonding is rewriting how manufacturers achieve crashworthiness without mass penalties. European premium EV platforms adopt friction-stir welded bimetallic joints that place high-strength steel in load paths while retaining aluminum for thermal conductivity. This hybrid approach compresses the addressable market for pure aluminum frame specialists while rewarding metallurgical process innovators.
REACH SVHC candidate list expansion is accelerating substitution of chromate conversion coatings on aluminum frames. Automotive suppliers in Stuttgart and Wolfsburg face supply chain audit requirements for hexavalent chromium elimination by 2026, driving qualification of zirconium-based pretreatment chemistries and laser-structured surface adhesion systems.
Fleet operators now specify battery residual value guarantees as standard procurement terms. Commercial vehicle buyers in California and the Netherlands demand frame designs enabling automated disassembly and material recovery, shifting supplier selection criteria toward modularity and standardized joining methods rather than unit cost alone.
Automotive Battery Frames Market Segmentation
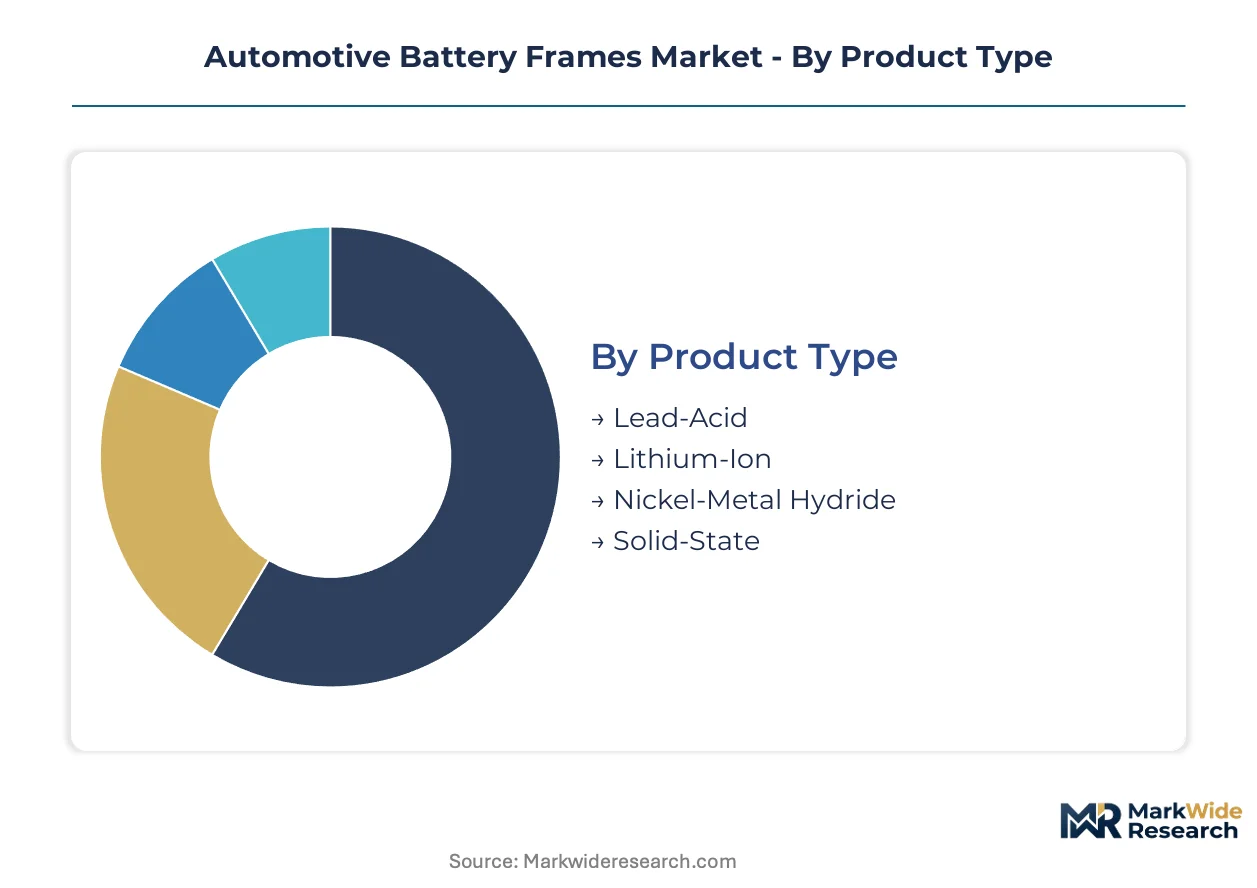
Segmentation reveals how battery frame procurement splits across competing chemistries, buyer types, and material specifications. Each axis carries distinct margin profiles and qualification barriers that reshape supplier positioning.
Product Type:
Cell chemistry dictates thermal expansion tolerances, sealing requirements, and crash-load distribution through the frame structure.
- Lithium-Ion:Aluminum-intensive enclosures with integrated cooling channels dominate current procurement volumes. German OEMs specify these frames for high-energy-density pouch and prismatic cell formats requiring precise dimensional stability under charge-discharge cycling.
- Solid-State:Hermetic sealing interfaces and modified thermal expansion coefficients distinguish these next-generation frames. Sulfide electrolyte cell architectures from Korean and Japanese developers are forcing frame producers outside incumbent lithium-ion supply relationships to qualify new material interfaces.
- Lead-Acid:Cost-optimized stamped steel enclosures serve commercial vehicle starter battery applications where energy density requirements remain modest.
- Nickel-Metal Hydride:Hybrid vehicle legacy platforms in Japan sustain limited demand for these moderate-temperature frames with simplified thermal management.
Lithium-ion leads on scale; solid-state leads on momentum.
End User:
Buyer concentration and technical integration depth vary sharply across the procurement chain.
- OEMs:Direct sourcing of integrated frame-to-chassis assemblies accelerates as Volkswagen, BMW, and Mercedes-Benz consolidate structural battery procurement under single-source contracts. These buyers demand crash simulation capabilities and thermal management system design competence.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH intermediate frame production for OEMs lacking in-house enclosure engineering. Their procurement emphasizes bimetallic joining processes and smart sensor integration for state-of-health monitoring.
- Vehicle Assemblers:Contract manufacturers in emerging EV markets source standardized frame platforms with reduced customization requirements.
- Aftermarket Providers:Replacement frame demand concentrates in commercial vehicle segments where battery refurbishment extends asset life.
OEMs command specification authority; Tier-1 suppliers capture integration value.
Material:
Mass, conductivity, and recyclability trade-offs drive material selection against platform cost targets.
- Aluminum:Extruded 6xxx series profiles with friction-stir welded joints balance thermal conductivity and crash absorption. CATL's captive extrusion capacity anchors competitive positioning for this category.
- Steel:High-strength alloys serve commercial vehicle applications where payload economics override weight savings. Indian bus and last-mile delivery chassis manufacturers specify these frames for cost-sensitive electrification programs.
- Composites:Glass-fiber reinforced polymers gain traction in specialty applications requiring electromagnetic shielding or extreme corrosion resistance.
- Plastic:Injection-molded structural polymers occupy auxiliary housing roles with limited load-bearing requirements.
Aluminum dominates revenue; steel defends share in commercial segments.
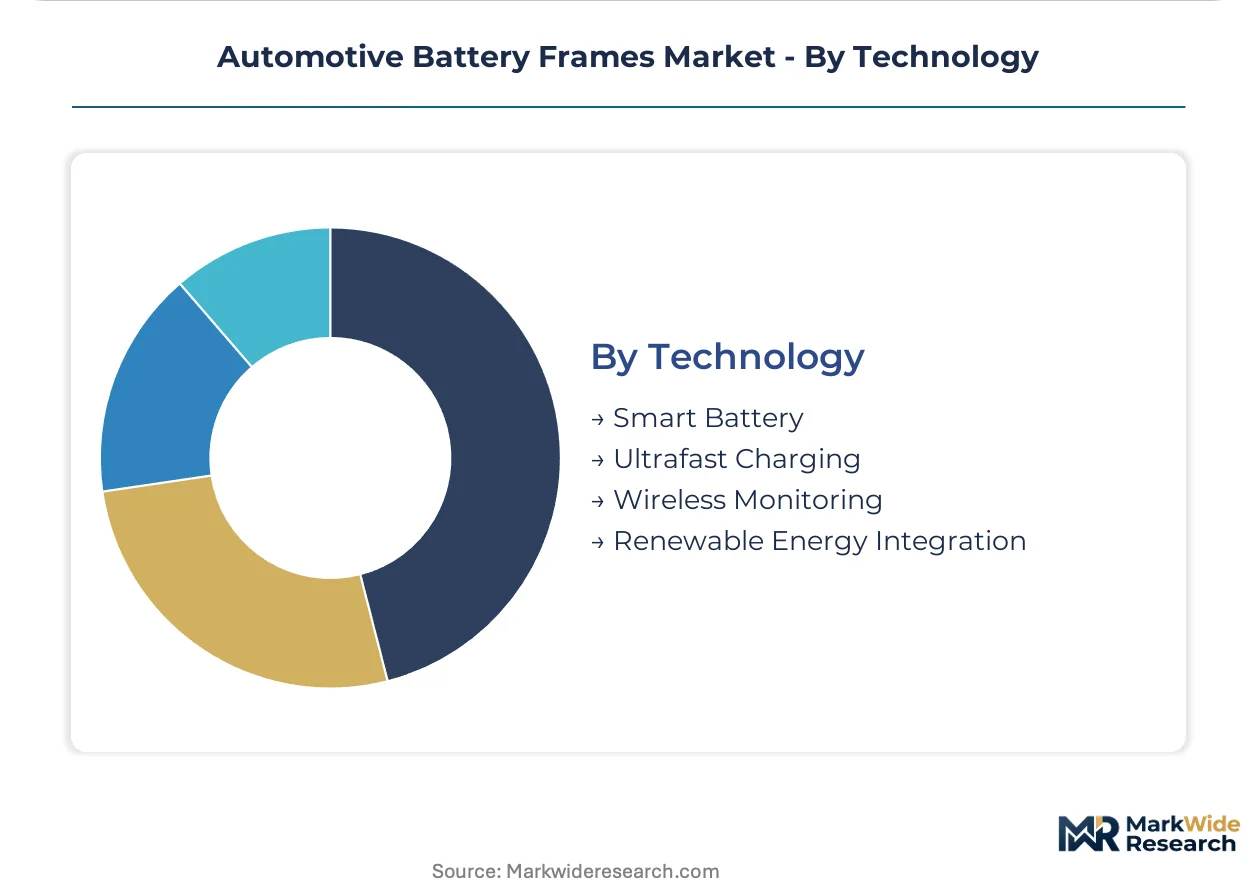
Technology:
Intelligence and charging speed specifications are embedding electronics and thermal hardware directly into frame architectures.
- Smart Battery:Sensor-integrated frames enable real-time state-of-health monitoring and predictive thermal regulation. Robert Bosch GmbH competes on embedding smart electronics within frame architectures for cell-level diagnostics.
- Ultrafast Charging:Enhanced cooling channel density and high-conductivity thermal interface materials accommodate 350kW+ charge rates. These frames require specialized aluminum alloys and precision machining for heat flux management.
- Wireless Monitoring:Inductive data and power transmission eliminates connector penetration points, improving sealing integrity for solid-state cell applications.
- Renewable Energy Integration:Bidirectional power frames with reinforced busbar structures support vehicle-to-grid discharge cycles.
Smart battery technology captures premium pricing; ultrafast charging expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering corridor pioneered integrated battery frame production during the early EV platform consolidation wave, establishing design protocols that now propagate through Chinese and North American supply chains.
Germany
BMW, Volkswagen, and Mercedes-Benz coordinate frame-to-chassis integration through Stuttgart and Wolfsburg engineering clusters. The EU Battery Regulation's recycled content thresholds and carbon footprint declarations force frame manufacturers to document closed-loop aluminum recovery through supply chain audits. Bavaria's supplier ecosystem captures preferential status by pursuing carbon-neutral vehicle certification.
China
Domestic EV manufacturers accelerate localization of frame supply chains to satisfy MIIT carbon intensity audits for production subsidies. NMPA enforces GB standards for battery system mechanical abuse testing, including frame penetration resistance protocols. Yangtze River Delta extrusion capacity anchors CATL's captive aluminum production for integrated frame assemblies.
United States
EPA's emerging vehicle battery end-of-life guidelines will shape frame disassembly requirements and material recovery economics. California fleet operators specify battery residual value guarantees, demanding frame designs enabling automated disassembly. Detroit-area OEMs consolidate structural battery procurement under single-source contracts with crash simulation requirements.
Japan
Solid-state cell developers from Korean and Japanese labs force frame producers outside incumbent lithium-ion supply relationships to qualify new material interfaces. METI standards guide thermal expansion coefficient matching for sulfide electrolyte architectures. Nagoya-area automotive suppliers face eighteen-month frame-to-cell interface validation cycles before revenue recognition.
India
Bus and last-mile delivery chassis manufacturers seek steel-intensive frame solutions where payload economics override aluminum weight premiums. BIS certification requirements shape commercial vehicle electrification programs. Maharashtra and Gujarat-based fabricators supply cost-sensitive electrification programs with high-strength alloy frames.
Automotive Battery Frames Market Competitive Environment
The competitive structure tilts toward systems integrators with captive metallurgical capabilities. Tier-1 suppliers with automotive heritage dominate procurement channels for OEMs lacking in-house enclosure engineering. Three archetypes define positioning: aluminum extrusion specialists with backward integration into billet supply, smart sensor integrators embedding diagnostics within frame architectures, and steel fabricators serving commercial vehicle payload economics. Dominant competitive moves include friction-stir welding process licensing and strategic partnerships for solid-state cell interface development.
Among German-based systems integrators, Continental AG and Robert Bosch GmbH exemplify the smart sensor integration archetype, anchoring premium-tier positioning through state-of-health monitoring capabilities. CATL represents the captive capacity model, with Zhengzhou-based extrusion operations supporting integrated frame-to-pack assemblies. These three entities occupy positions that reflect divergent strategic bets on aluminum intensity versus electronics integration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Sensata Technologies |
| LG Energy Solution |
| CATL |
| Panasonic |
| AVL |
| Ficosa Internacional |
| Others |
Value Chain & Pricing Dynamics
Primary aluminum ingot from Yunnan smelters flows through three pricing tiers before reaching German OEM assembly lines, with energy cost pass-throughs compressing margins at each conversion stage. Spot volatility in hydroelectric-dependent Chinese production transmits downstream as quarterly contract renegotiation pressure for extruded profile suppliers.
Pricing Analysis
Contract-based long-term offtake dominates procurement between German automotive OEMs and frame manufacturers, with pricing stratifying across crash-rated certification tiers, volume scale commitments, and thermal management integration depth. Cost compression in standard-grade aluminum frames is intensifying because CATL's captive extrusion capacity eliminates margin capture for independent suppliers. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while premium EV platforms prioritize crash simulation competence over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Wolfsburg, and Shanghai coordinate hub-and-spoke patterns for just-in-time frame delivery to vehicle assembly plants. Manufacturing concentrates in Germany, China, and South Korea, with supply chains drawing from aerospace-grade 6xxx series aluminum billet, high-purity copper busbar, and thermally conductive interface materials. Single-source vulnerability pervades the three Asian smelters controlling crash-rated alloy production. Distribution runs through Tier 1 integrators bundling thermal management with structural enclosures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: OEM procurement of integrated frame-to-chassis assemblies now prioritizes crash simulation capabilities and carbon-neutral certification over baseline cost. The shift toward solid-state cell interfaces demands premium engineering specifications that filter out commodity suppliers.
For Market Incumbents: Extend metallurgical process licensing agreements to capture value from aluminum-steel hybrid extrusion bonding adoption across European premium platforms. Deepen backward integration into closed-loop aluminum recovery systems to defend supplier status under EU Battery Regulation recycled content mandates. The threat of Korean and Japanese solid-state cell developers forcing eighteen-month qualification timelines compresses development budgets before revenue recognition. For New Entrants and Emerging Players: Commercial vehicle assemblers in India represent the most penetrable buyer archetype, with steel-intensive frame demand outpacing aluminum capacity for bus and last-mile delivery electrification. White-space targets include automated disassembly systems for California and Netherlands fleet operators specifying battery residual value guarantees. A go-to-market angle anchored in BIS certification compliance and payload-optimized alloy selection bypasses incumbent aluminum extrusion specialization. For Investors and Strategic Acquirers: Roll-up economics work for smart sensor integrators because OEM consolidation of structural battery procurement under single-source contracts rewards bundled thermal management and state-of-health monitoring capabilities. The five-to-ten year viability window favors acquisition targets with friction-stir welding process IP and solid-state cell interface development partnerships. Watch for MIIT carbon intensity audit enforcement accelerating Chinese domestic localization as the inflection signal for regional supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Friction-Stir Welding Process Licensing | European premium EV platforms adopt bimetallic joints placing steel in load paths while retaining aluminum thermal conductivity. |
| Closed-Loop Aluminum Recovery Investment | Frame manufacturers documenting supply chain audits capture preferential supplier status with German OEMs pursuing carbon-neutral certification. |
| Solid-State Cell Interface Development | Hermetic sealing and thermal expansion coefficient matching for sulfide electrolyte cells opens specialist engineering contracts outside incumbent lithium-ion relationships. |
| Smart Sensor Integration Partnership | Robert Bosch GmbH competes on embedding electronics within frame architectures for real-time cell-level diagnostics and predictive thermal regulation. |
| Steel-Intensive Frame Platform Standardization | Indian bus and last-mile delivery chassis manufacturers specify high-strength alloy frames where payload economics override aluminum weight premiums. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and aluminum extrusion plant managers with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs trade records. Bottom-up frame shipment aggregation and top-down OEM platform content analysis were triangulated against MIIT subsidy disbursement data and EU Battery Regulation implementation timelines.
Historical reference periods anchored volume and value outputs across the modeling period, with segmentation dimensions spanning cell chemistry architecture, buyer integration depth, material specification grade, and embedded technology tier. CAGRs were derived from coupled growth-rate analysis incorporating OEM platform launch schedules, extrusion capacity expansion announcements, and regulatory compliance deadline clustering. Forecast inputs included NMPA mechanical abuse testing protocol evolution and REACH SVHC candidate list expansion timelines for coating chemistry substitution.
Underlying measurement precision varies by segment; solid-state frame categories carry wider uncertainty bands than established lithium-ion enclosures due to unstandardized cell interface specifications. Forecasts reflect documented assumptions regarding aluminum price volatility, qualification timeline compression, and divergent national recycling mandate implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Connecting Rods Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Global Car Engine Oil Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Automotive Engine Cooling System Market
Automotive Parts
Global Automotive Damper Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
VVT Actuators Market
Automotive Parts
Automotive Parts Zinc Die Casting Market