
 Automotive Ethernet Switches Market | 2026-2036
Automotive Ethernet Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ethernet Switches Market Analysis
Buyer concentration among tier-1 automotive electronics suppliers is hardening as OEMs consolidate preferred vendor lists for zonal E/E architectures. Broadcom Inc. leverages its SerDes IP portfolio to dominate high-speed automotive connectivity sockets. NXP Semiconductors N.V. anchors European supply chains through its S32G vehicle network processors with integrated switch functionality. Texas Instruments Incorporated competes on manufacturing scale and AEC-Q100 qualification breadth across temperature grades.
Automotive Ethernet switches are multi-port Layer 2 or Layer 3 devices purpose-built for in-vehicle networks, supporting data rates from 100 Mbps to multi-gigabit speeds with deterministic latency under IEEE 802.1 TSN standards and operating temperatures from -40°C to +105°C per AEC-Q100 Grade 2. These components route sensor fusion data, ADAS camera feeds, and infotainment streams across twisted-pair cabling while replacing legacy CAN and LIN backbone segments. Managed switches command the richest margin pools where firmware-defined QoS and cybersecurity features differentiate supplier offerings. Gigabit Ethernet technology leads current design-ins, though 10 Gigabit Ethernet is gaining traction for central compute clusters and raw lidar data aggregation. OEM end users drive volume concentration through platform-level sourcing decisions that lock in switch specifications across multiple model years.
The IEEE 802.3 working group, UN ECE WP.29 cybersecurity regulations, and FDA-equivalent functional safety standards under ISO 26262 collectively shape product roadmaps and qualification timelines for automotive Ethernet switch suppliers. European REACH substance restrictions and China's GB/T standards for vehicle networking further fragment compliance requirements across manufacturing footprints. Stakeholders must monitor TSN conformance test evolution and OEM zonal architecture migration timelines to calibrate R&D allocation between current-generation Gigabit products and next-generation multi-gigabit platforms.
Market Dynamics
OEM migration toward zonal E/E architectures is compressing legacy domain-based wiring harnesses into high-speed Ethernet backbones, forcing tier-1 suppliers to requalify switch portfolios for deterministic latency under IEEE 802.1 TSN constraints.
Growth Catalysts
- UN ECE WP.29 cybersecurity mandates:Regulatory deadlines for intrusion detection and secure firmware update capabilities are expanding addressable demand for managed switches with embedded hardware security modules.
- Raw sensor data aggregation:Lidar point clouds and 8-megapixel camera streams from Level 2+ ADAS programs are saturating legacy CAN-FD bandwidth, pulling multi-gigabit Ethernet into central compute modules.
- China's GB/T vehicle networking standards:Domestic OEMs under MIIT guidance are accelerating local switch procurement for intelligent connected vehicle platforms, concentrating design-in activity around Shanghai and Shenzhen electronics clusters.
Market Restraints
- Silicon supply concentration:Advanced SerDes PHY IP for automotive-grade switches remains captive to a handful of foundry-qualified design houses, creating single-source exposure for 10 Gigabit roadmap products.
- AEC-Q100 Grade 2 qualification timelines:Extended temperature cycling and EMC validation for -40°C to +105°C operation stretches new product introduction cycles beyond 24 months, freezing second-tier suppliers out of platform sourcing decisions.
- Legacy LIN/CAN cost anchors:Body control modules and door electronics continue shipping on 500 kbps CAN for cost-optimized vehicle segments, capping Ethernet penetration in entry-price powertrain architectures.
Strategic Opportunities
- Software-defined vehicle platforms:Over-the-air update architectures are creating attach-rate expansion for switches with firmware-configurable QoS and remote diagnostics, particularly in premium German OEM programs.
- Power-over-Ethernet convergence:IEEE 802.3bu 100W power delivery integration is unifying data and 48V actuator power onto single twisted-pair runs, eliminating redundant harness weight in seat and climate modules.
- US Inflation Reduction Act domestic content rules:North American assembly requirements for EV tax credits are incentivizing switch sourcing from US-based backend facilities, reshaping supplier footprint decisions.
Industry Challenges
- TSN conformance testing bottlenecks:Limited certified test house capacity for IEEE 802.1AS time synchronization and 802.1Qbv traffic shaping is delaying production release schedules for zonal gateway programs.
- Functional safety integration:ISO 26262 ASIL-B to ASIL-D decomposition for switch fabrics co-located with ADAS compute is forcing redundant hardware paths that inflate die area and thermal design power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ethernet Switches Market |
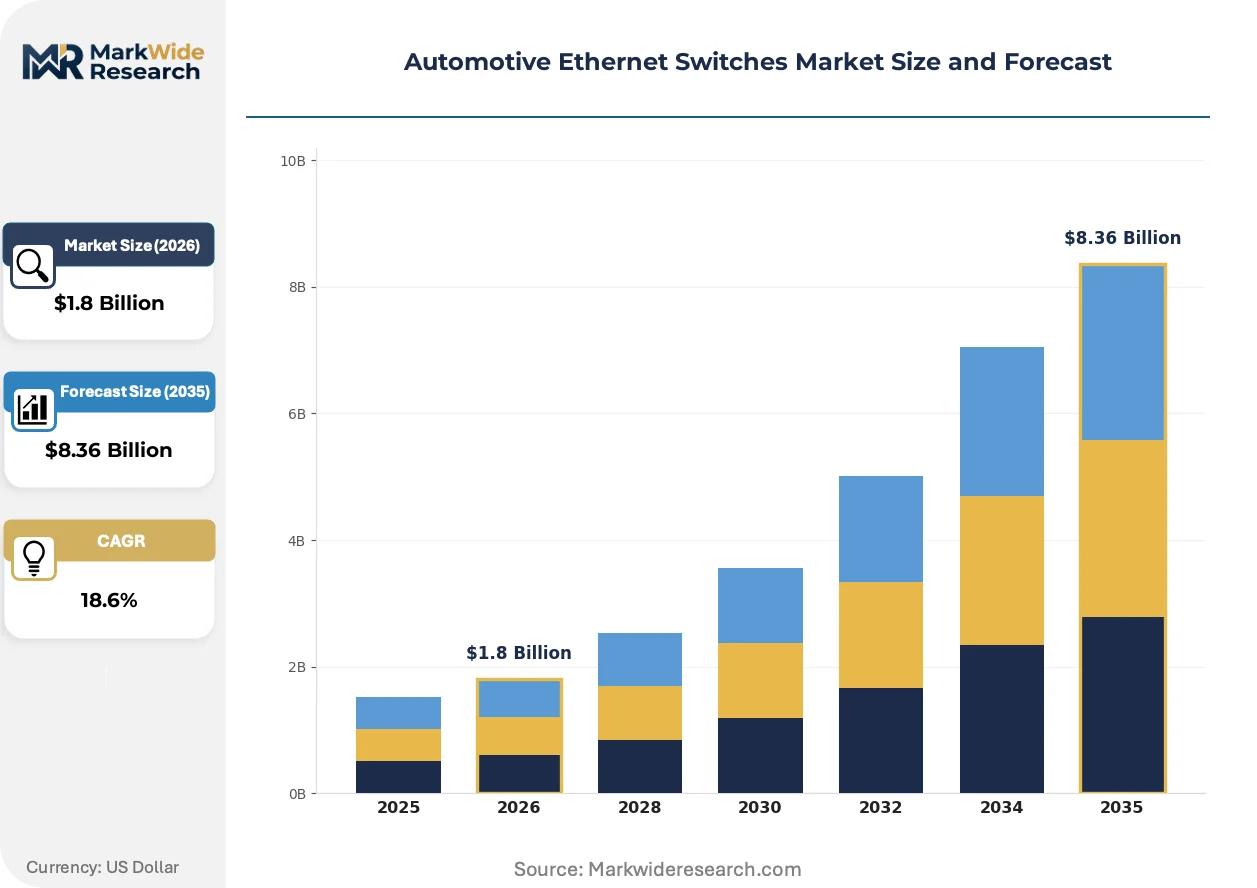
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Managed Switches, Unmanaged Switches, PoE Switches, Layer 3 Switches Technology: Fast Ethernet, Gigabit Ethernet, 10 Gigabit Ethernet, Time-Sensitive Networking End User: OEMs, Tier-1 Suppliers, Automotive Aftermarket, Vehicle Assemblers Installation: Onboard Installation, Offboard Installation, Rack-Mounted, Embedded Solutions |
| Companies Covered | Microchip Technology Inc., Infineon Technologies AG, Broadcom Inc., Molex, LLC, Cadence Design Systems, Inc., NXP Semiconductors N.V., Texas Instruments Incorporated, Keysight Technologies, Inc., Marvell Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ethernet Switches Market Emerging Trajectories
Automotive Ethernet switch roadmaps are converging on multi-gigabit speeds with embedded TSN offload engines, compressing the gap between sensor raw data and central fusion compute while cybersecurity firmware becomes a standard rather than premium feature.
Single-pair 100BASE-T1 and 1000BASE-T1 PHY technology is unifying infotainment, ADAS, and chassis control onto common twisted-pair infrastructure. European premium OEMs have completed design-ins for 1 Gbps zonal backbone switches across 2026-2028 model year platforms. This unification is collapsing the historical separation between comfort domain and safety-critical network segments, forcing suppliers to qualify single SKUs across mixed-criticality use cases.
EU Cyber Resilience Act requirements for vulnerability disclosure and secure-by-default configuration are mandating firmware signing and hardware root-of-trust in all networked vehicle components. Switch suppliers must now maintain certificate infrastructure and incident response capabilities that mirror enterprise IT security operations. Aftermarket diagnostic tool vendors and fleet telematics integrators face the steepest compliance recertification burdens under these rules.
Platform-level sourcing contracts now lock switch specifications across five-to-seven year vehicle lifecycles, compressing second-source qualification windows. Tier-1 electronics suppliers are consolidating vendor lists to three approved switch families per speed grade, freezing out emerging competitors without AEC-Q100 production history. Japanese and Korean OEMs have moved fastest on single-source approval models, while US-based manufacturers retain dual-source clauses for supply security.
Automotive Ethernet Switches Market Segmentation
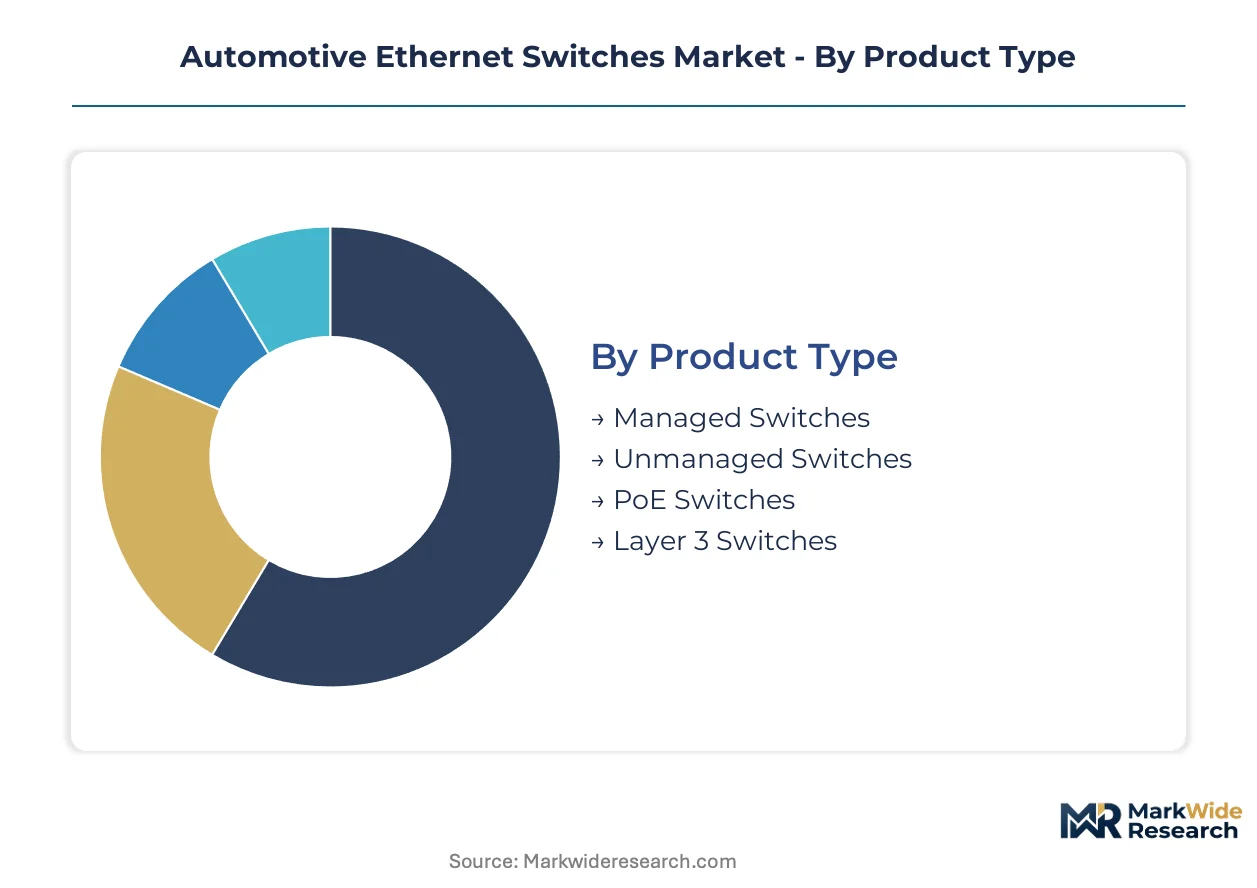
Segmentation in automotive Ethernet switches reveals how supplier portfolios align with zonal architecture roadmaps and qualification barriers. Product mix and technology choices determine margin capture and design-in longevity across OEM platform cycles.
Product Type:
Supply concentration in managed switch silicon favors incumbents with firmware development scale and hardware security module integration.
- Managed Switches:Full Layer 2/3 stack with IEEE 802.1Qbv traffic shaping and embedded HSM for UN ECE WP.29 compliance. German premium OEMs concentrate procurement here for central compute gateways requiring remote diagnostics and firmware-configurable QoS.
- Unmanaged Switches:Fixed-configuration Layer 2 devices with deterministic forwarding but no firmware programmability. Chinese EV assemblers favor these for cost-optimized zonal nodes where cybersecurity requirements remain lighter.
- PoE Switches:IEEE 802.3bu 100W power delivery integration for unified data and 48V actuator control in seat and climate modules.
- Layer 3 Switches:IP routing capability with OSPF and multicast offload for backbone convergence in multi-domain architectures.
Today's leader: Managed Switches. Tomorrow's challenger: PoE Switches.
Technology:
Cost tier stratification across PHY generations mirrors OEM platform positioning from mass-market B-segments to flagship E-segments.
- Gigabit Ethernet:1000BASE-T1 single-pair PHY dominating current zonal backbone design-ins with -40°C to +105°C AEC-Q100 Grade 2 qualification. European and US OEMs lock specifications across 2026-2028 model year platforms, pulling volume concentration toward established foundry-qualified suppliers.
- 10 Gigabit Ethernet:Multi-gigabit SerDes for raw lidar point cloud aggregation and central fusion compute. SerDes IP concentration creates single-source exposure, stretching NPI cycles beyond 24 months and freezing second-tier competitors out of flagship ADAS programs.
- Fast Ethernet:100BASE-T1 legacy infrastructure for body control modules where bandwidth requirements remain modest.
- Time-Sensitive Networking:IEEE 802.1AS time synchronization and 802.1Qbv frame preemption as overlay capability across all PHY speeds.
10 Gigabit Ethernet climbs fastest in OEM specification activity despite supply constraints.
End User:
Volume concentration tracks platform-level sourcing decisions that cascade switch specifications through multi-year vehicle lifecycles.
- OEMs:Direct procurement for central compute and zonal gateway modules with five-to-seven year specification locks. Platform architects at German, US, and Chinese manufacturers drive technology roadmaps and consolidate approved vendor lists to three switch families per speed grade.
- Tier-1 Suppliers:Electronics integrators qualifying switch portfolios across multiple OEM programs under IEEE 802.1 TSN constraints. These suppliers face requalification pressure as zonal architectures compress legacy domain-based wiring harnesses.
- Vehicle Assemblers:Contract manufacturing partners sourcing switches for regional assembly footprints under domestic content rules.
- Automotive Aftermarket:Fleet telematics and diagnostic tool vendors facing steep recertification burdens under EU Cyber Resilience Act requirements.
OEMs command specification authority. Tier-1 Suppliers absorb qualification risk.
Installation:
Application context determines thermal design power budgets and mechanical envelope constraints across passenger and commercial vehicle programs.
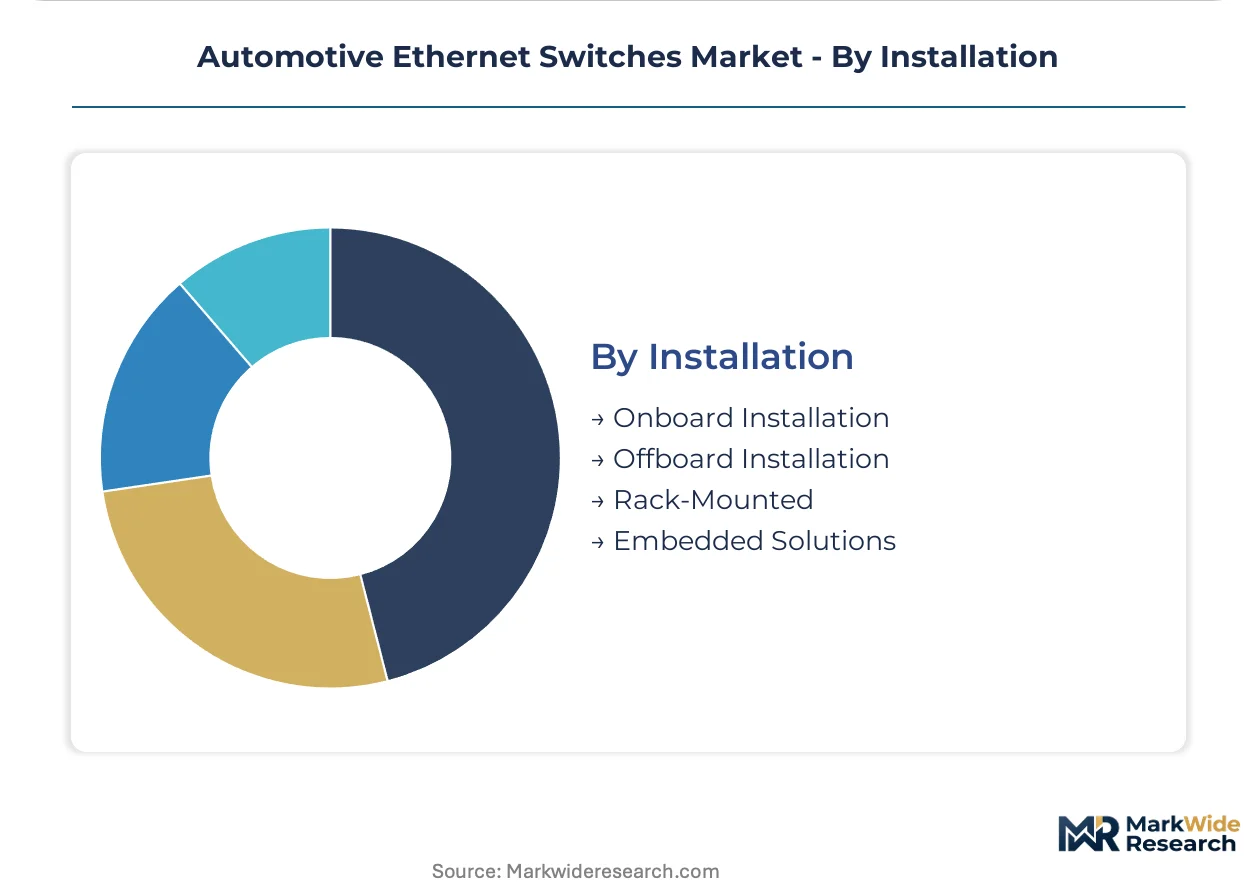
- Embedded Solutions:Chip-down switch fabrics integrated into domain controller PCBs with ASIL-B to ASIL-D functional safety decomposition. Redundant hardware paths inflate die area and thermal design power for ADAS compute co-location.
- Onboard Installation:Standalone switch modules for zonal gateway aggregation in IP6K9K-sealed enclosures.
- Rack-Mounted:Centralized test and validation infrastructure for pre-production vehicle fleets.
- Offboard Installation:Diagnostic and flash programming equipment for service bay environments.
Embedded Solutions anchor production volume. Onboard Installation scales with zonal architecture penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China outpaces Germany in zonal architecture procurement velocity, while the United States concentrates design-in activity around domestic EV tax credit compliance. Each geography imposes distinct regulatory and supply chain constraints on switch qualification timelines.
China
MIIT-guided intelligent connected vehicle platforms are accelerating local switch procurement for domestic OEMs. GB/T vehicle networking standards mandate conformance testing that favors Shanghai and Shenzhen electronics clusters. Tier-1 suppliers in the Yangtze River Delta are qualifying managed switch portfolios for 2026-2028 model year programs under compressed timelines.
Germany
Premium OEMs are consolidating approved vendor lists to three switch families per speed grade for central compute gateways. EU Cyber Resilience Act requirements for hardware root-of-trust are mandating firmware signing infrastructure. Bavaria-based electronics integrators face requalification pressure as zonal architectures compress legacy domain-based wiring harnesses.
United States
NHTSA-aligned functional safety expectations and IRA domestic content rules are reshaping supplier footprint decisions for EV platforms. Tier-1 suppliers are sourcing from US-based backend facilities to satisfy North American assembly requirements. Michigan and Texas electronics clusters are absorbing the bulk of design-in activity for 2026-2028 programs.
Japan
METI-supported autonomous driving roadmaps are pulling multi-gigabit Ethernet into central fusion compute modules. JIS standards for automotive networking create parallel qualification tracks that extend new product introduction cycles. Kanto and Kansai electronics clusters are concentrating SerDes PHY development for 10 Gigabit roadmap products.
South Korea
MFDS-equivalent automotive safety expectations and domestic OEM platform sourcing are driving managed switch procurement for Level 2+ ADAS programs. Seoul Capital Area electronics integrators are qualifying switches with embedded hardware security modules. Busan-Ulsan manufacturing corridors are absorbing volume production for export-oriented vehicle programs.
Automotive Ethernet Switches Market Vendor Landscape
United States producers anchor the high-speed connectivity tier; European specialists hold integrated vehicle network processor positions. The vendor base concentrates around three strategic archetypes: SerDes IP licensors, functional safety-integrated processor suppliers, and manufacturing-scale discrete switch fabric providers. Consolidation pressure is intensifying as OEMs lock specifications across five-to-seven year platform lifecycles. Competitive moves center on AEC-Q100 qualification breadth expansion and TSN conformance testing capacity acquisition.
Among US-based semiconductor suppliers, Broadcom Inc., Texas Instruments Incorporated, and Marvell Technology, Inc. occupy positions that exemplify the scale-driven and IP-rich archetypes. Broadcom represents the SerDes-intensive connectivity tier where PHY technology concentration creates single-source exposure. Texas Instruments anchors manufacturing-scale competition across temperature grade breadth. Marvell sits within the multi-gigabit roadmap segment where central compute aggregation demands are reshaping supplier qualification requirements.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Infineon Technologies AG |
| Broadcom Inc. |
| Molex, LLC |
| Cadence Design Systems, Inc. |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| Keysight Technologies, Inc. |
| Marvell Technology, Inc. |
| Others |
Supply Flow & Price Mechanics
Copper price volatility on the London Metal Exchange cascades through automotive Ethernet switch manufacturing, compressing margin pools for tier-2 suppliers while concentrating pricing power with foundry-qualified SerDes IP holders. This raw-material cost pressure intersects with AEC-Q100 Grade 2 qualification barriers to stratify component pricing across managed, unmanaged, and PoE switch tiers.
Pricing Analysis
Capacity additions in Taiwan are reshaping price floors for Gigabit Ethernet PHY silicon, forcing second-tier suppliers toward cost-optimized unmanaged switch configurations. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D qualified managed switches from fixed-configuration alternatives. Cost compression in the economy tier intensifies because Chinese EV assemblers prioritize per-unit procurement over firmware programmability. Tier-1 electronics integrators exhibit lowest price sensitivity given five-to-seven year platform specification locks, while aftermarket diagnostic vendors face acute margin pressure under EU Cyber Resilience Act compliance burdens.
Supply Chain Analysis
Advanced SerDes PHY IP rests on a concentrated base of Taiwan, South Korea, and United States design houses qualified for automotive-grade foundry processes. Silicon wafer supply draws from TSMC and Samsung Foundry captive production, while AEC-Q100 test capacity hinges on specialized facilities in Germany and Japan. Single-source vulnerability in 10 Gigabit roadmap products creates procurement risk for OEM central compute programs. Distribution runs through authorized tier-1 electronics distributors with bonded inventory programs for just-in-time zonal gateway assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as zonal E/E architecture migration locks switch specifications across multi-year vehicle lifecycles. OEM platform sourcing decisions create predictable revenue visibility for qualified suppliers.
For Market Incumbents: Lock in platform-level sourcing contracts before 10 Gigabit Ethernet design-ins crystallize around established SerDes IP holders. Defensive consolidation of AEC-Q100 Grade 2 qualification breadth across temperature grades protects against emerging competitors from Chinese electronics clusters. Vertical integration into TSN conformance testing capacity reduces production release bottlenecks for zonal gateway programs. For New Entrants and Emerging Players: Begin with unmanaged switch configurations for cost-optimized Chinese EV platforms where cybersecurity requirements remain lighter than European mandates. White-space opportunity concentrates in PoE switch integration for seat and climate modules, where IEEE 802.3bu power delivery unifies data and 48V actuator control. Go-to-market positioning through Yangtze River Delta tier-1 integrators accelerates domestic qualification timelines under MIIT-guided standards. For Investors and Strategic Acquirers: Asymmetric upside sits with functional safety-integrated processor suppliers possessing ISO 26262 ASIL-B to ASIL-D decomposition capabilities. Long-term viability over the next decade favors vendors with captive SerDes PHY development and hardware security module integration. Watch TSN conformance test house capacity expansion as the inflection signal for production release velocity in zonal architecture programs.| Strategic Initiative | Industry Significance |
|---|---|
| TSN Conformance Testing Capacity Acquisition | Expands production release velocity for IEEE 802.1AS-qualified zonal gateway programs. |
| Hardware Security Module Integration | Enables UN ECE WP.29 compliance for managed switch procurement by German premium OEMs. |
| SerDes PHY IP Vertical Integration | Captures multi-gigabit roadmap positioning for raw lidar data aggregation in central compute modules. |
| Power-over-Ethernet 100W Capability Development | Unifies data and 48V actuator power for seat and climate module harness reduction. |
| US Backend Facility Qualification | Satisfies IRA domestic content rules for EV tax credit eligibility in North American assembly. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-1 supplier procurement leads, automotive semiconductor R&D directors, and TSN test house certification specialists combined with secondary validation from SEC 10-K filings, IHS Markit vehicle registration databases, MIIT intelligent connected vehicle policy disclosures, and IEEE standards committee documentation. Triangulation across these sources calibrated switch content-per-vehicle assumptions across passenger and commercial segments.
Input-output matrices mapped switch procurement volumes against zonal architecture penetration rates, PHY speed tier adoption curves, and regional production cluster concentrations. Segmentation dimensions modeled include product type, technology generation, end-user category, and installation configuration. CAGRs derived from slope-consistent growth trajectory analysis anchored to OEM platform lifecycle timing. Forecast inputs incorporated AEC-Q100 qualification timeline data and UN ECE WP.29 regulatory deadline schedules.
Several conditions sit outside the modeled scope, including potential IEEE 802.1 standards revision timelines, foundry capacity allocation shifts for automotive-grade processes, and geopolitical disruptions to China-Europe electronics trade corridors. Forecasts reflect documented assumptions about zonal architecture migration velocity and tier-1 supplier consolidation patterns. A small set of named triggers warrants ongoing watch: TSN conformance test house capacity expansion, SerDes PHY IP licensing dispute outcomes, and EU Cyber Resilience Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Automotive Throttle Position Sensor Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Automotive Grade Inductors Market
Automotive Circuit Systems
Ignition Control Module Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Automotive Steer-by-Wire Actuator Market
Automotive Circuit Systems
Traction Control System Market