
 High Speed Engine Market | 2026-2036
High Speed Engine Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Engine Market Intelligence
OEM-direct procurement channels for marine and power generation applications is reconfiguring as engine makers consolidate authorized distributor networks. Caterpillar leverages its captive dealer system to control aftermarket parts flow and service revenue. Cummins Inc. competes through modular platform architectures that span multiple horsepower bands and emission tiers. Wärtsilä Corporation anchors its position in medium-speed crossover segments while extending electronics and controls integration.
High speed engines are internal combustion power units operating above 1,000 revolutions per minute, typically featuring compact cylinder blocks, forced induction systems, and precision fuel injection to deliver high power-to-weight ratios for propulsion and stationary power. Turbocharged configurations dominate commercial marine and genset applications where brake mean effective pressure determines fuel efficiency and transient load response. Diesel fuel type retains the largest installed base across industrial and marine end users, though ethanol-capable spark-ignited variants are gaining share in stationary power where carbon intensity regulations tighten. Aerospace application demand concentrates in auxiliary power units and emergency systems, while automotive high speed engine volumes shift toward hybrid-electric architectures.
EPA Tier 4 Final mandates in the United States, EU Stage V frameworks enforced by member state regulators, and IMO Tier III standards administered by flag-state authorities are reshaping combustion architecture, aftertreatment sizing, and fuel system calibration across all major sales geographies. Engine makers must certify platforms under multiple regimes simultaneously, raising development costs and narrowing the field of compliant suppliers. Stakeholders should monitor how ammonia and hydrogen pilot fuel programs rewrite the engineering specification for high speed combustion systems.
Market Dynamics
EPA Tier 4 Final and EU Stage V emission standards are forcing simultaneous combustion architecture redesigns, aftertreatment sizing increases, and fuel system recalibrations across all major sales geographies. Engine makers must certify platforms under multiple regulatory regimes simultaneously, compressing development timelines and raising barriers to compliant supply.
Growth Catalysts
- Data center power generation:Hyperscale facilities in the United States, Germany, and India are expanding orders for high speed diesel and gas engines to secure on-site backup capacity and grid-independent operations.
- IMO Tier III standards:Flag-state authorities administering these marine emission rules are accelerating scrubber and selective catalytic reduction retrofits in commercial shipping fleets.
- Dual carbon goals:China's national carbon neutrality targets are concentrating state procurement for distributed power applications using high speed natural gas engines in industrial clusters.
Market Restraints
- Platinum group metal costs:Diesel oxidation catalysts and diesel particulate filters require palladium and platinum inputs subject to South African and Russian supply concentration.
- Technical limitation in ammonia combustion:Pilot fuel ignition systems for ammonia dual-fuel engines face incomplete combustion at partial load conditions, delaying commercial marine adoption.
- Substitution threat from solid oxide fuel cells:Stationary power buyers in Japan and Germany are evaluating fuel cell systems for baseload generation below 10 megawatts.
Strategic Opportunities
- Underpenetrated geography:Vietnam's industrial zone expansion and port modernization are creating first-mover positions for high speed marine propulsion and genset suppliers.
- Technology convergence:Integration of cylinder pressure indication with cloud-based predictive maintenance platforms is enabling performance-optimized service contracts.
- Regulatory tailwind:The EU Green Deal's carbon border adjustment mechanism is incentivizing European manufacturers to source low-carbon intensity engines for export production.
Industry Challenges
- Aftertreatment thermal management:EPA Tier 4 Final cold-start emission compliance requires complex exhaust temperature modulation strategies that strain control system calibration resources.
- Skill gap in combustion modeling:Engine developers face scarcity of specialists capable of simulating turbulent flame propagation in high-pressure direct-injection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Engine Market |
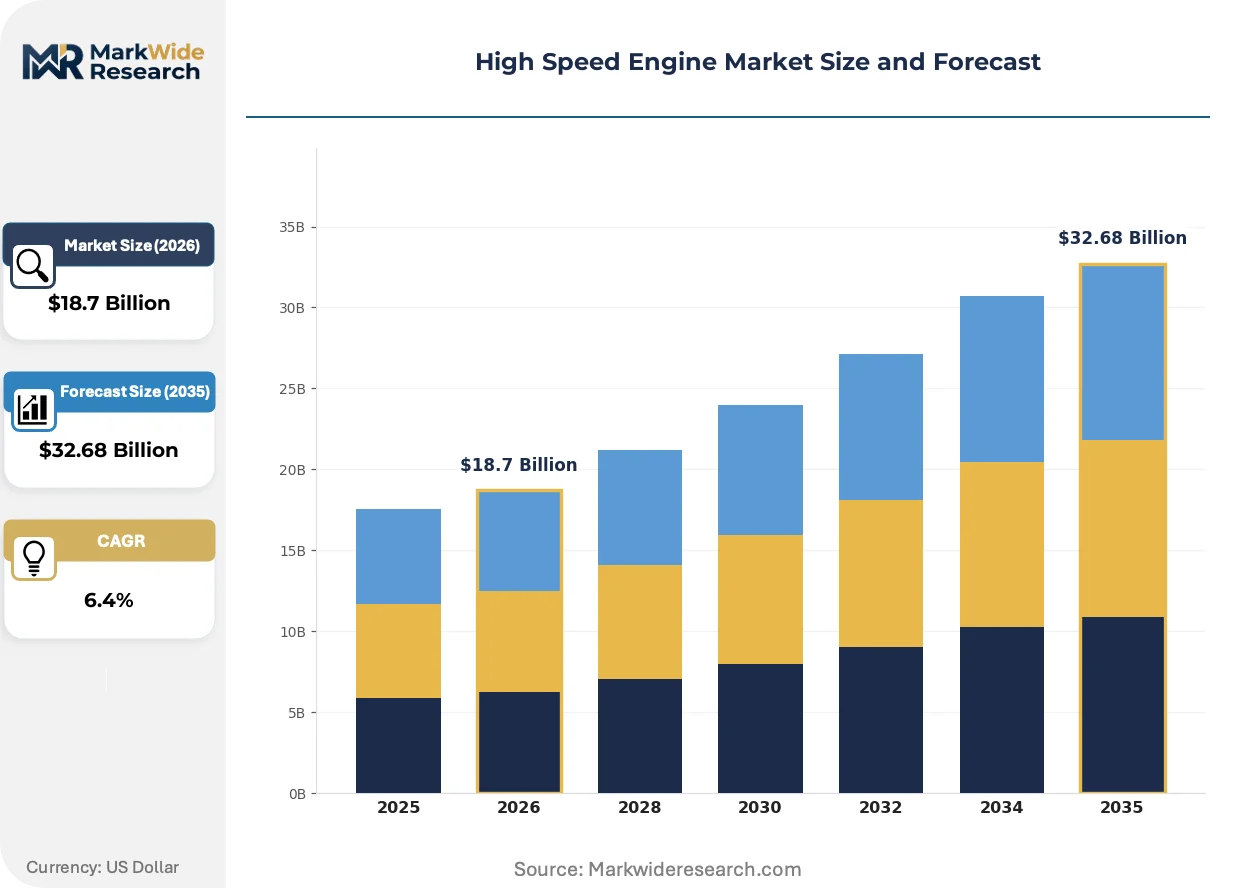
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Turbocharged, Naturally Aspirated, Supercharged, Hybrid Fuel Type: Gasoline, Diesel, Ethanol, Biodiesel Application: Aerospace, Marine, Automotive, Industrial End User: OEMs, Aftermarket Providers, Government, Private Sector |
| Companies Covered | Caterpillar, Cummins Inc., Rolls-Royce Holdings plc, Volvo Penta, MAN Energy Solutions SE, Wärtsilä Corporation, Yanmar Co., Ltd., Mitsubishi Heavy Industries, Ltd., Weichai Power Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Engine Market Strategic Shifts & Innovations
High speed engine architecture is pivoting toward modular platform designs that span multiple emission tiers and fuel types through common cylinder heads and crankcase structures. This convergence is compressing development cycles while expanding addressable application scope.
Variable geometry turbocharging is migrating from heavy-duty truck applications into marine and stationary power segments. Ship operators in Norway and ferry fleets across the Baltic are adopting these systems to improve transient load response. The technology is migrating from automotive-derived designs toward purpose-built marine configurations with corrosion-resistant turbine housings.
EPA Tier 4 Final mandates in the United States are reshaping aftertreatment packaging and thermal management strategies. Engine makers must integrate diesel oxidation catalysts, diesel particulate filters, and selective catalytic reduction into compact envelopes without sacrificing power density. Off-highway equipment manufacturers in construction and agriculture are absorbing the largest cost and space penalties.
Buyer concentration among hyperscale data center operators is compressing procurement cycles and standardizing performance specifications. These operators in Northern Virginia, Frankfurt, and Singapore are issuing multi-year framework agreements that lock in service pricing and parts availability. Channel relationships are consolidating around OEM-direct contracting with reduced distributor intermediation.
High Speed Engine Market Segmentation
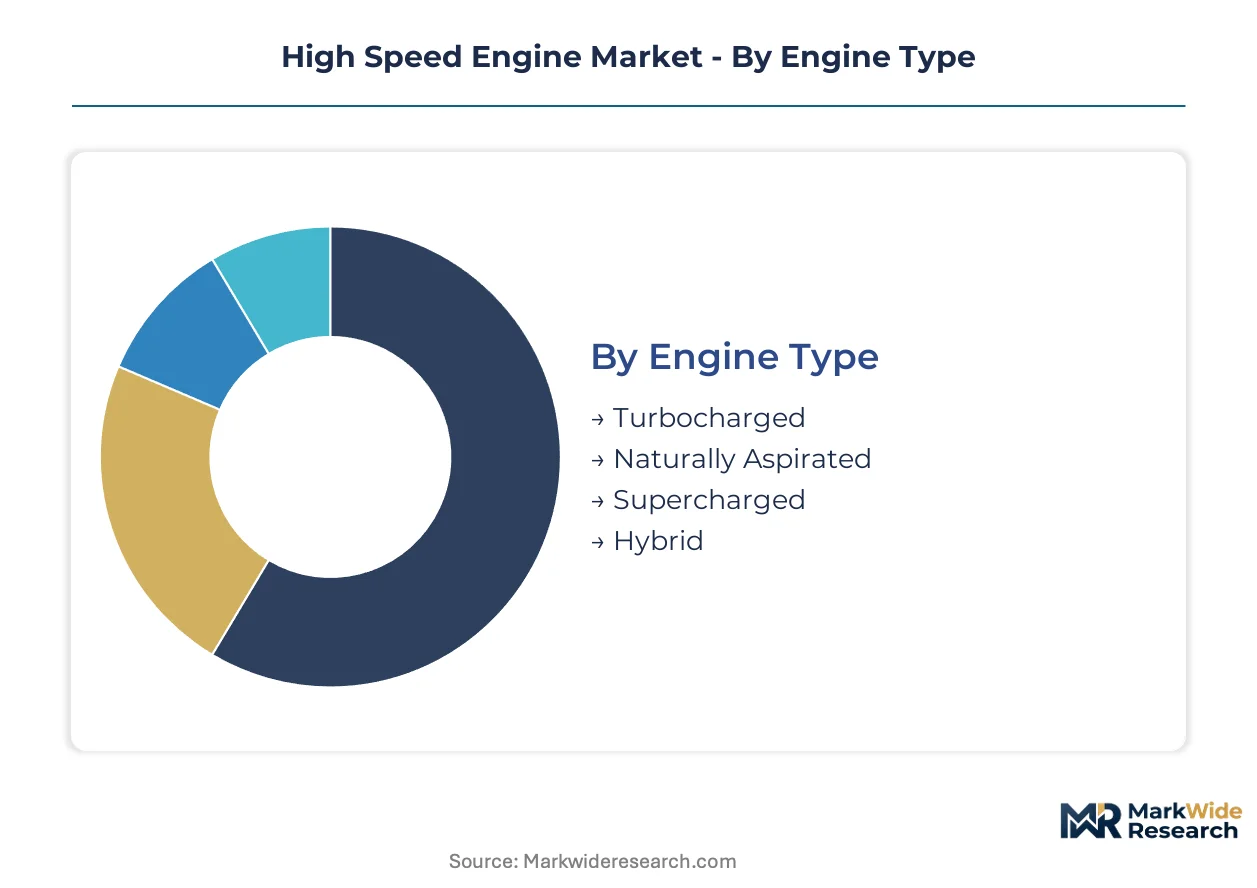
Segmentation in the high speed engine market reveals distinct service intensity patterns across configurations. Turbocharged marine units demand continuous cylinder pressure monitoring and turbocharger overhaul programs, while industrial diesel gensets concentrate procurement around long-term service contracts and predictive maintenance platforms.
Engine Type:
After-sales service intensity varies sharply across forced-induction architectures, with turbocharged platforms requiring specialized turbine balancing and intercooler maintenance that reshape channel economics.
- Turbocharged:Forced induction via exhaust-driven turbines delivers brake mean effective pressure above 25 bar for commercial marine and data center genset applications. Demand concentrates in Norway's ferry fleets and hyperscale facilities in Northern Virginia where transient load response requirements drive specification. Service revenue per unit runs three times higher than naturally aspirated equivalents due to turbocharger overhaul cycles.
- Naturally Aspirated:Atmospheric induction without compressor assistance limits power density but reduces mechanical complexity for emergency backup and light-duty industrial roles. Demand clusters in Southeast Asian manufacturing zones where first-cost sensitivity dominates procurement and local technician availability constrains maintenance sophistication.
- Supercharged:Mechanically driven compressors provide immediate boost response for high-performance marine and aerospace auxiliary power units. Applications favor military and coast guard specifications requiring instantaneous power delivery.
- Hybrid:Integrated electric motor assistance enables downsized combustion cores with load-leveling functionality. Pilot programs in German inland shipping and Singapore port operations are validating fuel consumption reduction claims against capital cost premiums.
Turbocharged configurations hold the largest share; momentum sits with hybrid architectures as battery cost curves improve electric assist economics.
Fuel Type:
Cost tier stratification separates premium low-carbon alternatives from established hydrocarbon baselines, with fuel pathway availability determining regional adoption ceilings.
- Diesel:Compression-ignited mineral distillate retains dominant installed base across marine propulsion and stationary power with established supply chains and technician familiarity. EPA Tier 4 Final compliance costs concentrate in aftertreatment hardware rather than combustion redesign, preserving platform continuity for fleet operators in the United States and India.
- Gasoline:Spark-ignited light distillate serves aerospace auxiliary power units and small-scale industrial equipment where power-to-weight ratio outweighs thermal efficiency considerations. Demand localizes in North American and European general aviation sectors with mature avgas distribution networks.
- Ethanol:Bio-derived alcohol blends reduce carbon intensity metrics for stationary power buyers facing EU Green Deal carbon border adjustment exposure. Brazilian sugarcane ethanol and US corn ethanol pathways compete on lifecycle carbon accounting methodologies.
- Biodiesel:Fatty acid methyl ester from waste feedstocks offers drop-in compatibility with existing diesel infrastructure for marine and industrial users seeking fuel diversification without engine modification. European Union renewable fuel mandates accelerate uptake in German and Dutch inland shipping.
Diesel retains dominant position; biodiesel gains share fastest where renewable fuel quotas tighten compliance pathways.
Application:
Volume concentration diverges between high-unit automotive production and low-unit, high-value marine and aerospace programs with divergent margin structures.
- Marine:Commercial shipping and ferry propulsion applications specify medium-speed crossover architectures with IMO Tier III aftertreatment integration. Norwegian operators and Baltic Sea flag states drive scrubber and selective catalytic reduction retrofits that extend engine overhaul intervals.
- Industrial:Stationary power generation for data centers, manufacturing facilities, and oilfield operations prioritizes grid-independent capacity and black-start capability. Hyperscale operators in Germany and India consolidate procurement through multi-year framework agreements standardizing performance envelopes.
- Aerospace:Auxiliary power units and emergency systems require extreme power density with airworthiness certification timelines stretching development cycles. Demand concentrates in commercial aviation fleet renewal programs and defense procurement.
- Automotive:High speed internal combustion volumes shift toward hybrid-electric architectures with engine downsizing and thermal efficiency optimization. Passenger car and light truck applications face electrification displacement pressure in European and Chinese markets.
Industrial applications hold the largest share; marine represents the steepest expansion trajectory as fleet renewal accelerates under emission mandates.
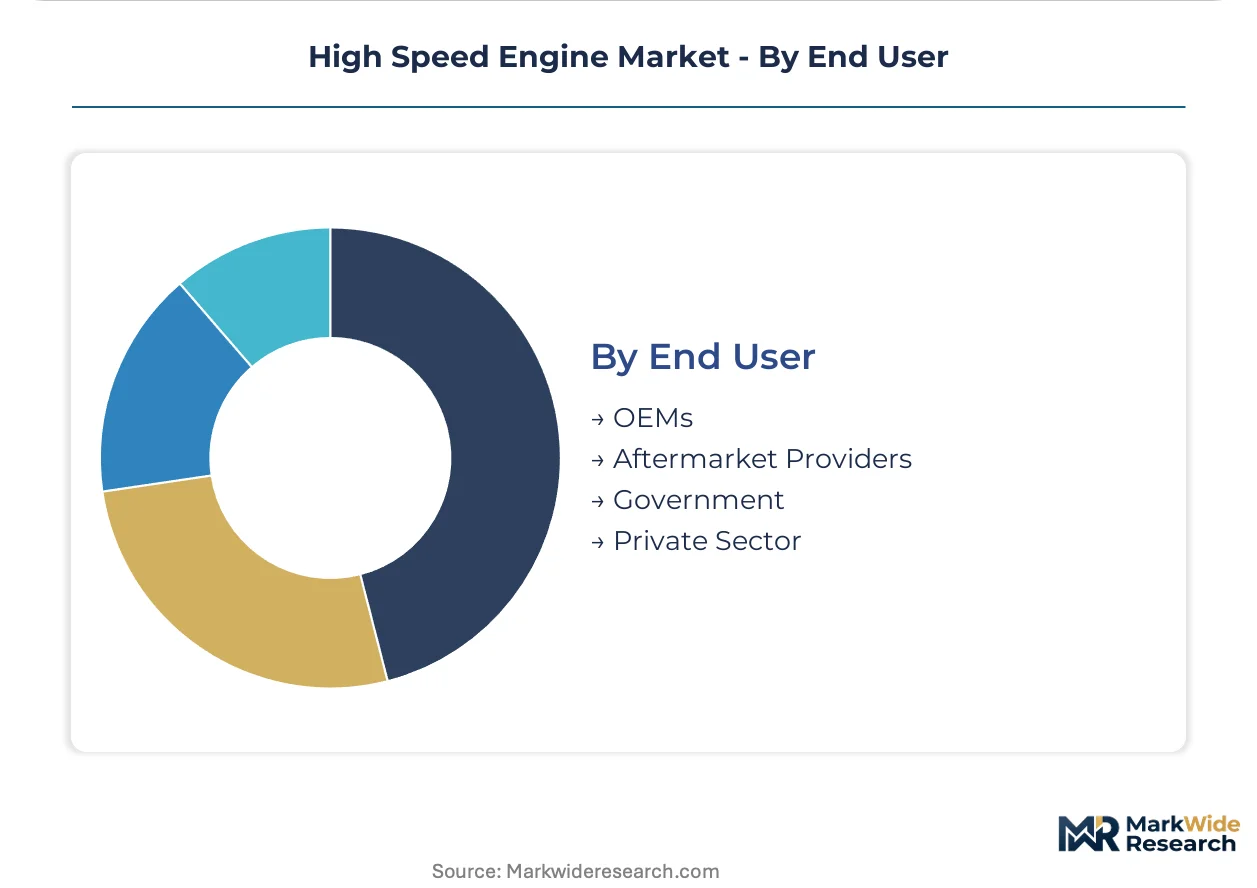
End User:
Customer type segmentation reveals procurement pattern divergence between specification-integrated OEM channels and price-sensitive aftermarket replacement demand.
- OEMs:Original equipment manufacturers integrate engines into vessel, vehicle, and equipment platforms with captive specification control and volume pricing leverage. Caterpillar's dealer network and Cummins' direct contracting models illustrate divergent channel strategies for marine and power generation bundling.
- Private Sector:Industrial facility operators and fleet owners prioritize total cost of ownership with service contract structuring and parts availability guarantees. Data center operators in Singapore and Frankfurt standardize on OEM-direct procurement with reduced distributor intermediation.
- Government:Defense, coast guard, and public utility procurement emphasizes domestic content requirements and offset agreements over pure price competition. Flag-state naval specifications often mandate specific emission compliance pathways independent of commercial standards.
- Aftermarket Providers:Independent rebuilders and parts distributors serve aging installed base with remanufactured components and non-original equipment alternatives. Channel consolidation around authorized networks constrains independent market access in developed economies.
OEMs command the largest share; aftermarket providers are expanding most quickly as installed base age extends rebuild demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Panama Canal expansion and US inland waterway lock systems anchor Americas-based marine propulsion demand, while China's Yangtze River Delta port cluster and Germany's Rhine-Danube corridor concentrate industrial power generation procurement.
United States
Hyperscale data center construction in Northern Virginia and Texas drives diesel and natural gas genset procurement for grid-independent backup capacity. EPA Tier 4 Final emission mandates force aftertreatment integration into compact engine envelopes. Caterpillar's captive dealer network controls parts flow across the Midwest manufacturing belt.
Germany
Industrial clusters in North Rhine-Westphalia and Bavaria specify high speed engines for combined heat and power installations under EU Green Deal carbon border adjustment exposure. EU Stage V frameworks administered by the KBA reshape combustion calibration timelines. Frankfurt's data center operators consolidate procurement through multi-year framework agreements.
China
State procurement concentrates in Yangtze River Delta industrial zones for distributed natural gas power under dual carbon goals. The MEE enforces emission standards that compress development cycles for domestic engine makers. Weichai Power anchors manufacturing in Shandong Province with platform architectures spanning multiple horsepower bands.
India
Port modernization in Gujarat and Maharashtra creates demand for marine propulsion systems with IMO Tier III compliance pathways. The CEA regulates grid interconnection standards for captive power plants. Cummins Inc. competes through modular designs adapted to Indian emission tier transitions.
Norway
Ferry fleet electrification programs in the Baltic and North Sea corridors drive hybrid engine pilot deployments. Flag-state authorities administer IMO Tier III scrubber and selective catalytic reduction retrofits. Wärtsilä Corporation extends electronics integration from medium-speed crossover segments into high speed auxiliary systems.
High Speed Engine Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in forced-induction and fuel injection architectures. The vendor base concentrates around consolidated OEM-direct channels with authorized distributor networks controlling aftermarket revenue. Three archetypes dominate: captive dealer systems, modular platform architects, and electronics-integrated system bundlers. M&A activity targets control system capabilities while capacity expansion focuses on emission-compliant assembly lines.
Among US-based platform integrators, Caterpillar and Cummins Inc. exemplify divergent channel strategies for marine and power generation bundling. Wärtsilä Corporation occupies a position bridging medium-speed and high speed segments with controls integration. These three anchors represent the spectrum from captive distribution to modular architecture to electronics convergence.
| Leading Market Players |
|---|
| Caterpillar |
| Cummins Inc. |
| Rolls-Royce Holdings plc |
| Volvo Penta |
| MAN Energy Solutions SE |
| Wärtsilä Corporation |
| Yanmar Co., Ltd. |
| Mitsubishi Heavy Industries, Ltd. |
| Weichai Power Co., Ltd. |
| Others |
Cost & Logistics Intelligence
South African and Russian platinum group metal concentration anchors cost structures for diesel oxidation catalysts and particulate filters, compressing margin pools downstream at engine makers and tier-one aftertreatment integrators. OEM-direct procurement by hyperscale data center operators amplifies volume leverage, redirecting margin capture toward service contract bundling and captive parts distribution.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by emission certification grade and after-sales service bundling. Premium tiers command pricing power through EPA Tier 4 Final and EU Stage V compliance guarantees paired with predictive maintenance platforms. Price differentiation hinges on turbocharger specification and thermal management calibration sophistication. Cost compression in standard-tier marine propulsion intensifies as Chinese and Indian domestic makers expand platform coverage. Industrial genset buyers in Southeast Asia exhibit highest price sensitivity, while Norwegian ferry operators and Northern Virginia data center developers prioritize performance guarantees over first cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electronic control modules and precision fuel injection components. Manufacturing concentrates in Germany, China, and the United States for cylinder blocks and crankcase assemblies. Component sourcing draws from South Africa for platinum group metals, Japan for turbocharger turbine wheels, and South Korea for high-pressure common rail systems. Single-source vulnerability persists in selective catalytic reduction substrate supply. Distribution runs through authorized dealer networks controlled by Caterpillar and Cummins, with independent aftermarket channels constricting in developed economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around modular engine architectures that span diesel, gas, and pilot-fuel variants through shared cylinder heads and electronic control systems. Interoperability between Wärtsilä's medium-speed electronics and high speed auxiliary configurations illustrates ecosystem convergence.
For Market Incumbents: Harden aftermarket revenue capture by deepening captive dealer network control over turbocharger overhaul cycles and predictive maintenance platform subscriptions. Consolidate authorized distributor tiers to constrain independent parts channel access. Capacity addition in Vietnam's industrial zones defends position against Chinese engine makers expanding Southeast Asian coverage.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's port modernization and industrial zone expansion where first-mover positions remain available for marine propulsion and genset suppliers. Target hybrid-electric marine auxiliary systems in German inland shipping pilot programs. Go-to-market leverage rests on cloud-based cylinder pressure indication integration with performance-guaranteed service contracts.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed control system specialists holding automotive-derived turbocharger electronics applicable to marine migration. Long-term viability centers on ammonia and hydrogen pilot fuel combustion architecture readiness. Acquisition targets include cylinder pressure indication software platforms and corrosion-resistant marine turbocharger housing manufacturers. Watch IMO Tier III scrubber retrofit acceleration in Baltic and North Sea flag states as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Cummins' architecture spanning multiple horsepower bands compresses development cycles across emission tiers. |
| Backward Integration into Aftertreatment | Caterpillar's captive catalyst substrate sourcing insulates margin from South African platinum volatility. |
| Electronics-Controls Convergence | Wärtsilä extends medium-speed automation into high speed marine auxiliary systems. |
| Hybrid-Electric Pilot Deployment | German inland shipping and Singapore port operations validate fuel consumption reduction claims. |
| Authorized Network Consolidation | OEM-direct contracting with hyperscale data center operators reduces distributor intermediation. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with marine fleet engineering directors, data center facility procurement managers, engine OEM platform architects, aftermarket service contract administrators, and turbocharger remanufacturing specialists. Secondary validation drew from EPA certification filings, EU Stage V type-approval databases, IMO marine engine records, customs trade data for platinum group metal flows, and SEC 10-K disclosures from listed engine manufacturers. Bottom-up unit shipment estimates by configuration and fuel type were triangulated against top-down market value reconstruction.
Calibration against historical emission standard implementation cycles and fleet renewal patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include engine type, fuel configuration, application vertical, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and replacement demand maturation. Forecast inputs incorporated platinum group metal price trajectory assumptions and data center construction pipeline tracking.
Sensitivities concentrate around IMO Tier III enforcement acceleration and ammonia dual-fuel combustion commercialization timelines. Forecasts reflect documented assumptions on emission standard harmonization and aftermarket channel consolidation. Material shifts in carbon border adjustment mechanism scope or solid oxide fuel cell cost competitiveness would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Tuning Box Market
Powertrain
Engine Flush Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Automotive Conversion Kit Market
Powertrain
Fuel Pumps Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Drive Shaft Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Italy Electro Hydraulic Power Steering Market