
 Automotive Filter Paper Market | 2026-2036
Automotive Filter Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Filter Paper Market Analysis
Specialized pulp engineering talent is bifurcating the competitive landscape, separating manufacturers with in-house fiber formulation expertise from those dependent on commodity suppliers. Ahlstrom leverages its Nordic pulp supply chains to sustain premium cellulose output for OEM contracts. Hollingsworth & Vose anchors North American aftermarket distribution through dedicated technical service networks. Freudenberg Filtration Technologies differentiates via synthetic fiber R&D programs targeting extended service intervals.
Automotive filter paper is a porous cellulose or synthetic fiber medium engineered to specific grammage, permeability, and efficiency ratings for trapping contaminants in engine and cabin air systems. Manufacturing employs wet-laid nonwoven processes with resin impregnation to achieve pleatability and thermal stability under cyclic flow conditions. Cabin filter applications are maturing as standard equipment penetration peaks, while oil filter media in heavy-duty trucks commands margin concentration due to severe-duty specifications and synthetic fiber blends. Air filter segments for passenger cars remain volume leaders but face substitution pressure from washable electrostatic designs in aftermarket channels.
EPA emission standards and Euro 7 proposals are mandating finer particulate filtration, directly raising basis-weight and efficiency specifications for fuel and oil filter media. China's GB standards and MIIT fuel consumption rules are accelerating domestic certification requirements for filter suppliers serving BYD, Geely, and SAIC. Stakeholders must monitor regulatory divergence between European particle-number limits and US gravimetric standards, as compliance strategies for one jurisdiction may not transfer to the other.
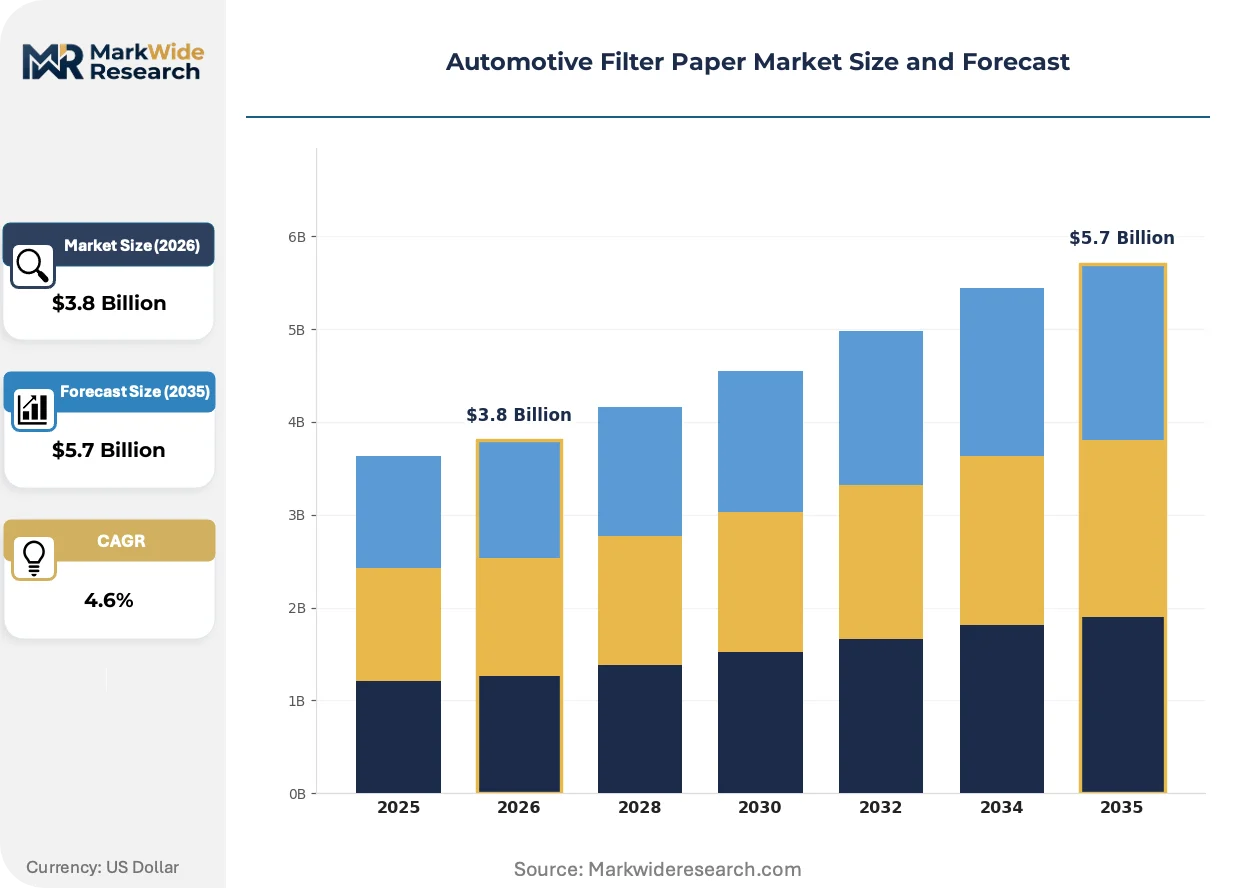
Market Dynamics
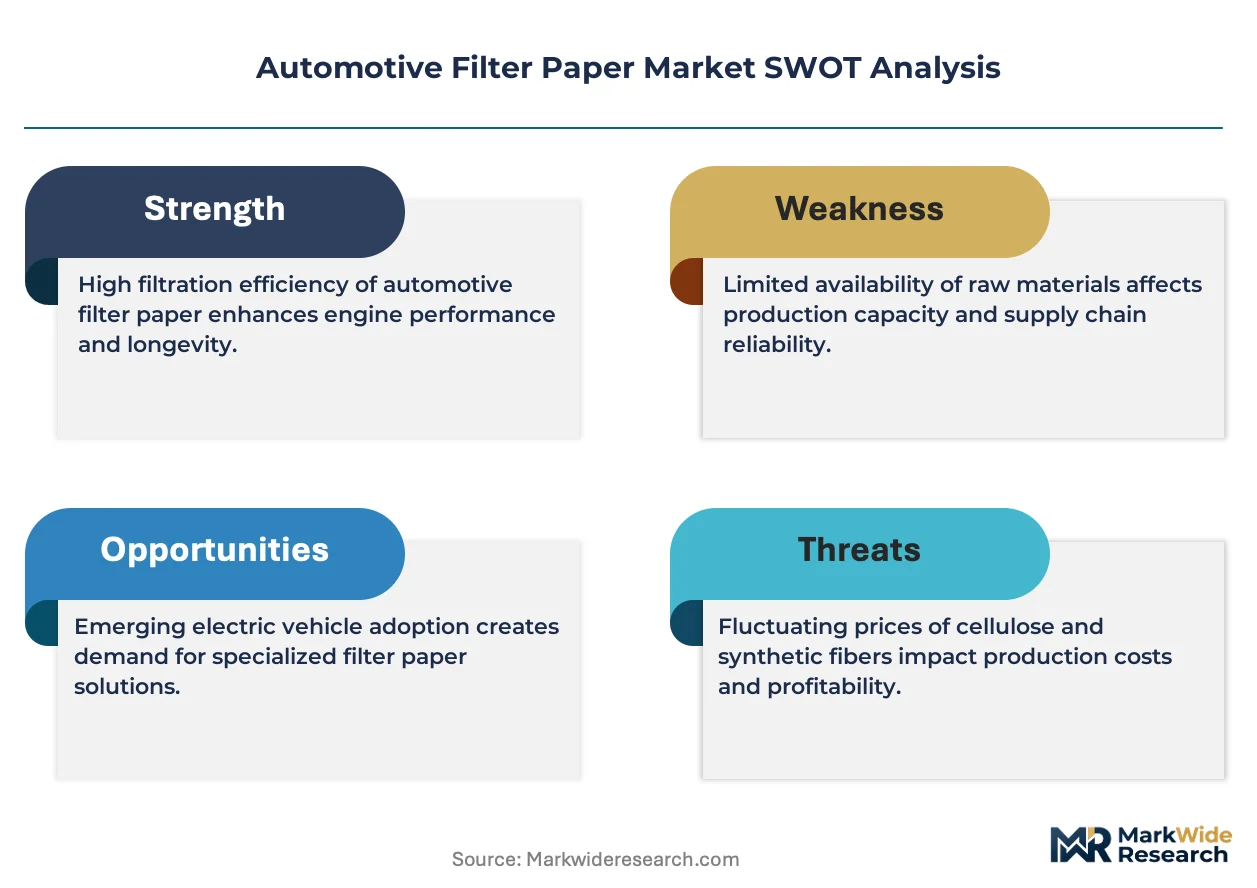
EPA Tier 3 and Euro 7 emission standards are compressing particulate capture thresholds, forcing filter media suppliers to engineer higher basis-weight papers with synthetic fiber blends while maintaining pleatability for compact engine bay geometries.
Growth Catalysts
- Heavy-duty fleet electrification lag:Diesel commercial vehicles retain extended service lives in logistics corridors, sustaining demand for severe-duty oil filter media with extended drain intervals.
- China GB standard convergence:MIIT fuel consumption rules and domestic emission protocols are mandating OEM-grade filtration for BYD and Geely captive production lines.
- Synthetic fiber R&D maturation:Glass and melt-blown polypropylene blends are enabling thinner media packs without efficiency sacrifice, opening packaging-constrained applications.
Market Restraints
- Pulp supply geographic concentration:Nordic softwood fiber availability constrains premium cellulose output for pleatable resin-impregnated grades.
- Washable electrostatic substitution:Aftermarket channels in passenger car air filtration face displacement from reusable cabin filter designs with permanent charge retention.
- Resin chemistry cost volatility:Phenolic and acrylic binder systems face feedstock price instability from petrochemical supply fluctuations.
Strategic Opportunities
- India aftermarket channel formalization:Organized service networks are displacing unbranded filter replacement, creating pull for certified media suppliers.
- Battery electric vehicle thermal management:Cabin air quality systems in EV architectures require high-capacity particulate and activated carbon media for battery pack ventilation.
- Extended service interval convergence:Synthetic blend media enabling 15,000+ mile oil changes align with OEM service bundling strategies.
Industry Challenges
- Wet-laid process engineering talent scarcity:Fiber suspension and drainage optimization for sub-micron efficiency ratings requires specialized nonwoven production expertise concentrated in aging workforces.
- Dual certification timeline compression:Simultaneous EPA gravimetric and Euro 7 particle-number validation protocols extend product qualification cycles for multi-continental suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Filter Paper Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Filters, Oil Filters, Fuel Filters, Cabin Filters Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Material: Cellulose, Synthetic Fibers, Glass Fiber, Non-Woven Fabrics End User: OEMs, Aftermarket Suppliers, Service Centers, Distributors |
| Companies Covered | Awa Paper & Technological, Mann+Hummel, Ahlstrom, Clean & Science, Shijiazhuang Chentai Filter Paper, Hollingsworth & Vose, Freudenberg Filtration Technologies, Xinji Fangli Nonwoven Technology, Neenah Gessner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Filter Paper Market Emerging Trajectories
Active material science programs are redefining filtration performance hierarchies, with synthetic fiber blends and nanofiber surface layers compressing traditional cellulose dominance while regulatory particulate thresholds tighten across major automotive production zones.
Nanofiber surface coating technology is miniaturizing capture mechanisms onto conventional substrate backbones. Tier 1 suppliers are integrating electrospun polyamide layers onto cellulose or synthetic bases for sub-micron efficiency without permeability penalty. This architecture is miniaturizing overall filter dimensions while maintaining contaminant retention ratings, enabling compact module designs in downsized engine compartments where packaging volume has become the binding constraint for air intake and crankcase ventilation systems.
REACH substance restriction proposals and EPA Significant New Use Rules are accelerating fluorochemical phase-out in oil-repellent filter treatments. Media manufacturers are pivoting to silicone and hydrocarbon-based alternatives for fuel and oil filtration applications. Heavy-duty truck segments in North America and commercial vehicle fleets in Germany face the most immediate reformulation deadlines, with KBA type-approval processes already rejecting legacy chemistries in new filter submissions.
Fleet procurement departments are consolidating filter sourcing through integrated vehicle lifecycle contracts rather than transactional aftermarket purchasing. Leasing and full-service maintenance providers are specifying single-supplier media programs with guaranteed cost-per-mile performance. This consolidation is most visible in Germany's Mittelstand logistics sector and US Class 8 truck fleet operators, where total cost of ownership modeling has displaced upfront unit price as the primary vendor selection criterion.
Automotive Filter Paper Market Segmentation
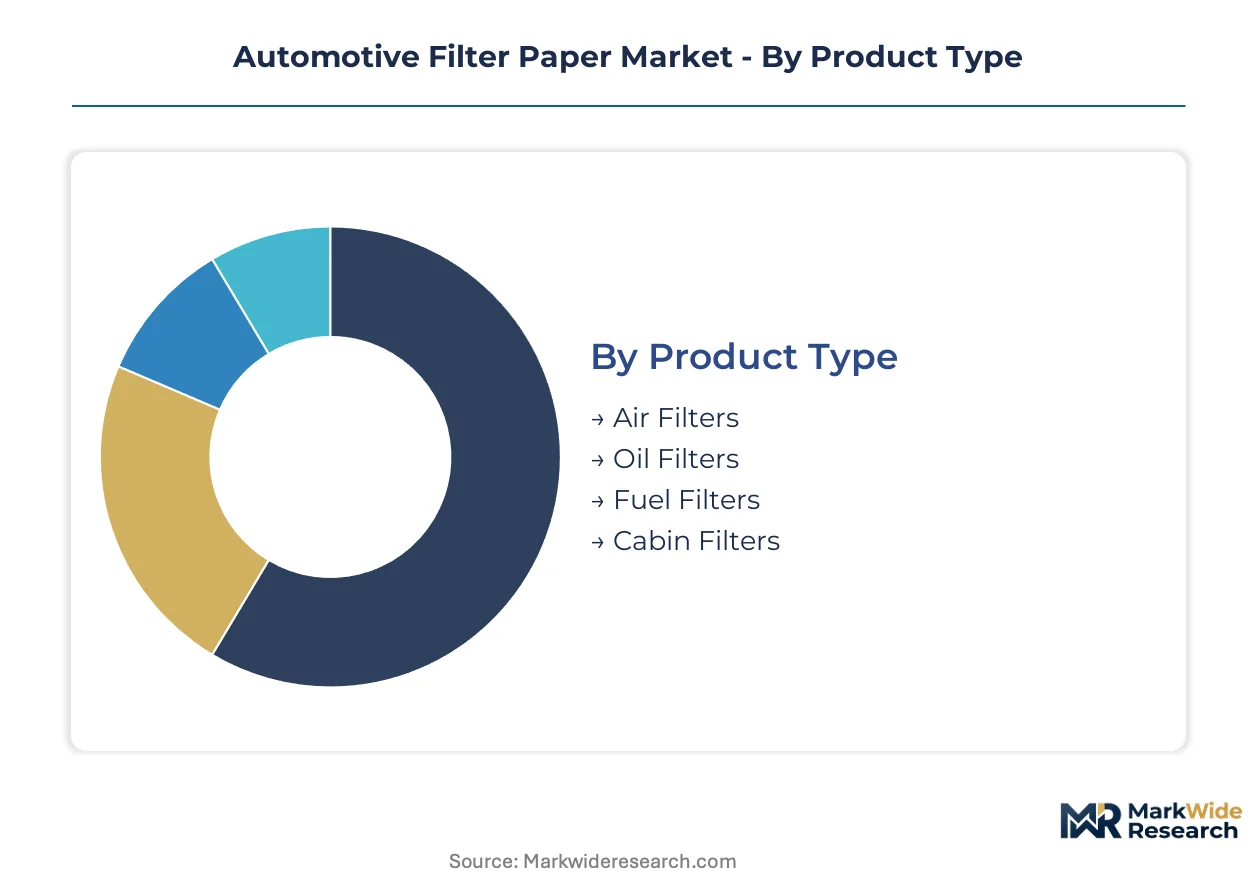
Filter paper specifications diverge sharply across automotive subsystems, with pleatability requirements and contaminant load profiles dictating material selection and basis-weight engineering. Segmentation clarity enables suppliers to align wet-laid production capacity with the diverging certification demands of OEM captive supply versus aftermarket price elasticity.
Product Type:
Washable electrostatic designs threaten replacement frequency most acutely in segments where consumer access is easiest and technical specifications are least stringent.
- Oil Filters:Resin-impregnated cellulose and synthetic fiber blends engineered for thermal stability under cyclic flow conditions. Heavy-duty truck fleets in Germany and North America specify severe-duty grades with extended drain intervals, compressing supplier margins through lifecycle cost-per-mile contracting.
- Cabin Filters:Multi-layer composites combining particulate media with activated carbon adsorption layers. China's BYD and Geely are mandating OEM-grade certification for cabin air quality systems as standard equipment penetration peaks in domestic passenger car production.
- Air Filters:Pleatable cellulose substrates dominate passenger car intake systems.
- Fuel Filters:Tighter EPA Tier 3 and Euro 7 particulate thresholds are elevating basis-weight specifications.
Oil filters retain volume leadership; cabin filters hold the steepest expansion curve as EV thermal management architectures multiply air quality system counts per vehicle.
Application:
Service interval differentiation creates distinct margin tiers, with severe-duty specifications commanding premium pricing against commodity passenger car replacement cycles.
- Heavy-Duty Trucks:Severe-duty oil filter media with synthetic fiber blends enabling 15,000+ mile drain intervals. Fleet procurement consolidation in Germany's Mittelstand logistics sector and US Class 8 operators prioritizes total cost of ownership over unit price.
- Commercial Vehicles:Diesel powertrain retention in logistics corridors sustains demand for high-efficiency filtration media as electrification lags in long-haul applications.
- Passenger Cars:Downsized engine compartments constrain packaging volume for air intake systems.
- Two-Wheelers:Cost-sensitive markets in India favor basic cellulose grades.
Heavy-duty trucks anchor margin concentration; commercial vehicles are gaining share fastest as fleet electrification timelines extend.
Material:
REACH fluorochemical phase-outs are forcing reformulation across oil-repellent treatments, advantaging suppliers with in-house synthetic fiber R&D capabilities.
- Synthetic Fibers:Melt-blown polypropylene and glass fiber blends enabling thinner media packs without efficiency sacrifice. Glass fiber R&D programs at Freudenberg and Hollingsworth & Vose target compact module designs for packaging-constrained engine bays.
- Cellulose:Nordic softwood fiber supply chains constrain premium output for pleatable resin-impregnated grades serving OEM contracts.
- Glass Fiber:Sub-micron efficiency ratings for fuel and oil filtration under Euro 7 particle-number protocols.
- Non-Woven Fabrics:Wet-laid process engineering for cabin filter composites.
Cellulose retains installed base dominance; synthetic fibers are climbing the fastest as basis-weight and efficiency specifications tighten.
End User:
OEM captive supply demands dual EPA gravimetric and Euro 7 particle-number certification, compressing qualification timelines for multi-continental suppliers.
- OEMs:BYD, Geely, and SAIC are scaling captive filter production under MIIT fuel consumption rules and domestic GB standards, requiring localized certification from media suppliers.
- Aftermarket Suppliers:India organized service networks are displacing unbranded replacement, creating pull for certified media with guaranteed performance.
- Service Centers:Fleet lifecycle contracts consolidate sourcing through single-supplier programs.
- Distributors:North American aftermarket channels face displacement pressure from washable electrostatic cabin filter designs.
OEMs command specification authority; aftermarket suppliers are expanding most quickly as India channel formalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT fuel consumption rules and GB standards in China are compressing certification timelines for filter media suppliers serving domestic OEM captive production. Regulatory divergence between EPA gravimetric protocols and Euro 7 particle-number limits is fragmenting compliance strategies across major automotive manufacturing zones.
China
BYD, Geely, and SAIC are scaling captive filter production lines under MIIT fuel consumption rules and domestic GB emission standards. MEE enforcement of dual carbon goals is tightening particulate capture requirements for commercial vehicle fleets. The Yangtze River Delta cluster around Shanghai anchors wet-laid nonwoven capacity expansion for OEM-grade certification.
Germany
KBA type-approval processes are rejecting legacy fluorochemical treatments in new filter submissions under REACH substance restriction proposals. The Mittelstand logistics sector is consolidating fleet procurement through single-supplier lifecycle contracts. Bavaria's industrial corridor hosts severe-duty oil filter media development for extended drain interval specifications.
United States
EPA Tier 3 emission standards are elevating basis-weight and efficiency specifications for fuel and oil filter media in Class 8 truck applications. Fleet operators are prioritizing total cost of ownership over unit price in procurement decisions. The Midwest manufacturing belt around Michigan and Ohio retains concentration in pleatable resin-impregnated grade production.
India
Organized service networks are displacing unbranded filter replacement in aftermarket channels, creating pull for certified media suppliers. BIS certification requirements are formalizing quality standards for domestic and import substitution. Maharashtra and Gujarat industrial clusters are scaling wet-laid capacity to serve formalizing distribution channels.
Japan
METI industrial policy is accelerating synthetic fiber R&D programs for compact module designs in packaging-constrained engine bays. JIS standards are converging with Euro 7 efficiency protocols for export-oriented OEM supply. The Kanto region around Tokyo anchors nanofiber surface coating technology development for sub-micron filtration applications.
Automotive Filter Paper Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in automotive filter paper supply. Nordic pulp supply chains and synthetic fiber R&D capabilities separate premium cellulose producers from commodity-grade competitors. Three archetypes dominate: pulp-integrated Nordic manufacturers, synthetic fiber technology specialists, and China-based scale fabricators serving domestic OEM captive demand. Competitive moves concentrate on backward integration into fiber formulation and geographic certification expansion for dual EPA-Euro compliance.
Among Nordic pulp-integrated manufacturers, Ahlstrom exemplifies premium cellulose supply chain control for OEM contract stability. Synthetic fiber technology specialists include Hollingsworth & Vose and Freudenberg Filtration Technologies, occupying positions defined by glass and melt-blown polypropylene R&D capabilities. China-based scale fabricators such as Shijiazhuang Chentai Filter Paper and Xinji Fangli Nonwoven Technology represent the cost-optimized tier serving domestic certification requirements under MIIT and GB standards.
| Leading Market Players |
|---|
| Awa Paper & Technological |
| Mann+Hummel |
| Ahlstrom |
| Clean & Science |
| Shijiazhuang Chentai Filter Paper |
| Hollingsworth & Vose |
| Freudenberg Filtration Technologies |
| Xinji Fangli Nonwoven Technology |
| Neenah Gessner |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day resin inventory buffers at Nordic pulp mills signal supply-chain rigidity that concentrates pricing power among cellulose-integrated manufacturers serving OEM-grade contracts. Wet-laid nonwoven capacity expansion in China and India is loosening aftermarket pricing discipline while compressing margins for commodity-grade suppliers dependent on spot pulp purchases.
Pricing Analysis
Forty-percent spreads separate German severe-duty oil filter media from Indian two-wheeler cellulose grades, reflecting certification-tier differentiation rather than input cost divergence. Three-tier pricing structure across premium OEM-grade, certified aftermarket, and unbranded economy levels stratifies buyer segments, with fleet procurement departments least sensitive and independent distributors most vulnerable to washable electrostatic substitution. Pricing pressure stems from phenolic resin feedstock volatility and REACH-driven fluorochemical reformulation costs. Passenger car air filter aftermarket channels face the steepest price erosion as reusable designs displace replacement frequency.
Supply Chain Analysis
Resin inventory cycles stretching to twelve weeks in Nordic softwood fiber supply chains expose media manufacturers to phenolic and acrylic binder price swings. Production gravity centers on Finland and Sweden for premium cellulose, China for synthetic fiber scale fabrication, and Germany for severe-duty engineering grades. Raw material dependencies span Nordic softwood pulp, melt-blown polypropylene, and glass fiber rovings. Single-source vulnerability concentrates in specialized wet-laid process engineering talent pools. Distribution runs through OEM captive supply agreements, organized aftermarket networks in India, and fleet lifecycle contracts in Germany and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 particle-number protocols and EPA Tier 3 gravimetric standards are compressing qualification timelines, creating asymmetric returns for suppliers with dual-certification capabilities and synthetic fiber R&D depth.
For Market Incumbents: Shield OEM contract stability by securing Nordic pulp supply agreements and accelerating nanofiber surface coating capacity before REACH fluorochemical deadlines force competitor reformulation. Backward integration into resin chemistry protects margin structures from petrochemical volatility. Prioritize wet-laid process engineering recruitment to offset aging workforce concentration. For New Entrants and Emerging Players: Anchor in India's formalizing aftermarket channels where BIS certification requirements are displacing unbranded replacement with certified media pull-through. Target synthetic fiber blend development for battery electric vehicle thermal management systems as OEMs multiply air quality module counts per vehicle. Pursue technical service partnerships with organized service networks rather than distributor price competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive filtration divisions lacking standalone scale or certification depth. Five-to-ten-year viability hinges on synthetic fiber R&D amortization across expanding EV thermal management applications. Watch for KBA type-approval rejection patterns signaling fluorochemical-dependent portfolio obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Nanofiber Surface Coating Scale-Up | Electrospun polyamide layers enable sub-micron efficiency without permeability sacrifice for compact engine bays. |
| Dual EPA-Euro Certification Investment | Simultaneous gravimetric and particle-number validation compresses competitor qualification timelines for multi-continental supply. |
| Nordic Pulp Supply Agreement Extension | Long-term softwood fiber contracts secure premium cellulose output for pleatable resin-impregnated OEM grades. |
| Fluorochemical-Free Reformulation | Silicone and hydrocarbon-based oil-repellent treatments satisfy KBA type-approval ahead of REACH enforcement deadlines. |
| India Aftermarket Channel Partnership | Organized service network alliances displace unbranded replacement with certified media in Maharashtra and Gujarat clusters. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and wet-laid process engineering specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs trade flows, and regulatory filing repositories. Bottom-up segment sizing triangulated with top-down market reconstruction from pulp and synthetic fiber consumption patterns.
Segmentation dimensions modeled span filter type, application severity, material composition, and end-user channel across the projection horizon. CAGRs derive from regression analysis against historical adoption curves adjusted for regulatory inflection points. Forecast inputs incorporate MIIT fuel consumption rule implementation timelines, fleet electrification lag assumptions for commercial vehicles, and wet-laid capacity expansion schedules in China and India.
Decision-makers should treat outputs as directional under sustained Euro 7 and EPA Tier 3 enforcement, stable Nordic pulp supply availability, and linear EV thermal management system adoption; material deviation in regulatory timelines or fiber supply disruptions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
EV Reduction Gears Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market