
 Automotive Counter Shaft Market | 2026-2036
Automotive Counter Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Counter Shaft Market Outlook
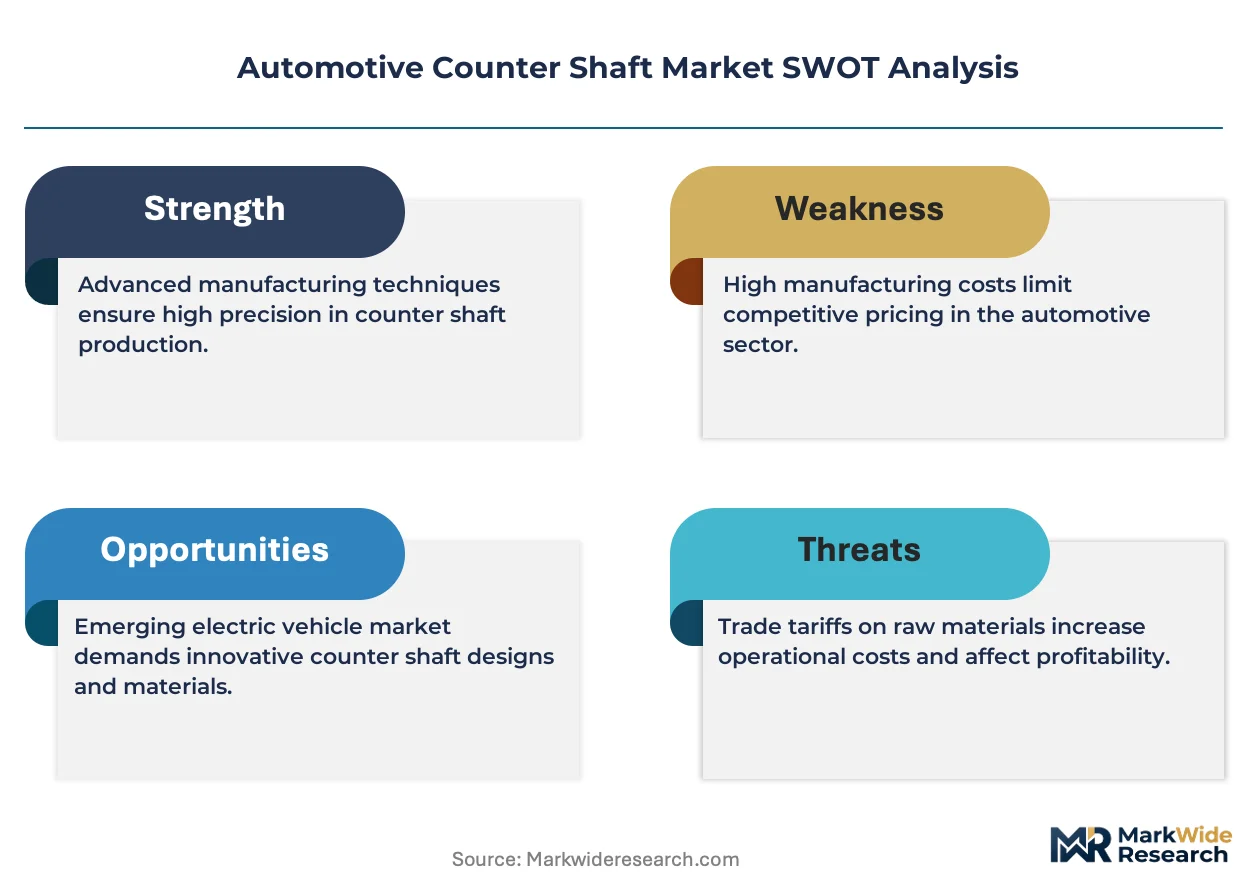
Precision-forged grade specifications is redrawing procurement criteria across the Automotive Counter Shaft Market. Hirschvogel Automotive Group leverages captive forging capacity in Germany and Mexico to anchor supply contracts with premium transmission builders. Bharat Forge dominates India's commercial vehicle counter shaft segment through backward integration into alloy steel billet production. Schaeffler AG differentiates via integrated bearing-shaft modules that reduce assembly steps for dual-clutch transmission platforms.
An automotive counter shaft is a parallel-mounted rotating element within manual, automatic, or dual-clutch transmissions that receives torque from the input shaft and distributes it through fixed or selectable gear ratios to the output shaft; manufacturers typically produce these components from case-hardened alloy steels with surface hardness exceeding HRC 58 to withstand cyclic bending and contact fatigue across million-cycle service lives. Automatic transmission counter shafts retain the largest volume share as torque converter architectures persist in North American and Japanese passenger vehicle fleets, while electric vehicle transmission shafts represent the fastest-expanding category as single-speed and multi-speed e-axle designs proliferate. Steel alloys command the dominant material position due to established forging infrastructure and cost predictability, though composite-reinforced hybrid shafts are gaining traction in high-performance electric vehicle reduction gearboxes where mass reduction justifies premium processing.
The EPA's Corporate Average Fuel Economy standards and NHTSA safety regulations in the United States compel counter shaft producers to validate fatigue life under stricter load-cycle protocols, while the EU Green Deal's embedded carbon reporting through CSRD extends compliance obligations to tier-2 forging suppliers serving European OEMs. Japan's METI enforces JIS precision standards that effectively gate market access for non-domestic shaft producers targeting Toyota, Honda, and Nissan transmission platforms. Stakeholders must monitor how China's dual carbon goals reshape alloy steel sourcing economics and whether India's PLI scheme for automotive components accelerates domestic counter shaft capacity buildout ahead of Western OEM localization timelines.
Market Dynamics
Transmission electrification timelines are compressing counter shaft design cycles as OEMs pivot from multi-speed architectures toward integrated e-axle modules, forcing forging houses to retool for hollow-bore and splined-shaft geometries at accelerated capital deployment rates.
Growth Catalysts
- China's NMPA efficiency mandates:Vehicle energy consumption thresholds now require transmission loss reductions that precision-forged alloy shafts deliver through tighter tolerance control and optimized tooth profiles.
- India's PLI scheme for automotive components:Tier-1 suppliers in Pune and Aurangabad corridors are expanding forging capacity to capture localization incentives for both domestic OEMs and export programs.
- Dual-clutch transmission proliferation:European and Japanese passenger vehicle platforms now specify integrated bearing-shaft modules that reduce assembly complexity and improve power density metrics.
Market Restraints
- Alloy steel billet price volatility:Nickel and molybdenum input costs fluctuate with mining supply disruptions, compressing margin predictability for mid-scale forging operations without captive melt shop capacity.
- Japan's METI JIS precision standards:Non-domestic shaft producers face certification barriers that effectively limit access to Toyota, Honda, and Nissan transmission platform supply chains.
- Single-speed e-axle substitution:Battery electric vehicle architectures eliminate multi-gear counter shafts entirely, threatening volume exposure for suppliers concentrated in conventional automatic transmission segments.
Strategic Opportunities
- Composite-reinforced hybrid shafts:Carbon fiber overwrapped steel cores enable 30-40% mass reduction in high-performance electric vehicle reduction gearboxes where rotational inertia penalties justify premium processing costs.
- Southeast Asia commercial vehicle buildout:Indonesia and Thailand light truck manufacturers are expanding domestic transmission assembly, creating first-mover openings for precision forging partnerships.
- EU CSRD embedded carbon reporting:Tier-2 suppliers who validate low-carbon alloy sourcing and forge energy intensity metrics gain preferred supplier status with European OEMs under Green Deal compliance frameworks.
Industry Challenges
- CNC spline grinding skill scarcity:Hardened shaft finishing requires specialized machinist training that outpaces vocational pipeline output in India's forging clusters.
- Dual-carbon alloy certification timelines:China's MEE verification protocols for low-emission steel sourcing extend procurement lead times for export-bound shaft producers.
- Legacy press reconfiguration costs:Conventional forging lines require seven-figure capital outlays to accommodate hollow-bore geometries demanded by e-axle transmission designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Counter Shaft Market |
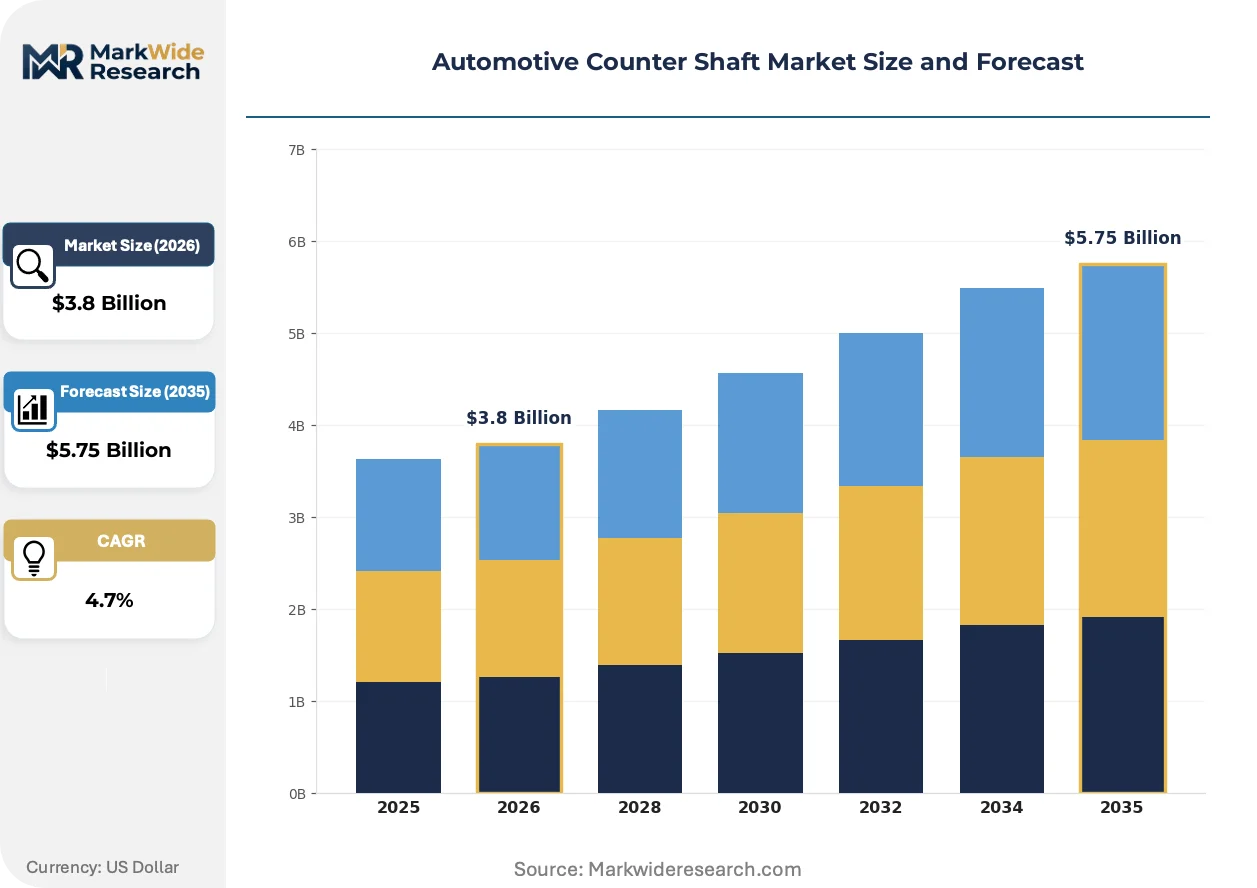
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Transmission, Automatic Transmission, Dual-Clutch Transmission, Electric Vehicle Transmission Material: Steel, Aluminum, Composite, Alloy End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles |
| Companies Covered | Hirschvogel Automotive Group, Bharat Forge, GKN Automotive, Aisin Seiki Co Ltd, ZF Friedrichshafen AG, BorgWarner Inc, Schaeffler AG, JTEKT Corporation, NSK Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Counter Shaft Market Strategic Shifts
Material science advances and regulatory carbon accounting are converging to redefine counter shaft value propositions, with forging houses now competing on validated lifecycle emissions rather than unit economics alone.
High-strength low-alloy steel grades with vanadium microalloying are supplanting conventional 8620 case-hardening steels in dual-clutch transmission counter shafts. European premium transmission builders specify these grades for their as-forged hardness capability that eliminates post-forge normalizing cycles. The resulting process compression is supplanting traditional multi-step heat treatment workflows and shortening supplier qualification timelines by 40-60%.
REACH SVHC disclosure requirements and the EU Green Deal's CSRD scope-three reporting obligations now extend to tier-2 forging suppliers serving German and French OEM transmission programs. Component-level carbon footprint validation has become a contractual gate for new platform awards, with alloy steel melt shop energy sourcing now subject to documentary audit. Suppliers operating electric arc furnace billet production in Scandinavia and hydro-powered forge shops in Austria capture preferential sourcing allocation.
Consolidated transmission assembler procurement now favors module-level suppliers capable of delivering bearing-integrated shaft assemblies rather than discrete forged blanks. Tier-1 transmission builders in Japan and South Korea specify pre-assembled counter shaft modules that reduce line-side inventory and eliminate press-fit operations. This specification compression is most visible in the premium passenger vehicle segment, where dual-clutch platform complexity rewards suppliers with in-house bearing integration capability.
Automotive Counter Shaft Market Segmentation
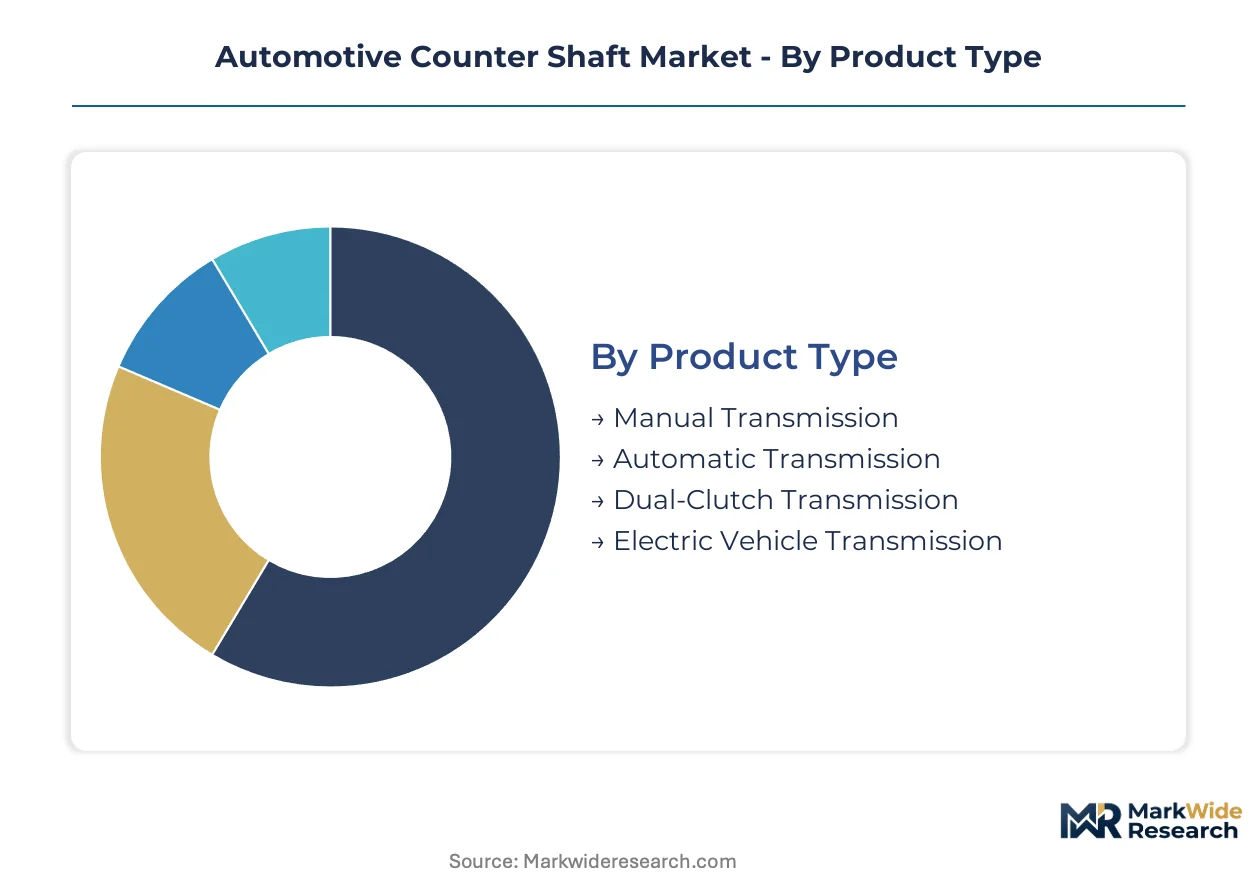
Counter shaft procurement patterns diverge sharply across transmission architectures and material specifications, with forging houses calibrating capacity investments to capture margin concentration in precision-forced alloy segments. The four-dimensional segmentation reveals how electrification timelines and regional supply chain restructuring are redrawing volume allocation across product categories.
Product Type:
Highest margin capture sits with integrated shaft-bearing modules for dual-clutch platforms, where assembly step reduction commands premium pricing from European and Japanese transmission builders.
- Automatic Transmission:Torque converter architectures in North American and Japanese passenger fleets sustain the largest volume base. Demand concentrates around legacy six and eight-speed designs where forging tolerances and surface hardness specifications are well-established.
- Dual-Clutch Transmission:European premium platforms specify pre-assembled counter shaft modules that eliminate press-fit operations at the transmission line. Schaeffler AG and Hirschvogel anchor supply contracts through captive bearing integration capability.
- Manual Transmission:Synchronous mesh designs persist in light commercial vehicles across India and Southeast Asia, where cost-sensitive procurement favors conventional forged steel shafts without modular integration.
- Electric Vehicle Transmission:Single-speed and multi-speed e-axle designs are expanding most quickly as OEMs pivot from multi-speed architectures toward integrated electric drive modules requiring hollow-bore geometries.
The dominant share belongs to Automatic Transmission, while Electric Vehicle Transmission is closing the gap fastest.
Material:
Cost tier stratification separates commodity steel procurement from premium alloy specifications where vanadium microalloying eliminates post-forge normalizing cycles.
- Steel:Conventional case-hardened grades retain volume leadership through established forging infrastructure and cost predictability across manual and automatic transmission programs.
- Alloy:High-strength low-alloy grades with vanadium microalloying are supplanting 8620 steels in dual-clutch applications. Bharat Forge dominates India's commercial vehicle segment through backward integration into alloy steel billet production.
- Aluminum:Lightweight specifications gain traction in hybrid transmission designs where mass reduction justifies processing cost premiums in European passenger vehicle platforms.
- Composite:Carbon fiber overwrapped steel cores enable 30-40% mass reduction in high-performance electric vehicle reduction gearboxes where rotational inertia penalties justify premium processing.
Steel commands the widest deployment base, though Alloy specifications are gaining share fastest among premium transmission builders.
End User:
Customer type determines qualification intensity, with OEM direct contracts demanding validated lifecycle emissions documentation under EU CSRD frameworks.
- Tier-1 Suppliers:Consolidated transmission assemblers in Japan and South Korea specify module-level procurement that reduces line-side inventory. These suppliers capture the steepest margin expansion through bearing-shaft integration.
- OEMs:Direct platform awards from Toyota, Honda, and Nissan require METI JIS precision certification that gates market access for non-domestic producers.
- Vehicle Assemblers:Light commercial vehicle manufacturers in India's Pune-Aurangabad corridor are expanding domestic forging partnerships to capture PLI scheme localization incentives.
- Aftermarket Providers:Replacement shaft demand concentrates in regions with aging automatic transmission fleets, where remanufacturing protocols differ from OEM first-fit specifications.
Tier-1 Suppliers hold the dominant procurement position, while Vehicle Assemblers are expanding captive sourcing fastest under regional incentive schemes.
Application:
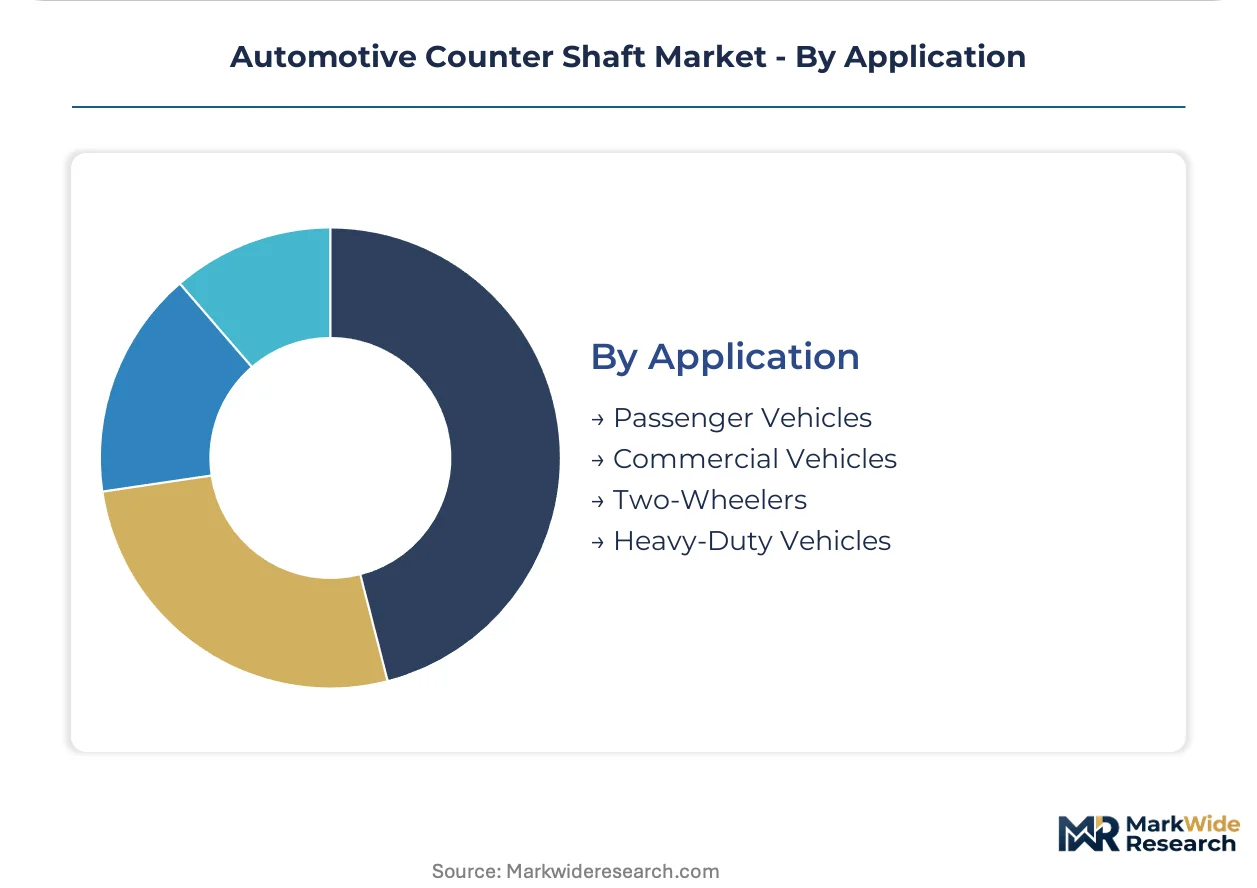
Volume concentration maps to light commercial vehicle buildout in emerging manufacturing corridors, while technology leadership clusters around passenger vehicle electrification.
- Passenger Vehicles:Dual-clutch and automatic transmission specifications drive precision-forging investment in European and Japanese supply chains. EPA Corporate Average Fuel Economy standards compel fatigue life validation under stricter load-cycle protocols.
- Commercial Vehicles:Light truck manufacturers in Indonesia and Thailand are expanding domestic transmission assembly, creating first-mover openings for precision forging partnerships in Southeast Asia.
- Heavy-Duty Vehicles:High-torque applications require surface hardness exceeding HRC 58 to withstand cyclic bending across million-cycle service lives in long-haul freight configurations.
- Two-Wheelers:Cost-optimized manual transmission designs in South Asian markets specify conventional steel shafts without modular integration or premium alloy content.
Passenger Vehicles anchor the largest volume base, though Commercial Vehicles are climbing the fastest as Southeast Asian manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement theaters. Indian commercial vehicle buyers demand cost-optimized forged shafts, while German premium transmission builders absorb alloy premiums for validated carbon footprints. Japanese OEMs impose the tightest qualification barriers.
China
NMPA efficiency thresholds compel transmission loss reductions through precision-forged alloy shafts with optimized tooth profiles. The MIIT enforces GB standards for vehicle energy consumption that cascade to component-level specifications. Yangtze River Delta forging clusters retool for hollow-bore geometries demanded by e-axle transmission designs.
Germany
Dual-clutch transmission platforms from premium OEMs specify integrated bearing-shaft modules commanding premium pricing. The EU Green Deal's CSRD extends scope-three carbon reporting obligations to tier-2 forging suppliers. Bavarian transmission assemblers validate low-carbon alloy sourcing from Scandinavian electric arc furnace producers.
India
Light commercial vehicle manufacturers in the Pune-Aurangabad corridor scale domestic forging partnerships. The PLI scheme for automotive components accelerates capacity buildout ahead of Western OEM localization timelines. Tier-1 suppliers expand precision forging to capture both domestic OEM contracts and export programs for European transmission builders.
Japan
METI enforces JIS precision standards that gate market access for non-domestic shaft producers targeting Toyota, Honda, and Nissan platforms. Dual-clutch and hybrid transmission specifications drive module-level procurement from consolidated assemblers. Kanto-based transmission builders specify pre-assembled counter shaft modules reducing line-side inventory.
United States
Torque converter architectures in North American passenger fleets sustain volume demand for legacy automatic transmission shafts. EPA Corporate Average Fuel Economy standards and NHTSA safety regulations compel fatigue life validation under stricter load-cycle protocols. Midwest transmission plants source from forging houses with captive heat treatment capacity.
Automotive Counter Shaft Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes. Precision-forging specialists with captive bearing integration command premium positioning in European and Japanese dual-clutch platforms. Scale-driven commercial vehicle suppliers dominate India's cost-sensitive procurement through backward integration into alloy billet production. Three archetypes define competitive structure: integrated module suppliers, alloy-forging specialists with melt shop control, and hollow-bore e-axle capability leaders. Consolidation pressures favor M&A between forging houses and bearing manufacturers, while capacity expansion concentrates in India's PLI-incentivized corridors.
Among German-based integrated suppliers, Schaeffler AG exemplifies the module-level archetype through bearing-shaft assembly capability. Hirschvogel Automotive Group occupies a position bridging European premium transmission specifications with Mexican export capacity. Bharat Forge represents the cost-leadership archetype through India's dominant commercial vehicle forging position. These three anchors illustrate how geographic specialization and integration depth stratify competitive positioning across procurement theaters.
| Leading Market Players |
|---|
| Hirschvogel Automotive Group |
| Bharat Forge |
| GKN Automotive |
| Aisin Seiki Co Ltd |
| ZF Friedrichshafen AG |
| BorgWarner Inc |
| Schaeffler AG |
| JTEKT Corporation |
| NSK Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive forging capacity in Germany and Mexico anchors premium pricing power for integrated suppliers serving dual-clutch transmission platforms, while mid-scale operators without melt shop control face compressed margins from alloy steel billet volatility. Scale economies in India's Pune-Aurangabad corridor enable cost-competitive positioning for light commercial vehicle procurement, though hollow-bore e-axle geometries demand seven-figure reconfiguration investments that reshape supplier tiering.
Pricing Analysis
EU CSRD embedded carbon reporting dictates the pricing tier structure across European procurement theaters, separating suppliers with validated low-carbon alloy sourcing from commodity-grade competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with METI JIS precision standards gating access to Japanese OEM contracts at the premium tier. Cost compression in the standard tier is intensifying because nickel and molybdenum input costs fluctuate with mining supply disruptions. Light commercial vehicle manufacturers in India exhibit the highest price sensitivity, while German premium transmission builders absorb alloy premiums for validated carbon footprints.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains just-in-time delivery windows for alloy steel billet shipments to Southeast Asian forging partnerships. Supply concentrates in Germany, China, and India, with the Yangtze River Delta and Pune-Aurangabad corridors serving as primary precision-forging hubs. Raw material dependencies draw from nickel-molybdenum alloy steels, carbon fiber composite feedstock, and high-purity steel billets. Single-source vulnerability around Scandinavian electric arc furnace producers for low-carbon alloy sourcing creates procurement risk. Distribution runs through consolidated transmission assembler procurement channels that favor module-level suppliers with captive bearing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-speed e-axle substitution threatens multi-gear counter shaft volumes, forcing incumbents to defend positioning through material science differentiation and hollow-bore capability acquisition.
For Market Incumbents: Compound defensive positioning by deepening backward integration into alloy steel billet production and acquiring CNC spline grinding capability ahead of India's skill scarcity widening. Schaeffler AG's bearing-shaft module integration demonstrates how assembly step reduction commands premium pricing that single-speed e-axle suppliers cannot replicate. METI JIS precision certification investment gates access to Toyota, Honda, and Nissan platforms worth defending. For New Entrants and Emerging Players: Lead with composite-reinforced hybrid shaft specifications targeting high-performance electric vehicle reduction gearboxes where rotational inertia penalties justify 30-40% mass reduction premiums. Southeast Asia commercial vehicle buildout in Indonesia and Thailand presents the most penetrable geography, with first-mover openings for precision forging partnerships ahead of domestic capacity scaling. EU CSRD compliance documentation offers a go-to-market angle for European OEM preferred supplier status. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated module suppliers with captive bearing-shaft assembly capability serving dual-clutch transmission platforms. Long-term viability over the analysis window favors forging houses with hollow-bore e-axle reconfiguration completed and validated low-carbon alloy sourcing locked. Acquisition target archetype: mid-scale German or Japanese precision forgers with METI certification and open capacity for Southeast Asian expansion. Signal to watch: China's MEE dual-carbon verification protocol timelines extending procurement lead times for export-bound producers.| Strategic Initiative | Industry Significance |
|---|---|
| Hollow-Bore E-Axle Capability Buildout | Retools forging lines for integrated electric drive module geometries demanded by OEM electrification roadmaps. |
| Backward Integration into Alloy Billet Production | Captures margin compression protection from nickel-molybdenum price volatility through melt shop control. |
| METI JIS Precision Certification Investment | Gates market access to Toyota, Honda, and Nissan transmission platform supply chains. |
| Composite-Reinforced Hybrid Shaft Development | Enables 30-40% mass reduction for high-performance electric vehicle reduction gearbox specifications. |
| EU CSRD Carbon Footprint Validation | Secures preferred supplier status with European OEMs under Green Deal scope-three reporting obligations. |
Study Parameters
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and forging plant managers provided ongoing calibration across primary interview rounds. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive component suppliers, and customs/trade flow records. Bottom-up unit economics modeling triangulated against top-down market sizing from industry association outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include transmission architecture, material specification grade, end-user procurement tier, and regional production cluster. CAGRs derived from regression analysis of historical shipment data correlated with OEM platform launch timelines and electrification spend disclosures. Forecast inputs incorporated alloy steel price indices, PLI scheme capacity buildout schedules, and e-axle penetration assumptions by vehicle class.
Underlying assumptions cover NMPA efficiency mandate enforcement, India's PLI localization timelines, and EU CSRD reporting phase-in, with deviation risk concentrated in single-speed e-axle substitution velocity and China's dual-carbon protocol stringency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Turbine Housing for Automobile Market
Powertrain
Automotive Oil Sump Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Fuel Pumps Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Tuning Box Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Clutch Pedals Market