
 Automotive Cylinder Block Market | 2026-2036
Automotive Cylinder Block Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cylinder Block Market Analysis
Foundry capacity across East Asia is broadening as regional producers scale high-pressure die casting lines for aluminum cylinder blocks. Cummins leverages its integrated engine manufacturing footprint to anchor heavy-duty diesel block supply. Yasunaga Corporation specializes in precision machining processes that differentiate its offerings for Japanese OEMs. Perkins Engine Company sustains agricultural and industrial engine block production through captive foundry operations in the United Kingdom.
An automotive cylinder block serves as the structural skeleton of an internal combustion engine, housing cylinders, coolant passages, and crankcase chambers in cast aluminum or gray iron alloys with wall thicknesses typically ranging from 3.5 to 6 millimeters. Its primary function is to maintain dimensional stability under thermal cycling and combustion pressures while supporting piston reciprocation and lubricant distribution. Aluminum cylinder blocks now lead passenger car applications due to weight-driven fuel efficiency mandates, while cast iron persists in commercial vehicle segments where thermal fatigue resistance commands premium positioning. Hybrid engine architectures represent the fastest-expanding manufacturing process category as dual-powertrain designs require modified cooling gallery geometries and reinforced main bearing bulkheads.
The EPA and California Air Resources Board enforce tailpipe emissions thresholds that directly constrain cylinder block weight and thermal management specifications in the United States. REACH regulations and the EU Green Deal compel European foundries to phase out certain binder chemistries in sand casting processes and document carbon intensity across aluminum supply chains. Stakeholders must monitor divergent regulatory timelines across major production geographies when allocating capital between cast iron consolidation and aluminum conversion investments.
Market Dynamics
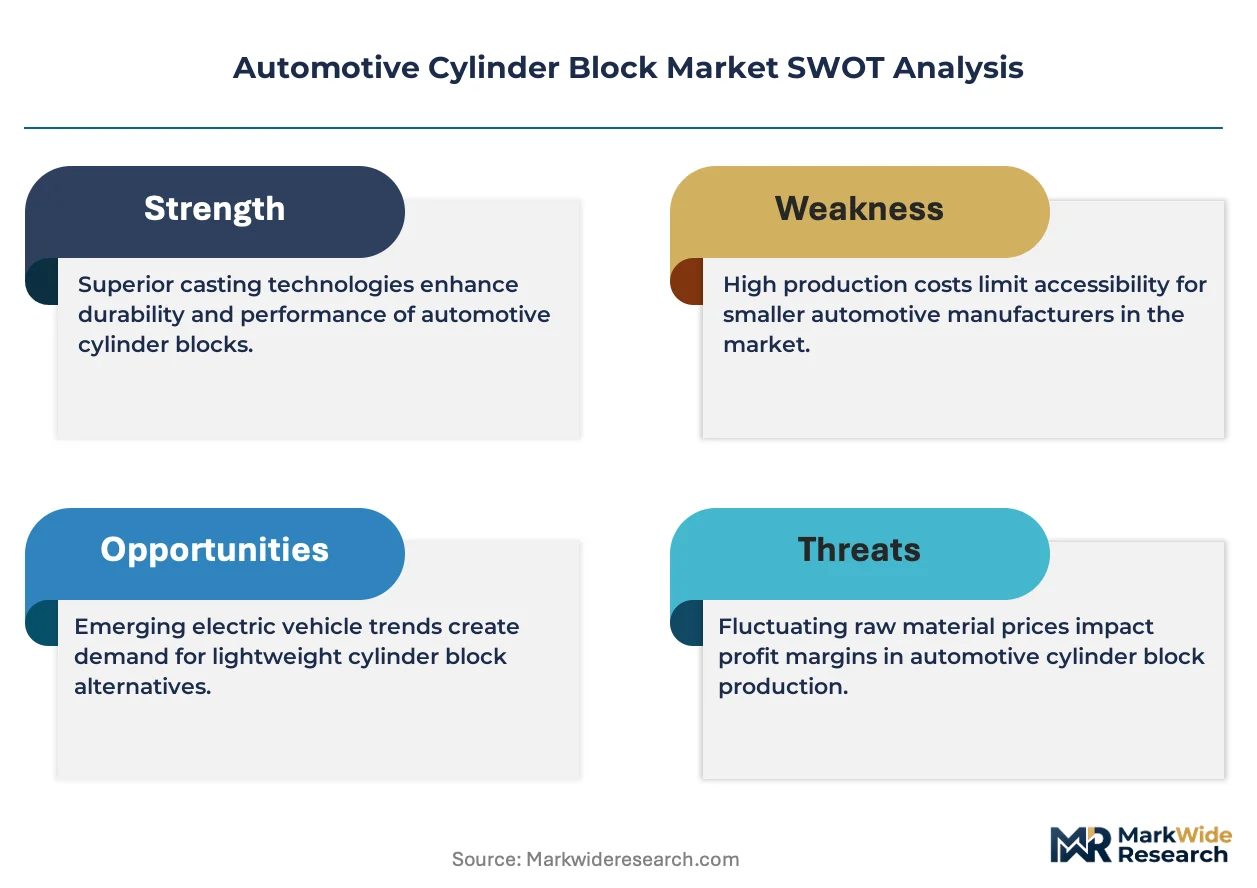
Aluminum conversion of cylinder block architectures is compressing foundry economics and forcing capital reallocation between gray iron consolidation and high-pressure die casting expansion across major production clusters.
Growth Catalysts
- EPA Tier 4 and Euro 7 emissions protocols:These standards mandate weight reduction in powertrain components, accelerating aluminum cylinder block adoption in passenger vehicle segments across the United States and European Union.
- Hybrid powertrain proliferation:Dual-architecture engines require reinforced main bearing bulkheads and modified cooling galleries, generating incremental demand for specialized cylinder block designs.
- East Asian foundry scaling:Regional producers are expanding high-pressure die casting capacity to serve both domestic OEM demand and export contracts for aluminum engine blocks.
Market Restraints
- Primary aluminum price volatility:Input cost swings for A-grade aluminum ingot strain margin structures for foundries committed to long-term OEM supply contracts.
- Gray iron foundry consolidation risk:Supply concentration in mature cast iron capacity creates vulnerability for commercial vehicle segments requiring thermal fatigue-resistant block architectures.
- Binder chemistry constraints under REACH:European foundries face forced process retooling as ECHA phases out specific sand casting binder systems, elevating compliance costs.
Strategic Opportunities
- India commercial vehicle localization:PLI scheme incentives and domestic OEM expansion create white space for aluminum cylinder block suppliers establishing captive foundry operations.
- Closed-loop aluminum recycling:Integration of secondary aluminum streams into OEM supply chains aligns with EU Green Deal carbon intensity documentation requirements.
- Industrial engine aftermarket:Agricultural and construction equipment replacement cycles generate demand for remanufactured cylinder blocks with upgraded thermal management features.
Industry Challenges
- High-pressure die casting talent scarcity:Shortages of process engineers capable of managing porosity control in thin-wall aluminum block casting constrain foundry output scaling.
- Dual-material certification complexity:OEM validation protocols for hybrid aluminum-iron engine architectures extend product qualification timelines and elevate testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cylinder Block Market |
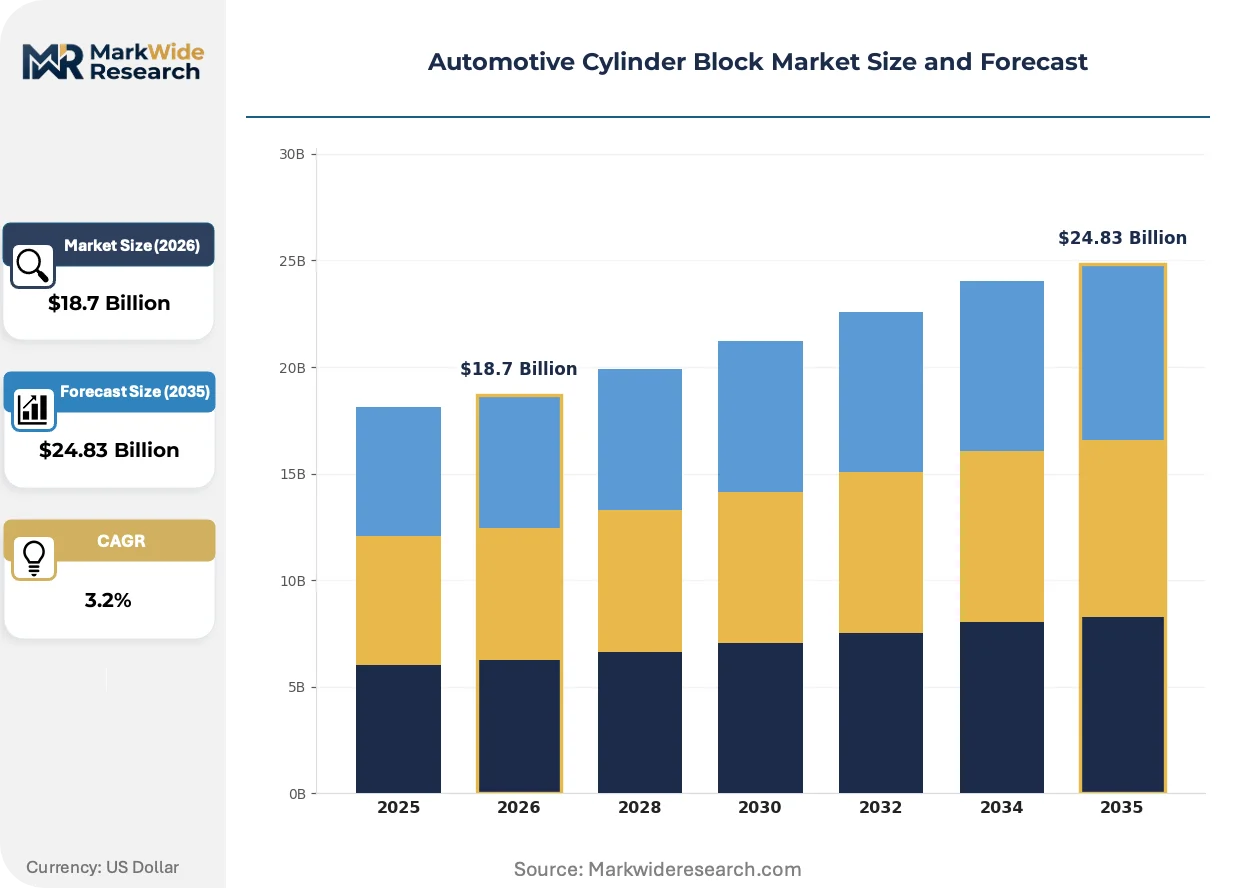
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $24.83 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Petrol, Diesel, Hybrid, Electric Material: Aluminum, Cast Iron, Composite, Steel Manufacturing Process: Die Casting, Sand Casting, Forging, Machining Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy Vehicles |
| Companies Covered | Cummins, Perkins Engine Company, Yasunaga Corporation, Fiat Chrysler Automobiles, Deutz, Cooper Corporation, Ahresty Corporation, Rico Auto Industries, SEACO Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cylinder Block Market Emerging Trajectories
Digital foundry technologies and regulatory carbon accounting are restructuring how cylinder blocks are designed, sourced, and validated across the value chain.
Artificial intelligence-driven defect detection is automating quality assurance in high-pressure die casting lines. Tier 1 foundries serving German and Japanese OEMs are deploying machine vision systems at cycle times below 12 seconds per block. This capability is automating the displacement of manual ultrasonic inspection stations and compressing post-cast processing bottlenecks.
REACH carbon footprint documentation mandates are forcing supply chain transparency investments. European foundries must now quantify and report Scope 3 aluminum sourcing emissions to retain OEM qualification status. Passenger car block suppliers with integrated secondary aluminum streams are capturing preferential sourcing status under these protocols.
Fleet operators are consolidating procurement specifications around standardized block architectures. Large North American commercial vehicle lessors are pushing OEMs toward common cylinder block platforms across multiple engine displacement classes. This concentration is most visible in heavy-duty diesel segments where maintenance standardization drives total cost of ownership calculations.
Automotive Cylinder Block Market Segmentation
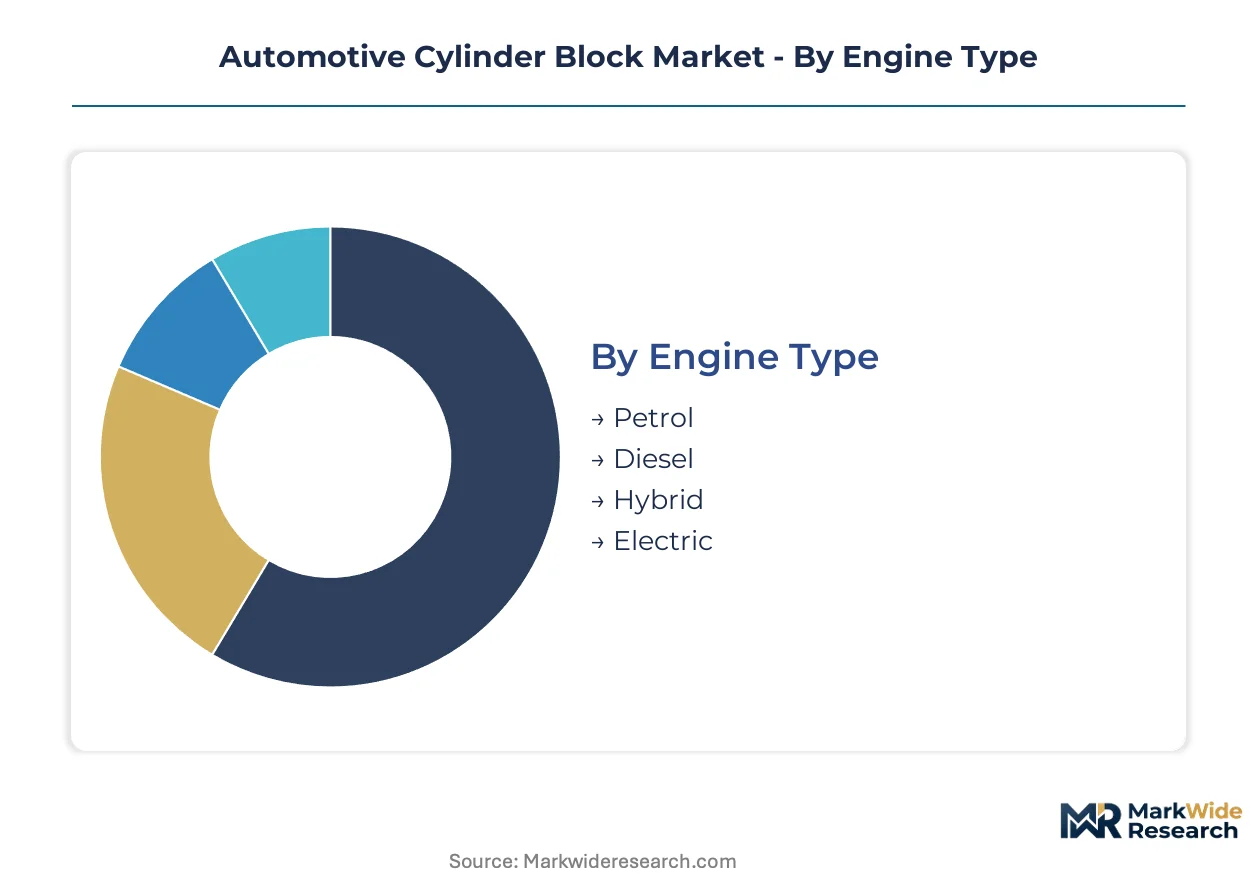
Cylinder block procurement patterns diverge sharply across powertrain architectures and vehicle duty cycles. Foundries must align casting capacity with material-specific thermal demands while OEMs prioritize weight reduction pathways that satisfy divergent emissions protocols.
Engine Type:
Upgrade cycles for internal combustion architectures are shortening as hybrid integration forces block redesigns to accommodate dual-powertrain thermal loads.
- Petrol:Aluminum thin-wall designs with 3.5-4.5mm wall thickness dominate light-duty applications. United States passenger car production anchors volume demand as EPA fuel economy standards tighten.
- Diesel:Gray iron retains structural primacy for heavy-duty compression ignition due to superior thermal fatigue resistance. Commercial vehicle fleets in Germany specify reinforced main bearing bulkheads for extended duty cycles.
- Hybrid:Modified cooling gallery geometries accommodate electric motor thermal management integration. Dual-architecture designs are climbing fastest as Japanese and Chinese OEMs expand parallel hybrid production.
- Electric:Structural battery housings and motor mounts replace traditional cylinder block functions. Demand concentrates in premium EV platforms where integrated thermal management reduces component count.
Volume placements concentrate in Petrol; the faster expansion belongs to Hybrid.
Material:
Cost tier differentiation separates commodity foundry outputs from precision-cast premium architectures serving high-performance segments.
- Aluminum:High-pressure die casting enables 25-35% weight reduction versus iron equivalents. German and Japanese OEM procurement specifications now mandate secondary aluminum content documentation under EU Green Deal protocols.
- Cast Iron:Vermicular graphite and compacted graphite variants deliver thermal fatigue resistance for commercial vehicle duty cycles. Supply concentration in mature European foundries creates vulnerability for heavy-duty diesel block sourcing.
- Composite:Polymer-metal hybrid architectures target niche motorsport and hypercar applications where extreme weight reduction justifies unit cost premiums.
- Steel:Forged billet constructions serve aftermarket performance and industrial engine remanufacturing segments requiring custom bore spacing and deck height modifications.
Cast Iron retains the largest installed base; Aluminum gains share fastest.
Manufacturing Process:
Customer type requirements split between high-volume OEM supply contracts and low-volume aftermarket remanufacturing flexibility.
- Die Casting:High-pressure aluminum die casting achieves cycle times under 90 seconds for passenger car block production. East Asian foundry scaling is displacing traditional sand casting for sub-2.0L engine architectures.
- Sand Casting:Binder chemistry flexibility accommodates complex coolant passage geometries for heavy-duty diesel blocks. REACH-mandated binder phase-outs are forcing European foundry retooling investments.
- Forging:Closed-die forging of steel billets produces grain-aligned structures for racing and industrial remanufacture applications requiring custom specifications.
- Machining:CNC finishing centers deliver precision bore honing and deck surfacing for aftermarket cylinder block remanufacturing and performance engine builds.
Die Casting commands the highest volume throughput; Sand Casting faces the steepest regulatory compliance cost escalation.
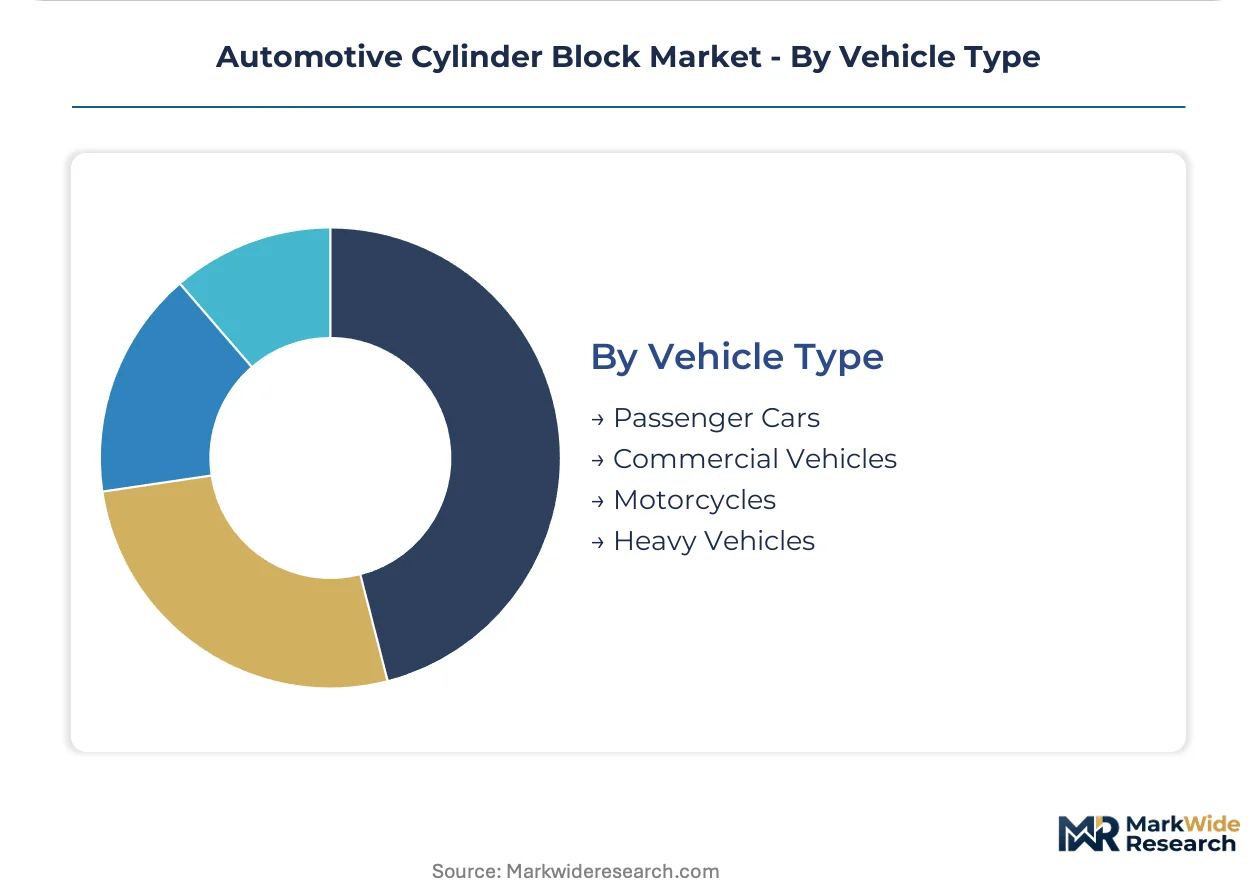
Vehicle Type:
Application-specific thermal and mechanical loading profiles dictate material selection and foundry process allocation across transportation segments.
- Passenger Cars:Aluminum high-pressure die casting dominates as OEMs pursue fleet-average CO2 reduction. China and Germany production volumes anchor global demand for sub-2.5L four-cylinder architectures.
- Commercial Vehicles:Cast iron sand casting persists for heavy-duty diesel blocks requiring 500,000+ kilometer durability. United States EPA Phase 2 greenhouse gas standards are accelerating aluminum trials in medium-duty segments.
- Motorcycles:Compact single and twin-cylinder aluminum blocks serve high-revving powertrains where power-to-weight ratio determines competitive positioning.
- Heavy Vehicles:Mining and construction equipment specifications demand thick-wall cast iron blocks with reinforced crankcase structures for severe duty cycles.
Passenger Cars generate the largest absolute demand; Commercial Vehicles show the most pronounced material transition pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminum smelting corridors in China's Shandong and Henan provinces feed casting operations across East Asia. Germany's Ruhr industrial basin retains foundry density for commercial vehicle diesel architectures. The United States, India, and Japan complete the core production geography where regulatory divergence shapes capital allocation.
United States
Commercial vehicle fleets drive steady demand for cast iron heavy-duty blocks while passenger car OEMs trial aluminum architectures. EPA Tier 4 emissions protocols constrain thermal management specifications and weight targets. Foundry investment clusters around Detroit-Warren-Dearborn and the Southeast automotive corridor where high-pressure die casting lines serve domestic hybrid production.
Germany
Precision machining demand from premium OEMs anchors specialized cylinder block supply chains. REACH regulations and the EU Green Deal compel foundries to document carbon intensity across aluminum sourcing. The Stuttgart and Munich industrial regions concentrate high-pressure die casting capacity serving both domestic production and export contracts.
China
Domestic OEM expansion and hybrid powertrain scaling generate the fastest-growing absolute demand for aluminum cylinder blocks. MIIT fuel consumption standards push weight reduction mandates across passenger vehicle segments. Yangtze River Delta foundries in Shanghai and Jiangsu province lead high-pressure die casting scaling for sub-2.0L engine architectures.
India
Commercial vehicle localization under the PLI scheme creates white space for aluminum block suppliers establishing captive foundry operations. BIS certification requirements and domestic OEM expansion reshape procurement patterns. Tamil Nadu and Maharashtra industrial corridors attract die casting investment to serve both local demand and regional export positioning.
Japan
Hybrid engine architecture specialization drives modified cooling gallery demand from domestic OEMs. METI carbon neutrality roadmaps accelerate secondary aluminum integration into supply chains. Aichi prefecture's Nagoya industrial cluster anchors precision machining and casting operations serving Japanese automaker technical specifications.
Automotive Cylinder Block Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue aluminum conversion and hybrid-specific architectures. The vendor base stratifies across integrated engine manufacturers, independent foundry specialists, and precision machining contractors. Three archetypes dominate: captive foundry operations serving single OEM ecosystems, independent Tier 1 suppliers qualifying across multiple manufacturers, and regional specialists anchoring local industrial clusters. Competitive moves concentrate on high-pressure die casting capacity expansion and closed-loop aluminum recycling integration.
Among integrated engine manufacturers, Cummins and Perkins Engine Company exemplify the captive foundry archetype where in-house casting operations align with long-durability commercial vehicle specifications. Yasunaga Corporation occupies a position within the precision machining specialist tier serving Japanese OEM technical requirements. These three entities represent distinct competitive positioning vectors: Cummins anchors heavy-duty diesel supply chains, Perkins sustains agricultural and industrial engine production, and Yasunaga differentiates through machining process specialization rather than primary casting scale.
| Leading Market Players |
|---|
| Cummins |
| Perkins Engine Company |
| Yasunaga Corporation |
| Fiat Chrysler Automobiles |
| Deutz |
| Cooper Corporation |
| Ahresty Corporation |
| Rico Auto Industries |
| SEACO Pvt Ltd |
| Others |
Supply Flow & Price Mechanics
Aluminum-grade certification divergence separates OEM-qualified foundries from commodity casting operations, with this bifurcation manifesting in both contract pricing structures and raw material sourcing configurations across Germany, China, and the United States. Premium-tier suppliers commanding secondary aluminum documentation under EU Green Deal protocols capture price premiums through integrated carbon accounting, while unbundled commodity foundries compete on spot aluminum pricing with compressed margin structures.
Pricing Analysis
Warranty and technical service bundling distinguishes OEM direct contracts from aftermarket supply arrangements, with Tier 1 foundries embedding multi-year thermal performance guarantees into long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments, with commercial vehicle fleet operators exhibiting highest price sensitivity due to total cost of ownership calculations. Price differentiation intensifies as REACH-mandated binder chemistry retooling elevates compliance costs for European sand casting operations.
Supply Chain Analysis
Containerized freight cost volatility from East Asian ports to European and North American assembly plants compresses margin structures for aluminum ingot-dependent foundries. Primary supply concentration centers on China, Germany, and the United States, with secondary aluminum streams drawing from recycled automotive scrap networks. Raw material dependencies rest on A-grade aluminum ingot, vermicular graphite iron, and specialized sand casting binders facing ECHA phase-out restrictions. Single-source vulnerability in high-pressure die casting equipment creates procurement risk for scaling foundries. Distribution runs through captive OEM supply chains and independent Tier 1 supplier networks serving aftermarket remanufacturing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive cylinder block market sits in a material-transition phase as high-pressure die casting displaces traditional sand casting for passenger vehicle architectures, with aluminum conversion now the dominant technology replacing legacy gray iron designs.
For Market Incumbents: To counter primary aluminum price volatility eroding long-term contract margins, consolidate gray iron capacity in commercial vehicle strongholds while accelerating captive secondary aluminum recycling integration. Prioritize high-pressure die casting talent acquisition in East Asian production clusters to defend technical qualification status with German and Japanese OEMs. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian commercial vehicle localization creates white-space opportunity for aluminum block suppliers establishing captive foundry operations under PLI scheme incentives. Target medium-duty diesel segments where EPA Phase 2 standards are accelerating aluminum trials, with go-to-market positioning around closed-loop recycling documentation serving EU export qualification requirements. For Investors and Strategic Acquirers: Re-rating potential sits with precision machining specialists given hybrid powertrain proliferation demanding modified cooling gallery geometries. Long-term viability across the analysis window favors foundries with integrated secondary aluminum streams and OEM-qualified high-pressure die casting capacity. Watch for inflection signals in Indian BIS certification timelines and domestic OEM procurement pattern shifts.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Die Casting Capacity Expansion | East Asian foundries scaling 90-second cycle lines capture German and Japanese OEM volume commitments. |
| Closed-Loop Aluminum Recycling Integration | Secondary aluminum stream documentation satisfies EU Green Deal Scope 3 carbon intensity reporting mandates. |
| Hybrid-Specific Cooling Gallery Redesign | Modified architectures serving dual-powertrain thermal loads command premium positioning with Japanese OEMs. |
| Captive Foundry Localization in India | PLI scheme incentives reshape procurement patterns for commercial vehicle aluminum block supply. |
| AI-Driven Defect Detection Deployment | Machine vision systems below 12-second cycle times automate displacement of manual ultrasonic inspection stations. |
Methodological Framework
Multi-period observation of foundry capacity utilization rates, OEM platform engineering timelines, and aluminum price index movements anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and high-pressure die casting process specialists. Secondary validation drew from EPA regulatory filings, MIIT fuel consumption standard updates, ECHA REACH substance restriction notifications, and vehicle production databases. Bottom-up triangulation across individual foundry output estimates converged with top-down OEM powertrain production forecasts.
Segment-weighting approaches applied differential growth assumptions across petrol, diesel, hybrid, and electric powertrain architectures, with material-specific thermal demand profiles and manufacturing process cost structures modeled throughout the forecast period. Propulsion architecture, vehicle duty cycle, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from production volume trajectories and content-per-vehicle assumptions, with foundry investment cycle timing and OEM platform refresh schedules serving as industry-specific forecast inputs.
Inputs from regulatory agency publications, trade association capacity surveys, and OEM technical specification disclosures were available through the study window; gaps in real-time foundry utilization data and proprietary alloy formulation developments introduce uncertainty bands around capacity expansion timing assumptions. Forecasts reflect documented assumptions regarding emissions protocol enforcement timelines and aluminum price stabilization trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
India Automotive Engine Oils Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Crate Engines Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Automotive Carburetor Market
Powertrain
Natural Gas Engines Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Car Drive System Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Continuous Variable Transmission Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automotive Power Steering Cooler Market