
 Spark Plugs Market | 2026-2036
Spark Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Spark Plugs Market Analytics
Iridium is rebalancing cost-performance trade-offs across the Spark Plugs Market as manufacturers reduce platinum loadings in mid-tier product lines. NGK leverages its captive iridium supply chain to sustain margin structures in premium electrode segments. Bosch competes through integrated ceramics manufacturing that anchors thermal conductivity specifications across its European production base. Denso specializes in ultra-fine wire configurations that dominate Japanese OEM fitment programs for downsized turbocharged engines.
A spark plug is an electrical device threaded into the cylinder head of an internal combustion engine, featuring a central electrode insulated by sintered alumina ceramic and a grounded shell electrode with a specified gap typically ranging from 0.6 to 1.3 millimeters, designed to ignite compressed air-fuel mixtures through high-voltage arc discharge. Iridium product types command the highest per-unit margins due to extended service life and reduced voltage demand, while copper segments retain volume leadership in price-sensitive aftermarket channels. Gasoline engine applications still generate the majority of unit demand despite electrification headwinds, though hybrid engine types represent the fastest-growing installation category as combustion cycles become more intermittent and thermally stressful.
The US EPA enforces Tier 3 emissions standards that tighten particulate and NOx thresholds, forcing manufacturers to optimize ignition timing precision and flame kernel propagation through enhanced electrode geometries. The EU F-Gas Regulation and REACH frameworks govern material composition disclosures and restrict certain heavy metal coatings in automotive components sold across member states. China's GB standards and MIIT administrative rules mandate domestic certification for spark plugs installed in vehicles produced within the country's manufacturing zones. Stakeholders must monitor how dual carbon goals in Beijing and Brussels reshape the residual value of combustion-engine component portfolios as electrification timelines compress.
Market Dynamics
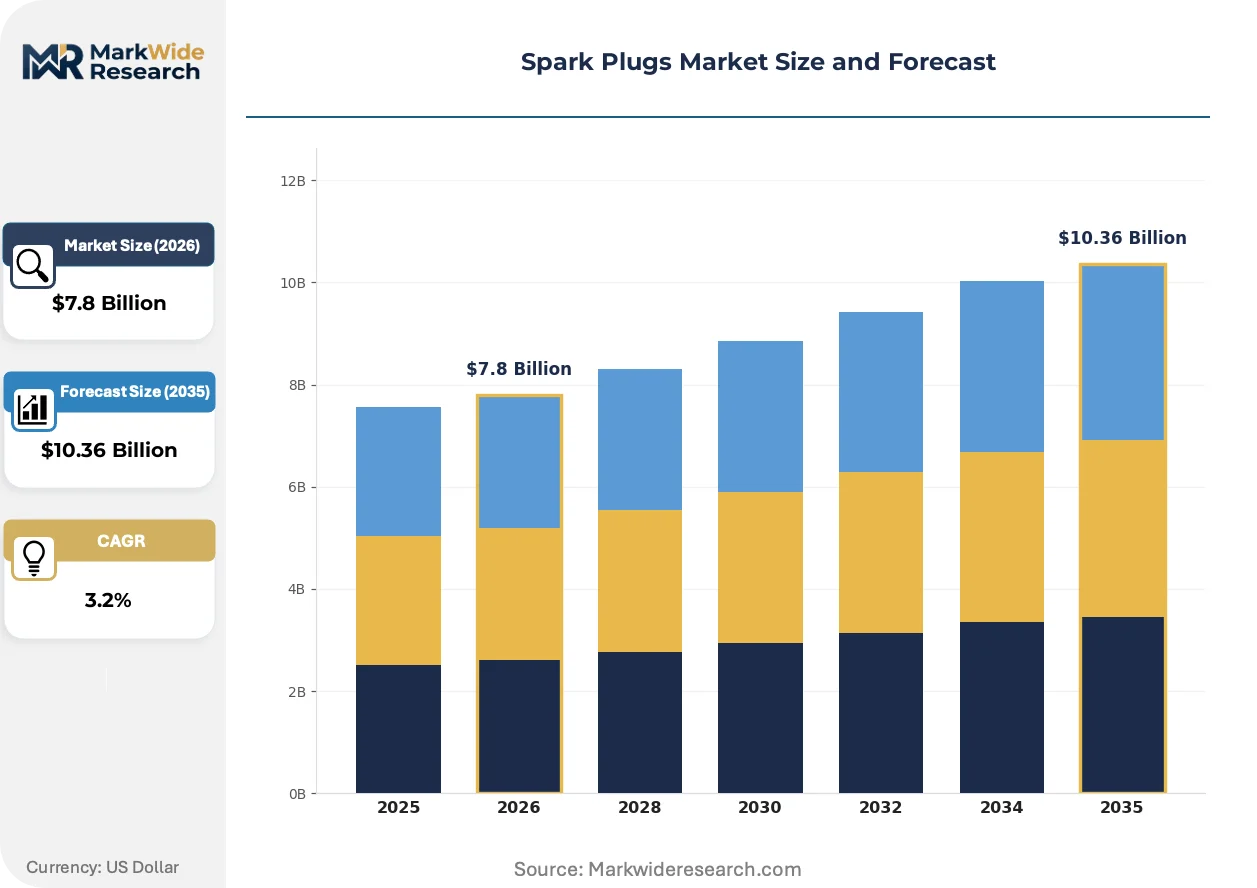
The Spark Plugs Market faces compression from electrification timelines that pull forward obsolescence risk for combustion-engine components, even as hybrid powertrains extend residual demand through more thermally stressful ignition cycles.
Growth Catalysts
- US EPA Tier 3 emissions standards:Tightened particulate thresholds force gasoline engine manufacturers to optimize flame kernel propagation through precision electrode geometries, sustaining premium spark plug specifications.
- Telematics-driven maintenance scheduling:Commercial fleet operators in North America deploy connected vehicle platforms to extend replacement intervals while maintaining reliability, creating demand for extended-life iridium configurations.
- Germany's autobahn corridor:High-speed driving patterns accelerate electrode wear rates, concentrating aftermarket demand in dense highway networks where replacement frequency exceeds continental averages.
Market Restraints
- Platinum group metal price volatility:Iridium and platinum supply concentration in South African and Russian mining operations exposes manufacturers to input cost swings that compress margin structures.
- Electrification substitution:Battery electric powertrains eliminate ignition system requirements entirely, eroding long-term addressable market scope as OEM electrification commitments harden.
- REACH material disclosure requirements:EU frameworks mandate heavy metal composition reporting that adds compliance overhead and restricts certain coating chemistries in European aftermarket channels.
Strategic Opportunities
- Hybrid engine proliferation:Intermittent combustion cycles in downsized turbocharged hybrids create thermal stress profiles that favor ultra-fine wire electrode technologies with enhanced durability specifications.
- China's domestic certification mandates:GB standards and MIIT administrative rules require in-country validation for spark plugs installed in locally produced vehicles, creating captive supply opportunities for certified manufacturers.
- Direct-to-fleet distribution platforms:Digital procurement channels bypass traditional aftermarket intermediaries, enabling margin capture through subscription-based maintenance programs for commercial vehicle operators.
Industry Challenges
- Ceramic insulator thermal shock resistance:Sintered alumina formulations must withstand increasingly aggressive combustion chamber temperatures as engine downsizing advances, requiring capital-intensive materials science capabilities.
- Multi-regulatory certification synchronization:Simultaneous compliance with US EPA Tier 3, EU REACH, and China's GB standards creates timeline friction for product launches across major automotive manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spark Plugs Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $10.36 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Iridium, Platinum, Copper Engine Type: Gasoline, Diesel, Hybrid, Electric Manufacturing Stage: OEM, Aftermarket, Custom, Re-manufactured Installation: Do-it-yourself, Professional, Fleet, Retail |
| Companies Covered | NGK, Bosch, Denso, Federal-Mogul, Champion, Autolite, Brisk, E3 Spark Plugs, ACDelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spark Plugs Market Evolving Landscape
Iridium electrode technology is converging with ceramic thermal management systems to redefine durability benchmarks across the Spark Plugs Market, while regulatory precision requirements and fleet procurement digitization reshape competitive dynamics.
Laser-welded iridium tips are converging with advanced sintered alumina ceramic insulators to extend service intervals beyond 100,000 miles. Japanese OEM fitment programs for downsized turbocharged engines prioritize these configurations to manage thermal stress from intermittent hybrid combustion cycles. This convergence is compressing replacement frequency expectations in premium vehicle segments and forcing aftermarket suppliers to match extended-life specifications.
REACH frameworks and the EU F-Gas Regulation now govern material composition disclosures and restrict certain heavy metal coatings in automotive components sold across member states. Manufacturers must reformulate electrode platings and ceramic dopants to maintain European market access. Germany's KBA type-approval processes have become the de facto gatekeeper for EU-wide spark plug certification, centralizing compliance investment decisions.
Fleet procurement teams now unbundle after-sales service from component supply, negotiating direct maintenance contracts that specify performance outcomes rather than part specifications. Traditional distributor networks in North America face disintermediation as telematics platforms enable predictive replacement scheduling. This pattern is most visible among commercial vehicle operators in the US Midwest corridor, where large fleet concentrations drive volume consolidation toward integrated service providers.
Spark Plugs Market Segmentation
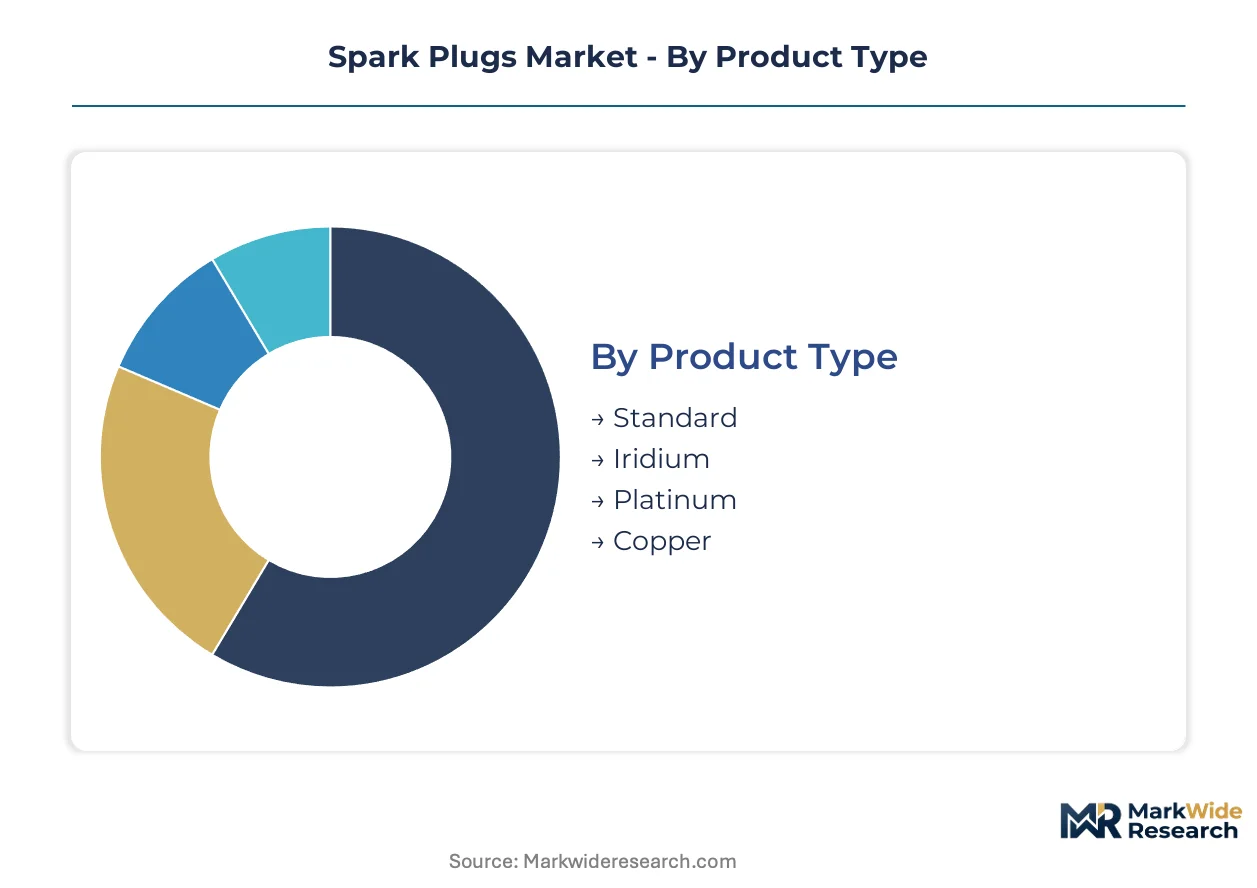
Spark plug segmentation reveals how replacement cycles, thermal stress profiles, and procurement channels fragment demand across distinct technical and commercial categories. Upgrade decisions hinge on electrode material durability versus unit economics, while installation preferences diverge sharply between consumer convenience and fleet operational efficiency.
Product Type:
Replacement cycles vary dramatically by electrode composition, with extended-life materials commanding premium positioning despite higher upfront costs.
- Iridium:Laser-welded fine-wire tips deliver 100,000-mile service intervals through exceptional wear resistance and reduced voltage demand. Demand concentrates in Japanese OEM fitment programs for downsized turbocharged engines where thermal stress from intermittent hybrid combustion cycles necessitates durability specifications.
- Copper:Solid nickel alloy center electrodes provide cost-optimized ignition performance with shorter replacement horizons of 20,000-30,000 miles. Volume leadership persists in price-sensitive aftermarket channels across Germany's autobahn corridor where high-speed driving accelerates wear and favors frequent, low-unit-cost replacement.
- Platinum:Mid-tier positioning balances extended life against material cost through reduced platinum loadings in contemporary designs.
- Standard:Conventional nickel-chromium configurations serve legacy vehicle populations and emerging market cost constraints.
Volume placements concentrate in Copper; the faster expansion belongs to Iridium.
Engine Type:
Combustion architecture determines ignition system requirements, with electrification trajectories reshaping addressable scope across powertrain categories.
- Gasoline:Spark-ignited engines retain majority unit demand despite electrification headwinds, with port and direct injection configurations sustaining baseline spark plug requirements across passenger and light commercial vehicle fleets.
- Hybrid:Downsized turbocharged engines operating intermittent combustion cycles generate thermal stress profiles that favor ultra-fine wire electrode technologies. US EPA Tier 3 emissions standards tighten allowable particulate thresholds, forcing manufacturers to optimize ignition timing precision through enhanced electrode geometries in this fastest-expanding installation category.
- Diesel:Compression-ignition architecture eliminates spark-based ignition entirely, excluding this segment from spark plug applicability.
- Electric:Battery electric powertrains remove ignition system requirements completely, representing structural demand erosion as OEM electrification commitments harden.
Gasoline maintains volume dominance; hybrid configurations are climbing the fastest as electrification timelines compress.
Manufacturing Stage:
Channel structure separates captive OEM supply from fragmented aftermarket distribution, with certification requirements creating divergent competitive barriers.
- OEM:Factory-installed specifications demand synchronized compliance with US EPA Tier 3, EU REACH, and China's GB standards, creating timeline friction for product launches across major automotive manufacturing zones.
- Aftermarket:Replacement demand concentrates in Germany's dense autobahn corridor where high-speed driving accelerates electrode wear rates beyond continental averages.
- Custom:Specialized applications serve performance and racing segments with non-standard heat range specifications.
- Re-manufactured:Refurbished core recovery programs target cost-sensitive fleet operators in North America extending replacement intervals through telematics-driven maintenance scheduling.
Aftermarket channels capture volume leadership; OEM specifications are gaining share fastest through extended-life iridium configurations.
Installation:
Procurement modality reflects customer sophistication, from individual consumer convenience to enterprise-scale operational optimization.
- Fleet:Commercial vehicle operators in the US Midwest corridor deploy telematics platforms for predictive replacement scheduling, unbundling after-sales service from component supply through direct maintenance contracts specifying performance outcomes.
- Professional:Independent repair shops and dealership service bays handle complex turbocharged and hybrid engine configurations requiring specialized tooling.
- Do-it-yourself:Consumer self-installation persists for accessible engine bays and standard copper plug applications.
- Retail:Mass merchandisers and auto parts chains serve emergency replacement needs and planned maintenance purchases.
Professional installation handles volume concentration; fleet direct procurement is expanding most quickly as digital platforms disintermediate traditional distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturing zones and high-speed highway corridors concentrate spark plug demand across distinct national markets, with regulatory emissions frameworks and fleet telematics adoption reshaping replacement patterns.
United States
Commercial fleet operators in the Midwest corridor deploy predictive maintenance platforms to extend replacement intervals, sustaining demand for iridium configurations. EPA Tier 3 emissions standards tighten particulate thresholds for gasoline engines, forcing ignition timing optimization. Detroit's automotive manufacturing cluster anchors OEM specification development for downsized turbocharged powertrains.
Germany
High-speed autobahn driving accelerates electrode wear rates, concentrating aftermarket demand in dense highway networks where replacement frequency exceeds continental averages. KBA type-approval processes serve as the de facto gatekeeper for EU-wide spark plug certification. Stuttgart's automotive engineering base drives premium electrode geometry specifications for European OEM fitment programs.
China
Domestic vehicle production mandates under MIIT administrative rules require in-country certification for spark plugs installed in locally manufactured vehicles. GB standards govern material composition and performance testing protocols. Yangtze River Delta manufacturing zones host captive supply relationships between certified producers and joint-venture assembly plants.
Japan
Downsized turbocharged hybrid engines generate thermal stress profiles favoring ultra-fine wire electrode technologies with enhanced durability specifications. METI industrial policy supports advanced ceramics research for thermal management applications. Nagoya's automotive component cluster specializes in precision electrode welding for OEM fitment programs.
South Korea
Hyundai-Kia manufacturing networks drive specification requirements for extended-life spark plugs in compact SUV and sedan platforms. MFDS material safety frameworks govern heavy metal disclosure in automotive components. Busan-Ulsan industrial corridor hosts integrated ceramics production serving regional OEM supply chains.
Spark Plugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium electrode technology concentrating among Japanese and German incumbents while price-sensitive aftermarket channels fragment across regional suppliers. Three archetypes dominate: integrated ceramics producers controlling thermal conductivity specifications, captive noble metal processors securing iridium supply chains, and fleet-focused distributors building direct procurement platforms. Competitive moves center on backward integration into sintered alumina manufacturing and strategic partnerships with telematics providers for predictive maintenance integration.
Among Japanese specialists, NGK and Denso exemplify the premium electrode archetype through precision wire configurations and extended-life specifications. Bosch anchors the integrated ceramics tier with European manufacturing base advantages. These three occupy positions across OEM fitment and certified aftermarket channels, with geographic origin and corporate structure reflecting distinct strategic postures toward regulatory compliance and thermal management technology.
| Leading Market Players |
|---|
| NGK |
| Bosch |
| Denso |
| Federal-Mogul |
| Champion |
| Autolite |
| Brisk |
| E3 Spark Plugs |
| ACDelco |
| Others |
Value Network & Pricing Analysis
EPA Tier 3 emissions standards gate qualified supply and premium-tier pricing access by mandating precision electrode geometries that only certified manufacturers can deliver, compressing margins for non-compliant producers while extending replacement intervals for fleet operators who absorb upfront cost premiums.
Pricing Analysis
Short lead-time premiums distinguish contract pricing from spot inventory discounts across the Spark Plugs Market. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume scale, with iridium configurations commanding sustained premiums due to extended service life specifications. Price differentiation reflects thermal conductivity testing protocols and KBA type-approval status. Cost compression in copper segments intensifies because of platinum group metal volatility, while fleet procurement teams demonstrate lowest price sensitivity through outcome-based maintenance contracts.
Supply Chain Analysis
Reverse-logistics flows for remanufactured core recovery programs anchor aftermarket cost structures in North American fleet channels. Supply concentrates in Japan, Germany, and China, with sintered alumina ceramic production drawing from bauxite refining operations in Australia and Guinea. Iridium and platinum sourcing rests on South African and Russian mining concentration, creating single-source vulnerability for noble metal processors. Distribution runs through traditional aftermarket intermediaries facing disintermediation from telematics-enabled direct procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
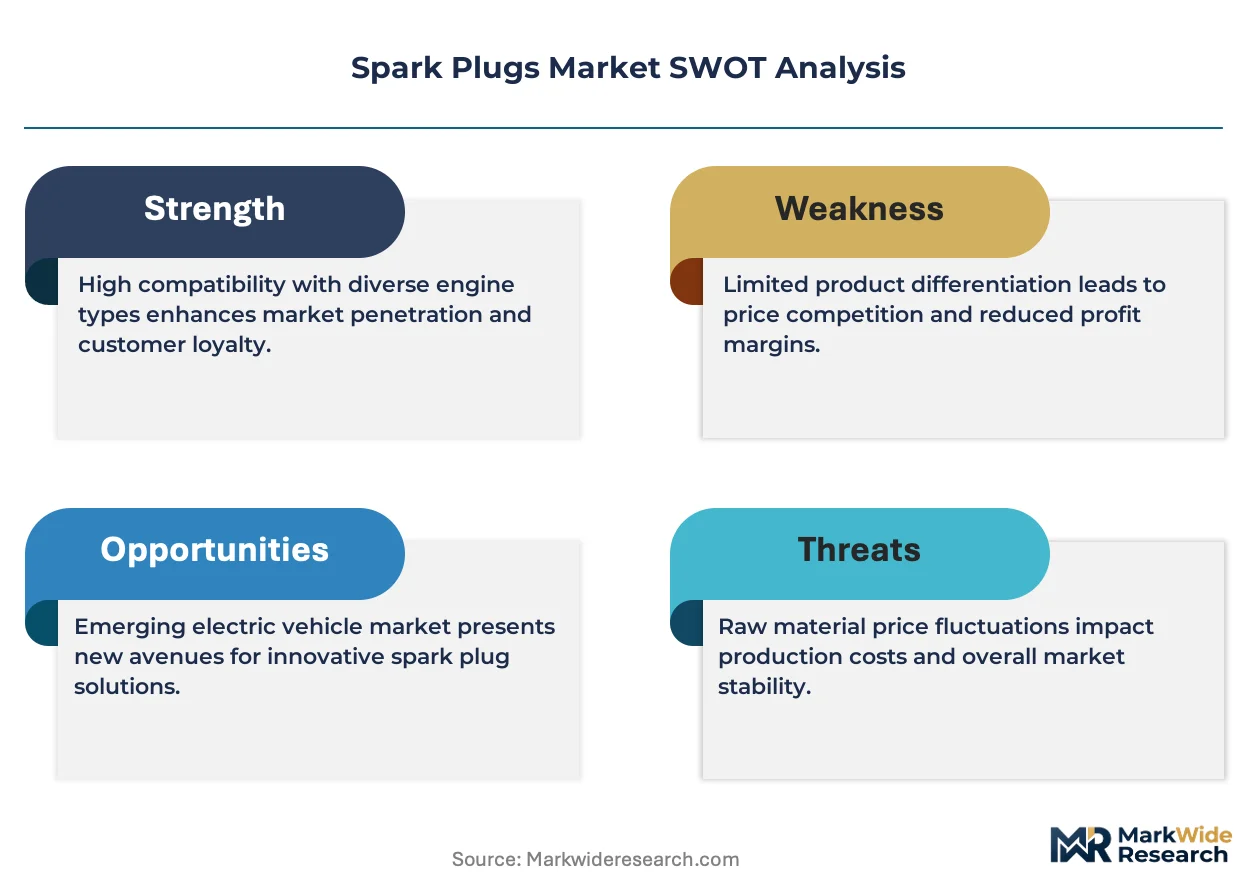
This market reads as a cost-of-compliance story where REACH material disclosure requirements and EPA Tier 3 certification create barrier-to-entry moats for players with capital-intensive testing infrastructure.
For Market Incumbents: To counter electrification substitution risk, NGK and Denso should deepen backward integration into captive iridium supply chains while expanding ceramic insulator capacity in Nagoya manufacturing zones. Bosch must defend European market access through synchronized REACH and KBA certification investments that smaller competitors cannot replicate. For New Entrants and Emerging Players: The price-point gap between laser-welded iridium OEM specifications and standard nickel-chromium aftermarket units creates white-space opportunity in China's domestic certification channel. Target re-manufactured core recovery programs for Midwest fleet operators through telematics-integrated service platforms that bypass traditional distributor markups. For Investors and Strategic Acquirers: Hybrid engine proliferation announcements from Detroit and Stuttgart OEMs are the leading indicator that residual combustion component demand will concentrate in thermal-stress-optimized electrode technologies. Acquisition targets should display integrated ceramics manufacturing capabilities and MIIT certification status for Yangtze River Delta supply relationships. Practitioners should monitor EPA enforcement actions and EU F-Gas Regulation amendments for compliance cost inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Insulator Capacity Expansion | Captive sintered alumina production secures thermal conductivity specifications against Bosch's European manufacturing base. |
| Iridium Supply Chain Integration | Backward control over South African and Russian noble metal sourcing buffers margin structures from commodity volatility. |
| Telematics Platform Partnership | Predictive maintenance integration with Fleet telematics providers disintermediates traditional aftermarket distributor networks. |
| MIIT Certification Investment | Domestic validation under China's GB standards creates captive supply relationships with joint-venture assembly plants. |
| REACH Compliance Reformulation | Heavy metal coating substitutions maintain European market access under ECHA disclosure mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Spark Plugs Market analysis. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership service heads combined with EPA enforcement databases, ECHA REACH registrations, MIIT administrative filings, and vehicle production statistics from IHS Markit. Bottom-up unit demand modeling and top-down value triangulation validated segmentation outputs.
Granularity-level modeling operated at electrode material, engine architecture, and manufacturing stage dimensions across the projection horizon. CAGRs derived from replacement cycle analysis by vehicle class, propulsion architecture, and content per vehicle specifications. Forecast inputs incorporated telematics adoption curves in North American fleet channels and hybrid engine penetration rates in Japanese OEM fitment programs.
Inputs from EPA, ECHA, and MIIT regulatory databases were available through the study window; gaps in real-time platinum group metal pricing introduce uncertainty bands around margin projections. Forecasts reflect assumptions about electrification timeline compression and emissions standard enforcement intensity. Practitioners should monitor hybrid powertrain announcement volumes and REACH amendment proceedings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Transmission Repair Market
Powertrain
Engine Rocker Arm Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Europe Turbocharger Market
Powertrain
Automotive Crankshaft Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Small Gas Engine Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Transmission Fluids Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Oil Sump Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
Motor Vehicle Carburetors Market