
 Electrically Powered Hydraulic Steering Market | 2026-2036
Electrically Powered Hydraulic Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Electrically Powered Hydraulic Steering Market Foresight
The OEM supply channel is narrowing as vehicle assemblers consolidate preferred supplier lists. JTEKT Corporation leverages its integrated steering control unit and actuator manufacturing to sustain long-term contracts with Japanese OEMs. Nexteer Automotive anchors North American production through captive engineering centers in Michigan and Mexico. ZF Friedrichshafen AG competes across European and Asian markets with modular electro-hydraulic platforms that span passenger and commercial applications.
Electrically powered hydraulic steering combines an electric motor-driven hydraulic pump with electronic control units to provide variable steering assistance, typically operating at system pressures between 80 and 140 bar depending on vehicle class. The technology preserves hydraulic road feel while enabling on-demand pump operation that reduces parasitic engine load versus traditional constant-flow systems. Steering control units and ECUs command the strongest margin pools due to firmware complexity and calibration IP, while actuator demand tracks most closely with heavy machinery and commercial vehicle production cycles. Electro-hydraulic technology leads installed base volumes, though smart steering architectures with integrated lane-keeping and automated parking functions represent the fastest-expanding development frontier.
NHTSA fuel economy standards and EPA emissions frameworks in the United States compel OEMs to adopt on-demand hydraulic steering as a compliance pathway, while KBA type-approval requirements in Germany enforce functional safety validation under UN ECE regulations. The EU Green Deal and embedded carbon reporting through CSRD extend compliance burdens upstream to steering component suppliers. Stakeholders must monitor how automated driving capability tiers redefine the boundary between electrically powered hydraulic and fully steer-by-wire architectures.
Market Dynamics
Commercial vehicle electrification mandates and EPA fuel economy enforcement are compressing the transition window from constant-flow hydraulic systems to on-demand electro-hydraulic architectures, forcing simultaneous investments in steering control firmware and pump motor efficiency.
Growth Catalysts
- EPA Phase 3 Standards:The EPA's tightened fuel economy requirements for medium and heavy-duty trucks compel fleet operators to retrofit existing vehicles with electrically powered hydraulic steering to reduce parasitic engine load during highway operation.
- Commercial Vehicle Fleets:North American logistics operators expanding Class 6-8 truck procurement are specifying electro-hydraulic systems as standard equipment to achieve measurable fuel savings across high-mileage duty cycles.
- Modular Pump Integration:Advances in compact electric motor-hydraulic pump packages enable retrofit compatibility with legacy steering gearboxes, extending addressable vehicle populations beyond new production.
Market Restraints
- Rare Earth Magnet Costs:Neodymium and dysprosium price volatility in electric motor supply chains creates margin compression for pump manufacturers without long-term offtake agreements.
- German Supply Concentration:KBA certification infrastructure and tier-one actuator production cluster disproportionately in Baden-Württemberg, exposing the market to single-region logistics disruptions.
- Fully Electric Steer-by-Wire:Elimination of hydraulic fluid entirely in next-generation automated vehicles threatens electro-hydraulic's intermediate position in the technology roadmap.
Strategic Opportunities
- Indian Commercial Vehicle Market:Bharat Stage VI emission enforcement and expanding domestic truck manufacturing create first-mover potential for electro-hydraulic system localization.
- Agricultural Autonomy:Precision farming platforms requiring variable steering assistance across field and transport modes favor electro-hydraulic's tunable road feel over fully electric alternatives.
- CSRD Carbon Reporting:The EU's Corporate Sustainability Reporting Directive rewards suppliers with embedded carbon transparency, favoring electro-hydraulic producers with lifecycle-certified production facilities.
Industry Challenges
- Functional Safety Certification:UN ECE R79 validation timelines extend 18-24 months for new steering control unit firmware, delaying platform launches and freezing engineering resources.
- Legacy System Integration:Compatibility engineering for 15-20 year-old commercial vehicle chassis architectures consumes disproportionate validation budgets relative to new platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrically Powered Hydraulic Steering Market |
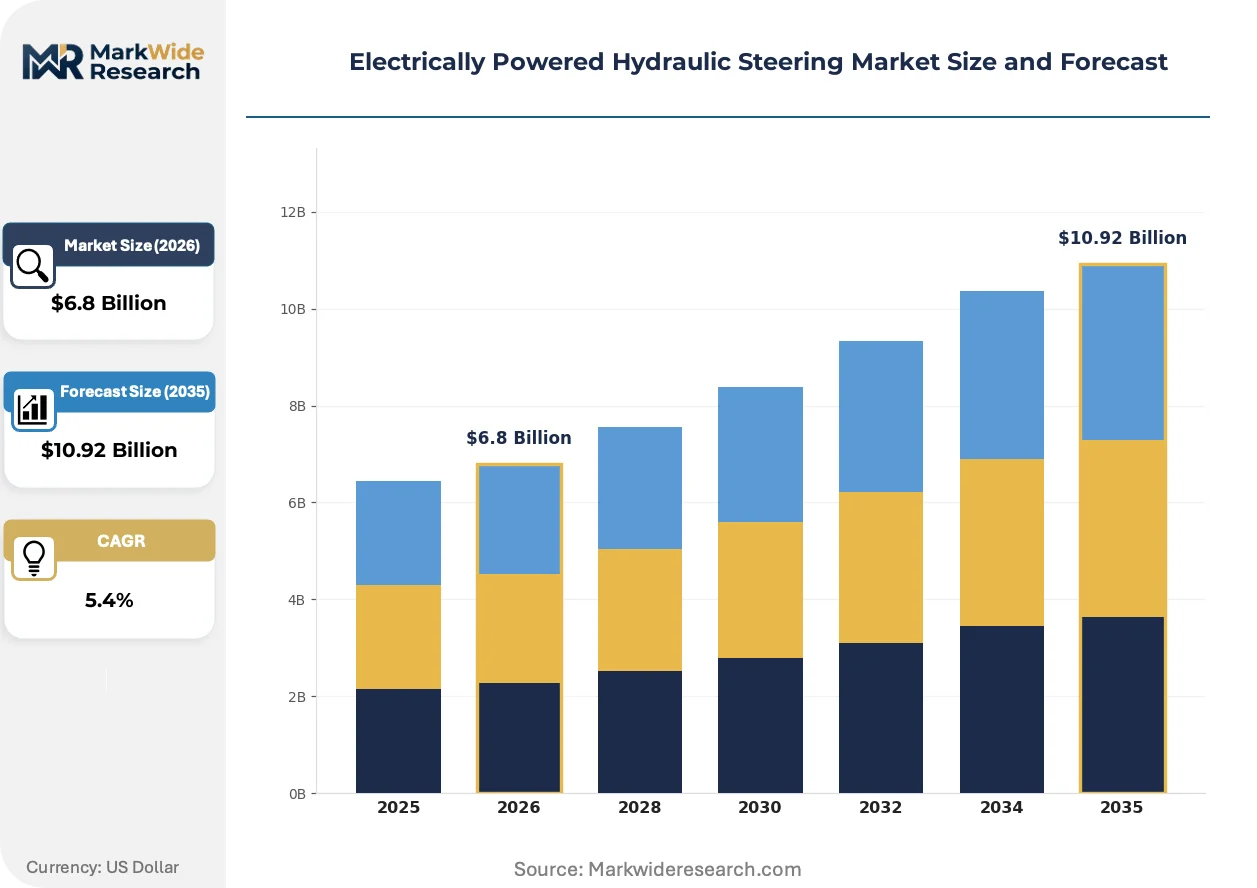
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steering Control Unit, Hydraulic Pump, Actuator, ECU End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electro-Hydraulic, Electric Assist, Variable Ratio, Smart Steering Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery |
| Companies Covered | JTEKT Corporation, Nexteer Automotive, ZF Friedrichshafen AG, NSK Ltd., Robert Bosch GmbH, Hyundai Mobis, Mitsubishi Electric, Delphi Technologies, GKN Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrically Powered Hydraulic Steering Market Shifts & Advancements
Intelligent steering architectures are converging sensor fusion, predictive load algorithms, and over-the-air calibration to transform electro-hydraulic systems from passive assistance mechanisms into active chassis control nodes.
Variable displacement pump technology with integrated torque-angle sensors is rendering obsolete fixed-displacement gear pumps in heavy commercial applications. Fleet operators running regional distribution routes are adopting these systems at replacement-cycle pace to capture 4-6% fuel economy gains. The technology is rendering obsolete the traditional separation between hydraulic power steering and electronic stability control modules.
CSRD disclosure requirements and EU Green Deal carbon border adjustments are forcing steering component suppliers to document embedded emissions from raw material extraction through end-of-life recycling. Industrial consequence includes accelerated supplier consolidation around facilities with certified renewable energy supply. German and Czech manufacturing clusters are most affected, with producers investing in hydrogen-fired heat treatment and closed-loop aluminum die-casting to maintain OEM qualification status.
Service-contract unbundling is disrupting traditional aftermarket parts distribution for steering systems. Independent repair facilities now procure remanufactured electro-hydraulic pumps through direct manufacturer portals rather than regional distributors. This pattern is most visible in the US Great Lakes automotive corridor, where independent truck service chains negotiate direct pump exchange programs with JTEKT and Nexteer bypassing traditional jobber networks.
Electrically Powered Hydraulic Steering Market Segmentation
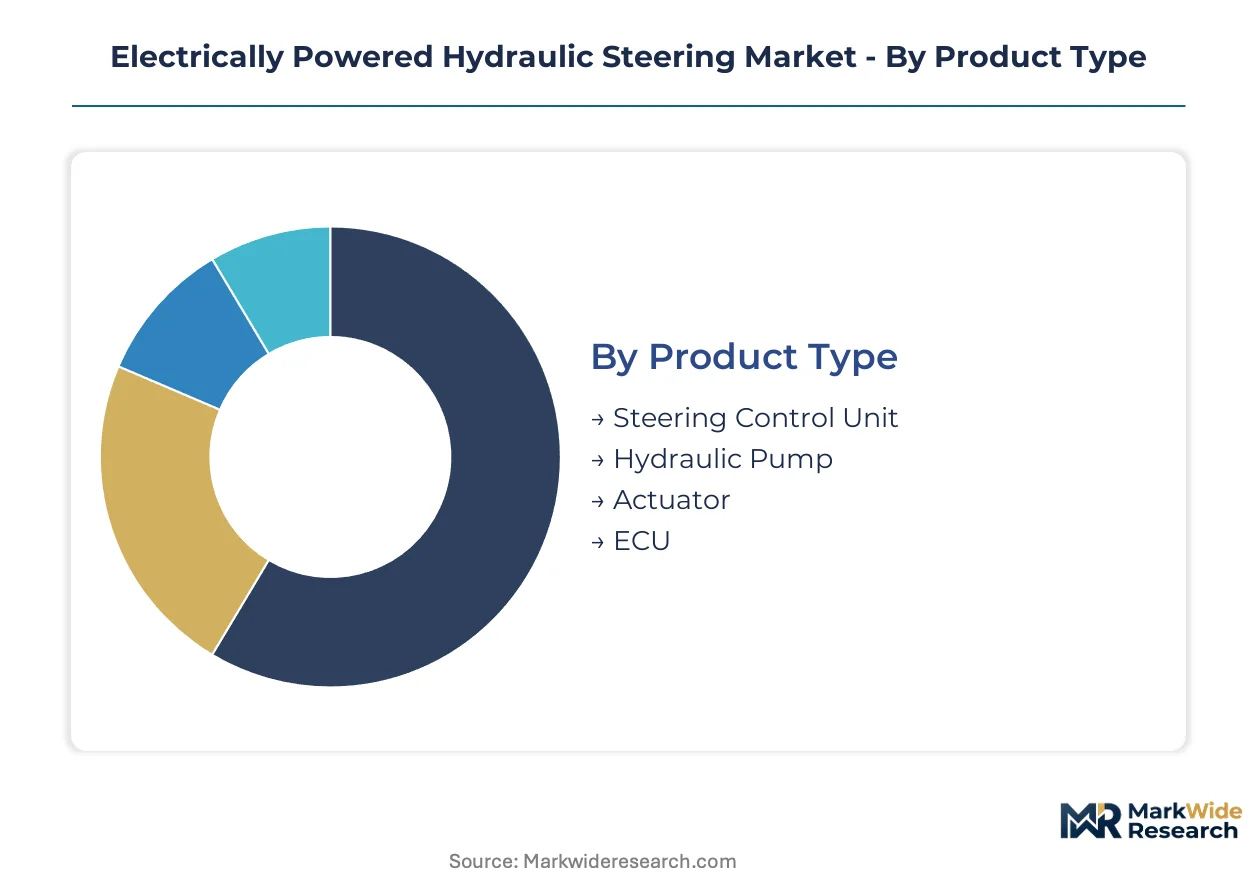
Segmentation in electrically powered hydraulic steering reveals how technology position, supply chain role, and vehicle application intersect to determine margin structure and competitive intensity. Understanding these boundaries clarifies where firmware IP, hardware commoditization, and regulatory compliance create divergent investment requirements.
Product Type:
The use-case spectrum spans from software-defined steering control to commodity hydraulic hardware, with margin pools concentrating where electronic and mechanical domains integrate.
- Steering Control Unit:Embedded firmware platforms executing torque-angle algorithms and diagnostic protocols command premium positioning through calibration IP. German OEMs source these units from captive engineering centers in Baden-Württemberg to satisfy KBA functional safety validation.
- ECU:Electronic control units process sensor fusion inputs for predictive load management and over-the-air parameter updates. EPA Phase 3 compliance deadlines in the United States accelerate procurement of ECU-integrated pump packages for medium-duty retrofits.
- Hydraulic Pump:Electric motor-driven pump assemblies deliver variable flow on demand, reducing parasitic losses versus constant-flow architectures.
- Actuator:Linear and rotary actuators translate hydraulic pressure into mechanical steering force, with demand tracking commercial vehicle production cycles.
Established volume favors Hydraulic Pump; emerging adoption favors Steering Control Unit.
End User:
Supply chain position determines specification authority and contract duration, with vehicle assemblers consolidating preferred supplier lists while aftermarket channels fragment.
- OEMs:Original equipment manufacturers specify complete steering systems and validate firmware through 18-24 month UN ECE R79 certification timelines. Japanese OEMs maintain long-term contracts with integrated control unit suppliers to secure platform continuity.
- Tier-1 Suppliers:System integrators combine pumps, actuators, and electronics into modular packages for multiple OEM programs. North American tier-1 operations anchor production in Michigan and Mexico to serve regional truck assembly.
- Vehicle Assemblers:Final assembly plants procure pre-validated steering modules for line-fit installation, prioritizing logistics synchronization over component sourcing.
- Aftermarket Providers:Independent repair facilities and remanufacturers exchange failed pumps through direct manufacturer portals, bypassing traditional distributor networks in the US Great Lakes corridor.
Contract stability concentrates with Tier-1 Suppliers; margin compression threatens Aftermarket Providers.
Technology:
Architecture maturity ranges from proven electro-hydraulic platforms to experimental steer-by-wire alternatives, with development investment weighted toward sensor integration and predictive algorithms.
- Electro-Hydraulic:Combines electric motor-driven pumps with hydraulic actuation to preserve road feel while enabling on-demand operation. This architecture leads installed base volumes across passenger and commercial applications.
- Smart Steering:Sensor-fusion platforms integrating lane-keeping, automated parking, and chassis control functions are climbing the fastest as OEMs differentiate through automated driving capability tiers.
- Variable Ratio:Speed-sensitive steering racks adjust mechanical advantage to reduce driver effort at low speeds while maintaining highway stability.
- Electric Assist:Motor-on-rack configurations eliminate hydraulic fluid entirely, threatening intermediate electro-hydraulic positioning in next-generation vehicle programs.
Deployment scale favors Electro-Hydraulic; development priority favors Smart Steering.
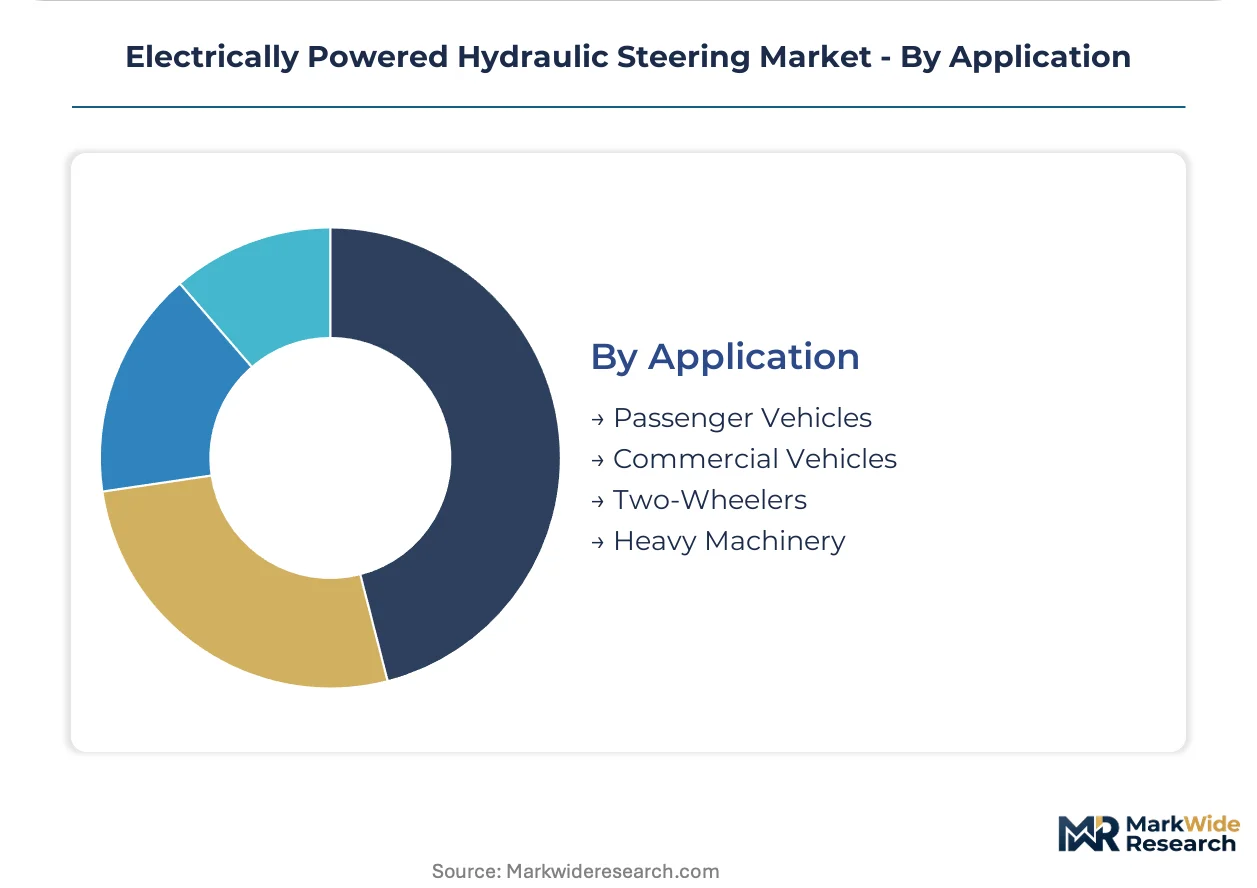
Application:
Vehicle duty cycle determines hydraulic pressure requirements, pump sizing, and control firmware complexity, with commercial applications demanding higher system pressures and longer validation horizons.
- Commercial Vehicles:Class 6-8 trucks and regional distribution fleets specify 80-140 bar systems to manage loaded axle weights, with fuel economy gains of 4-6% driving retrofit demand under EPA enforcement.
- Heavy Machinery:Construction and agricultural equipment requires tunable steering assistance across field and transport modes, favoring electro-hydraulic's variable displacement over fully electric alternatives.
- Passenger Vehicles:Light-duty cars and SUVs adopt compact electro-hydraulic packages for weight reduction and packaging efficiency in front-wheel-drive architectures.
- Two-Wheelers:Motorcycles and scooters represent limited addressable volume due to weight constraints and cost sensitivity in emerging markets.
Revenue concentration sits with Commercial Vehicles; technology migration pressure weighs on Two-Wheelers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing through KBA certification infrastructure while India offers localization arbitrage for cost-sensitive commercial vehicle programs. This asymmetry reshapes where OEMs source steering control units versus hydraulic pump assemblies.
United States
EPA Phase 3 fuel economy enforcement drives fleet retrofits of Class 6-8 trucks with on-demand electro-hydraulic systems. NHTSA safety validation protocols govern steering control firmware deployment. Michigan anchors North American engineering with captive design centers serving Detroit-based OEMs and Mexican assembly operations.
Germany
KBA type-approval requirements under UN ECE R79 enforce 18-24 month functional safety validation timelines for steering control units. EU Green Deal carbon border adjustments pressure suppliers to document embedded emissions. Baden-Württemberg clusters tier-one actuator production with hydrogen-fired heat treatment investments maintaining OEM qualification status.
Japan
Long-term supply contracts with integrated control unit manufacturers secure platform continuity for domestic OEMs. METI industrial standards govern electric motor efficiency benchmarks in pump assemblies. Kanto region engineering centers concentrate firmware calibration IP for export programs.
India
Bharat Stage VI emission enforcement accelerates electro-hydraulic adoption in expanding domestic truck manufacturing. Ministry of Road Transport and Highways safety regulations align with UN ECE frameworks. Maharashtra and Gujarat host first-mover localization facilities targeting cost-sensitive commercial vehicle specifications.
China
Dual carbon goals and MIIT new energy vehicle mandates compress adoption timelines for efficiency-focused steering architectures. GB standards govern electromagnetic compatibility in electronic control units. Yangtze River Delta manufacturing bases scale variable displacement pump production for domestic OEMs and export markets.
Electrically Powered Hydraulic Steering Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in pump and actuator manufacturing. The vendor base organizes around three archetypes: Japanese conglomerates with integrated steering divisions, German automotive suppliers with modular electro-hydraulic platforms, and North American tier-one operations anchored to regional truck assembly. Consolidation pressures favor long-term OEM contracts over spot-market component sales. Dominant competitive moves include captive engineering center investments and direct aftermarket portal strategies bypassing traditional distribution.
Among Japanese conglomerates, JTEKT Corporation and Mitsubishi Electric occupy positions emphasizing integrated control unit and actuator manufacturing. German supplier ZF Friedrichshafen AG exemplifies the modular platform archetype spanning passenger and commercial applications. These three anchors represent divergent geographic and structural strategies within the competitive set.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive |
| ZF Friedrichshafen AG |
| NSK Ltd. |
| Robert Bosch GmbH |
| Hyundai Mobis |
| Mitsubishi Electric |
| Delphi Technologies |
| GKN Automotive |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's tier-one actuator production cluster concentrates firmware calibration IP and KBA-certified heat treatment capacity, anchoring premium margin pools in steering control units while hydraulic pump assemblies face commodity pressure from Chinese and Indian manufacturing scale.
Pricing Analysis
Configured-to-order steering control units carrying UN ECE R79 certification command 40-60% premiums over standard hydraulic pump SKUs. Price differentiation rests on firmware complexity and validation timeline — Japanese OEMs pay premiums for integrated actuator-ECU packages with 18-24 month lock-in periods, while aftermarket channels squeeze pump margins through direct portal procurement. Cost compression in commodity pump tiers is intensifying because rare earth magnet volatility and Chinese oversupply of variable displacement architectures erode manufacturer leverage. Fleet operators running Class 6-8 retrofits exhibit highest price sensitivity, whereas German OEM captive engineering centers show lowest sensitivity due to platform continuity requirements.
Supply Chain Analysis
Export-control restrictions on high-performance neodymium-dysprosium magnet grades limit electric motor flows from Chinese processors to Western pump manufacturers, forcing supply chain reconfiguration. Production gravity centers on Germany for steering control units, China for compact motor-pump packages, and Mexico for North American truck assembly feedstock. The electro-hydraulic supply chain draws from rare earth concentrate dependencies in Myanmar and Australia, semiconductor-grade ECU components from Taiwan and South Korea, and precision-machined aluminum castings from Czech and Polish facilities. Single-source vulnerability concentrates in KBA-certified firmware validation labs clustered in Stuttgart. Distribution runs through tier-one system integrators holding long-term OEM contracts, with aftermarket channels increasingly bypassing traditional jobber networks through manufacturer-direct exchange programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware calibration expertise and functional safety validation capacity sit in critically short supply relative to hardware manufacturing scale, compressing returns for undifferentiated pump producers while concentrating margin capture among control unit specialists with KBA and NHTSA certification track records.
For Market Incumbents: Build certification moats by expanding captive validation laboratory capacity in Baden-Württemberg and Michigan to extend UN ECE R79 timeline advantages over emerging competitors. Deepen backward integration into rare earth magnet offtake agreements to insulate pump margins from dysprosium price volatility. Channel control through direct aftermarket portals threatens traditional distributor relationships; securing fleet operator exchange programs now prevents disintermediation. For New Entrants and Emerging Players: India's Maharashtra and Gujarat commercial vehicle corridors present the most penetrable white-space, with Bharat Stage VI enforcement creating first-mover windows before incumbent localization investments mature. Agricultural autonomy platforms in precision farming offer secondary entry points where tunable electro-hydraulic road feel outperforms fully electric alternatives. A go-to-market angle anchored to CSRD-compliant carbon transparency documentation unlocks EU tier-one supplier qualification faster than commodity pricing competition. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated control unit specialists with captive firmware IP and established KBA validation relationships, as these assets compound defensibility against steer-by-wire substitution threats. The long-term viability window favors suppliers bridging electro-hydraulic installed base service with smart steering sensor fusion development. The signal to watch is EPA Phase 3 enforcement intensity — accelerated retrofit mandates would extend electro-hydraulic relevance beyond current technology roadmap assumptions, while stall or delay would compress transition timelines toward fully electric architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Firmware Validation Center Investment | UN ECE R79 certification timelines lock OEM relationships for 18-24 month cycles. |
| Rare Earth Magnet Long-term Offtake Agreement | Dysprosium and neodymium price hedging secures pump assembly margin stability. |
| Direct Aftermarket Portal Launch | Fleet operator exchange programs in the US Great Lakes bypass traditional distributor networks. |
| CSRD-Certified Production Facility Upgrade | Hydrogen-fired heat treatment maintains OEM qualification under EU Green Deal carbon border adjustments. |
| Smart Steering Sensor Fusion Platform Development | Lane-keeping and automated parking integration extends electro-hydraulic relevance against steer-by-wire substitution. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with OEM platform engineers, tier-one supplier procurement leads, aftermarket service chain operators, and steering system calibration specialists. Secondary validation drew from EPA fuel economy compliance filings, KBA type-approval documentation, UN ECE R79 regulatory texts, vehicle production databases, and customs trade records for rare earth magnet flows. Bottom-up segment sizing triangulated against top-down OEM procurement budget analysis.
Calibration across the analysis window employed vehicle class, propulsion architecture, steering technology tier, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from production volume forecasts weighted by content-per-vehicle assumptions for commercial versus passenger applications. Industry-specific inputs included EPA Phase 3 enforcement trajectory scenarios and Bharat Stage VI adoption curves in Indian truck manufacturing.
Macroeconomic conditions sit as an overlay; deviation in rare earth commodity prices, commercial vehicle fleet investment cycles, or automated driving regulatory pacing would shift the trajectory. Forecasts assume current UN ECE R79 validation timelines and CSRD disclosure requirements remain stable. Material shifts in steer-by-wire technology readiness or EPA enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Crankshaft Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
LNG Engine Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Fuel Injection Systems Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Clutch Market
Powertrain
Europe Turbocharger Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Carburetor Market
Powertrain
Automotive Paddle Shifter Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Automotive Coil Spring Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
EV Powertrain Market