
 Automotive Fuel Feed Pumps Market | 2026-2036
Automotive Fuel Feed Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Feed Pumps Market Analysis
German component manufacturing is pivoting toward electrification-compatible pump architectures. Robert Bosch GmbH leverages its mechatronics integration depth to supply electronically controlled variable displacement pumps for mild-hybrid platforms. Continental AG anchors its position through in-house production of precision-machined pump housings and sensor-integrated modules. Denso Corporation competes aggressively in the Asian OEM channel with compact, high-pressure designs optimized for downsized gasoline direct-injection engines.
An automotive fuel feed pump is a precision fluid-handling device that draws fuel from the tank and delivers it to the engine at regulated pressure, typically operating between 3 bar and 200 bar depending on injection architecture and fuel type. Its primary commercial purpose is to ensure consistent fuel delivery across varying engine loads, ambient temperatures, and altitude conditions while minimizing vapor lock and cavitation risk. Electric pump configurations now dominate structural margin pools as electronic control enables real-time pressure modulation for start-stop and hybrid systems. Variable displacement technology leads volume growth due to its parasitic loss reduction, while mechanical lift applications contract in passenger vehicles but sustain demand in commercial and off-road segments where electrical system simplicity outweighs efficiency gains.
EPA fuel economy mandates and Euro 7 emission frameworks are forcing pump suppliers to validate designs for broader fuel compatibility, including ethanol blends and synthetic e-fuels. NHTSA safety standards govern crashworthiness and leak prevention, adding material and testing burdens that favor suppliers with established regulatory dossiers. Stakeholders must monitor how rapidly OEMs consolidate fuel system architectures onto integrated thermal-fluid modules, as this determines whether standalone pump suppliers retain design authority or become captive component sources to larger system integrators.
Market Dynamics
EPA Corporate Average Fuel Economy standards and Euro 7 emission limits are compressing pump supplier development cycles while OEMs accelerate hybrid powertrain procurement, forcing component manufacturers to validate architectures for multi-fuel compatibility ahead of regulatory deadlines.
Growth Catalysts
- Hybrid powertrain mandates:OEM procurement of electric fuel feed pumps intensifies as automakers balance efficiency targets against electrification timelines, creating sustained demand for electronically controlled variable displacement units.
- Downsized direct-injection engines:Gasoline direct-injection architectures require high-pressure pump designs operating above 150 bar, favoring suppliers with precision-machining capabilities and sensor integration expertise.
- China localization requirements:Domestic vehicle production scaling and component sourcing rules reshape supplier geography, concentrating volume growth in localized manufacturing clusters.
Market Restraints
- Aluminum and rare-earth magnet costs:Input price volatility for pump motor materials compresses margins for suppliers without long-term commodity hedging or backward integration into magnet sourcing.
- Supplier concentration in precision machining:Germany and Japan dominate high-tolerance housing production, creating geographic single-source risk for OEMs qualifying alternative suppliers.
- Mechanical pump substitution ceiling:Commercial and off-road segments retain mechanical lift pump demand where electrical system simplicity outweighs efficiency gains, fragmenting R&D investment across incompatible architectures.
Strategic Opportunities
- Synthetic e-fuel compatibility:Euro 7 frameworks validate designs for broader fuel compatibility, opening certification pathways for pumps engineered for ethanol blends and hydrogen-derived synthetic fuels.
- Integrated thermal-fluid modules:OEM consolidation of fuel system architectures onto unified modules creates white space for suppliers with mechatronics integration depth to capture design authority from standalone pump manufacturers.
- Aftermarket sensor retrofit kits:Channel innovation through diagnostic-enabled replacement pumps allows independent service networks to offer pressure-monitoring upgrades for legacy vehicle fleets.
Industry Challenges
- Multi-fuel calibration expertise:Talent scarcity in fluid dynamics simulation and corrosive fuel material science extends validation timelines as suppliers staff for ethanol-blend and e-fuel compatibility testing.
- Crashworthiness certification burden:NHTSA safety standards governing leak prevention and fire suppression add material testing costs and documentation requirements that favor established regulatory dossiers over new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Feed Pumps Market |
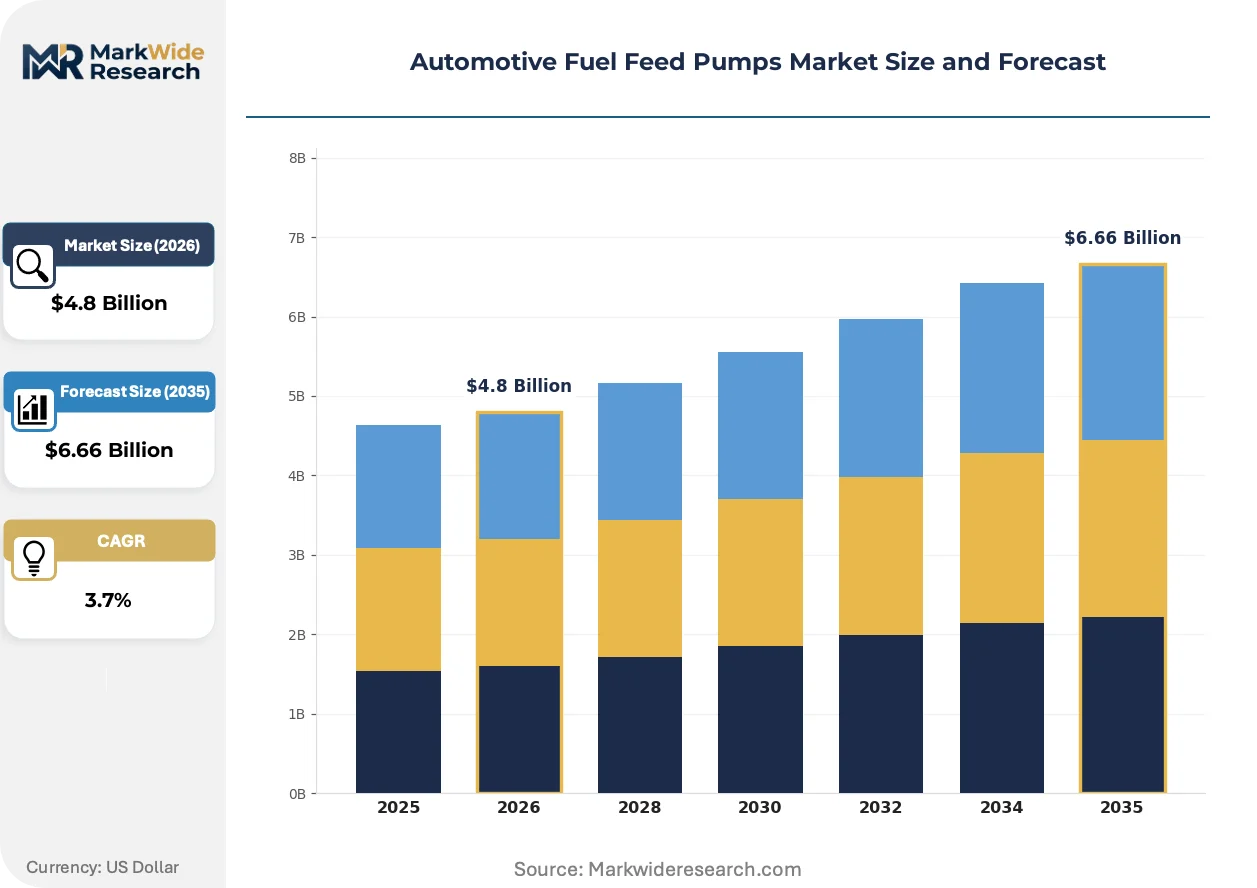
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Pump, Electric Pump, Diaphragm Pump, Gear Pump Technology: Variable Displacement, Constant Displacement, Mechanical Lift, Electronic Control End User: OEMs, Aftermarket Suppliers, Garage Service Providers, Fleet Operators Fuel Type: Gasoline, Diesel, Ethanol, Biodiesel |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Aisin Corporation, Delphi Technologies, Hitachi Astemo, TI Automotive, Carter Fuel Systems, Walbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Feed Pumps Market Emerging Trajectories
Real-time pressure modulation capabilities and variable displacement architectures are displacing fixed-output designs across passenger vehicle segments, while regulatory mandates force simultaneous validation for synthetic fuel compatibility.
Brushless DC motor technology with integrated electronic control is expanding into mild-hybrid and start-stop applications, enabling precise fuel pressure adjustment across engine load cycles. Tier 1 suppliers are adopting these motors for 48V architectures to minimize parasitic losses during coasting and regeneration phases. The technology is expanding into cost-sensitive compact vehicle segments previously served by fixed-displacement pumps, compressing the addressable market for legacy mechanical designs.
EPA fuel economy mandates and Euro 7 emission frameworks are forcing pump suppliers to validate designs for broader fuel compatibility, including ethanol blends and synthetic e-fuels. The industrial consequence is extended material testing protocols and corrosion-resistant coating requirements that add six to twelve months to qualification cycles. Passenger vehicle gasoline direct-injection platforms are most affected, with suppliers accelerating stainless steel and polymer composite housing development to meet chemical resistance specifications.
Fleet procurement departments are consolidating fuel system sourcing onto platform-shared modules, reducing the number of qualified pump suppliers per OEM group. Tier 1 system integrators are capturing design authority previously held by standalone pump manufacturers, displacing component-level RFPs with subsystem procurement contracts. This concentration is most visible in German and Japanese OEM supply chains, where vertical integration strategies favor captive fuel system divisions over external pump specialists.
Automotive Fuel Feed Pumps Market Segmentation
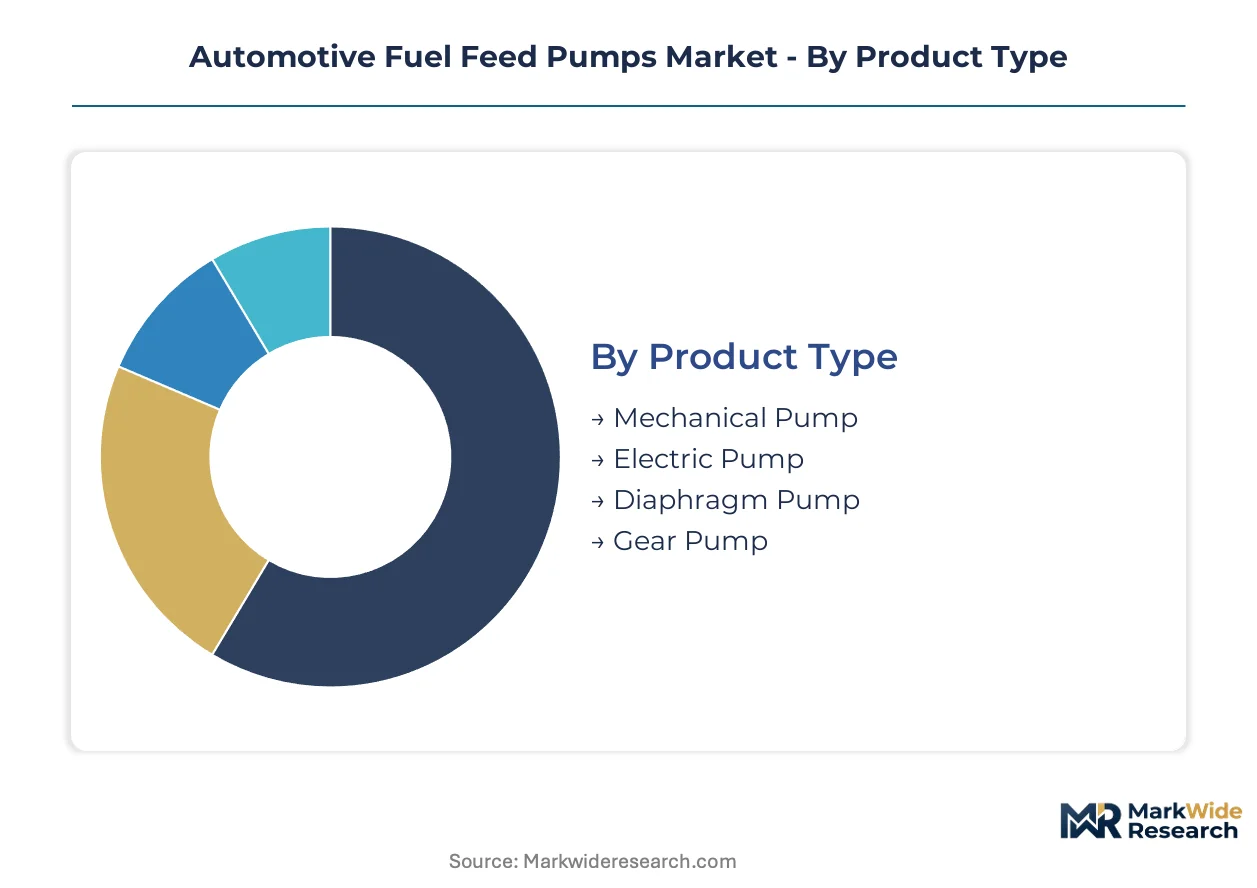
Fuel feed pump architectures fragment across integration depth, from standalone modules to embedded thermal-fluid systems. Understanding where each segment sits on this spectrum clarifies supplier design authority and margin capture potential.
Product Type:
Standalone pump configurations dominate serviceable replacement channels, while embedded designs integrate into unified fuel system modules.
- Electric Pump:Brushless DC motor architectures with integrated electronic control enable real-time pressure modulation for start-stop and hybrid powertrains. Demand concentrates in German and Japanese OEM supply chains where 48V mild-hybrid platforms require precise fuel delivery across regeneration cycles. EPA fuel economy mandates accelerate procurement of electronically controlled variable displacement units over fixed-output designs.
- Mechanical Pump:Camshaft-driven diaphragm or plunger mechanisms deliver fuel without electrical dependency, operating reliably in high-vibration environments. Commercial and off-road segments in Brazil and India retain demand where electrical system simplicity outweighs efficiency gains and mechanic familiarity reduces service costs.
- Diaphragm Pump:Flexible membrane displacement suits low-pressure carbureted engines and small-displacement motorcycles.
- Gear Pump:Positive displacement rotary designs handle high-viscosity fuels in heavy-duty diesel applications.
Electric pumps lead volumes today; diaphragm pumps are gaining share fastest in emerging market two-wheeler segments.
Technology:
Cost tier stratification separates premium electronically controlled architectures from economy mechanical lift systems.
- Variable Displacement:Swashplate or eccentric ring mechanisms modulate output to match engine demand, reducing parasitic losses during partial load operation. Euro 7 emission frameworks validate these designs for synthetic e-fuel compatibility, extending qualification cycles but opening premium pricing tiers for corrosion-resistant stainless steel housings.
- Electronic Control:Sensor-integrated modules with CAN bus communication enable closed-loop pressure regulation and diagnostic feedback. German OEM procurement concentrates here as fleet operators demand predictive maintenance capabilities and OBD-II compliance for emissions monitoring.
- Constant Displacement:Fixed-output designs serve cost-sensitive compact vehicles where electronic control adds unacceptable bill-of-material burden.
- Mechanical Lift:Suction or gravity-fed systems persist in agricultural and construction equipment where electrical failure modes create unacceptable downtime risk.
Variable displacement leads volumes today; electronic control is climbing the fastest as OEMs consolidate onto integrated thermal-fluid modules.
End User:
Customer type determines specification authority and channel economics, from captive OEM sourcing to fragmented aftermarket service.
- OEMs:Platform-shared module procurement reduces qualified supplier pools per vehicle program, favoring Tier 1 system integrators with mechatronics depth. NHTSA crashworthiness certification requirements add documentation burdens that exclude new entrants without established regulatory dossiers.
- Aftermarket Suppliers:Diagnostic-enabled replacement pumps with pressure sensor retrofit kits create channel innovation opportunities. Independent service networks in the United States and Germany leverage these upgrades for legacy fleet maintenance revenue.
- Garage Service Providers:Repair shop procurement favors plug-and-play replacement units with standardized mounting interfaces.
- Fleet Operators:Volume purchasers negotiate subsystem contracts with fuel system integrators rather than standalone pump manufacturers.
OEMs lead volumes today; aftermarket suppliers are expanding most quickly through sensor-enabled diagnostic retrofit kits.
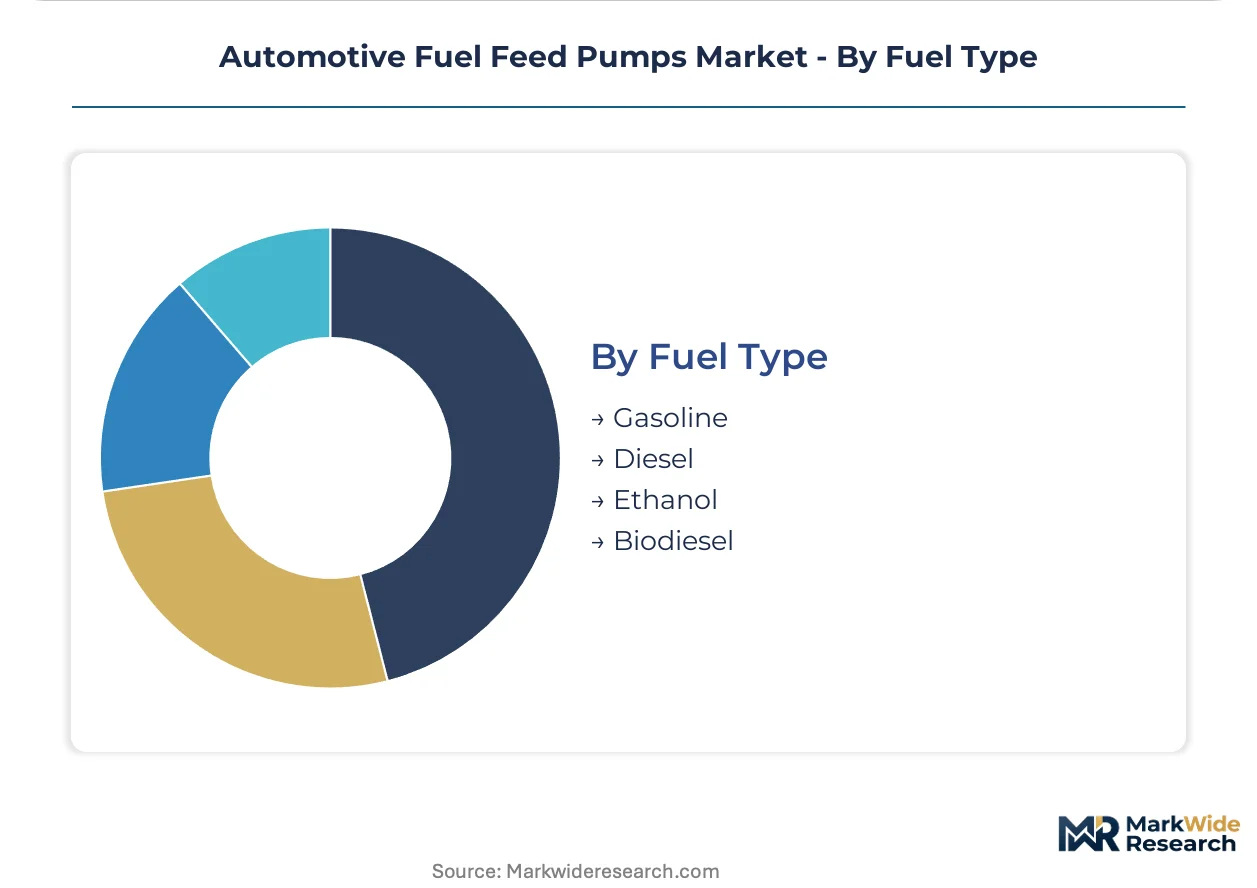
Fuel Type:
Material compatibility requirements segment suppliers by corrosion science expertise and coating technology maturity.
- Gasoline:Direct-injection architectures above 150 bar demand precision-machined stainless steel housings and polymer composite internals. Chinese domestic production scaling concentrates volume in localized manufacturing clusters serving SAIC, Geely, and BYD platforms.
- Diesel:High-pressure common-rail systems require robust sealing against abrasive fuel properties and water contamination. Indian commercial vehicle production sustains demand for heavy-duty gear pump configurations.
- Ethanol:Blends above E10 accelerate material testing protocols for elastomer compatibility and galvanic corrosion resistance.
- Biodiesel:Fatty acid methyl ester content challenges seal integrity and deposit formation in precision clearances.
Gasoline leads volumes today; ethanol-compatible designs are gaining share fastest as Euro 7 frameworks mandate broader fuel flexibility validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing geography as suppliers relocate to jurisdictions with lower cost-of-compliance structures while maintaining EPA and Euro 7 certification equivalence for export-bound production.
China
Domestic vehicle production scaling and MIIT localization mandates concentrate pump procurement in SAIC, Geely, and BYD supply chains. GB standards for fuel system safety and the country's dual carbon goals accelerate electric pump adoption across 48V mild-hybrid platforms. Manufacturing clusters in the Yangtze River Delta around Shanghai and the Pearl River Delta near Shenzhen dominate precision-machined housing production for gasoline direct-injection systems.
Germany
KBA type-approval requirements and Euro 7 pre-certification timelines compress supplier development cycles for variable displacement architectures. Bavaria anchors Continental AG and Robert Bosch GmbH operations, where in-house mechatronics integration enables sensor-embedded pump modules for German OEM hybrid platforms. North Rhine-Westphalia precision-machining corridors sustain high-tolerance housing output for 150-bar gasoline direct-injection applications.
United States
NHTSA crashworthiness standards and EPA Corporate Average Fuel Economy mandates drive OEM procurement of electronically controlled pumps for start-stop systems. Michigan and Ohio manufacturing belts concentrate Tier 1 system integrator activity, where subsystem contracts displace standalone pump RFPs. Detroit-area engineering centers validate multi-fuel compatibility for ethanol blends ahead of federal renewable fuel standard deadlines.
Japan
METI energy efficiency targets and JIS quality certification sustain demand for compact, high-pressure designs in downsized gasoline engines. Denso Corporation and Hitachi Astemo operations in the Chubu region around Nagoya dominate Asian OEM channel supply. Kansai manufacturing corridors near Osaka specialize in brushless DC motor production for 48V mild-hybrid architectures.
India
Bureau of Indian Standards fuel system safety norms and PLI scheme incentives for automotive components attract localized pump manufacturing. Commercial vehicle production in Maharashtra and Tamil Nadu sustains mechanical lift pump demand where electrical system simplicity reduces service costs. Haryana and Gujarat clusters serve Maruti Suzuki and Tata Motors platforms with cost-optimized fixed-displacement units.
Automotive Fuel Feed Pumps Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated thermal-fluid module partnerships with Tier 1 system integrators. The supplier base stratifies across three tiers: mechatronics-integrated specialists with sensor-embedded portfolios, precision-machining houses with housing production depth, and regional fabricators serving cost-sensitive aftermarket channels. Consolidation pressure intensifies as OEMs reduce qualified supplier pools per platform. Dominant competitive moves include backward integration into rare-earth magnet sourcing and strategic partnerships with fuel system integrators to retain design authority.
Among Germany-based fabricators, Robert Bosch GmbH and Continental AG exemplify the mechatronics-integrated archetype through their positioning in electronically controlled variable displacement architectures. Denso Corporation anchors the Asian OEM channel specialist tier. These three entities represent contrasting geographic concentrations—European system integration depth versus Asian high-volume manufacturing scale—while each occupies a distinct position in the transition from standalone pump supply to embedded fuel system module provision.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Aisin Corporation |
| Delphi Technologies |
| Hitachi Astemo |
| TI Automotive |
| Carter Fuel Systems |
| Walbro |
| Others |
Supply Flow & Price Mechanics
Euro 7 emission frameworks gate qualified supply for corrosion-resistant pump architectures while compressing margin structures for suppliers lacking stainless steel housing capabilities or multi-fuel certification dossiers. Premium-tier pricing access concentrates with German and Japanese producers possessing in-house precision machining and sensor integration depth, while cost-optimized fixed-displacement units face pricing pressure from Chinese manufacturing clusters.
Pricing Analysis
Distributor margin layers in aftermarket channels sustain 25-35 point markups over OEM direct procurement, creating arbitrage opportunities for independent service networks. Three-tier pricing structure across premium, standard, and economy levels separates sensor-embedded variable displacement modules from fixed-output electric designs and legacy mechanical lift pumps. Cost compression in economy tiers intensifies because aluminum and rare-earth magnet input volatility erodes fabricator margins without long-term commodity hedging. Fleet operators exhibit lowest price sensitivity due to subsystem procurement contracts, while garage service providers in emerging markets drive volume through plug-and-play replacement units.
Supply Chain Analysis
Rare-earth magnet supply rests on Chinese processing dominance and Japanese magnet alloy production, creating geographic concentration risk for brushless DC motor fabricators. Precision-machined pump housings draw from German and Japanese high-tolerance manufacturing corridors, while aluminum die-casting feeds from Chinese and Indian secondary metal markets. Single-source vulnerability in neodymium magnet sourcing threatens production continuity for electronically controlled architectures. Distribution runs through Tier 1 system integrator channels that consolidate standalone pump procurement into unified fuel system module contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between Euro 7 pre-certification timelines in Germany and cost-optimized manufacturing in China creates geographic positioning advantages for suppliers with dual-qualification capabilities. Cost differentials in precision machining labor and environmental compliance burden favor selective capacity relocation to Eastern European or Southeast Asian clusters while maintaining KBA and EPA certification equivalence.
For Market Incumbents: Cement design authority in integrated thermal-fluid modules through captive sensor-embedded pump production and strategic partnerships with fuel system integrators. Backward integration into rare-earth magnet sourcing defends margin position against commodity volatility. Euro 7 multi-fuel calibration requirements threaten suppliers without corrosion science expertise; prioritize stainless steel housing capacity expansion in Bavaria or Nagoya corridors. For New Entrants and Emerging Players: Independent aftermarket service networks in Brazil and India represent an underserved buyer archetype with diagnostic-enabled retrofit kit demand. Cost-optimized fixed-displacement electric pumps for commercial vehicle segments in Maharashtra and Tamil Nadu offer the most penetrable entry point. Channel partnerships with regional garage service providers bypass OEM qualification barriers while building brand recognition for eventual Tier 2 supplier status. For Investors and Strategic Acquirers: Roll-up economics work for precision-machining specialists with housing production depth because OEM consolidation onto platform-shared modules reduces qualified supplier pools and concentrates pricing power with remaining vendors. Five-to-ten year viability hinges on mechatronics integration capabilities rather than standalone pump manufacturing. The signal to watch is Tier 1 system integrator acquisition activity targeting sensor-embedded module suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Sourcing | Captive neodymium supply secures brushless DC motor production continuity against Chinese export restrictions. |
| Multi-Fuel Compatibility Certification | Euro 7 validation for ethanol blends and synthetic e-fuels opens premium pricing tiers in German OEM channels. |
| Integrated Thermal-Fluid Module Partnership | Design authority capture from standalone pump suppliers depends on sensor-embedded architecture collaboration with Continental AG. |
| Regional Manufacturing Footprint Expansion | Yangtze River Delta clusters serve SAIC and Geely platforms while satisfying MIIT localization mandates. |
| Aftermarket Diagnostic Retrofit Development | Pressure sensor kits for legacy fleets create recurring revenue streams through independent US and German service networks. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs trade records. Triangulation between demand-side consumption patterns and supply-side capacity utilization ensures cross-verified volume estimates.
Historical trendline analysis across gasoline direct-injection penetration rates, hybrid powertrain adoption curves, and regional production cluster shifts established baseline growth trajectories. Segmentation dimensions modeled include propulsion architecture, pump technology tier, end-user channel, and regional regulatory framework throughout the forecast period. CAGRs derive from regression analysis against EPA and Euro 7 implementation timelines, with fuel system integration depth and rare-earth magnet cost indices as industry-specific forecast inputs.
Underlying measurement precision varies by segment; electric pump and variable displacement categories carry tighter precision than mechanical lift applications due to more transparent OEM procurement reporting. Forecasts reflect documented assumptions regarding regulatory implementation schedules, commodity price stabilization, and OEM platform consolidation trajectories. Accelerated electrification timelines, trade restriction expansion on critical minerals, or faster-than-expected integrated module adoption represent specific risk factors that could revise projections. A small set of regulatory trigger dates and Tier 1 supplier consolidation announcements warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Exhaust System Muffler Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Brazil Automotive Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Car Oil Filter Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
EV Powertrain Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Yaw Damper Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Half Shaft Market
Powertrain
Automotive Engine Piston Rings Market