
 Automotive Drivetrain Market | 2026-2036
Automotive Drivetrain Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Drivetrain Market Intelligence
Asset-light manufacturing models, which prioritize system integration over in-house component production, is tilting the competitive balance away from historically vertically integrated players. ZF Friedrichshafen AG leverages its deep R&D in complex transmission and e-mobility systems to maintain its market position. BorgWarner Inc. specializes in powertrain components for both internal combustion and electric vehicles, offering a bridge technology portfolio. Dana Limited focuses on axle and driveshaft technologies, particularly for commercial and off-highway vehicle applications.
An automotive drivetrain comprises the set of components that transmit power from the engine or electric motor to the driving wheels. This system's primary function is to manage torque and rotational speed through components like the transmission, driveshaft, axles, and differentials. The electric drivetrain technology segment is experiencing significant expansion, particularly within the passenger vehicles application. In contrast, conventional automatic transmissions maintain a large footprint in the aftermarket, driven by the vast number of existing internal combustion engine vehicles.
Governmental regulations directly steer drivetrain technology development and investment. Frameworks like the US EPA's vehicle emissions standards and the EU's CO2 emission performance standards for cars and vans are forcing a shift to more efficient and electrified solutions. Concurrently, technical specifications mandated by China's GB standards are critical for any component supplier seeking market access. Suppliers must therefore navigate the strategic choice between investing in incremental efficiency gains for legacy systems or committing fully to next-generation electric powertrain platforms.
Market Dynamics
The automotive drivetrain market's evolution is dictated by the global regulatory push for decarbonization. This momentum, codified in frameworks like the EU Green Deal and China's dual carbon goals, mandates a rapid pivot from internal combustion engines to electrified powertrain architectures.
Growth Catalysts
- Emissions Regulations:Stringent CO2 emission performance standards in the European Union compel automakers to increase the sales mix of battery-electric and plug-in hybrid vehicles, directly stimulating demand for advanced electric drivetrains.
- Semiconductor Technology:The adoption of wide-bandgap semiconductors, such as Silicon Carbide (SiC) in inverters, enables higher efficiency, faster charging, and more compact electric drivetrain designs, improving overall vehicle performance and appeal.
- Geographic Demand Concentration:China's combination of government incentives, charging infrastructure investment, and a dominant domestic EV manufacturing base creates the world's largest and fastest-growing market for electric drivetrain components.
Market Restraints
- Critical Material Costs:The high price and supply volatility of rare earth metals, particularly neodymium and dysprosium used in permanent magnet electric motors, pose a significant cost and sourcing challenge for drivetrain manufacturers.
- Infrastructure Deficits:Inadequate public charging infrastructure in many developing regions, including parts of Latin America and Southeast Asia, acts as a structural barrier to widespread consumer adoption of battery-electric vehicles.
- Battery Supply Bottlenecks:The geographic concentration of battery cell production in Asia creates supply chain vulnerabilities for automakers in North America and Europe, potentially delaying vehicle production and drivetrain order fulfillment.
Strategic Opportunities
- Commercial Vehicle Electrification:The growing focus on urban last-mile delivery and logistics sustainability opens a significant market for specialized electric drivetrain systems designed for light commercial vehicles and medium-duty trucks.
- High-Voltage Architectures:Developing and supplying components for 800-volt drivetrain systems offers a path to differentiation, as these architectures provide tangible benefits in charging speed and performance for premium electric vehicles.
- Emerging Market Entry:Automotive markets in Southeast Asia, such as Thailand and Indonesia, are introducing policies to encourage EV production and adoption, creating new growth frontiers for drivetrain component suppliers.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of power electronics engineers and software developers with expertise in electric motor control and battery management systems constrains R&D and production scalability for suppliers.
- System Integration Complexity:Integrating novel electric drivetrain units with existing vehicle platforms, particularly legacy software and network architectures, presents significant technical hurdles and validation timelines for automakers.
- Standardization Gaps:The lack of a single global standard for charging interfaces and communication protocols complicates the design of onboard chargers and related drivetrain components, requiring market-specific variations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Drivetrain Market |
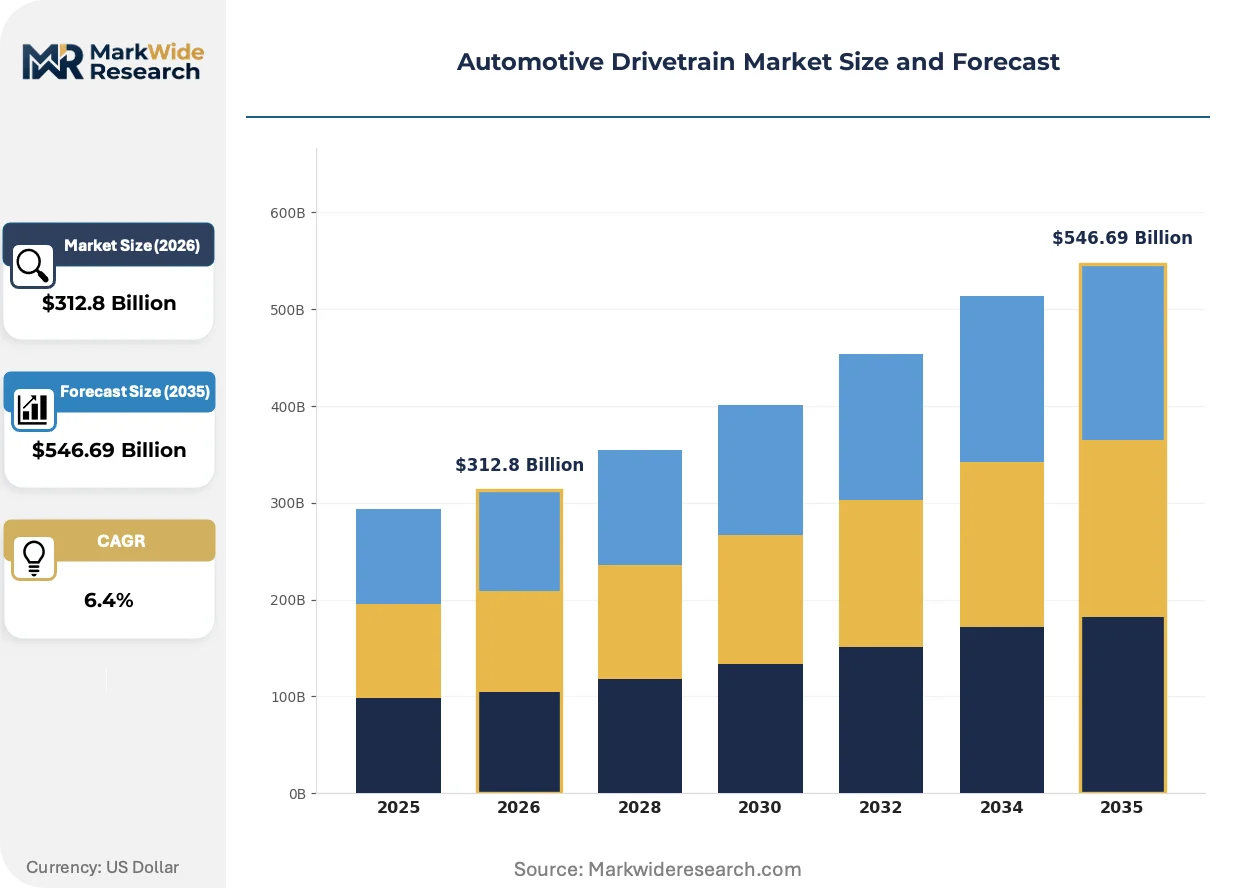
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $546.69 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmissions, Differentials, Axles, Driveshafts, Clutches, Transfer Cases Technology: Manual, Automatic, Continuously Variable Transmission, Dual Clutch, Electric Drivetrain, Hybrid Drivetrain Application: Passenger Vehicles, Commercial Vehicles, Agricultural Equipment, Construction Machinery, Mining Machines, Marine Vessels End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers, Fleet Operators, Repair Workshops |
| Companies Covered | Schaeffler AG, BorgWarner Inc., Magna International Inc., Denso Corporation, Continental AG, Aisin Seki Co., Ltd., Dana Limited, Robert Bosch GmbH, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Drivetrain Market Strategic Shifts & Innovations
The transition from mechanical engineering to software-defined functionality is reshaping the core of drivetrain design and validation. This shift prioritizes system-level simulation, digital integration, and modular architectures to manage the complexity and accelerate the development of next-generation electrified powertrains.
Digital twin technology provides a virtual replica of a physical drivetrain system, complete with its mechanical components and software controls. Automakers and Tier 1 suppliers increasingly adopt these models throughout the design and validation process. This technology is virtualizing the development cycle, enabling extensive testing under simulated real-world conditions and significantly reducing reliance on costly and time-consuming physical prototypes.
The US Inflation Reduction Act (IRA) introduces stringent local content requirements for critical minerals and battery components to qualify for consumer EV tax credits. This policy directly impacts drivetrain sourcing strategies, compelling manufacturers to re-shore or near-shore their supply chains for motors, batteries, and power electronics. The North American passenger vehicle segment is most affected, with suppliers now prioritizing regional production capabilities.
A notable behavioral change involves automakers licensing entire EV platform architectures rather than developing all drivetrain systems in-house. This disrupts the traditional model of sourcing individual components like transmissions or axles from multiple suppliers. This trend is most visible among EV startups and legacy automakers in Europe and North America who use these pre-integrated "skateboard" platforms to reduce development costs and speed market entry.
Automotive Drivetrain Market Segmentation
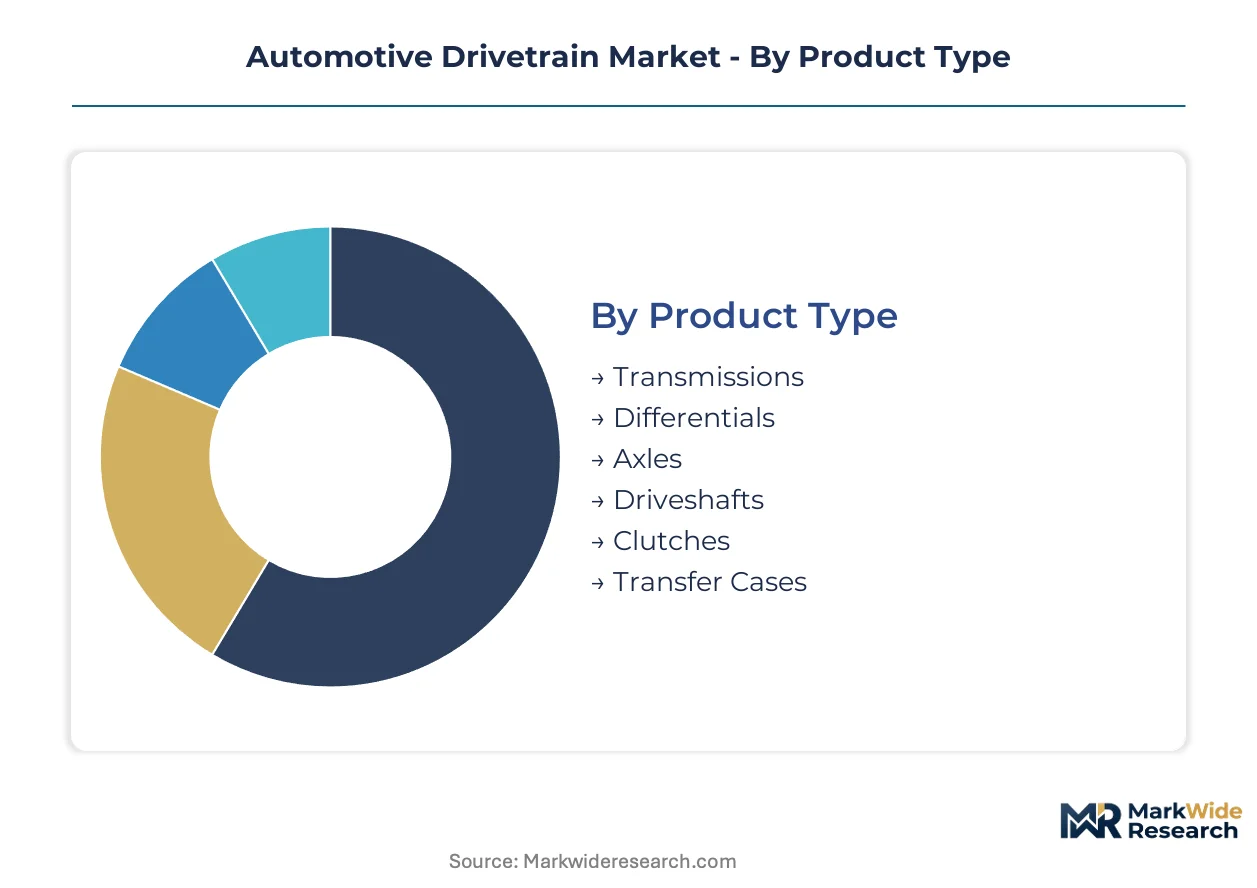
The automotive drivetrain market segments reflect diverse functional requirements and technological advancements across vehicle types. Understanding these distinct segments provides clarity on demand drivers, technological shifts, and competitive landscapes for component suppliers and vehicle manufacturers. Each category highlights specific areas of innovation or sustained market presence.
Product Type:
The use-case spectrum for drivetrain components ranges from fundamental power transfer to specialized torque management. Suppliers must offer tailored solutions across this range for both conventional and electrified powertrains.
- Transmissions:These mechanical or electro-mechanical assemblies manage engine or motor torque and speed, delivering power to the driveshaft. Demand for advanced multi-speed automatic transmissions remains high in North America, while electric vehicle drivetrains integrate single-speed reduction gears.
- Axles:Axles transmit power from the differential to the wheels, supporting vehicle weight and enduring significant stress. Commercial vehicle electrification in China increases demand for robust, integrated e-axle solutions, combining electric motors, power electronics, and gearboxes.
- Differentials:Differentials allow wheels on the same axle to rotate at different speeds, crucial for cornering and traction. Performance vehicles and off-highway equipment require specialized locking or limited-slip differentials.
- Driveshafts:Driveshafts connect the transmission or transfer case to the differential, transmitting rotational force. Light commercial vehicles frequently utilize multi-piece driveshaft designs for flexibility.
- Clutches:Clutches engage and disengage power from the engine to the transmission, primarily in manual transmission vehicles. The aftermarket segment for clutch replacements remains substantial in developing economies.
- Transfer Cases:Transfer cases are found in four-wheel-drive and all-wheel-drive vehicles, distributing power between front and rear axles. Heavy-duty pickups often feature electronically controlled transfer cases.
Established volume favors Transmissions; emerging adoption favors Axles, particularly e-axle variants.
Technology:
Drivetrain technology maturity spans from long-established mechanical systems to rapidly evolving electric and hybrid solutions. Each technology addresses different performance, efficiency, and emissions targets for vehicle manufacturers.
- Electric Drivetrain:This technology integrates electric motors, inverters, and reduction gears to power electric vehicles. Demand for compact, high-efficiency electric drivetrains is intensifying in Europe due to stringent CO2 emission performance standards.
- Automatic:Automatic transmissions automatically change gear ratios as the vehicle moves, enhancing driving comfort. Sales of automatic transmission vehicles dominate in the US passenger vehicle segment, supported by consumer preference.
- Hybrid Drivetrain:Hybrid drivetrains combine an internal combustion engine with an electric motor and battery system. China's new energy vehicle policies support the expansion of plug-in hybrid drivetrain components.
- Continuously Variable Transmission:CVTs offer seamless gear ratio changes, optimizing fuel efficiency and acceleration. Japanese automakers frequently integrate CVTs into their compact and mid-size passenger vehicle lines.
- Dual Clutch:DCTs use two separate clutches for odd and even gears, enabling faster and smoother shifts. Performance-oriented vehicle segments in Germany often feature advanced dual-clutch transmissions.
- Manual:Manual transmissions require the driver to manually select gears using a clutch pedal and gear stick. Cost-sensitive markets in India and Southeast Asia maintain a strong preference for manual drivetrain systems.
Demand for Automatic transmissions is driven by consumer convenience; Electric Drivetrain technology is expanding most quickly.
Application:
The application spectrum for automotive drivetrains ranges from high-volume passenger vehicles to specialized off-highway machinery. Each application dictates unique performance, durability, and integration requirements for drivetrain systems.
- Passenger Vehicles:This segment includes cars, SUVs, and light trucks, representing the largest volume for drivetrain components. The transition to electric drivetrains in passenger vehicles is accelerated by governmental incentives in countries like Germany and Norway.
- Commercial Vehicles:This category encompasses light, medium, and heavy-duty trucks, as well as buses. Electrification efforts for commercial vehicles, particularly for last-mile delivery fleets in urban centers, drive demand for robust e-axle systems.
- Agricultural Equipment:Drivetrain systems for tractors and harvesters require high torque capacity and durability for demanding field operations. Manufacturers in the US Midwest prioritize rugged, reliable drivetrain components.
- Construction Machinery:Excavators, loaders, and bulldozers utilize heavy-duty drivetrains designed for extreme loads and harsh environments. China's infrastructure development projects sustain demand for specialized construction machinery drivetrains.
- Mining Machines:Drivetrains in mining trucks and drilling equipment must withstand abrasive conditions and continuous heavy-duty cycles. Suppliers often develop custom solutions for large-scale mining operations in Australia.
- Marine Vessels:Drivetrain components for boats and ships focus on power transmission from engines to propellers, requiring corrosion resistance and high reliability. Recreational marine applications in North America drive demand for compact, efficient systems.
The Passenger Vehicles segment drives the largest market share; Commercial Vehicles presents significant growth opportunities.
End User:
The end-user ecosystem for automotive drivetrains includes new vehicle manufacturers, component suppliers, and service providers. Each end-user type has distinct procurement needs and influences market dynamics differently.
- OEMs:Original Equipment Manufacturers integrate drivetrain components into new vehicle production lines. Automakers in Europe are increasingly seeking modular electric drivetrain platforms from Tier-1 suppliers to accelerate EV development.
- Aftermarket Providers:These entities supply replacement parts and service components for existing vehicle fleets. The vast installed base of internal combustion engine vehicles in Latin America sustains a substantial aftermarket for traditional drivetrain parts.
- Vehicle Assemblers:These companies specialize in assembling vehicles, often sourcing major components like drivetrains from external suppliers. EV startups in North America frequently partner with established drivetrain technology providers.
- Tier-1 Suppliers:Tier-1 suppliers design and manufacture complex drivetrain systems and modules directly for OEMs. ZF Friedrichshafen AG consistently invests in advanced e-mobility system development.
- Fleet Operators:Businesses managing large vehicle fleets, such as logistics companies, procure drivetrain components for maintenance and repair. Urban delivery fleets increasingly demand efficient and durable electric drivetrain solutions.
- Repair Workshops:These service centers perform maintenance and repair on vehicles, requiring a steady supply of drivetrain spare parts. Independent repair workshops in India serve a diverse range of vehicle models.
The OEMs segment holds substantial long-term value; Aftermarket Providers are critical for maintaining the existing vehicle parc.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for automotive drivetrains heavily favors established automotive manufacturing hubs with high vehicle production. These regions exhibit significant consumer demand for new vehicles and robust supply chains for complex components. The global shift towards electric mobility is reshaping demand patterns across key geographies.
China
Demand for electric drivetrains in China is driven by substantial government incentives and a massive domestic EV manufacturing base. The country's dual carbon goals mandate a rapid pivot to electrified architectures, accelerating technology adoption. Major EV production clusters in Shenzhen and Shanghai are rapidly integrating advanced e-axle solutions.
Germany
Stringent CO2 emission performance standards in the European Union compel German automakers to increase sales of battery-electric and plug-in hybrid vehicles. This directly stimulates demand for advanced electric drivetrains and high-efficiency automatic transmissions. The Stuttgart region, a traditional automotive powerhouse, sees intensive R&D in e-mobility systems.
United States
Consumer preference for automatic transmissions and large SUVs drives a significant market for conventional drivetrain components. The US EPA's vehicle emissions standards push for greater efficiency. The Inflation Reduction Act (IRA) introduces stringent local content requirements, impacting sourcing strategies for Detroit-based automotive engineering hubs.
India
Cost-sensitive markets in India maintain a strong preference for manual drivetrain systems and robust, affordable components for passenger vehicles. The country's PLI scheme for automotive components encourages domestic manufacturing. The automotive industrial belt around Chennai and Pune is expanding production capacity for diverse drivetrain solutions.
Japan
Japanese automakers frequently integrate Continuously Variable Transmissions (CVTs) into compact and mid-size passenger vehicle lines, optimizing fuel efficiency. METI policies support innovation in hybrid drivetrain technology and advanced materials. The Aichi Prefecture, home to major automotive manufacturers, continues to be a center for powertrain development.
Automotive Drivetrain Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for automotive drivetrains. The competitive landscape features a mix of historically vertically integrated entities and agile, asset-light integrators. Strategic archetypes include full-system providers, component specialists, and emerging e-mobility solution developers. Dominant competitive moves involve strategic partnerships for technology co-development and targeted capacity expansion in electric powertrain components.
Within the full-system provider archetype, ZF Friedrichshafen AG exemplifies deep R&D in complex transmission and e-mobility systems, maintaining a strong market position. BorgWarner Inc. occupies a position as a powertrain component specialist, offering a bridge technology portfolio for both internal combustion and electric vehicles. Dana Limited represents a focused player in axle and driveshaft technologies, particularly for commercial and off-highway vehicle applications. These companies anchor different segments of the market, reflecting varied strategic priorities and technological expertise across the drivetrain ecosystem.
| Leading Market Players |
|---|
| Schaeffler AG |
| BorgWarner Inc. |
| Magna International Inc. |
| Denso Corporation |
| Continental AG |
| Aisin Seki Co., Ltd. |
| Dana Limited |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
The Asia-Europe maritime freight corridor's cost dynamics influence drivetrain component pricing, shaping supply concentration and downstream price differentiation for vehicle manufacturers. Supply chain resilience for critical components is paramount as the automotive industry pivots to electric powertrains.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material and energy prices, dominate long-term supply agreements between Tier-1 suppliers and OEMs. Price differentiation stems from the quality grade of components, such as high-performance e-axles versus standard automatic transmissions, and the level of customization required for specific vehicle platforms. Pricing pressure currently trends upward, driven by the high cost and supply volatility of rare earth metals used in electric motors. OEMs for mass-market passenger vehicles exhibit the highest price sensitivity, while specialized commercial vehicle manufacturers prioritize performance and reliability.
Supply Chain Analysis
Semiconductor export controls from major technology-producing nations limit the free flow of advanced power electronics essential for electric drivetrains. Geographic supply concentration for critical materials like rare earth metals is centered in China, while Germany and Japan remain key hubs for advanced transmission and hybrid technologies. The supply chain relies heavily on wide-bandgap semiconductors, such as Silicon Carbide (SiC), and battery cells. Commodity price volatility for rare earth metals poses a significant structural risk. Distribution for new vehicle production runs directly to OEMs, while the aftermarket segment utilizes a network of multi-channel distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive drivetrain market requires a robust substitution defense as electric powertrain architectures displace traditional internal combustion engine systems. Incumbents must navigate this fundamental shift by adapting their core competencies.
For Market Incumbents:
Pre-empt market share erosion by accelerating investment in electric drivetrain R&D and expanding production capacity for e-mobility systems. Strategic partnerships with specialized software firms can integrate advanced motor control and battery management systems, mitigating the threat from agile EV startups. Deep R&D in high-voltage architectures, such as 800-volt systems, provides a lever for differentiation in premium segments.
For New Entrants and Emerging Players:
Specialized electric drivetrain systems for light commercial vehicles and medium-duty trucks represent a penetrable entry point. Urban last-mile delivery fleets in Europe and North America offer a clear white space due to increasing sustainability mandates. Offering modular, pre-integrated "skateboard" platforms to new EV manufacturers provides a compelling go-to-market angle, reducing their development costs and accelerating market entry.
For Investors and Strategic Acquirers:
Carve-out targets emerge from legacy automotive suppliers seeking to divest non-core internal combustion engine assets, offering opportunities for specialized e-mobility plays. The market offers sustained growth potential over the next decade as electrification accelerates globally. Acquisition targets should focus on power electronics firms, advanced e-motor technology developers, or software specialists in control systems. Continued investment in commercial vehicle electrification is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate e-Drivetrain R&D | ZF Friedrichshafen AG strengthens its position in advanced e-mobility systems. |
| Invest in SiC Manufacturing | BorgWarner Inc. secures critical wide-bandgap semiconductor supply for inverters. |
| Expand e-Axle Production | Dana Limited meets rising demand for integrated commercial vehicle electrification solutions. |
| Form EV Platform Partnerships | Legacy OEMs reduce development costs by licensing pre-integrated "skateboard" architectures. |
| Target Emerging EV Markets | Suppliers gain new growth frontiers in Southeast Asia's developing electric vehicle ecosystems. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews, complemented by rigorous secondary validation. OEM procurement managers, Tier-1 R&D engineers, aftermarket distributors, and fleet operators provided critical insights. Secondary data sources included governmental emissions reports from the US EPA and EU Green Deal, industry association publications, and company financial reports.
Market volume and value outputs were calibrated through an integrated analytical framework applied across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional EV adoption rates. Compound annual growth rates were derived through a combination of regression analysis, market share shifts, and expert consensus. Key forecast inputs included global EV production forecasts and critical material price trends.
Stress conditions across geopolitical trade tensions and raw material supply volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented through this comprehensive approach. Material shifts in regulatory mandates or raw material supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Fuel Pumps Market
Powertrain
Automotive Coil Spring Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Spark Plugs Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Global Automotive Pumps Market
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
Motor Vehicle Carburetors Market