
 Europe Hill-Start Assist System Market | 2026-2036
Europe Hill-Start Assist System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hill-Start Assist System Market Insights
Steel in brake caliper housings is hardening cost structures as manufacturers pivot toward aluminum alloys to reduce unsprung mass. Continental AG leverages its integrated brake control architecture to sustain engineering partnerships with German premium OEMs. Robert Bosch GmbH anchors sensor-to-actuator development through in-house production of yaw-rate modules and pressure sensors. ZF Friedrichshafen AG competes on vehicle dynamics integration, bundling hill-start assist within broader chassis control systems.
A hill-start assist system is an active safety mechanism that temporarily maintains brake pressure for two to three seconds after pedal release, preventing rollback on inclined surfaces through solenoid valve modulation and longitudinal accelerometer input. Electronic systems dominate the product type landscape due to their compatibility with electronic stability control networks and lower hydraulic complexity. Passenger cars generate the largest vehicle type volume, though commercial vehicles carry superior per-unit content as multi-axle configurations demand distributed brake control. Sensor integration technology leads the technology dimension, with accelerometer and inclinometer fusion becoming baseline specification for Euro NCAP alignment.
The European Union General Safety Regulation mandates advanced driver assistance systems including hill-start assist on new vehicle types, while ECE R13-H governs braking performance and compatibility standards across member states. ECHA scrutiny of friction material compositions under REACH is shifting supplier qualification requirements toward copper-free brake pad formulations. Stakeholders must monitor how the EU Green Deal's embodied carbon tracking extends into automotive component sourcing, particularly for aluminum-intensive brake hardware manufactured outside the customs union.
Market Dynamics
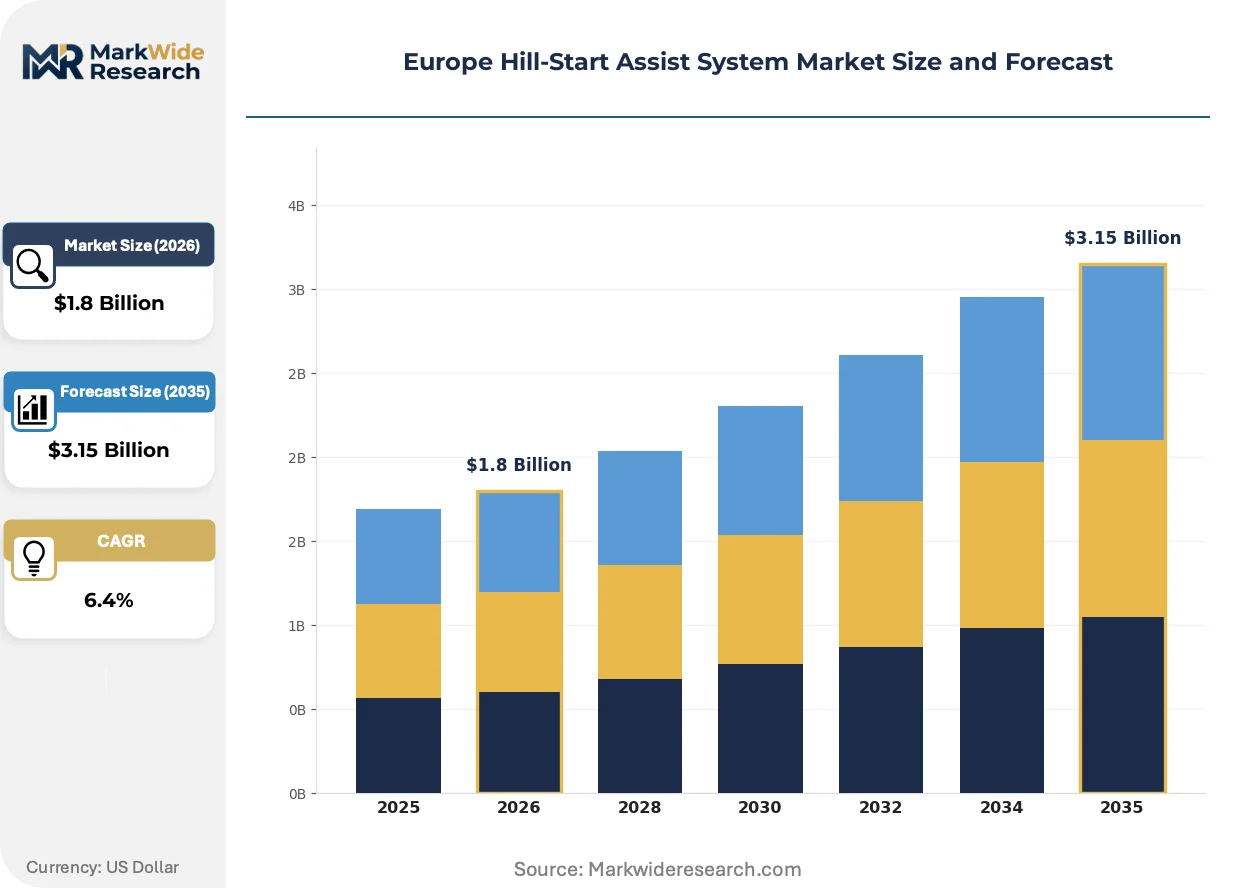
EU General Safety Regulation mandates are compressing adoption timelines across European OEM platforms, forcing brake system suppliers to rearchitect electronic control unit integration before 2026 type-approval deadlines.
Growth Catalysts
- ECE R13-H braking standards:Harmonized performance requirements across EU member states eliminate national certification fragmentation, reducing engineering validation cycles for multi-market vehicle programs.
- Commercial vehicle fleet electrification:Electric drivetrain torque characteristics amplify rollback risk on gradients, necessitating hill-start assist as baseline specification for electric trucks and buses.
- Copper-free friction materials:ECHA REACH restrictions on heavy metal content in brake pads are accelerating qualification of compliant formulations that integrate seamlessly with electronic brake control architectures.
Market Restraints
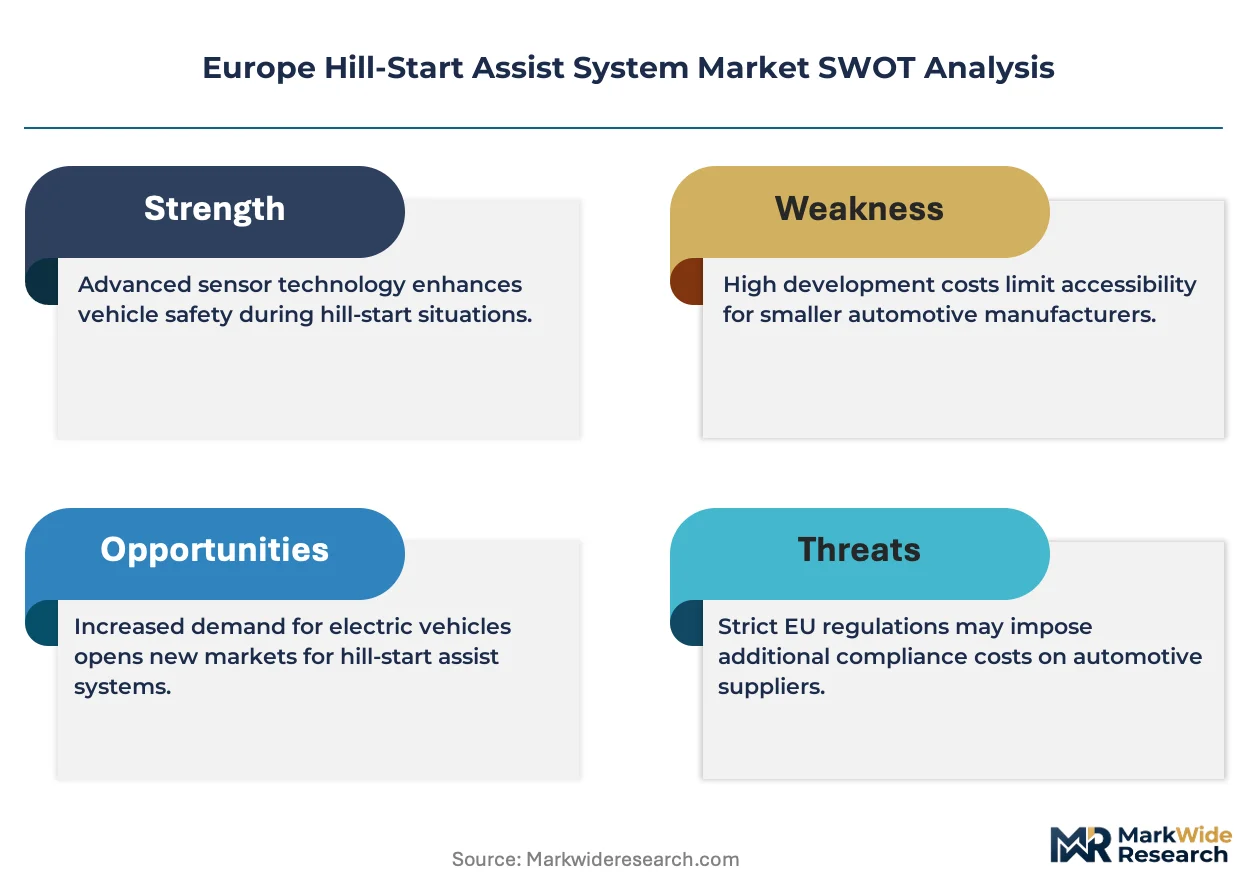
- Aluminum alloy supply concentration:Primary smelting capacity for brake caliper housings clusters in specific EU customs union neighbors, exposing tier-one suppliers to carbon border adjustment mechanism cost pass-through.
- Sensor fusion complexity:Integration of longitudinal accelerometers with vehicle CAN bus networks demands specialized calibration protocols that extend development timelines for smaller brake system manufacturers.
- Hydraulic system legacy inertia:Established service networks and technician training investments in conventional brake architectures slow fleet operator willingness to adopt fully electronic hill-start assist configurations.
Strategic Opportunities
- Eastern European manufacturing expansion:Slovakia and Czech Republic vehicle assembly plants are adding premium platform capacity requiring advanced chassis control systems including integrated hill-start assist modules.
- Sensor-to-cloud data monetization:Hill-start assist event logging combined with telematics platforms creates recurring revenue streams for fleet management software providers serving logistics operators.
- EU Green Deal embodied carbon tracking:Component-level carbon accounting favors suppliers with renewable-powered aluminum foundries and closed-loop brake pad recycling programs.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for brake control software remains concentrated among a limited pool of automotive semiconductor and tier-one suppliers.
- Multi-OEM platform integration:Divergent electronic architecture specifications between German premium manufacturers and French volume producers fragment engineering resource allocation for brake system suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hill-Start Assist System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional System, Electronic System, Hydraulic System, Pneumatic System End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Rental Services Technology: Brake Control, Sensor Integration, Vehicle Dynamics, Control Algorithms Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Trucks |
| Companies Covered | Knorr-Bremse AG, Valeo, Continental AG, Aisin Corporation, BorgWarner Inc., Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Murata Manufacturing Co., Ltd., ZF Friedrichshafen AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hill-Start Assist System Market Trends and Innovations
Brake control electronics are migrating from centralized hydraulic units toward distributed wheel-end architectures, compressing response latency and enabling vehicle-level dynamics coordination previously isolated within separate chassis domains.
Sensor fusion is decentralizing brake system intelligence from standalone electronic control units into integrated wheel speed and inertial measurement modules mounted directly at axle corners. German premium OEMs are specifying these consolidated packages for 2026 platform launches. This topology is compressing wiring harness complexity and enabling faster closed-loop pressure modulation.
EU General Safety Regulation phase-in timelines are mandating hill-start assist as standard equipment on all new vehicle types registered from mid-2024, eliminating optional equipment economics for budget segment producers. French and Italian volume manufacturers are responding by bundling the function within base-trim brake system specifications. Commercial vehicle operators face accelerated fleet refresh cycles to maintain regulatory compliance across cross-border haulage routes.
Specification authority is migrating from fleet procurement departments to vehicle engineering teams responsible for platform safety ratings. Tier-one brake suppliers in Germany report direct engineering engagement replacing traditional aftermarket distribution channels for commercial vehicle retrofits. This pattern concentrates order volume among OEM-authorized system integrators and compresses independent component distributor margins.
Europe Hill-Start Assist System Market Segmentation
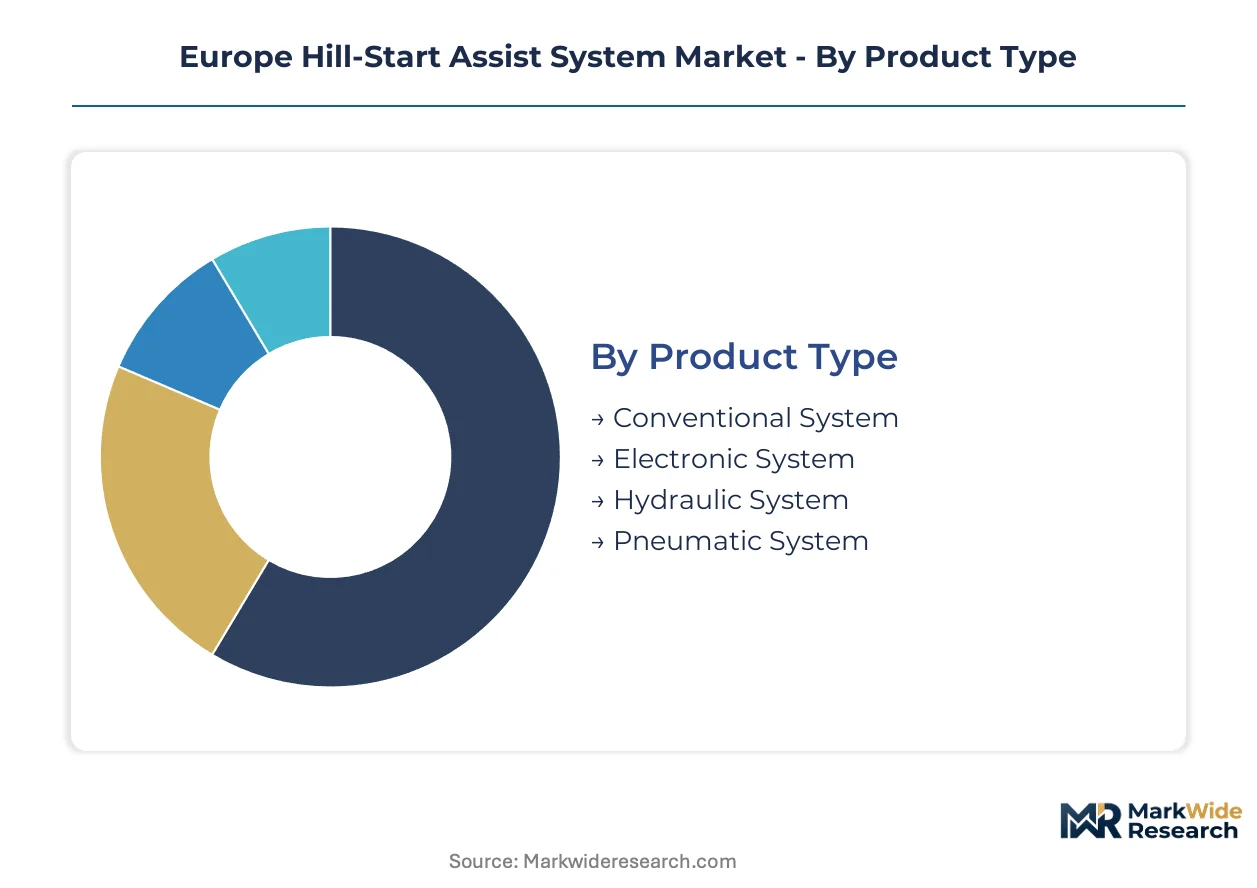
Hill-start assist system procurement patterns diverge sharply across product architectures and customer types, with certification requirements under ECE R13-H and EU General Safety Regulation creating tiered compliance burdens that reshape supplier qualification pathways.
Product Type:
ECE R13-H type-approval mandates differentiate certification complexity across hydraulic, electronic, and pneumatic architectures, with electronic systems facing accelerated validation timelines under EU General Safety Regulation phase-in schedules.
- Electronic System:Solenoid valve modulation controlled through electronic control unit architecture enables millisecond-response brake pressure maintenance. German premium OEMs specify these configurations for 2026 platform launches, driven by Euro NCAP alignment requirements and ESC network compatibility.
- Hydraulic System:Conventional brake fluid pressure retention through mechanical valving persists in commercial vehicle retrofit markets. Fleet operators in Italy and Spain favor these units for compatibility with existing service infrastructure, constrained by technician retraining costs for electronic alternatives.
- Conventional System:Mechanical hill-hold mechanisms using cable-actuated drum brakes serve budget vehicle segments in Eastern European markets.
- Pneumatic System:Compressed air brake pressure modulation dominates heavy truck and bus configurations across Alpine corridor haulage routes.
Leading the category by volume: Electronic System. Growing fastest: Pneumatic System in electric commercial vehicle platforms.
End User:
Specification authority concentrates with vehicle engineering teams versus procurement departments, fragmenting traditional aftermarket distribution economics.
- OEMs:German premium manufacturers integrate hill-start assist within base-trim brake system specifications to satisfy EU General Safety Regulation mandates. Direct engineering engagement with tier-one suppliers replaces component distributor intermediation, compressing independent channel margins.
- Vehicle Assemblers:Slovakia and Czech Republic assembly plants require advanced chassis control modules for premium platform capacity expansion. Eastern European manufacturing growth drives demand for pre-integrated hill-start assist systems delivered as axle-corner packages.
- Aftermarket Providers:Retrofit installations face declining addressable market as regulatory mandates eliminate optional equipment economics.
- Rental Services:Fleet standardization pressures accelerate refresh cycles for cross-border compliance.
Dominating procurement volume: OEMs. Expanding most quickly: Vehicle Assemblers in Eastern European manufacturing zones.
Technology:
Functional safety certification under ISO 26262 ASIL-D concentrates engineering resources among tier-one suppliers with in-house semiconductor capabilities.
- Sensor Integration:Accelerometer and inclinometer fusion modules mounted at axle corners enable decentralized brake intelligence. French volume manufacturers specify these consolidated packages to reduce wiring harness complexity, driven by platform cost reduction targets.
- Brake Control:Electronic control unit architectures with yaw-rate and pressure sensor inputs coordinate pressure modulation across multi-axle configurations. Commercial vehicle demand in Germany concentrates here for distributed brake control on electric trucks.
- Vehicle Dynamics:Chassis-level coordination integrating hill-start assist with stability control networks.
- Control Algorithms:Software calibration protocols for longitudinal accelerometer CAN bus integration.
Commanding development investment: Sensor Integration. Climbing the fastest: Vehicle Dynamics bundling.
Vehicle Type:
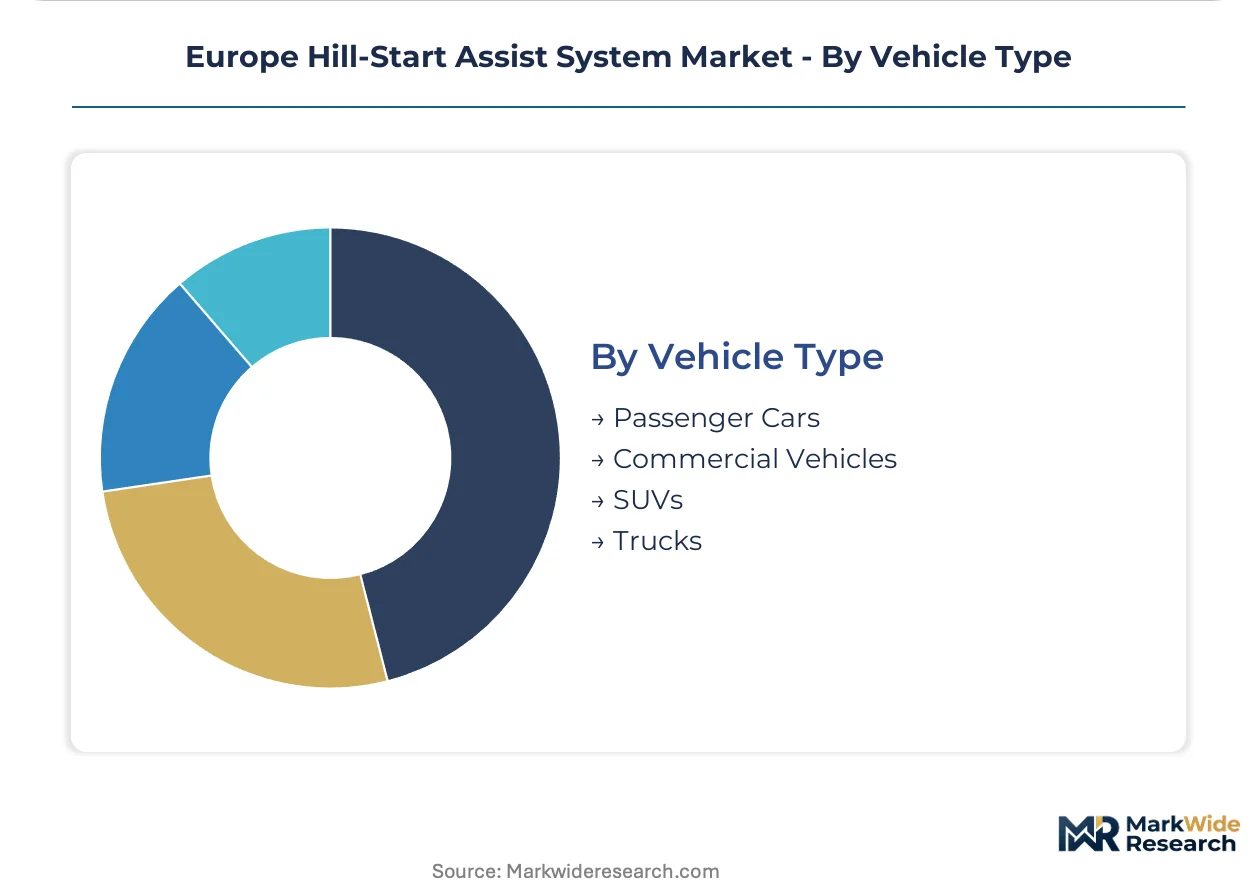
Per-unit content value escalates with axle count and gross vehicle weight rating, inverting volume-value economics across passenger and commercial segments.
- Commercial Vehicles:Multi-axle configurations demand distributed brake control with separate pressure modulation per axle group. Electric drivetrain torque characteristics amplify rollback risk, positioning hill-start assist as baseline specification for electric trucks and buses across German and French fleet operators.
- Passenger Cars:High-volume production generates largest absolute unit shipments despite lower per-vehicle content. Italian and French volume manufacturers bundle electronic systems within base trim to eliminate optional equipment economics.
- SUVs:Higher center-of-gravity profiles intensify gradient stability requirements.
- Trucks:Heavy-duty pneumatic configurations serve cross-border Alpine haulage.
Generating highest unit volume: Passenger Cars. Steepest expansion trajectory: Commercial Vehicles in electrified platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Slovakia and the Czech Republic concentrate new vehicle assembly capacity requiring advanced chassis control modules. These zones attract tier-one brake system suppliers through streamlined customs procedures and proximity to German premium OEM engineering centers.
Germany
Electric truck fleet operators in Bavaria and Baden-Württemberg demand distributed brake control systems for multi-axle configurations. KBA type-approval requirements under ECE R13-H compress validation timelines for new platform launches. Stuttgart's automotive engineering corridor hosts concentrated brake control software development for 2026 vehicle programs.
France
Volume manufacturers in Île-de-France bundle hill-start assist within base-trim specifications to satisfy EU General Safety Regulation mandates. ANSM oversight of automotive component safety standards influences supplier qualification protocols. The Auvergne-Rhône-Alpes region hosts aluminum foundry capacity serving brake caliper housing production.
Italy
Commercial vehicle retrofit markets in Lombardy and Piedmont favor hydraulic hill-start configurations compatible with existing service infrastructure. ECHA REACH compliance requirements for copper-free friction materials reshape brake pad supplier portfolios. Turin's automotive supplier cluster adapts technician training programs for electronic brake control architectures.
Slovakia
Premium platform assembly plants in Bratislava and Žilina require pre-integrated hill-start assist modules delivered as axle-corner packages. EU Green Deal embodied carbon tracking favors suppliers with renewable-powered aluminum sourcing. The country's special economic zones attract brake system component manufacturing through competitive energy tariffs.
Czech Republic
Vehicle assemblers in the Central Bohemian Region expand capacity for German OEM platforms requiring advanced chassis control integration. ECE R13-H harmonized standards eliminate national certification fragmentation for multi-market programs. The Ostrava industrial zone concentrates sensor module production for accelerometer and inclinometer fusion systems.
Europe Hill-Start Assist System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one system integrators commanding direct OEM relationships while independent distributors serve retrofit markets. The supplier base concentrates among German and Japanese conglomerates with in-house semiconductor capabilities, compressing margins for smaller brake component specialists. Two strategic archetypes dominate: integrated chassis control providers bundling hill-start assist within broader vehicle dynamics platforms, and dedicated brake electronics specialists focusing on sensor-to-actuator calibration. Competitive moves center on strategic partnerships for sensor fusion technology and geographic expansion into Eastern European manufacturing zones.
Within the integrated chassis control tier, Continental AG and ZF Friedrichshafen AG exemplify full-system providers leveraging electronic brake control architectures. Robert Bosch GmbH anchors the sensor-to-actuator development archetype through captive production of yaw-rate modules and pressure sensors. These three German entities occupy positions shaped by ISO 26262 ASIL-D functional safety certification requirements and direct engineering engagement with premium OEM platform teams.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| Valeo |
| Continental AG |
| Aisin Corporation |
| BorgWarner Inc. |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Murata Manufacturing Co., Ltd. |
| ZF Friedrichshafen AG |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal embodied carbon tracking gates qualified supply and premium-tier pricing access for brake system suppliers, favoring renewable-powered aluminum foundries with closed-loop recycling programs while compressing margins for carbon-intensive competitors locked out of German premium OEM sourcing pools.
Pricing Analysis
Short lead-time premiums dominate brake control module procurement, with German OEM platform teams paying above-contract rates for expedited sensor-to-actuator calibration cycles while spot inventory of hydraulic retrofit kits trades at discount in Italian commercial vehicle channels. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified electronic systems from ECE R13-H baseline configurations and mechanical hill-hold mechanisms. Cost compression in economy-tier pneumatic systems is intensifying because Eastern European fleet operators prioritize compatibility over performance. Aftermarket distributors serving Lombardy retrofit markets exhibit highest price sensitivity, while Stuttgart engineering corridors show lowest sensitivity due to platform safety rating imperatives.
Supply Chain Analysis
Direct-to-OEM channels handle German premium manufacturer demand through tier-one system integrators, bypassing traditional aftermarket distribution. Geographic supply concentration clusters in Germany for brake control software, Slovakia for axle-corner module assembly, and Czech Republic for accelerometer fusion sensor production. Raw material dependencies draw from aluminum alloy smelters in Auvergne-Rhône-Alpes, copper-free friction material formulations under ECHA REACH compliance, and semiconductor substrates for yaw-rate modules. Single-source vulnerability in ISO 26262 ASIL-D certified software engineering talent concentrates risk among Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG. Distribution runs through OEM-authorized system integrators with direct engineering engagement replacing component distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU General Safety Regulation phase-in deadlines are forcing consolidation across brake system suppliers, eliminating independent distributors and smaller hydraulic specialists unable to fund ASIL-D certification investments.
For Market Incumbents: Extend functional safety certification coverage into Eastern European manufacturing zones before Czech and Slovak assembly plant capacity ramps absorb available engineering talent pools. Anchor sensor-to-actuator development through captive production of yaw-rate modules and pressure sensors to defend against emerging Chinese brake electronics entrants targeting European aftermarket channels. Prioritize backward integration into renewable-powered aluminum foundries to secure Green Deal-compliant supply for premium OEM platform specifications. For New Entrants and Emerging Players: Fleet management software providers represent the most penetrable channel partner type, enabling sensor-to-cloud data monetization from hill-start assist event logging without competing directly on brake hardware certification. Target commercial vehicle electrification retrofits in Alpine corridor haulage routes where electric drivetrain torque characteristics amplify rollback risk and incumbent hydraulic service networks lag electronic system deployment. Pursue white-label sensor fusion module production for French volume manufacturers seeking axle-corner package consolidation to reduce wiring harness complexity. For Investors and Strategic Acquirers: Tier-one brake suppliers announcing Eastern European manufacturing expansion is the leading indicator that platform standardization opportunities are concentrating among integrated chassis control providers. The market reads as a 5-10 year consolidation play favoring acquirers of ISO 26262 ASIL-D certified software engineering teams and renewable-powered aluminum component suppliers. Watch for Czech Republic sensor module producers achieving accelerometer-inclinometer fusion qualification as the inflection signal for pre-integrated hill-start assist system acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Eliminates optional equipment economics for French and Italian volume manufacturers under EU General Safety Regulation mandates. |
| Backward Integration into Aluminum Foundries | Secures Green Deal-compliant brake caliper housing supply for German premium OEM sourcing pools. |
| Sensor-to-Cloud Data Monetization | Creates recurring revenue streams for fleet management software providers serving German and French logistics operators. |
| Geographic Manufacturing Footprint Expansion | Positions tier-one suppliers near Slovakia and Czech Republic premium platform assembly capacity. |
| Software-Defined Vehicle Investment | Enables chassis-level coordination integrating hill-start assist with stability control networks for electric commercial vehicles. |
Research Methodology
Multi-period observation of vehicle platform launch timelines, ECE R13-H type-approval filings, and EU General Safety Regulation compliance certifications anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, brake system R&D directors, and fleet operations managers. Secondary validation drew from KBA registration databases, ANSM safety standard publications, ECHA REACH substance restriction updates, vehicle production statistics, and customs trade records for aluminum alloy brake component flows. Bottom-up unit shipment modeling triangulated against top-down market value estimates derived from tier-one supplier revenue disclosures.
Input-output matrices mapped sensor integration technology adoption rates against commercial vehicle electrification penetration and passenger car platform refresh cycles across the projection horizon. Segmentation dimensions modeled include product architecture, end-user procurement authority, vehicle type content per unit, and regional production cluster regulatory alignment. CAGRs were computed through iterative convergence of historical trajectory analysis and forward-looking scenario weighting. Industry-specific forecast inputs incorporated ECE R13-H harmonization timelines and copper-free friction material qualification progress under ECHA scrutiny.
Caveats apply where EU carbon border adjustment mechanism implementation schedules or aluminum alloy supply disruptions from customs union neighbors could materially shift the outlook for brake caliper housing cost structures. Forecasts reflect assumptions regarding OEM platform engineering resource allocation and functional safety engineer availability concentrated among German tier-one suppliers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Dual Clutch Transmission (DCT) Market
Powertrain
Engine Tuner Market
Powertrain
CNG Powertrain Market
Powertrain
Global Automotive Clutch Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
Engine Flush Market
Powertrain
Power Assisted Steering Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Steering Damper Market
Powertrain
Transmission Repair Market
Powertrain
Diesel Engine Market