
 Automotive Intermediate Shaft Market | 2026-2036
Automotive Intermediate Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intermediate Shaft Market Outlook
Carbon fiber reinforced polymer is consolidating share against hollow steel in performance-oriented intermediate shaft applications where rotational inertia reduction commands premium positioning. JTEKT Corporation leverages its integrated bearing-to-shaft manufacturing architecture to capture value across the steering column assembly. GKN Automotive anchors European supply through its hollow-forging expertise in constant velocity joint integration. Nexteer Automotive competes aggressively on electromechanical power steering compatibility, sustaining R&D intensity above tier-average levels.
An automotive intermediate shaft is a torque-transmitting driveline component, typically manufactured from medium-carbon alloy steel or aluminum with splined ends, that connects the steering wheel column to the rack-and-pinion or steering gear assembly while accommodating angular misalignment and axial displacement. The component must maintain torsional stiffness tolerances within 0.5 degrees per meter under operational loads exceeding 100 Nm to preserve steering precision and haptic feedback. Manual transmission configurations retain the largest volume share globally, though dual-clutch applications are expanding fastest as torque converter architectures proliferate in premium SUVs. Steel dominates material selection for load-bearing shafts, while aluminum gains traction in mass-sensitive hatchback platforms where every kilogram reduction translates to fleet efficiency compliance.
NHTSA enforces FMVSS 203 and 204 for steering column impact absorption, compelling structural redesigns that integrate collapsible intermediate shaft segments. EPA corporate average fuel economy standards indirectly shape material selection by weight-targeting entire steering assemblies. ECE R12 regulations in Europe mandate comparable occupant protection, creating dual-homologation engineering burdens for multinational suppliers. Stakeholders must monitor electromechanical steering displacement timelines, as steer-by-wire elimination of mechanical intermediate shafts represents the most consequential demand destruction risk across the forecast horizon.
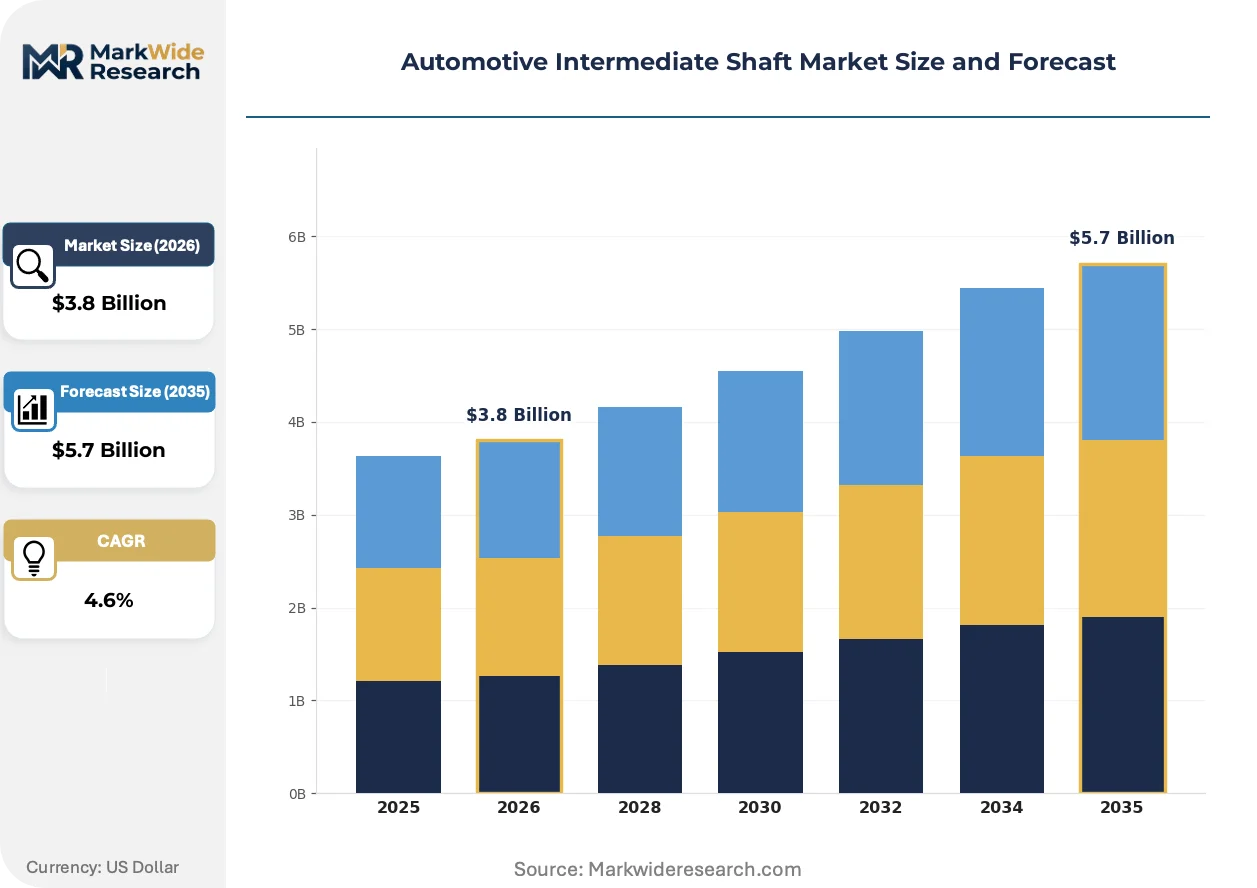
Market Dynamics
Electrification of steering architectures is compressing mechanical content per vehicle while simultaneously upgrading performance specifications for remaining intermediate shafts, forcing suppliers to engineer collapsible torque-transmitting components that satisfy both NHTSA impact standards and steer-by-wire compatibility matrices.
Growth Catalysts
- FMVSS 203/204 Collapsible Mandates:NHTSA impact absorption rules compel structural redesigns that integrate crushable intermediate shaft segments, expanding engineering service attach rates for Tier 1 suppliers.
- Dual-Clutch Transmission Proliferation:Torque converter architectures spreading through premium SUV segments multiply shaft count per powertrain and elevate torsional stiffness requirements.
- Carbon Fiber Reinforced Polymer Adoption:Rotational inertia reduction in performance applications commands premium positioning and displaces hollow steel in motorsport-derived road car platforms.
Market Restraints
- Aluminum Price Volatility:Mass-sensitive hatchback platforms depend on aluminum shafts for fleet efficiency compliance, exposing margins to London Metal Exchange commodity swings.
- Steer-by-Wire Substitution Threat:Elimination of mechanical torque paths in autonomous vehicle architectures threatens demand destruction across the forecast horizon.
- Dual-Homologation Burden:ECE R12 occupant protection mandates in Europe create parallel certification costs for multinational suppliers serving both NHTSA and UNECE jurisdictions.
Strategic Opportunities
- India Light Vehicle Production:Underpenetrated shaft specification levels in domestic OEM platforms offer upgrade potential as BIS safety standards converge with global norms.
- Electromechanical Steering Convergence:Integration of torque sensors and position encoders into shaft assemblies creates bundled value propositions beyond commodity torque transmission.
- EU Green Deal Material Incentives:Recyclability mandates and carbon border adjustments favor aluminum and polymer composite shafts over conventional steel in European sourcing decisions.
Industry Challenges
- Torsional Stiffness Calibration:Maintaining sub-0.5-degree-per-meter tolerances under 100+ Nm operational loads requires metrology capabilities scarce among mid-tier forgers.
- Legacy Rack-and-Pinion Integration:Electromechanical power steering retrofits demand axial displacement accommodation that conflicts with fixed-geometry steering gear interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intermediate Shaft Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Transmission, Automatic Transmission, CVT, Dual-Clutch Material: Steel, Aluminum, Composite, Magnesium Vehicle Type: SUV, Sedan, Truck, Hatchback End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | JTEKT Corporation, Aisin Seiki, GKN Automotive, American Axle & Manufacturing, Schaeffler AG, Magna International, ZF Friedrichshafen AG, Nexteer Automotive, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intermediate Shaft Market Strategic Shifts
Hollow-forging techniques and material substitution are redefining shaft mass-performance tradeoffs while regulatory harmonization pressures reshape engineering resource allocation across multinational supply footprints.
Carbon fiber reinforced polymer is expanding into performance-oriented intermediate shaft applications where rotational inertia reduction commands premium positioning. Motorsport-derived road car platforms from German and Italian OEMs specify CFRP torque tubes for unsprung mass advantages. This material migration is expanding into adjacent structural steering components as forge-hardening costs for hollow steel escalate.
ECE R12 occupant protection mandates in Europe are tightening column integrity requirements comparable to NHTSA FMVSS 203/204 standards. Multinational suppliers face dual-homologation engineering burdens that compress development timelines and elevate validation costs. Premium SUV and light truck segments absorb these compliance costs most readily due to higher per-vehicle component budgets.
Fleet procurement managers are consolidating steering column suppliers to reduce qualification overhead amid electrification platform complexity. Single-source contracts covering bearing, shaft, and joint assemblies displace discrete component purchasing. This concentration is most visible in United States-based light vehicle programs where OEM vertical integration has retreated from steering system manufacturing.
Automotive Intermediate Shaft Market Segmentation
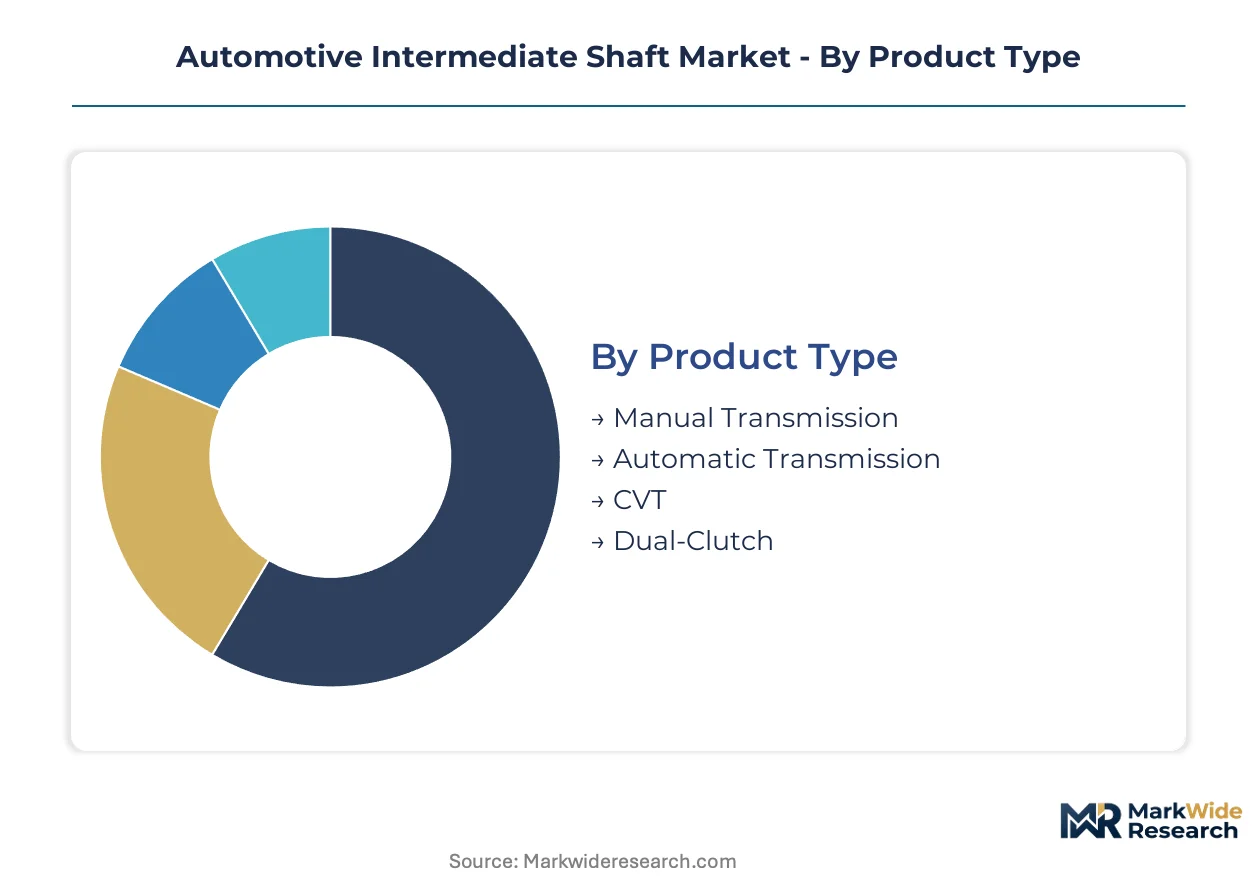
Intermediate shaft specifications diverge sharply across transmission architectures and material platforms, with each segment demanding distinct torsional stiffness calibrations and collapsible design integrations. Understanding these fault lines reveals where engineering complexity concentrates and where commodity substitution threatens margin compression.
Product Type:
Customization intensity escalates from mechanical torque paths through electronically modulated clutch packs, with each transmission category imposing unique angular misalignment tolerances and axial displacement ranges.
- Manual Transmission:Solid steel shafts with splined end configurations dominate this segment, requiring minimal axial travel accommodation. Demand concentrates in India and Brazil where cost-sensitive compact vehicle platforms retain stick-shift configurations for fleet efficiency compliance and consumer price points.
- Dual-Clutch:These architectures demand hollow-forged shafts with enhanced torsional stiffness to manage rapid torque transfer across dual input shafts. German and South Korean OEMs specify these for performance-oriented SUVs where shift-speed precision justifies premium engineering.
- Automatic Transmission:Conventional torque converter designs utilize simpler shaft geometries with standardized spline patterns, serving mass-market sedan and truck applications across North American light vehicle programs.
- CVT:Continuously variable transmissions require intermediate shafts engineered for sustained rotational speeds with minimal vibration transmission, finding traction in Japanese and Chinese compact hatchback platforms prioritizing fuel economy optimization.
Leading the category by volume: Manual Transmission. Growing fastest: Dual-Clutch.
Material:
Cost-to-performance ratios stratify sharply across metallic and polymer options, with regulatory weight mandates and motorsport heritage driving divergence between mass-market and premium applications.
- Steel:Medium-carbon alloy grades deliver the torsional stiffness baseline for load-bearing applications, with hollow-forging techniques reducing mass while preserving structural integrity under 100+ Nm operational loads. This material anchors global production across all transmission categories.
- Aluminum:Extruded and forged aluminum shafts serve mass-sensitive hatchback platforms where every kilogram reduction translates to corporate average fuel economy compliance. European and Japanese OEMs specify these for subcompact vehicle segments facing stringent emissions targets.
- Composite:Carbon fiber reinforced polymer torque tubes command premium positioning in motorsport-derived road car platforms from Italian and German manufacturers, where rotational inertia reduction delivers measurable handling advantages.
- Magnesium:Die-cast magnesium shafts occupy niche applications in ultra-lightweight urban mobility concepts, limited by corrosion susceptibility and higher raw material processing costs relative to aluminum alternatives.
Steel maintains volume leadership across all geographies. Aluminum climbs fastest as fleet efficiency regulations tighten.
Vehicle Type:
Platform architecture and duty-cycle severity segment shaft specifications, with body-on-frame and unibody constructions imposing fundamentally different packaging constraints and load profiles.
- SUV:Higher ride heights and increased unsprung mass demand reinforced intermediate shafts with extended axial travel ranges to accommodate suspension articulation. Premium SUV segments absorb compliance cost premiums most readily.
- Sedan:Conventional three-box platforms utilize standardized shaft lengths and spline configurations, benefiting from economies of scale across high-volume production runs in Chinese and United States assembly plants.
- Truck:Commercial and light-duty truck applications prioritize durability over mass reduction, with solid steel shafts dominating this segment despite fleet efficiency pressures.
- Hatchback:Compact packaging constraints and mass sensitivity drive aluminum and composite adoption, particularly in European A-segment and B-segment platforms where every gram influences CO2 fleet averages.
Sedan platforms generate highest unit volumes. SUV specifications show steepest expansion trajectory as consumer preference shifts.
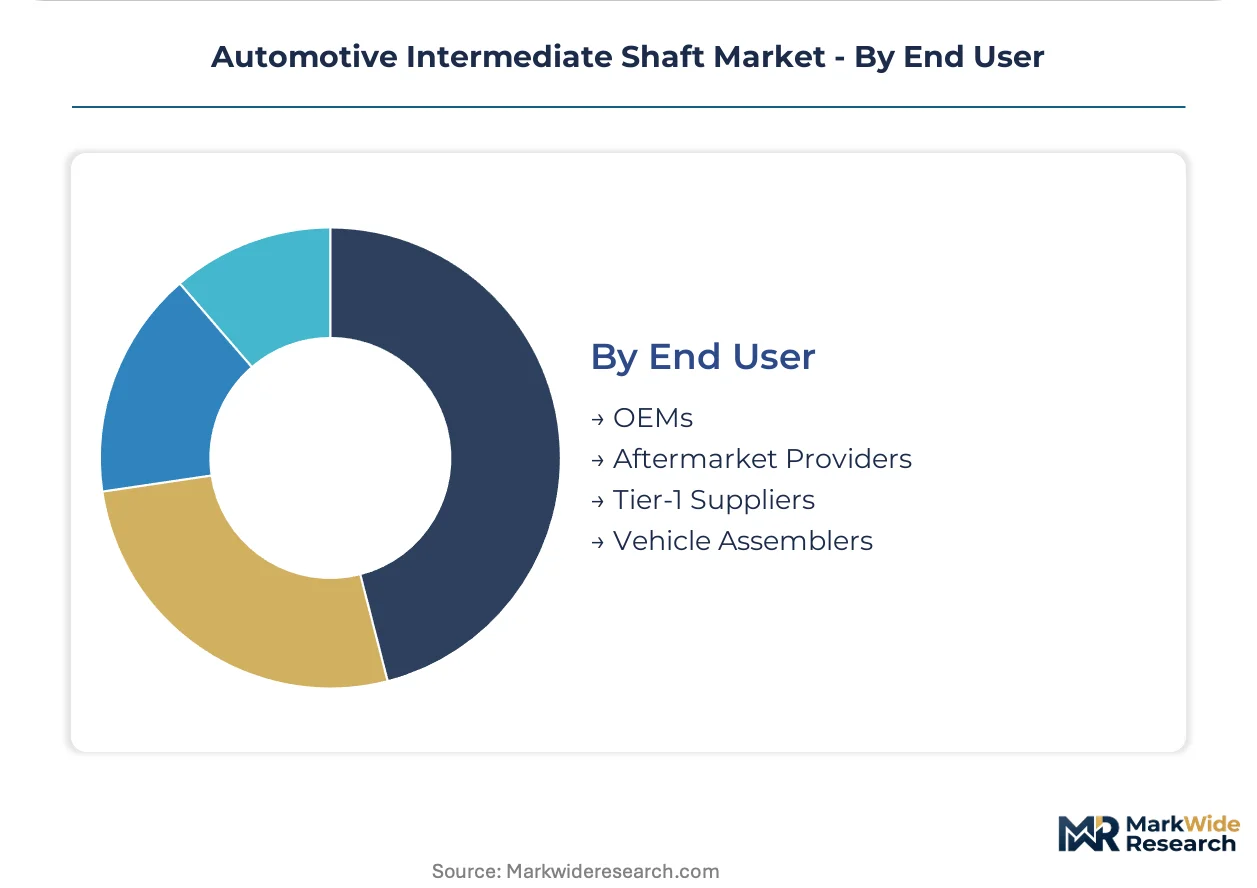
End User:
Supply chain position and integration depth determine procurement patterns, with captive production, tiered sourcing, and aftermarket replacement cycles creating distinct demand profiles.
- OEMs:Vehicle manufacturers with retained steering system capabilities specify intermediate shafts as part of integrated column assemblies, consolidating bearing, shaft, and joint procurement under single-source contracts.
- Tier-1 Suppliers:Specialized steering system integrators capture value across the full column assembly, with JTEKT Corporation and Nexteer Automotive leveraging electromechanical power steering compatibility to expand shaft specification influence.
- Vehicle Assemblers:Contract manufacturers and emerging EV specialists rely on external shaft sourcing, creating opportunities for modular suppliers offering pre-validated collapsible designs.
- Aftermarket Providers:Replacement shaft demand tracks vehicle age distribution and collision repair frequency, with independent distributors serving aging manual transmission fleets in developing markets.
Tier-1 Suppliers command the largest addressable value pool. Aftermarket Providers expand most quickly as global vehicle parc ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Light vehicle production volumes concentrate intermediate shaft demand in three manufacturing powerhouses. Regulatory divergence between NHTSA impact standards and ECE R12 occupant protection rules shapes supplier engineering footprints across these jurisdictions.
United States
Domestic OEMs retain substantial steering column assembly capacity, sustaining captive intermediate shaft production. NHTSA FMVSS 203 and 204 mandates drive collapsible segment integration into new platform designs. Detroit-area suppliers cluster around Michigan assembly plants serving full-size truck and SUV programs.
China
Joint-venture partnerships between global Tier-1s and domestic OEMs dominate specification influence. MIIT fuel consumption standards accelerate aluminum shaft adoption in mass-market hatchback segments. Yangtze River Delta forging clusters supply Shanghai-based vehicle assemblers with hollow-forged geometries.
Germany
Premium SUV and performance vehicle platforms sustain demand for high-torsional-stiffness hollow steel shafts. EU Green Deal recyclability incentives favor aluminum and polymer composite sourcing decisions. Bavarian engineering centers coordinate dual-homologation validation for NHTSA and UNECE jurisdictions.
Japan
Keiretsu-affiliated suppliers maintain backward integration into bearing and joint manufacturing. METI carbon neutrality roadmaps shape material selection for export-oriented platforms. Nagoya-area production clusters serve Toyota and Honda electromechanical steering convergence programs.
India
Cost-sensitive compact vehicles retain manual transmission configurations with solid steel shaft specifications. BIS safety standards are converging toward global impact absorption norms, creating upgrade potential. Tamil Nadu and Gujarat assembly corridors attract modular shaft suppliers offering pre-validated designs.
Automotive Intermediate Shaft Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated steering system suppliers commanding premium positioning over discrete component vendors. The vendor base concentrates around bearing-to-shaft manufacturing architectures and hollow-forging expertise. Three archetypes dominate: integrated column assemblers, forged shaft specialists, and electromechanical compatibility enablers. Capacity expansion and strategic partnerships represent the dominant competitive moves as electrification platforms reshape procurement consolidation.
Among integrated column assemblers, JTEKT Corporation, GKN Automotive, and Nexteer Automotive exemplify the bearing-to-shaft manufacturing architecture that captures value across full steering assemblies. These companies occupy positions where electromechanical power steering compatibility and collapsible design integration create bundled value propositions beyond commodity torque transmission. Their geographic footprints span Japanese, European, and North American engineering centers respectively.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Aisin Seiki |
| GKN Automotive |
| American Axle & Manufacturing |
| Schaeffler AG |
| Magna International |
| ZF Friedrichshafen AG |
| Nexteer Automotive |
| Dana Incorporated |
| Others |
Value Chain & Pricing Dynamics
Hollow-forging specialists concentrated in Germany's Bavarian industrial corridor command wage premiums that widen spreads between premium hollow-steel shafts and economy solid-steel alternatives. Labor-cost differentials between these high-skill forging clusters and emerging-market stamping operations drive three-tier pricing stratification across OEM procurement portfolios.
Pricing Analysis
Volume-mass market solid-steel shafts for manual transmission platforms generate thin margins at high throughput, while low-volume CFRP torque tubes for motorsport-derived platforms capture substantial premiums. Pricing stratifies across premium, standard, and economy tiers based on torsional stiffness certification grades and hollow-forging complexity. Cost compression in aluminum shaft categories is intensifying because LME commodity swings expose margin structures. Fleet procurement managers at mass-market OEMs exhibit highest price sensitivity, whereas performance vehicle divisions at German and Italian manufacturers demonstrate lowest sensitivity to per-unit cost.
Supply Chain Analysis
Specialty bearing steel supply rests on Swedish and Japanese integrated steel producers with vacuum-degassed ingot capabilities. Raw material feeds from medium-carbon alloy billets, precision-forged blanks, and carbon fiber prepreg tapes anchor tiered input cost structures. Single-source vulnerability concentrates in hollow-forging press capacity controlled by a narrow supplier base in Germany and Japan. Distribution runs through Tier 1 steering system integrators who bundle shaft procurement with bearing and joint assemblies under single-source contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as steer-by-wire displacement timelines compress mechanical content per vehicle and force sub-scale forgers into exit decisions.
For Market Incumbents: Cement backward integration into bearing manufacturing to capture value across full steering column assemblies and defend against electromechanical steering convergence programs at Nexteer and JTEKT. Prioritize collapsible design certification investment to maintain specification influence as NHTSA FMVSS 203/204 mandates tighten. Lock in long-term offtake agreements with Yangtze River Delta forging clusters to secure hollow-forging capacity ahead of platform consolidation waves. For New Entrants and Emerging Players: Contract vehicle assemblers in India's Tamil Nadu corridor represent the most penetrable buyer archetype as BIS safety standards converge toward global impact absorption norms. Target modular shaft suppliers offering pre-validated collapsible designs to emerging EV specialists lacking in-house steering engineering. Pursue aluminum shaft qualification for European hatchback platforms facing EU Green Deal recyclability mandates as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with hollow-forging specialists possessing dual-homologation capabilities given ECE R12 and NHTSA regulatory convergence compressing development timelines for multinational OEMs. Focus acquisition screening on mid-tier forgers with sub-0.5-degree-per-meter metrology capabilities and existing relationships with German premium SUV platforms. Watch steer-by-wire platform announcements at major OEMs as the critical inflection signal for mechanical shaft demand destruction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces qualification overhead for Tier 1 suppliers serving multiple OEM electrification programs. |
| Backward Integration into Bearing Manufacturing | JTEKT Corporation's architecture captures bundled value across full steering column assemblies. |
| Geographic Manufacturing Footprint Expansion | Yangtze River Delta clusters serve Shanghai-based assemblers with hollow-forged geometries. |
| Software-Defined Vehicle Investment | Steer-by-wire compatibility matrices reshape R&D allocation toward position encoder integration. |
| Long-term Supply Agreement | Secures hollow-forging press capacity ahead of dual-clutch transmission proliferation in premium SUVs. |
Study Parameters
Multi-period observation of vehicle production volumes, transmission architecture shifts, and steering system electrification timelines anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and hollow-forging plant managers. Secondary validation drew from NHTSA FMVSS filings, ECE R12 regulatory databases, IHS Markit vehicle registration data, and MIIT fuel consumption standard disclosures. Bottom-up shaft demand modeling triangulated against top-down steering system market sizing.
Input-output matrices mapped transmission category penetration rates to shaft content per vehicle across manual, dual-clutch, automatic, and CVT architectures. Segmentation dimensions modeled included vehicle class, propulsion architecture, material platform, and regional production cluster. CAGRs were derived from regression analysis of historical production correlations and forward projection of OEM platform electrification roadmaps. Industry-specific forecast inputs incorporated NHTSA regulatory compliance timelines and EU Green Deal material incentive structures.
Revisions become necessary when steer-by-wire platform announcements accelerate, aluminum price volatility exceeds historical bands, or dual-homologation burdens shift regulatory compliance costs disproportionately. Forecasts reflect documented assumptions regarding OEM electrification pacing and transmission architecture mix evolution. A small set of triggers—steer-by-wire deployment velocity, LME aluminum price regimes, and BIS safety standard convergence timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Gear Oil Market
Powertrain
Clutch Hub Puller Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Automotive Carburetor Market
Powertrain
Automotive Power Modules Market
Powertrain
North America Precision Gearbox Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Timing Belt Market
Powertrain
Small Gas Engine Market
Powertrain
Transmission Control System Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Global Automotive Pumps Market