
 Motor Vehicle Carburetors Market | 2026-2036
Motor Vehicle Carburetors Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Vehicle Carburetors Market Insights
ISO 9001 quality management certification is unwinding as a baseline gate for carburetor suppliers seeking OEM contracts in regulated markets. Holley Performance Products leverages its vertically integrated foundry operations to control casting tolerances for racing applications. Mikuni Corporation anchors its position through sustained dominance in motorcycle and powersport carburetion across Asian manufacturing clusters.
A motor vehicle carburetor is a mechanical device that blends air and fuel in precise ratios for internal combustion engines, typically employing venturi tubes, throttle plates, and adjustable jets to meter flow across operating conditions. Its primary commercial purpose remains supplying controlled air-fuel mixtures to spark-ignition engines in applications where electronic fuel injection retrofit costs prove prohibitive. Multiple barrel configurations command the highest margin pools in racing and performance segments, while electronic carburetors represent the fastest-growing category as suppliers integrate primitive electronic controls to meet tightening emissions protocols. Vintage car applications sustain steady demand from collectors and restoration specialists who prioritize period-correct components over modern substitutes.
EPA tailpipe standards and the EU F-Gas Regulation constrain hydrocarbon evaporative emissions from carbureted engines, forcing suppliers to redesign float bowls and accelerator pump circuits. CARB executive orders in California create a parallel compliance track that fragments product certification requirements across North American distribution channels. Stakeholders must monitor whether emerging economy regulators adopt Euro 6-equivalent standards that would accelerate electronic carburetor substitution or preserve grandfathering provisions protecting existing vehicle fleets.
Market Dynamics
The motor vehicle carburetors market faces a structural compression between tightening emissions mandates and persistent aftermarket demand from legacy vehicle fleets unable to absorb electronic fuel injection retrofit costs.
Growth Catalysts
- Vintage restoration demand:Collector communities in Germany and the United States are expanding purchases of period-correct replacement carburetors for pre-1990 vehicle fleets, sustaining manufacturing volumes for specialized suppliers.
- Brazilian aftermarket rebuild activity:Aging vehicle populations across São Paulo and Rio de Janeiro service corridors are concentrating demand for carburetor rebuild kits and remanufactured units in independent repair channels.
- Euro 6 regulatory grandfathering:Provisions protecting existing vehicle registrations from retrofit mandates are preserving legal operating status for carbureted engines in select EU member state implementations.
Market Restraints
- Electronic fuel injection substitution:Port and direct injection systems are capturing new powertrain allocations as OEMs prioritize compliance with EPA Tier 3 and Euro 6d tailpipe standards.
- Zinc and aluminum alloy volatility:Die-cast carburetor body production faces margin pressure from fluctuating base metal commodity costs concentrated in Chinese smelter output.
- Foundry capacity concentration:Gravity-cast component supply clusters in Shandong and Guangdong provinces create geographic single-point vulnerability for tier-two carburetor assemblers.
Strategic Opportunities
- Mexican light commercial aftermarket:Aging pickup and delivery vehicle fleets in Guadalajara and Monterrey industrial corridors present underserved demand for replacement carburetion hardware.
- Electronic carburetor convergence:Integration of solenoid-controlled metering rods with traditional venturi architectures enables primitive closed-loop fuel trimming without full EFI conversion expense.
- Direct-to-restorer digital channels:Specialized e-commerce platforms are disintermediating traditional distributor networks for vintage carburetor sourcing by individual collectors.
Industry Challenges
- Precision machining skill attrition:Venturi throat grinding and throttle shaft boring expertise is contracting as vocational programs pivot toward electronic system diagnostics.
- CARB executive order fragmentation:California Air Resources Board certification timelines for aftermarket carburetor applications vary unpredictably by engine family and model year.
- Legacy inventory integration:Remanufacturers struggle to match rebuilt unit specifications against sparse original manufacturer documentation for discontinued engine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Vehicle Carburetors Market |
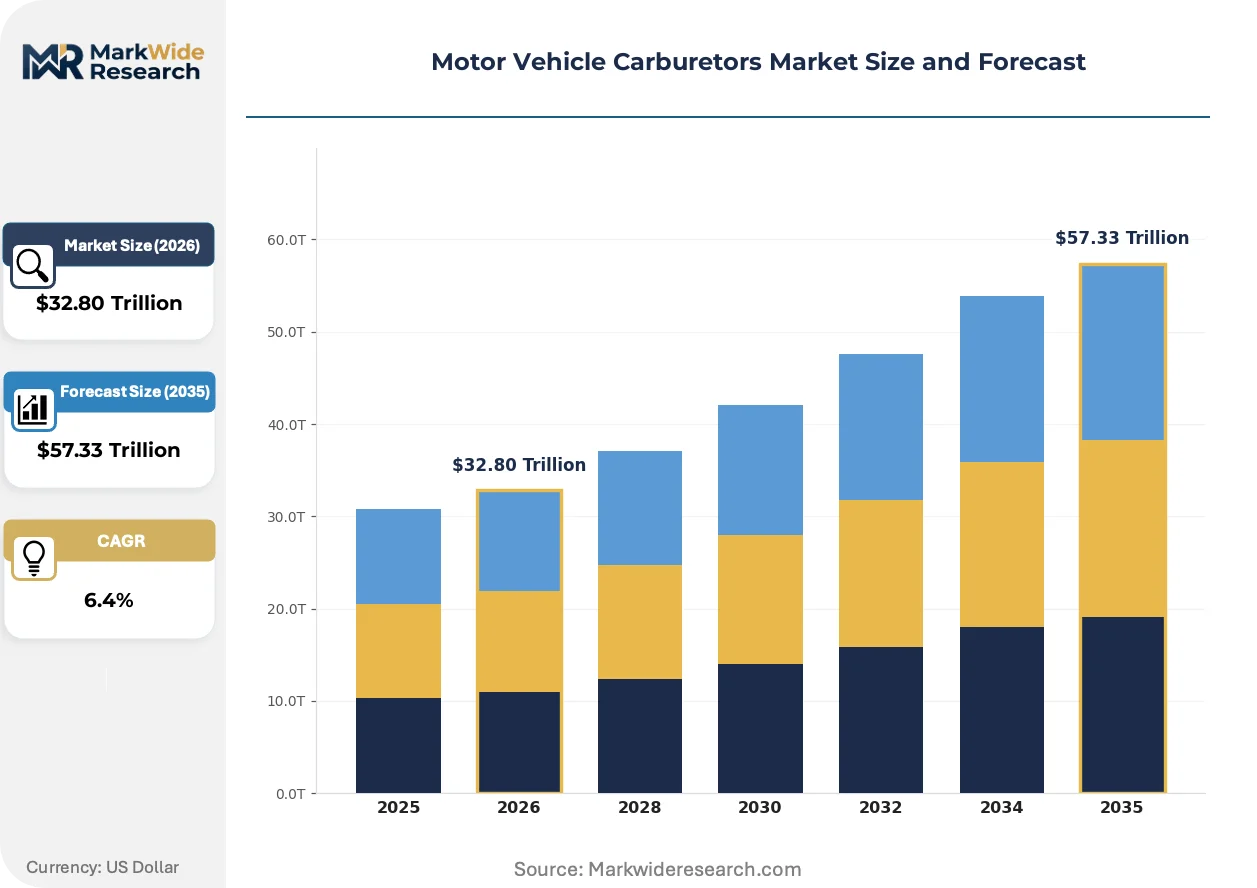
| Market Size in 2026 | $32.80 Trillion |
| Market Size in 2035 | $57.33 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Barrel, Double Barrel, Multiple Barrel, Electronic Carburetor Application: Passenger Vehicles, Commercial Vehicles, Racing Vehicles, Vintage Cars Fuel Type: Gasoline, Ethanol, Methanol, Diesel End User: OEMs, Aftermarket Suppliers, Repair Shops, Collectors |
| Companies Covered | Holley Performance Products, Edelbrock, Mikuni Corporation, Keihin Corporation, Zama Group, Walbro, Dell'Orto, Zhanjiang Deni, Fujian FuDing JingKe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Vehicle Carburetors Market Trends and Innovations
Carburetor technology is bifurcating between heritage-preserving mechanical precision and emissions-compliant electronic augmentation, with innovation investment flowing disproportionately toward hybrid architectures.
Electronically controlled carburetors are displacing purely mechanical units in emerging economy markets where regulators are adopting Euro 6-equivalent standards without full EFI infrastructure. These systems employ oxygen sensor feedback to trim air-fuel mixtures through solenoid-actuated metering rods, enabling compliance at one-third the cost of port injection retrofits. Motorcycle and small displacement automotive manufacturers in India and Southeast Asia are adopting this architecture fastest, compressing demand for conventional fixed-jet designs in price-sensitive segments.
EPA enforcement of evaporative emissions standards under 40 CFR Part 1060 is forcing redesign of float bowl venting and accelerator pump circuits across all carbureted engine categories. The regulation mandates sealed fuel systems with carbon canister purge control, compelling suppliers to engineer mechanical vacuum-operated purge valves compatible with existing carburetor architectures. Small engine and powersport manufacturers serving the US market are absorbing the largest compliance burden, redirecting R&D resources from performance optimization to evaporative control integration.
Collector procurement patterns are fragmenting across specialized digital marketplaces and restoration-focused subscription services that aggregate rare carburetor core inventory. These channels are replacing traditional brick-and-mortor speed shop networks for vintage Ford, Chevrolet, and Porsche applications, with transaction velocity concentrating in Germany and the United States where registered historic vehicle populations are largest. Restoration specialists now prioritize documented provenance and matching-number authenticity over price optimization, reshaping supplier value propositions toward archival documentation services.
Motor Vehicle Carburetors Market Segmentation
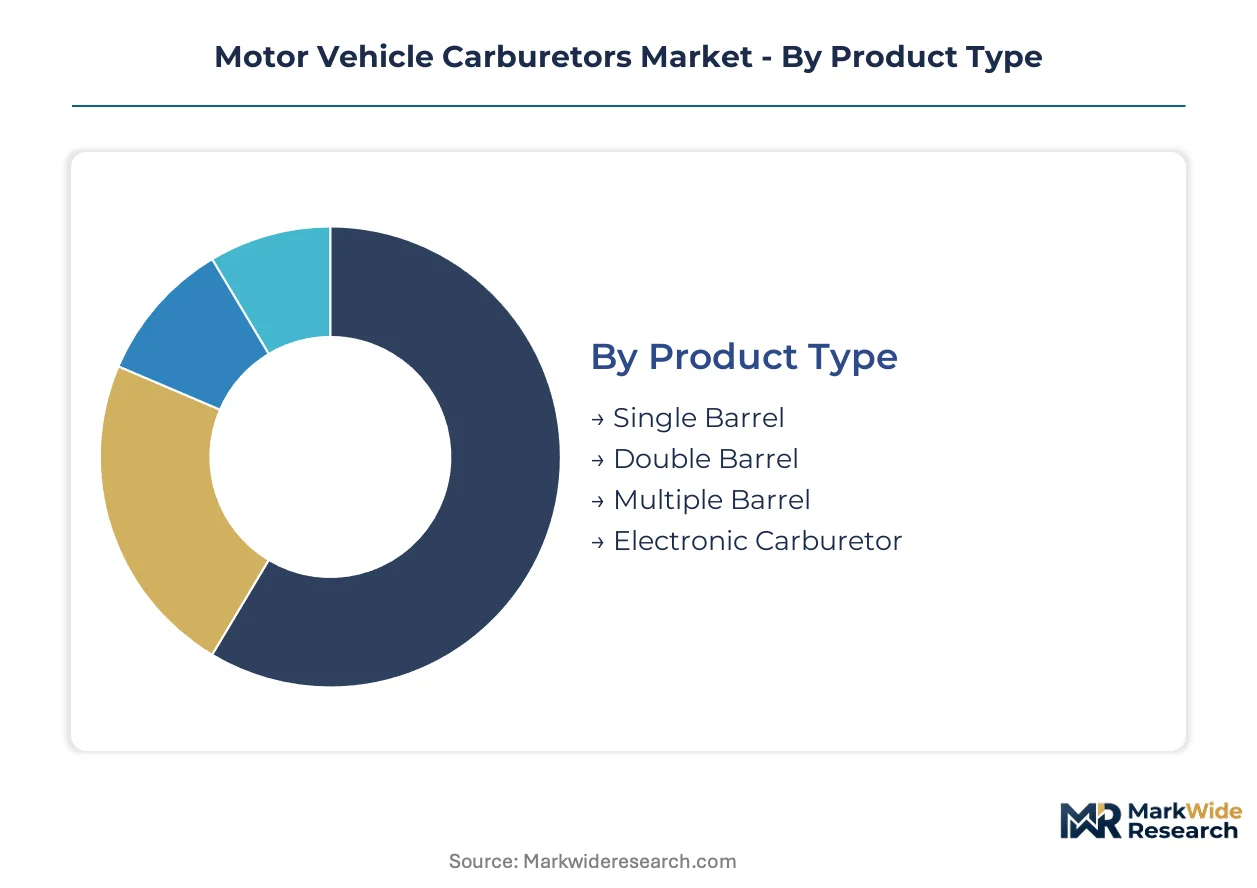
Carburetor market segmentation reveals how regulatory pressure and application-specific performance requirements fragment manufacturing priorities across product architectures. Each dimension—product type, application, fuel compatibility, and end-user channel—carries distinct compliance burdens and margin structures that reshape supplier investment allocation.
Product Type:
EPA Tier 3 and Euro 6 tailpipe standards are bifurcating R&D investment between heritage mechanical architectures and electronically augmented designs.
- Multiple Barrel:These configurations employ synchronized venturi throats and independent metering circuits to deliver high-flow air-fuel mixtures under variable load conditions. Racing and performance segments in the United States concentrate demand for these units, where CARB executive order compliance adds certification cost but preserves legal street operation. Multiple barrel handles the majority of throughput; electronic carburetor is the fastest mover on share.
- Electronic Carburetor:Solenoid-controlled metering rods receive oxygen sensor feedback to enable primitive closed-loop fuel trimming without full EFI conversion expense. Indian and Southeast Asian motorcycle manufacturers are adopting this architecture fastest as regulators adopt Euro 6-equivalent standards without complete injection infrastructure.
- Single Barrel:Fixed-venturi designs with single throttle plates serve cost-sensitive small-displacement applications where mechanical simplicity outweighs efficiency optimization.
- Double Barrel:Progressive linkage systems activate secondary barrels under load, balancing cruise economy against acceleration response in light commercial and passenger applications.
Mechanical variants retain volume leadership in price-sensitive emerging markets; electronically controlled units are expanding most quickly in jurisdictions adopting stringent emissions protocols.
Application:
End-use concentration varies sharply by vehicle age, with regulatory grandfathering provisions protecting certain fleet segments from retrofit mandates.
- Vintage Cars:Period-correct carburetors for pre-1990 vehicle fleets demand exacting reproduction of original casting numbers, venturi specifications, and throttle linkage geometry. Collector communities in Germany and the United States sustain this segment, where documented provenance commands premium pricing over functional equivalence. Vintage cars anchor margin pools; racing vehicles are gaining share fastest.
- Racing Vehicles:Unlimited-class competition applications prioritize flow bench performance and tunability over emissions compliance, with venturi throat machining tolerances measured in thousandths of an inch.
- Passenger Vehicles:Aging fleet maintenance in Brazil and Mexico concentrates demand for replacement and remanufactured units where EFI retrofit costs exceed vehicle residual value.
- Commercial Vehicles:Light pickup and delivery fleets in Guadalajara and Monterrey industrial corridors present underserved replacement demand for durable carburetion hardware.
Restoration applications dominate value capture; racing and performance segments show the steepest expansion trajectory in specialized supplier revenue.
Fuel Type:
Material compatibility and jet calibration requirements fragment manufacturing specifications across regional fuel supply variations.
- Gasoline:Conventional hydrocarbon formulations remain the baseline calibration for most carburetor architectures, with ethanol tolerance now standard in North American and Brazilian specifications.
- Ethanol:Corrosion-resistant alloys and modified elastomer seals address hygroscopic fuel behavior in Brazilian flex-fuel applications and US midwestern markets with E85 infrastructure.
- Methanol:Racing applications demand enlarged jet orifices and anodized aluminum components to handle oxygenated fuel's increased volume requirements and corrosive combustion byproducts.
- Diesel:Specialized carburetor variants for small compression-ignition engines employ heated intake manifolds and glow plug integration, serving agricultural and industrial equipment segments outside highway regulatory scope.
Gasoline-compatible hardware moves the largest unit volumes; ethanol-tolerant designs are climbing the fastest as biofuel mandates expand.
End User:
Channel structure determines certification burden and technical support requirements, with direct-to-restorer platforms disrupting traditional distribution economics.
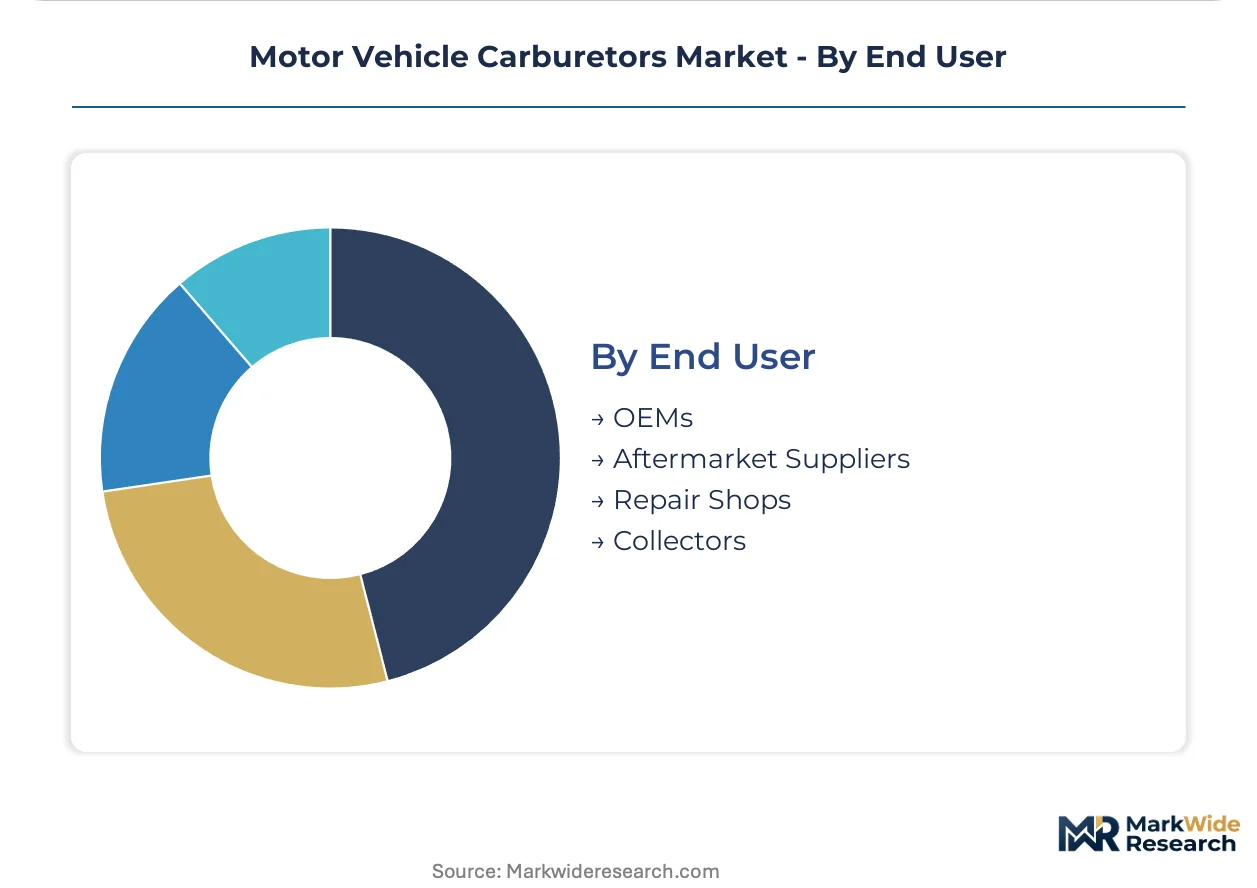
- Aftermarket Suppliers:Independent distributors and jobbers aggregate demand across fragmented repair channels, absorbing inventory risk for slow-moving legacy applications. Brazilian rebuild corridors in São Paulo and Rio de Janeiro concentrate this activity, where remanufactured units compete against low-cost Asian imports. Aftermarket suppliers handle the majority of throughput; collectors are the fastest mover on share.
- Collectors:Individual restoration specialists now source through specialized digital marketplaces that disintermediate traditional speed shop networks, prioritizing matching-number authenticity over price optimization.
- OEMs:Original equipment contracts demand ISO 9001 quality management certification as baseline gate for regulated markets, with evaporative emissions compliance adding engineering validation cost.
- Repair Shops:Independent service bays in emerging economies sustain rebuild kit demand, where labor cost economics favor jet replacement and float adjustment over complete unit substitution.
Aftermarket channels dominate transaction velocity; direct collector procurement is expanding most quickly as digital platforms fragment traditional distributor control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe standards and Euro 6 grandfathering provisions are redistributing carburetor demand toward jurisdictions preserving legacy vehicle operating rights. Brazil's aging fleet sustains rebuild activity while Germany's restoration economy commands premium pricing for period-correct components.
United States
CARB executive orders fragment aftermarket certification across California and federal channels, preserving parallel compliance tracks. EPA 40 CFR Part 1060 evaporative emissions enforcement forces float bowl redesigns for small engine manufacturers. Vintage restoration clusters in Southern California and the Midwest concentrate collector demand for pre-1990 Ford and Chevrolet applications.
Germany
KBA historic vehicle registration provisions protect carbureted engine operating status under Euro 6 implementation variants. The EU F-Gas Regulation constrains hydrocarbon evaporative emissions from classic car fleets. Restoration specialists in Bavaria and Baden-Württemberg source matching-number carburetors through specialized digital marketplaces disintermediating traditional distributors.
Brazil
ANVISA flex-fuel compatibility mandates drive ethanol-tolerant carburetor specifications for aging passenger and light commercial fleets. Prolonged vehicle lifecycles in São Paulo and Rio de Janeiro service corridors sustain independent rebuild kit demand. Remanufactured units compete against low-cost Asian imports in price-sensitive aftermarket channels.
India
BIS emission standards adoption without full EFI infrastructure accelerates electronic carburetor penetration in motorcycle manufacturing. PLI scheme incentives for automotive component localization reshape supplier investment toward domestic assembly. Tamil Nadu and Maharashtra industrial corridors concentrate two-wheeler OEM sourcing for solenoid-controlled metering architectures.
Mexico
Foundry capacity in Guadalajara and Monterrey industrial corridors supplies light commercial aftermarket replacement demand. NOM emissions standards for legacy pickup fleets preserve carburetor relevance where EFI retrofit economics fail. Independent repair channels absorb inventory risk for slow-moving legacy applications across northern border states.
Motor Vehicle Carburetors Market Competitive Landscape
Listed leaders compete with private specialists across certification and heritage authenticity dimensions. The vendor base stratifies between vertically integrated foundry operators, heritage-brand restoration suppliers, and emerging economy volume manufacturers. Three archetypes dominate: integrated casting-to-assembly specialists, heritage-brand authenticity purveyors, and cost-optimized emerging market fabricators. Competitive moves concentrate on backward integration into foundry operations and direct-to-restorer digital channel construction.
Among heritage-brand specialists, Holley Performance Products and Edelbrock occupy positions emphasizing period-correct authenticity for United States collector markets. Mikuni Corporation anchors the Asian manufacturing cluster archetype, representing sustained dominance in motorcycle and powersport carburetion. Keihin Corporation exemplifies the transition pathway from mechanical to electronically augmented architectures, reflecting broader industry bifurcation between heritage preservation and emissions compliance.
| Leading Market Players |
|---|
| Holley Performance Products |
| Edelbrock |
| Mikuni Corporation |
| Keihin Corporation |
| Zama Group |
| Walbro |
| Dell'Orto |
| Zhanjiang Deni |
| Fujian FuDing JingKe |
| Others |
Pricing and Supply Chain Analysis
Foundry scale economies in Shandong and Guangdong provinces concentrate casting capacity among vertically integrated operators, compressing price floors for tier-two assemblers while elevating margin capture for integrated specialists serving CARB-certified aftermarket channels.
Pricing Analysis
Certification level creates the primary spread across the motor vehicle carburetors market, with EPA 40 CFR Part 1060 and CARB executive order compliance adding substantial validation cost to premium tiers. Pricing stratifies across heritage authenticity, emissions-compliant electronic architectures, and economy rebuild specifications. Cost compression in economy carburetor rebuild kits is intensifying because low-cost Asian imports flood Brazilian and Mexican aftermarket channels. Vintage collectors in Germany and the United States exhibit the lowest price sensitivity, prioritizing documented provenance and matching-number authenticity over functional equivalence.
Supply Chain Analysis
Inventory lead times for gravity-cast carburetor bodies extend disproportionately when Shandong and Guangdong foundry capacity faces seasonal utilization spikes. Supply concentrates in China for die-cast zinc and aluminum alloy components, with secondary machining clusters in India and Mexico. Raw material dependencies rest on zinc ingot pricing from Chinese smelter output, aluminum alloy formulations, and corrosion-resistant elastomer seals for ethanol-tolerant specifications. Single-source vulnerability persists in Shandong gravity-casting capacity for venturi throat precision. Distribution runs through independent jobber networks in Brazil and specialized digital marketplaces disintermediating traditional speed shops for vintage applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory grandfathering provisions and restoration authenticity requirements is creating defendable niche positions for specialists who anchor in heritage documentation or emissions-compliant hybrid architectures.
For Market Incumbents: Secure backward integration into captive foundry operations to control casting tolerances for racing and restoration applications against margin pressure from low-cost Asian imports. Prioritize ISO 9001 certification maintenance as baseline gating for OEM contract retention amid evaporative emissions redesign requirements. Defend position by building proprietary digital channels that disintermediate traditional distributor networks for collector procurement. For New Entrants and Emerging Players: Anchor in Mexican light commercial aftermarket corridors where aging pickup fleets in Guadalajara and Monterrey present underserved replacement demand. Target electronic carburetor assembly for Indian motorcycle OEMs adopting BIS emission standards without full EFI infrastructure conversion. Pursue direct-to-restorer marketplace positioning that aggregates rare carburetor core inventory with archival documentation services. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage-brand restoration suppliers with proprietary digital channels and documented provenance capabilities. Long-term viability over a multi-year window favors specialists with backward integration into foundry operations and regulatory certification expertise rather than pure-play assemblers. Monitor electronic fuel injection substitution rates in emerging economies as the critical inflection signal for carburetor demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive casting capacity secures venturi throat tolerances for CARB-certified racing applications. |
| Digital Marketplace Construction | Direct-to-collector platforms disintermediate traditional speed shop distribution in Germany and the United States. |
| Electronic Carburetor Architecture Development | Solenoid-controlled metering enables Euro 6-equivalent compliance without full EFI conversion expense. |
| Heritage Documentation Service Expansion | Archival provenance capabilities command premium pricing from matching-number authenticity collectors. |
| Brazilian Rebuild Kit Localization | ANVISA flex-fuel compatibility specifications anchor position in ethanol-tolerant aftermarket segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with restoration specialists, aftermarket distributors, foundry operations managers, and OEM procurement leads. Secondary validation drew from EPA 40 CFR Part 1060 regulatory filings, CARB executive order databases, KBA historic vehicle registration statistics, and ANVISA flex-fuel compatibility mandates. Bottom-up volume estimates from country-level fleet age demographics were triangulated against top-down value projections from trade flow analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product architecture, application category, fuel compatibility specification, and end-user channel structure. CAGRs were derived from regression analysis of historical replacement rates against regulatory phase-in schedules and fleet turnover dynamics. Industry-specific inputs incorporated zinc and aluminum alloy commodity price trajectories, evaporative emissions compliance cost curves, and electronic fuel injection substitution elasticity estimates.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory grandfathering provisions and stable vintage vehicle registration growth; material deviation in emissions mandate enforcement or collector demographic shifts would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Brazil Automotive Market
Powertrain
Global Automotive Pumps Market
Powertrain
Automotive Crank Trigger Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Torque Converter Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Axle Shaft Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Racing Clutches Market
Powertrain
South America Automotive Market
Powertrain
EGR and Emissions Control Actuator Systems Market