
 Automotive Retrofit Electric Vehicle Powertrain Market | 2026-2036
Automotive Retrofit Electric Vehicle Powertrain Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Retrofit Electric Vehicle Powertrain Market Outlook
The pricing gap between premium heritage-vehicle conversions and mass-market commuter retrofits is rebalancing as battery pack costs compress the middle tier. Continental leverages its Tier-1 supplier relationships to dominate OEM-adjacent fleet conversions. Electrogenic specializes in bespoke classic-car electrification, anchoring the high-margin heritage segment with proprietary integration protocols. Altigreen Propulsion Labs competes on cost-engineered motor kits for light commercial vehicles across South Asian markets.
Automotive retrofit electric vehicle powertrain systems replace internal combustion engines with electric motor-battery-controller architectures, typically delivering 50-400 kW output through purpose-designed mounting subframes and CAN-bus integrated control electronics. The primary purpose is extending vehicle service life while eliminating tailpipe emissions and reducing total cost of ownership for fleet assets. Complete powertrain solutions capture the largest margin pools as they bundle installation, calibration, and warranty liability, whereas motor kit segments attract price-sensitive aftermarket providers seeking modular upgrade paths. Battery pack configurations using Li-ion chemistry currently lead volume shipments, though solid-state technology positions for premium applications demanding higher energy density.
The EU Green Deal and REACH chemical compliance frameworks govern battery material sourcing and end-of-life recycling obligations across European conversion workshops. The EPA and NHTSA in the United States set crashworthiness and emissions-equivalency standards that determine street-legality for converted vehicles. Stakeholders must monitor how divergent national homologation pathways affect cross-border kit certification and service network scalability.
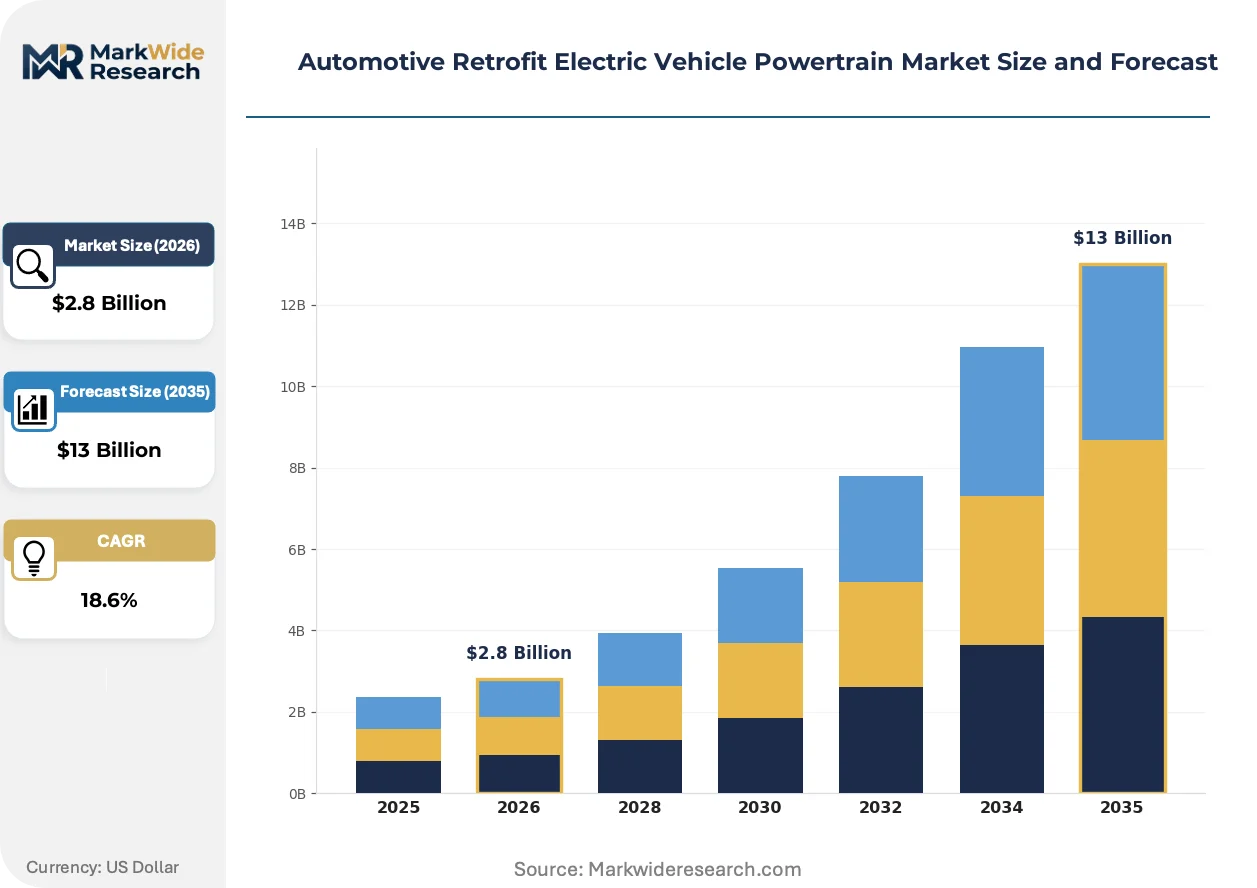
Market Dynamics
EU Green Deal mandates are compressing certification timelines for converted commercial fleets while battery pack standardization creates procurement leverage for high-volume retrofitters.
Growth Catalysts
- Fleet electrification mandates:Urban logistics operators face combustion-engine phaseout deadlines under EU Green Deal frameworks, forcing accelerated conversion schedules for last-mile delivery vans.
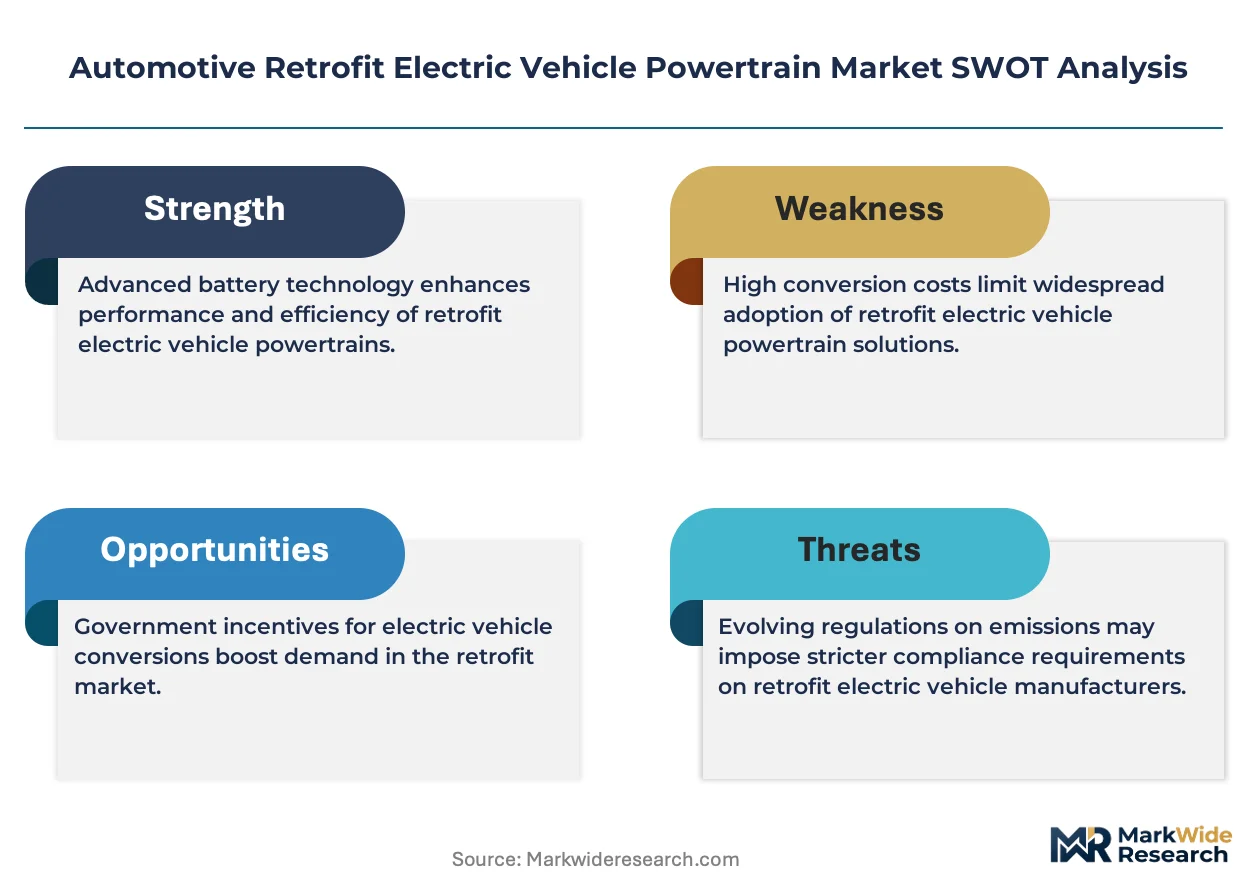
- Li-ion cost compression:Cell chemistry improvements and manufacturing scale are narrowing the total-cost-of-ownership gap versus diesel powertrains for high-mileage commercial assets.
- Germany:KBA homologation pathways provide regulatory clarity that attracts Tier-1 supplier investment and establishes template certification protocols adopted across neighboring markets.
Market Restraints
- Raw material concentration:Cobalt and lithium refining capacity clusters in China, exposing European conversion workshops to supply disruption and price volatility in battery pack procurement.
- Homologation fragmentation:Divergent national approval standards between Germany's KBA, France's DGCCRF-equivalent processes, and Italy's MOT requirements create cross-border kit certification friction.
- Structural warranty liability:Complete powertrain solutions carry 8-year battery performance guarantees that strain balance sheets of mid-cap retrofitters without OEM backing.
Strategic Opportunities
- Heritage vehicle electrification:Classic car collectors in the United Kingdom and Italy present premium-margin conversion demand for bespoke motor-battery integration with period-correct aesthetics.
- Second-life battery applications:Repurposed automotive cells from end-of-life EVs enable cost-engineered retrofit kits for price-sensitive light commercial segments in South Asian markets.
- Workforce retraining incentives:EU Social Climate Fund allocations support mechanic certification programs that expand installation capacity for independent conversion workshops.
Industry Challenges
- High-voltage technician scarcity:Certified electricians capable of 400V+ battery system installation command wage premiums that inflate labor costs for conversion workshops.
- Legacy CAN-bus integration:Proprietary vehicle communication protocols from pre-2010 commercial fleets require reverse-engineering that extends calibration timelines and voids manufacturer warranties.
- End-of-life recycling compliance:REACH battery material traceability obligations impose documentation burdens on small-scale retrofitters lacking established reverse-logistics partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Retrofit Electric Vehicle Powertrain Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Powertrain, Motor Kit, Battery Pack, Control System Technology: Li-ion, Solid State, Plug-in Hybrid, Regenerative Braking End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Vehicle Type: Passenger Cars, Commercial Vehicles, Buses, Light Trucks |
| Companies Covered | Electrogenic, Continental, Altigreen Propulsion Labs, Etrio, Robert Bosch, EV West, Bedeo, Electric GT, ZeroLabs Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Retrofit Electric Vehicle Powertrain Market Strategic Shifts
Digital twin simulation and modular platform architectures are compressing development cycles while regulatory pressure on embodied carbon reshapes material selection criteria across the conversion value chain.
Software-defined powertrain calibration is automating motor-controller mapping for heterogeneous vehicle platforms. Tier-1 suppliers deploy cloud-based parameter libraries that slash commissioning time from weeks to days. Fleet operators with standardized vehicle pools adopt this capability fastest, compressing project economics for high-volume retrofit contracts.
REACH chemical compliance frameworks now govern cobalt and nickel sourcing transparency for battery packs sold into European conversion markets. The regulation forces supply chain documentation upgrades that disadvantage small importers lacking established smelter relationships. German certification bodies have responded by publishing standardized material passport templates that streamline audit procedures for compliant retrofitters.
Service bundling is displacing component-only sales as the dominant commercial model. Fleet buyers now demand performance guarantees covering battery state-of-health maintenance and residual value protection. This shift concentrates contract wins with retrofitters possessing captive service networks, squeezing pure-play kit manufacturers toward white-label partnerships with established workshop chains.
Automotive Retrofit Electric Vehicle Powertrain Market Segmentation
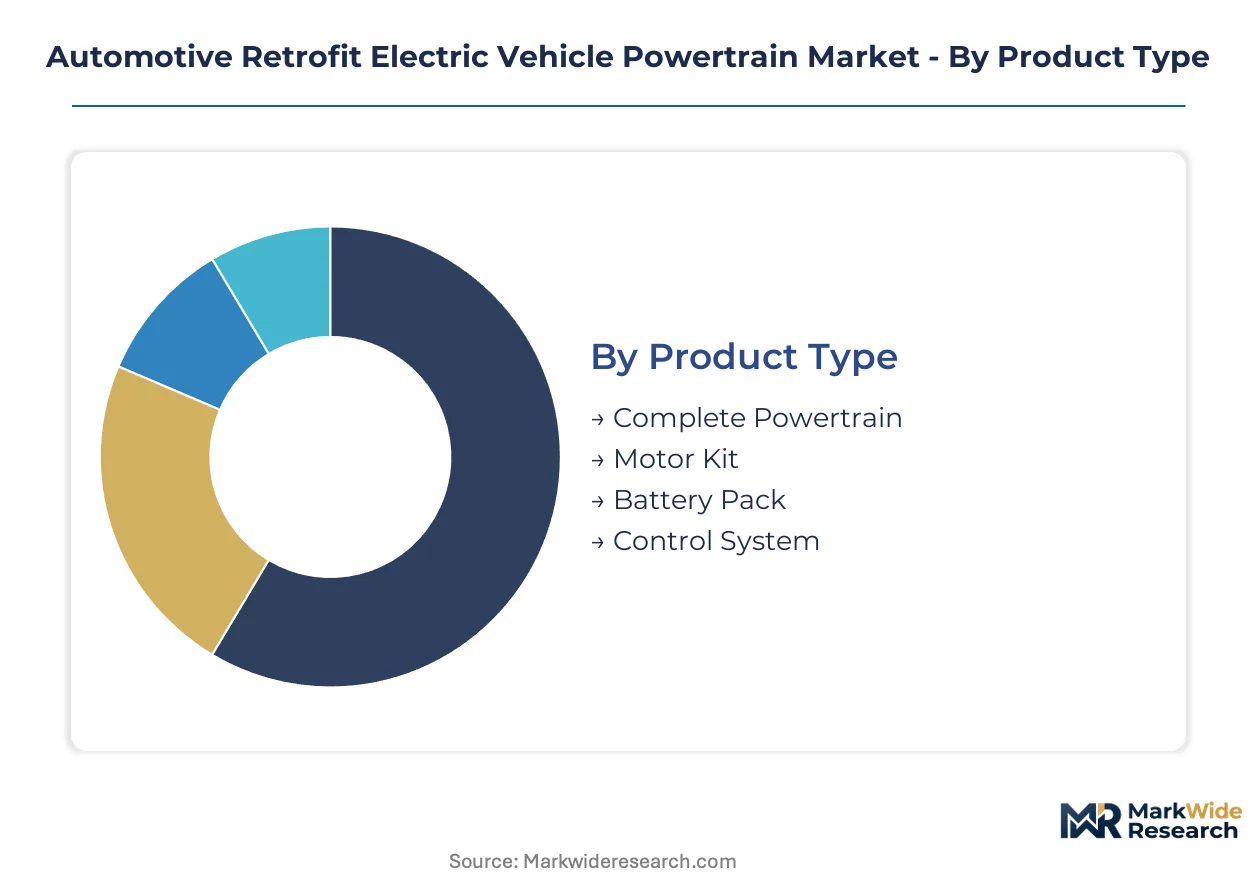
Retrofit powertrain purchasing decisions split sharply between fleet procurement teams seeking total-cost optimization and heritage collectors prioritizing bespoke integration quality. Segment boundaries are blurring as battery pack standardization enables kit manufacturers to compete across multiple vehicle categories.
Product Type:
Fleet procurement teams weigh upfront capital commitment against warranty coverage depth when selecting system completeness tiers.
- Complete Powertrain:Bundled motor-battery-controller architectures with installation, calibration, and 8-year performance guarantees. German logistics fleets favor these solutions for last-mile delivery vans under EU Green Deal compliance deadlines.
- Motor Kit:Modular drive unit assemblies requiring buyer-sourced battery integration. South Asian commercial operators select these for cost-engineered light truck conversions where local battery assembly reduces landed costs.
- Battery Pack:Li-ion cell modules with CAN-bus compatible battery management systems. Second-life automotive cells dominate price-sensitive retrofit applications.
- Control System:Motor controller units with vehicle-specific parameter mapping software. Demand concentrates among independent conversion workshops serving heritage vehicle collectors.
Complete Powertrain leads on scale; Control System gains share fastest through software-defined calibration automation.
Technology:
Energy density requirements and charging infrastructure maturity determine chemistry selection across application tiers.
- Li-ion:NMC and LFP cell chemistries delivering 150-300 Wh/kg energy density with established recycling pathways. Volume shipments dominate European commercial fleet conversions where REACH compliance mandates material traceability.
- Solid State:Ceramic electrolyte architectures promising 400+ Wh/kg density with enhanced thermal stability. Premium heritage conversions in Italy and the United Kingdom specify these for packaging constraints in classic vehicle chassis.
- Plug-in Hybrid:Retained combustion range-extender configurations for commercial routes lacking charging infrastructure.
- Regenerative Braking:Kinetic recovery systems integrated into motor controller firmware. Urban bus operators deploy these for stop-start route efficiency.
Li-ion leads on scale; Solid State climbs the fastest as cell manufacturing matures.
End User:
Contract structure preferences and technical integration capabilities segment buyer types sharply.
- Fleet Operators:High-volume procurement with standardized vehicle pools and captive service network requirements. Urban logistics operators across Germany accelerate conversion schedules under municipal combustion-engine restrictions.
- OEMs:Factory-authorized retrofit programs leveraging Tier-1 supplier relationships for warranty continuity.
- Aftermarket Providers:Independent conversion workshops serving heterogeneous vehicle fleets with reverse-engineered CAN-bus solutions.
- Individual Consumers:Heritage vehicle owners commissioning bespoke electrification with period-correct aesthetic preservation.
Fleet Operators lead on scale; Individual Consumers command steepest expansion trajectory as classic car electrification gains cultural traction.
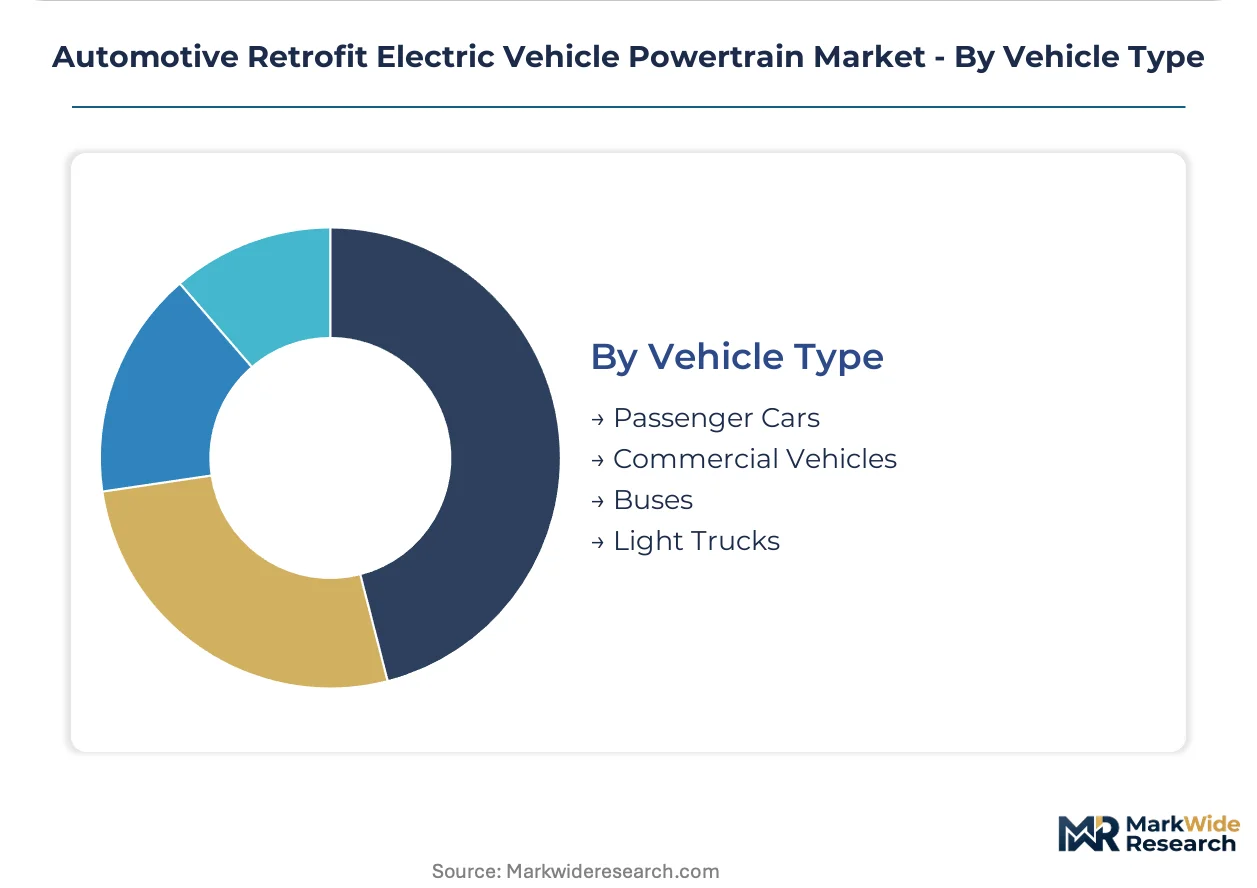
Vehicle Type:
Payload requirements and duty cycle intensity shape powertrain sizing and thermal management specifications.
- Commercial Vehicles:Light vans and medium-duty trucks with 100-200 kWh battery configurations for urban delivery routes. German parcel networks drive volume demand under KBA homologation clarity.
- Passenger Cars:Sedan and hatchback platforms receiving 50-150 kWh retrofits for commuter applications.
- Buses:Heavy-duty transit configurations with rooftop battery packaging and regenerative braking integration. Municipal operators in France specify these for depot-charged urban routes.
- Light Trucks:Pickup and utility vehicle platforms for mixed commercial-personal use across South Asian markets.
Commercial Vehicles lead on scale; Buses show strongest momentum through municipal electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA homologation framework attracts Tier-1 supplier investment that France's fragmented approval processes struggle to match. Fleet conversion demand concentrates where regulatory clarity intersects with established automotive supplier ecosystems.
Germany
Urban logistics operators accelerate last-mile van conversions under municipal combustion-engine restrictions. KBA certification pathways provide template protocols adopted across neighboring markets. Stuttgart and Munich host dense supplier clusters where Continental leverages OEM-adjacent relationships for fleet retrofit contracts.
United Kingdom
Classic car collectors commission bespoke electrification preserving period-correct aesthetics. The Driver and Vehicle Standards Agency maintains conversion safety standards aligned with EU frameworks. Oxfordshire and the Midlands concentrate heritage-vehicle specialists serving premium-margin demand.
France
Municipal bus operators specify depot-charged urban transit configurations with regenerative braking integration. DGCCRF-equivalent processes create certification friction versus German templates. Lyon and Paris transit authorities drive volume procurement for heavy-duty retrofit platforms.
India
Light commercial vehicle operators select cost-engineered motor kits where local battery assembly reduces landed costs. The Ministry of Road Transport and Highways develops retrofit safety standards for commercial fleets. Bangalore and Pune host propulsion system developers competing on price-optimized integration.
Italy
Heritage vehicle owners in Milan and Turin demand solid-state battery configurations for classic chassis packaging constraints. MOT requirements diverge from German KBA standards, complicating cross-border kit certification. Emilia-Romagna's automotive supplier base supports bespoke integration workshops.
Automotive Retrofit Electric Vehicle Powertrain Market Competitive Environment
Top-tier vendors anchor complete powertrain solutions with warranty-backed fleet contracts, while mid-cap specialists compete on modular motor kits for price-sensitive segments. The vendor base stratifies across three strategic archetypes: Tier-1 suppliers leveraging OEM relationships, heritage-vehicle boutiques commanding premium margins, and cost-engineered kit manufacturers serving emerging markets. Dominant competitive moves include backward integration into battery pack assembly and geographic expansion through certified installer networks.
Within the heritage-conversion tier, Electrogenic and ZeroLabs Automotive exemplify bespoke integration specialists anchoring high-margin collector demand. Continental occupies a position representing Tier-1 supplier archetypes with fleet-scale deployment capabilities. Altigreen Propulsion Labs sits within the cost-optimized segment serving South Asian commercial operators.
| Leading Market Players |
|---|
| Electrogenic |
| Continental |
| Altigreen Propulsion Labs |
| Etrio |
| Robert Bosch |
| EV West |
| Bedeo |
| Electric GT |
| ZeroLabs Automotive |
| Others |
Value Chain & Pricing Dynamics
Li-ion cell cathode materials trace a cost cascade from Chinese cobalt refineries through German conversion workshops to tiered buyer segments. REACH-mandated material passports add documentation overhead that separates premium-certified battery packs from gray-market alternatives.
Pricing Analysis
Capacity additions in South Korean cell manufacturing are reshaping price floors for NMC and LFP chemistries deployed in European fleet conversions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under KBA homologation versus uncertified motor kits. Cost compression in standard-tier battery packs intensifies as second-life automotive cells enter South Asian supply channels. Fleet operators in Germany demonstrate lowest price sensitivity due to EU Green Deal compliance deadlines, while independent workshops in India prioritize landed cost minimization above warranty depth.
Supply Chain Analysis
Cobalt and lithium hydroxide supply rests on Chinese refining infrastructure, South Korean precursor processing, and Australian hard-rock mining concessions. Battery pack assembly draws from Japanese BMS semiconductor suppliers and German thermal management component specialists. Single-source vulnerability concentrates in cathode active material production where Chinese state-owned enterprises control capacity expansion timelines. Distribution runs through Tier-1 supplier captive networks for complete powertrain solutions, whereas motor kits reach end-users via independent aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on battery pack cost-down curves and the premium-tier shift toward heritage vehicle collectors willing to pay for solid-state configurations.
For Market Incumbents: Lock in long-term cathode material offtake agreements with Chinese refineries to hedge cobalt price volatility threatening 8-year warranty coverage. Deepen backward integration into battery pack assembly to capture margin pools currently leaking to Korean cell suppliers. Defend against modular motor kit competitors by embedding proprietary CAN-bus calibration software that raises switching costs for fleet operators. For New Entrants and Emerging Players: Begin with second-life battery aggregation for light commercial retrofits in South Asian markets where incumbent warranty infrastructure remains underdeveloped. Target municipal bus operators in France seeking depot-charged configurations with regenerative braking integration. Pursue white-label partnerships with established German workshop chains rather than building captive service networks from scratch. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap retrofitters lack balance sheet capacity to underwrite 8-year battery performance guarantees demanded by fleet procurement teams. Acquisition target archetypes include heritage-vehicle boutiques with proprietary integration protocols and certified installer networks spanning multiple EU member states. Watch KBA homologation pathway adoption rates across Eastern European markets as inflection indicator for scalable kit certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode material contracts with Chinese refineries stabilize input costs for warranty-backed powertrain solutions. |
| Software-Defined Vehicle Investment | Cloud-based parameter libraries slash commissioning timelines from weeks to days for heterogeneous fleet conversions. |
| Platform Standardization | Modular motor-battery architectures enable kit manufacturers to compete across commercial van and light truck categories simultaneously. |
| Charging Infrastructure Partnership | Depot-charging collaborations with municipal transit authorities unlock heavy-duty bus retrofit contracts in France. |
| Geographic Manufacturing Footprint | Local battery assembly in Bangalore reduces landed costs for South Asian commercial operators selecting motor kit configurations. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operations directors grounded the qualitative foundation. Secondary validation drew from KBA homologation filings, EU Green Deal implementation documents, REACH compliance registries, and vehicle production databases. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmentation outputs reflect disaggregation by vehicle class, propulsion architecture, system completeness tier, and regional production cluster. CAGRs emerged from installed base modeling and replacement cycle analysis rather than extrapolation of historical growth rates. Forecast inputs incorporated Li-ion cell cost curves, municipal combustion-engine restriction timelines, and certified high-voltage technician supply constraints.
Several conditions sit outside the modeled scope, including unannounced solid-state cell manufacturing scale-up, abrupt REACH chemical restriction amendments, and geopolitical disruption of Chinese refining capacity. Forecasts reflect documented assumptions about regulatory continuity and material cost trajectories. A small set of named triggers warrants ongoing watch: KBA certification adoption outside Germany, second-life battery safety incident rates, and EU Social Climate Fund disbursement timing for mechanic retraining programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South America Automotive Market
Powertrain
Automotive Fuel Cock Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Crankshaft Oil Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Turbocharger Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
High Speed Engine Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Timing Belt Kits Market
Powertrain
Automotive Camshaft Market
Powertrain
Clutch Friction Plate Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Power Seat Adjustment Motor Market