
 Automotive Haptic Accelerator Pedal Market | 2026-2036
Automotive Haptic Accelerator Pedal Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Haptic Accelerator Pedal Market Analysis
ISO 26262 functional safety compliance is unwinding legacy mechanical pedal architectures across premium and mass-market vehicle platforms. Continental AG leverages its integrated braking and pedal systems portfolio to anchor European OEM supply chains. Robert Bosch GmbH sustains R&D intensity in electromechanical actuation for haptic feedback modules. KSR International dominates North American pedal assembly contracts through manufacturing scale and just-in-sequence delivery capabilities.
An automotive haptic accelerator pedal integrates force-feedback actuators, position sensors, and control electronics to communicate throttle response boundaries and driving efficiency cues to the operator through tactile sensation, typically operating with feedback resolution below 0.1 millimeter displacement and response latencies under 50 milliseconds. Adaptive and smart pedal variants are capturing margin pools as OEMs specify programmable resistance curves for eco-driving modes and autonomous handoff scenarios. Electromechanical technology leads unit volume while piezoelectric approaches compete on precision in luxury electric vehicle applications.
NHTSA accelerator control safety investigations and EPA emissions compliance requirements in the United States shape pedal system validation protocols, while EU type-approval frameworks under UNECE WP.29 govern haptic interface homologation across European markets. OEM procurement teams must monitor evolving functional safety standards and semiconductor supply constraints as haptic actuator controller integration deepens into vehicle domain architectures.
Market Dynamics
ISO 26262 functional safety mandates are systematically dismantling legacy mechanical pedal architectures, forcing tier-one suppliers to revalidate entire actuator control stacks under ASIL-D requirements for throttle-by-wire systems.
Growth Catalysts
- UNECE WP.29 type-approval frameworks:European homologation standards for haptic interfaces are accelerating OEM adoption of programmable resistance pedals across EU27 vehicle platforms.
- EPA emissions compliance requirements:US regulatory pressure on fleet efficiency is embedding eco-driving haptic cues into mass-market accelerator designs.
- Autonomous handoff scenarios:SAE Level 2+ deployment is creating demand for tactile driver-alert systems in transition-to-manual driving moments.
Market Restraints
- Semiconductor supply concentration:Haptic actuator controller chips face allocation bottlenecks from Taiwan and South Korea foundry capacity constraints.
- Piezoelectric ceramic input volatility:Lead zirconate titanate supply price swings compress margin on precision feedback modules for luxury electric vehicles.
- Legacy mechanical pedal substitution:Low-cost vehicle segments in emerging markets retain cable-actuated throttles, limiting haptic penetration below premium tiers.
Strategic Opportunities
- Commercial vehicle retrofit channels:Fleet operators in Germany and Japan are specifying aftermarket haptic pedals for fuel-efficiency training programs.
- India BIS safety standard evolution:Draft automotive electronics regulations are opening design-win opportunities for adaptive pedal architectures in domestic OEM programs.
- Electromechanical-piezoelectric convergence:Hybrid actuator designs are capturing margin pools in high-resolution feedback applications for performance electric vehicles.
Industry Challenges
- ISO 26262 certification timeline compression:ASIL-D validation cycles for new pedal platforms extend 18-24 months, delaying program launches.
- Domain architecture integration friction:Haptic controller migration from standalone ECUs to zonal compute clusters requires software stack re-architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Haptic Accelerator Pedal Market |
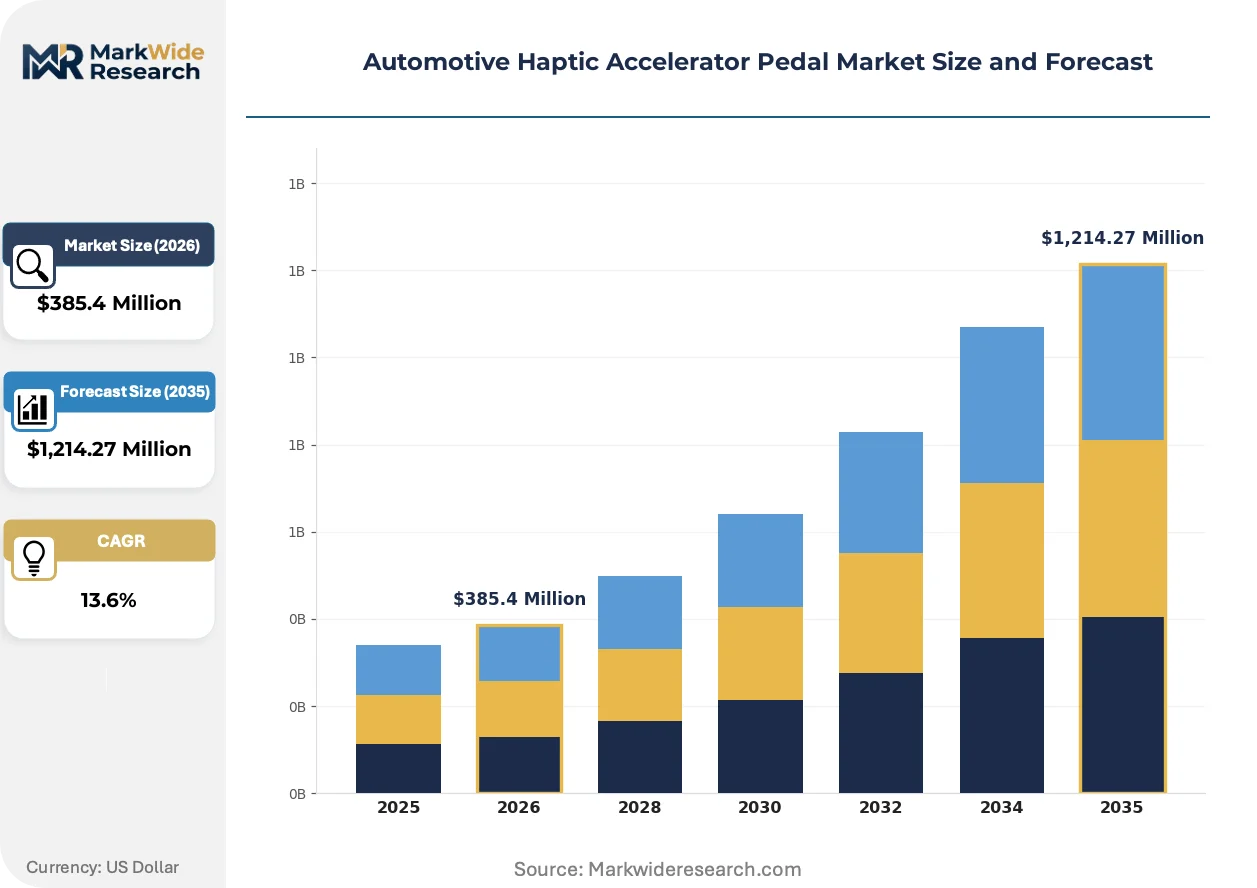
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,214.27 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pedals, Racing Pedals, Adaptive Pedals, Smart Pedals Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Customizers Technology: Electromechanical, Piezoelectric, Capacitive, Resistive |
| Companies Covered | KSR International, F-Tech, Continental AG, WABCO, Brano Group, Robert Bosch GmbH, CTS Corporation, CJ Automotive, HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Haptic Accelerator Pedal Market Emerging Trajectories
Actuator technology is compressing feedback resolution thresholds while regulatory pressure fuses safety and efficiency mandates into single hardware platforms. These shifts are redefining supplier R&D priorities and OEM specification patterns.
Magnetostrictive actuator cores are miniaturizing force-feedback mechanisms without sacrificing displacement precision. Tier-one suppliers are embedding these into compact pedal modules for mid-size electric vehicle platforms. This miniaturization is collapsing the footprint differential between premium and mass-market haptic implementations.
NHTSA accelerator control safety investigations are mandating redundant position sensing architectures in US-market pedals. The regulatory pressure is forcing validation of dual-sensor electromechanical designs with independent signal paths. Passenger vehicle OEMs are responding by consolidating haptic and safety-critical sensing into unified pedal assemblies.
Fleet procurement teams are unbundling pedal system sourcing from full powertrain contracts. Commercial vehicle operators in Germany are issuing standalone RFQs for programmable haptic modules with telematics integration. This procurement fragmentation is creating direct supplier relationships previously intermediated by engine manufacturers.
Automotive Haptic Accelerator Pedal Market Segmentation
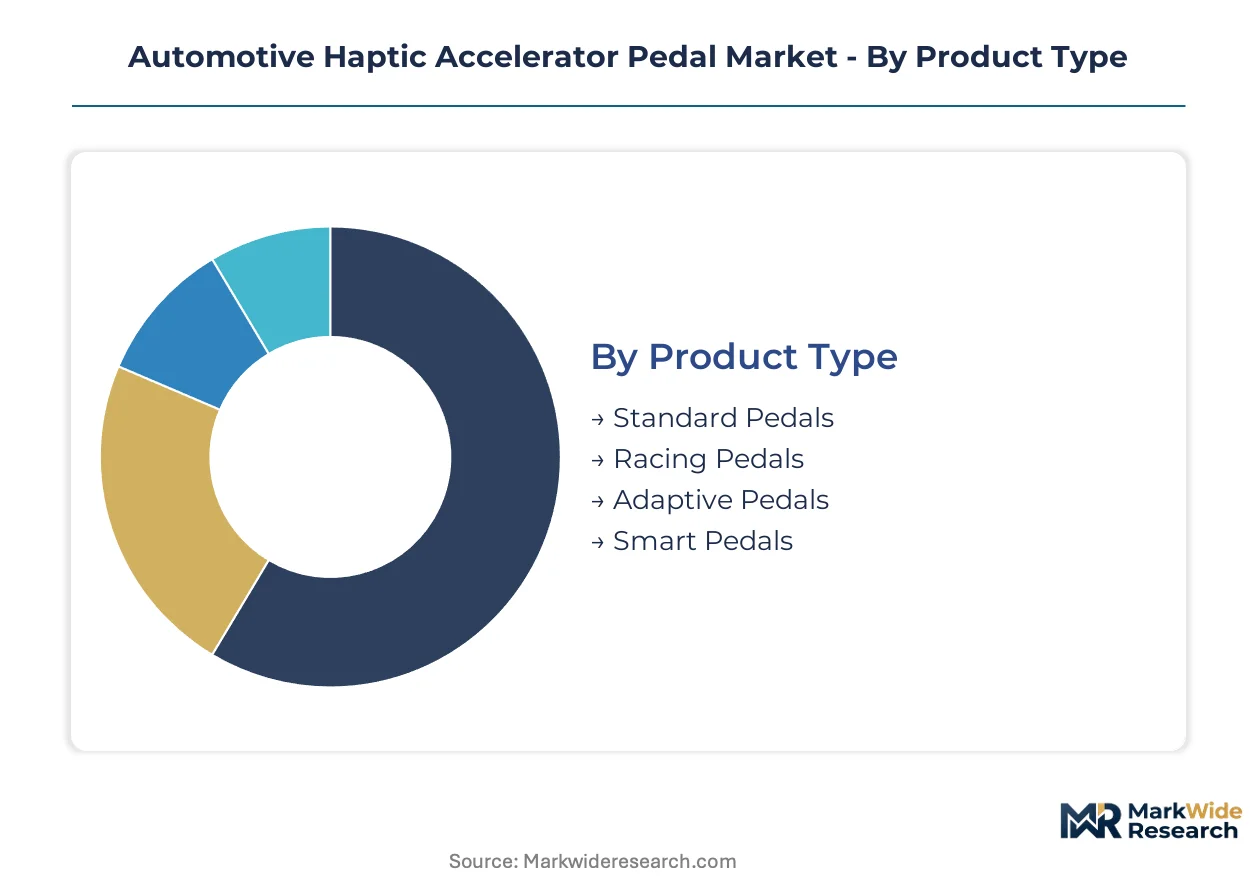
Haptic accelerator pedal architectures fragment across four intersecting dimensions: product sophistication tiers, powertrain categories, procurement channels, and actuator technologies. Each segmentation axis reveals distinct margin structures, validation protocols, and geographic demand concentrations that reshape supplier competitive positioning.
Product Type:
Standard and racing pedal variants dominate export flows from German and Japanese manufacturing clusters, while adaptive and smart pedal programs concentrate in domestic OEM engineering centers.
- Standard Pedals:Fixed-resistance mechanical-electromechanical hybrids with basic position sensing. Demand concentrates in mass-market passenger vehicle programs from Detroit and Stuttgart, constrained by legacy platform validation cycles and ASIL-B cost ceilings.
- Adaptive Pedals:Programmable resistance curves with real-time throttle boundary communication. German fleet operators and California-based EV manufacturers are specifying these for eco-driving training and autonomous handoff scenarios, driving the steepest R&D allocation among tier-one suppliers.
- Racing Pedals:High-stiffness aluminum or carbon-fiber reinforced polymer constructions with minimal feedback latency. Motorsport applications in Silverstone, Monza, and Suzuka circuits anchor demand, with limited crossover to road-legal performance vehicles.
- Smart Pedals:Integrated biometric monitoring and predictive haptic cueing via edge AI processing. Early deployment in Shanghai and Silicon Valley premium EV platforms faces ISO 26262 algorithm validation bottlenecks.
Standard pedals command the established base. The steepest expansion runs through adaptive pedals.
Vehicle Type:
Volume concentration tilts toward electrified platforms where throttle-by-wire architectures eliminate mechanical linkage cost barriers.
- Electric Vehicles:Native drive-by-wire compatibility enables full haptic feature exploitation without legacy mechanical compromise. OEMs in Shenzhen, Munich, and Austin are mandating smart pedal interfaces as standard equipment.
- Passenger Cars:The broadest application span across premium, mass-market, and entry tiers. Japanese and Korean OEMs are consolidating haptic specifications across consolidated platform architectures to amortize ASIL-D validation costs.
- Hybrid Vehicles:Dual-mode powertrain complexity demands context-aware pedal feedback for engine-on transitions. European mild-hybrid programs are driving electromechanical actuator volume.
- Commercial Vehicles:Fleet efficiency mandates from German logistics operators and Japanese trucking cooperatives are accelerating programmable pedal adoption in long-haul tractor configurations.
Passenger cars retain volume leadership. Electric vehicles are gaining share fastest.
End User:
Procurement authority is fragmenting as fleet operators and vehicle customizers bypass traditional powertrain supplier intermediation.
- OEMs:Centralized specification authority with 18-24 month program cycles. Stuttgart, Wolfsburg, and Toyota City engineering centers are consolidating haptic pedal sourcing into domain controller procurement packages.
- Fleet Operators:German and Japanese logistics chains are issuing standalone RFQs for telematics-integrated pedals with fuel-efficiency analytics. Direct supplier relationships are displacing engine manufacturer intermediation.
- Aftermarket Providers:Retrofit channel concentration in North American and European performance tuning segments. Regulatory homologation variance across state and national boundaries fragments addressable market scale.
- Vehicle Customizers:Low-volume, high-margin specialist applications in Dubai, Los Angeles, and Monaco luxury modification shops. Bespoke haptic mapping for individual driver profiles commands premium pricing.
OEMs anchor established procurement flows. Fleet operators are climbing the fastest as a demand channel.
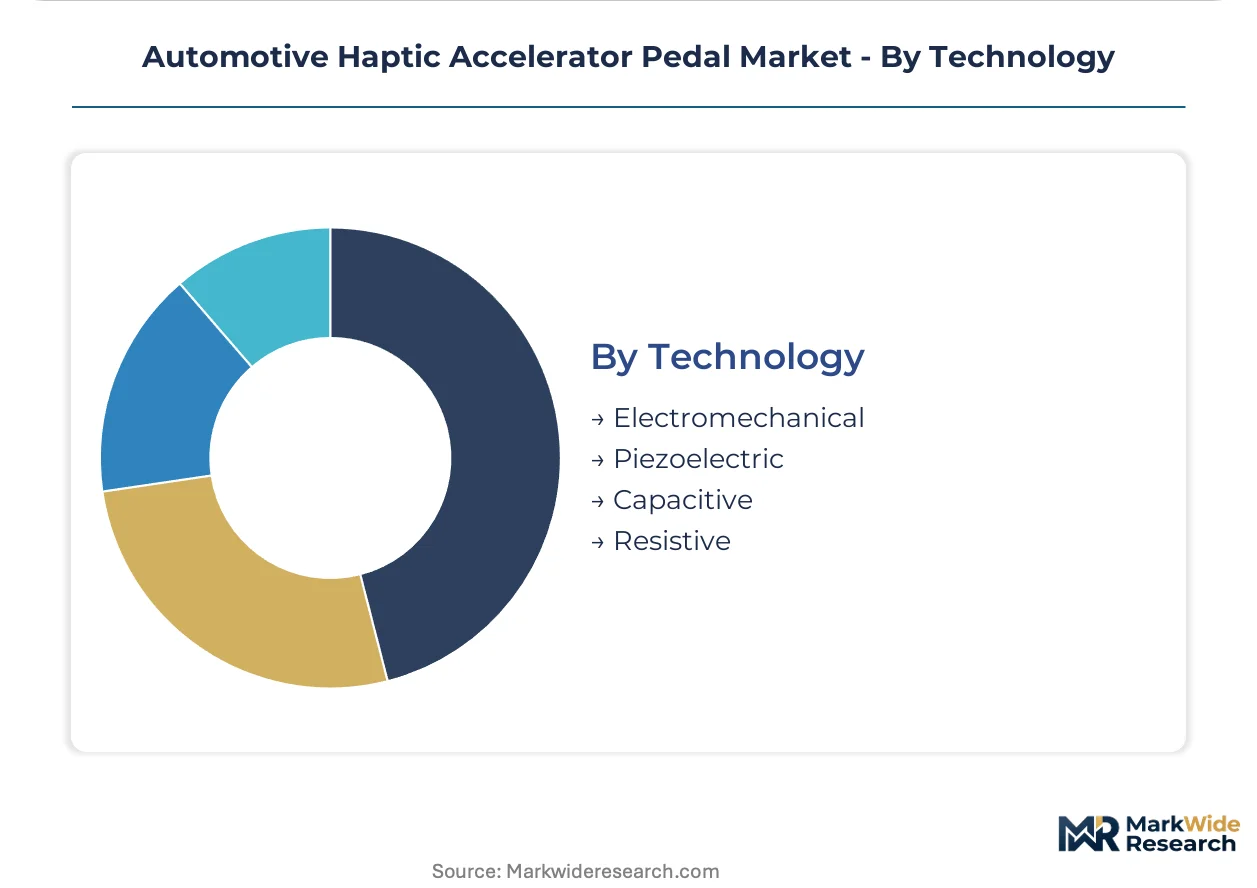
Technology:
Actuator technology selection stratifies by precision requirements, cost position, and supply chain concentration risk.
- Electromechanical:DC motor and solenoid-based force feedback with sub-50 millisecond latency. Dominates unit volume across mass-market and mid-premium tiers from Chinese and Mexican manufacturing footprints.
- Piezoelectric:Lead zirconate titanate ceramic stacks enabling sub-0.05 millimeter displacement resolution. Luxury EV applications in Munich and Stuttgart are absorbing limited supply despite ceramic input price volatility.
- Capacitive:Non-contact position sensing with gesture recognition capability. Emerging integration in Shanghai-developed autonomous vehicle platforms for redundant input pathways.
- Resistive:Strain-gauge and potentiometer-based sensing with mature supply chains. Retained in cost-optimized emerging market vehicle programs where functional safety tiering permits ASIL-A implementations.
Electromechanical technology commands the established base. Piezoelectric approaches are expanding most quickly in precision-critical segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with German and Japanese buyers absorbing premium haptic features while Indian and Brazilian fleets prioritize cost-optimized mechanical-electromechanical hybrids. Price sensitivity concentrates in emerging market entry segments, whereas US and European OEMs specify full smart pedal suites regardless of vehicle tier.
United States
NHTSA accelerator control safety investigations and EPA emissions compliance are forcing dual-sensor redundant architectures into mass-market vehicle programs. Detroit-based engineering centers are consolidating haptic pedal sourcing with domain controller procurement packages. Michigan and Ohio manufacturing corridors anchor Continental AG and Robert Bosch GmbH supply chain investments for North American OEM programs.
Germany
UNECE WP.29 type-approval frameworks and KBA homologation standards are accelerating programmable resistance pedal adoption across EU27 platforms. Stuttgart and Wolfsburg engineering centers specify adaptive pedals for eco-driving training and autonomous handoff scenarios. Bavarian and Baden-Württemberg automotive clusters concentrate tier-one supplier R&D for electromechanical actuator validation under ASIL-D requirements.
China
MIIT intelligent vehicle development guidelines and GB standards for drive-by-wire systems are mandating haptic interfaces in premium EV platforms. Shenzhen and Shanghai OEM engineering centers specify smart pedals with edge AI processing as standard equipment. Yangtze River Delta and Pearl River Delta manufacturing footprints dominate electromechanical actuator volume production for domestic and export programs.
Japan
METI carbon neutrality roadmaps and JIS functional safety standards are embedding haptic feedback into hybrid powertrain transition management. Toyota City and Nagoya engineering centers consolidate haptic specifications across consolidated platform architectures. Kanto and Chubu industrial corridors anchor CJ Automotive and F-Tech manufacturing scale for just-in-sequence delivery to major OEMs.
India
Draft BIS automotive electronics regulations and PLI scheme incentives for advanced driver-assistance components are opening design-win opportunities for adaptive pedal architectures. Tamil Nadu and Maharashtra domestic OEM programs are evaluating haptic implementations for compact SUV and sedan platforms. Haryana and Gujarat manufacturing corridors concentrate cost-optimized electromechanical pedal assembly for price-sensitive entry segments.
Automotive Haptic Accelerator Pedal Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision actuator specialists competing against high-volume mechanical pedal manufacturers for OEM program allocation. The vendor base stratifies into three tiers: integrated braking-pedal system suppliers, standalone haptic module specialists, and legacy mechanical pedal converters adapting to electromechanical architectures. Dominant competitive moves include strategic partnerships for semiconductor supply security and portfolio diversification into zonal compute integration.
Among German-integrated system suppliers, Continental AG and Robert Bosch GmbH occupy positions anchoring European OEM supply chains through combined braking and pedal system portfolios. KSR International exemplifies the North American scale-driven archetype, with manufacturing footprints concentrated in Michigan and Ontario for just-in-sequence delivery capabilities. These three entities represent distinct strategic postures: technology integration, geographic scale, and domain controller migration readiness.
| Leading Market Players |
|---|
| KSR International |
| F-Tech |
| Continental AG |
| WABCO |
| Brano Group |
| Robert Bosch GmbH |
| CTS Corporation |
| CJ Automotive |
| HELLA GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Magnetostrictive actuator cores replacing electromechanical solenoids in mid-premium pedal modules are redrawing supplier geography from Mexican assembly corridors toward Bavarian precision-component clusters while compressing the cost delta between mass-market and luxury haptic implementations.
Pricing Analysis
Aftermarket service contracts and retrofit calibration subscriptions now generate lifetime value multiples exceeding original equipment sales for adaptive pedal platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASIL certification grade and real-time feedback resolution, with piezoelectric ceramic stacks commanding substantial premiums over electromechanical alternatives. Pricing pressure stems from lead zirconate titanate input volatility squeezing margin on precision modules. Fleet operators in Germany exhibit lowest price sensitivity due to fuel-efficiency ROI calculations, while Indian domestic OEM programs face hard cost ceilings.
Supply Chain Analysis
Taiwan and South Korea anchor haptic actuator controller chip fabrication, while China dominates electromechanical pedal assembly volume and Germany concentrates precision actuator R&D. Lead zirconate titanate ceramic feeds from Japanese and Chinese suppliers, with rare-earth magnet inputs drawing from Chinese processing facilities. Single-source vulnerability concentrates in Taiwan foundry capacity for automotive-grade microcontroller units. Distribution runs through Tier 1 supplier consolidation into OEM domain controller procurement packages, bypassing legacy engine manufacturer intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIL-D functional safety engineering talent scarcity constrains program launch velocity, with validation cycle compression creating bottlenecks that favor incumbent suppliers with certified control stack architectures.
For Market Incumbents: Fortify semiconductor supply security through foundry partnership diversification beyond Taiwan concentration, and embed haptic controllers deeper into zonal compute clusters to capture domain architecture migration value. Magnetostrictive miniaturization threatens electromechanical volume positions. Certification investment in ISO 26262 algorithm validation for smart pedal edge AI represents the critical defensive lever. For New Entrants and Emerging Players: India BIS certification fast-tracks for adaptive pedal architectures open design-win opportunities ahead of full regulatory codification. Commercial vehicle retrofit channels in Germany and Japan present the most penetrable white-space, with telematics-integrated fuel-efficiency training modules offering direct fleet procurement access previously blocked by powertrain supplier intermediation. Target standalone RFQ participation rather than Tier 2 sub-supply positioning. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors vertically integrated braking-pedal system suppliers with ASIL-D validation infrastructure already amortized across platform portfolios. Long-term viability hinges on software-defined vehicle integration depth rather than hardware manufacturing scale alone. Watch for NHTSA rulemaking on redundant position sensing architectures as inflection indicator for regulatory-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Compresses validation timelines for throttle-by-wire haptic platforms competing for OEM program allocation. |
| Semiconductor Supply Diversification | Reduces Taiwan foundry concentration risk for haptic actuator controller chip procurement security. |
| Zonal Compute Integration | Migrates pedal controllers from standalone ECUs into domain architectures capturing software value. |
| Magnetostrictive Actuator Adoption | Miniaturizes force-feedback mechanisms without sacrificing displacement precision for mid-size EVs. |
| Commercial Fleet Retrofit Channel Development | Creates direct supplier relationships with German and Japanese logistics operators bypassing intermediation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributors, and fleet operations managers, cross-validated against secondary sources including NHTSA regulatory filings, UNECE WP.29 type-approval documentation, vehicle production databases, and semiconductor trade flow records, with bottom-up program-level build-up triangulated against top-down market sizing.
Across the analysis window, the forecasting framework models volume and value trajectories through segmentation across product sophistication tiers, vehicle propulsion architectures, actuator technology types, and regional production clusters, with CAGRs derived from program launch timing analysis and content-per-vehicle scaling assumptions for electrified platforms, incorporating regulatory compliance deadlines and semiconductor supply availability as key demand-shaping inputs.
Underlying assumptions cover NHTSA rulemaking timelines, foundry capacity allocation patterns, and ceramic input price stabilization, with deviation risk concentrated in ISO 26262 certification timeline extensions and autonomous vehicle deployment pace. Recalibration cycles align with material shifts in functional safety standard revisions and domain architecture adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Brazil Automotive Actuators Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Transmission Sales Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Engine Flush Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Internal Combustion Engine Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
Automotive Turbocharger Hose Market