
 Electric Vehicle Powertrain Market | 2026-2036
Electric Vehicle Powertrain Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Powertrain Market Analysis
Multi-source battery supply contracts is repositioning how OEMs secure cell capacity and manage geopolitical risk. Tesla leverages its in-house 4680 cell program to reduce supplier dependency. CATL anchors the premium segment through high-nickel chemistry partnerships with European automakers. Samsung SDI competes on cylindrical cell reliability for performance-oriented platforms.
An electric vehicle powertrain comprises the battery pack, electric motor, inverter, and thermal management hardware that converts stored electrical energy into mechanical propulsion, typically operating at 400–800 volts DC with energy densities exceeding 250 watt-hours per kilogram in leading cell formats. Battery Electric technology captures the dominant share of OEM engineering budgets as range targets harden, while Power Electronics represents the fastest-improving margin pool due to silicon carbide semiconductor substitution. Passenger Vehicles absorb the majority of cell output, though Commercial Vehicles is where fleet-scale procurement is restructuring supplier negotiation dynamics.
The EPA tailpipe rules in the United States, the EU Green Deal's 2035 ICE phase-out, and China's MIIT new-energy vehicle credit system are collectively mandating powertrain electrification timelines that eliminate incremental compliance pathways. EMA and REACH frameworks in Europe add chemical stewardship requirements to cell supply chains. Stakeholders must track how regulatory credit trading mechanics in multiple jurisdictions alter the effective cost of powertrain technology choices.
Market Dynamics
Fleet-scale electrification mandates are compressing OEM engineering cycles while silicon carbide semiconductor substitution rewrites power electronics economics across voltage classes.
Growth Catalysts
- China's MIIT credit system:Mandatory new-energy vehicle quotas force domestic OEMs to accelerate battery-electric drivetrain deployment or purchase compliance credits from competitors.
- Logistics electrification:Last-mile delivery operators are standardizing 800-volt architectures to enable rapid depot charging and minimize vehicle downtime.
- High-nickel cathode chemistry:Cell energy density exceeding 250 watt-hours per kilogram extends passenger vehicle range without proportional pack mass penalties.
Market Restraints
- Critical mineral concentration:Cobalt and lithium refining capacity clusters in China's Yangtze River Delta, exposing non-Chinese OEMs to geopolitical supply disruption.
- Silicon carbide substrate scarcity:Wafer fabrication bottlenecks limit inverter production scaling despite design wins across premium platforms.
- REACH chemical stewardship:ECHA disclosure requirements for cell supply chains add compliance latency to European procurement timelines.
Strategic Opportunities
- Commercial vehicle retrofit:Existing diesel chassis in India present addressable white space for integrated electric axle conversion kits.
- Vehicle-to-grid integration:Bidirectional charging hardware creates new revenue streams for fleet operators participating in frequency regulation markets.
- US Inflation Reduction Act:Domestic content credits incentivize North American cell and pack assembly investment independent of Asian supply.
Industry Challenges
- Power electronics talent scarcity:Shortage of engineers proficient in wide-bandgap semiconductor thermal management slows inverter platform development.
- Multisource qualification timelines:OEMs must validate cell chemistry variants from three-plus suppliers simultaneously to meet production ramps.
- Thermal system integration:Unified cooling architectures for batteries, motors, and cabins require cross-functional coordination absent from legacy siloed teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Powertrain Market |
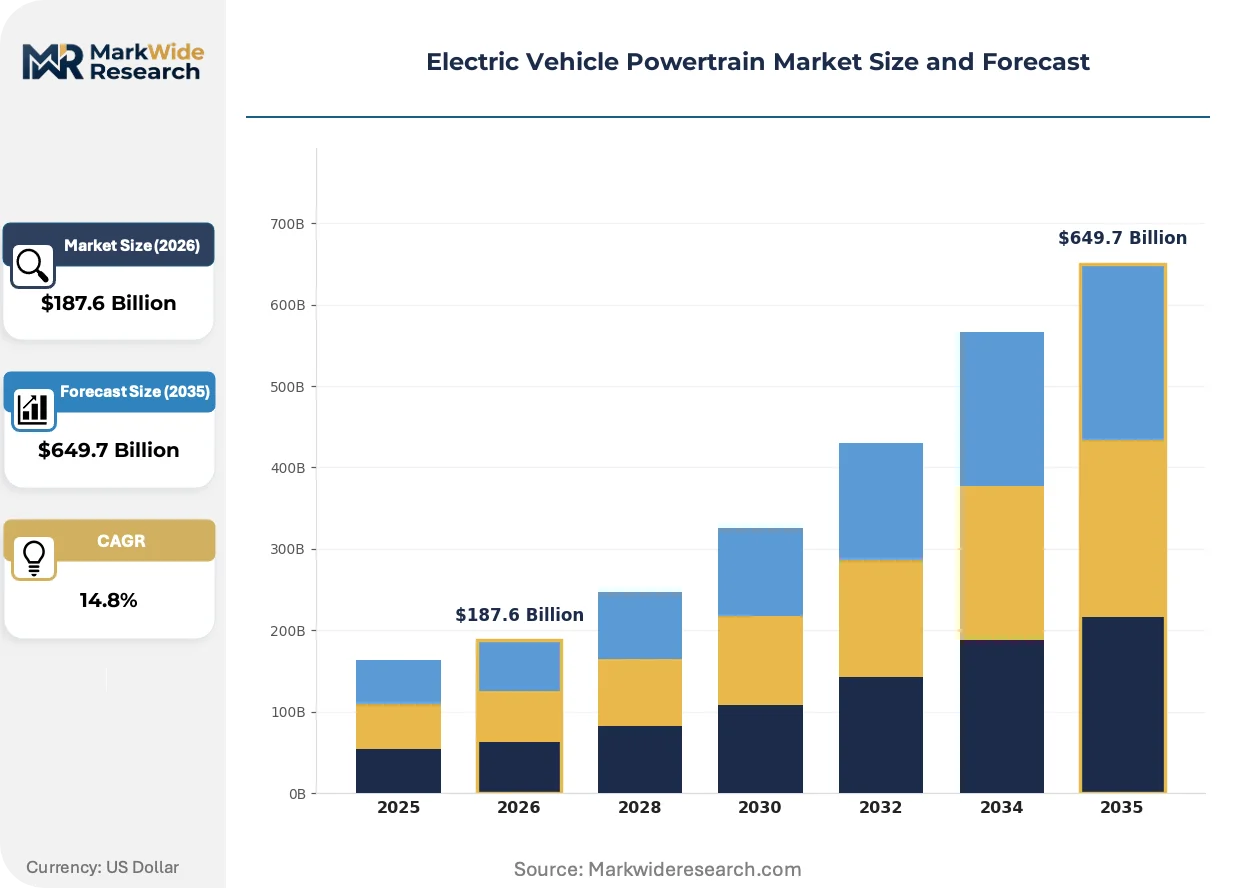
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $649.7 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Batteries, Electric Motors, Power Electronics, Fuel Cells Technology: Battery Electric, Hybrid Electric, Plug-in Hybrid, Fuel Cell Electric End User: OEMs, Fleet Operators, Residential Users, Aftermarket Providers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Public Transport |
| Companies Covered | LG Energy Solution, Samsung SDI, Tesla, General Motors, Volkswagen Group, BYD, Panasonic, Ford, CATL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Powertrain Market Emerging Trajectories
Powertrain architecture is fragmenting into standardized subsystems that OEMs can source or insource based on margin pressure and control preferences.
Silicon carbide MOSFET technology is replacing insulated-gate bipolar transistors in traction inverters to cut switching losses and enable higher voltage operation. Tier 1 suppliers are shipping 800-volt platforms to European performance OEMs and Chinese premium brands simultaneously. The technology is modularizing inverter design into discrete power stages that manufacturers can scale across vehicle segments without complete redesign.
The EU Green Deal's 2035 internal combustion engine phase-out eliminates incremental compliance pathways for European OEMs. Engineering budgets are consolidating exclusively on battery-electric architectures with no hybrid intermediate. Power electronics specialists face compressed development windows as vehicle programs abandon parallel technology hedges.
Fleet operators are consolidating procurement around total-cost-of-ownership metrics that internalize charging infrastructure, residual value guarantees, and energy arbitrage potential. Traditional dealer networks lose relevance as direct OEM-fleet negotiations standardize multi-year supply agreements with embedded service provisions. Ride-hailing and logistics verticals in California and Germany lead this contract restructuring.
Electric Vehicle Powertrain Market Segmentation
Powertrain procurement patterns diverge sharply across customer types and vehicle architectures. Component sourcing strategies, technology roadmaps, and application requirements create distinct margin pools that suppliers must navigate simultaneously.
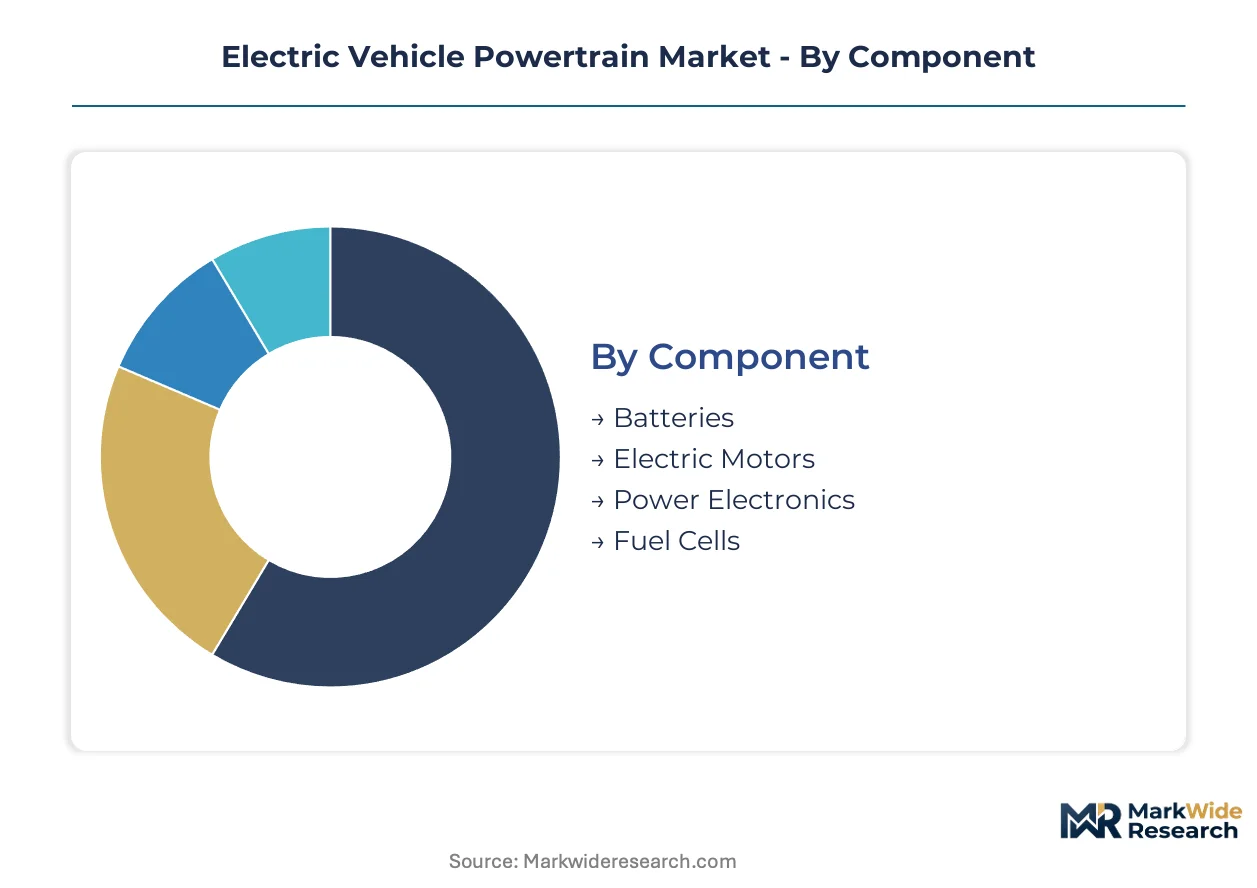
Component:
Standardization pressure varies enormously across this category, with some subsystems commoditizing while others remain fiercely proprietary.
- Batteries:High-nickel lithium-ion cells dominate engineering investment, with energy densities exceeding 250 watt-hours per kilogram in premium formats. Cell chemistry selection locks in thermal management architecture and dictates pack integration complexity for the full vehicle program.
- Electric Motors:Permanent magnet synchronous designs with hairpin windings capture volume production, though rare-earth magnet dependency creates supply vulnerability. Chinese manufacturers in the Yangtze River Delta control neodymium processing, forcing non-Chinese OEMs into long-term offtake negotiations or magnet-free design pivots.
- Power Electronics:Silicon carbide MOSFET substitution is rewriting inverter economics across voltage classes.
- Fuel Cells:Proton exchange membrane stacks remain niche outside Korean and Japanese passenger programs and Chinese heavy-duty bus deployments.
Leading the category by volume: Batteries. Expanding most quickly: Power Electronics.
Technology:
Cost tier stratification separates architectures with fundamentally different engineering intensity and supplier ecosystem requirements.
- Battery Electric:Pure-electric architectures consolidate OEM engineering budgets as regulatory deadlines harden. China's MIIT credit system and Europe's CO2 fleet standards eliminate hybrid compliance pathways, forcing full platform redesigns around 400–800 volt electrical systems.
- Hybrid Electric:Full hybrids retain relevance in markets with charging infrastructure gaps, though engineering investment is flat or declining. Japanese OEMs maintain production lines for Southeast Asian and Latin American export markets where grid reliability concerns persist.
- Plug-in Hybrid:Transitional technology faces compressed development windows as battery cost curves improve. European premium brands utilize PHEVs for fleet CO2 averaging during BEV production ramp, but program extensions beyond current generations appear unlikely.
- Fuel Cell Electric:Heavy-duty commercial applications in California and German freight corridors sustain limited deployment, with Hyundai and Toyota anchoring passenger volume.
Commanding investment share: Battery Electric. Steepest expansion trajectory: Battery Electric.
End User:
Customer type determines contract structure, with fleet procurement consolidating around total-cost-of-ownership metrics that reshape supplier relationships.
- OEMs:Vertical integration decisions differentiate strategies, with some captive-producing cells and motors while others rely on Tier 1 module supply. Engineering cycles compress as platform electrification mandates eliminate technology hedging.
- Fleet Operators:Logistics and ride-hailing services in California and Germany are standardizing 800-volt architectures with embedded charging infrastructure and residual value guarantees. Direct OEM negotiations bypass traditional dealer networks.
- Residential Users:Individual purchasers prioritize range and charging speed, driving demand for high-voltage platforms with rapid DC capability.
- Aftermarket Providers:Retrofit conversion kits for existing diesel chassis present addressable white space in India and Southeast Asian markets.
Concentrating procurement power: Fleet Operators. Gaining share fastest: Fleet Operators.
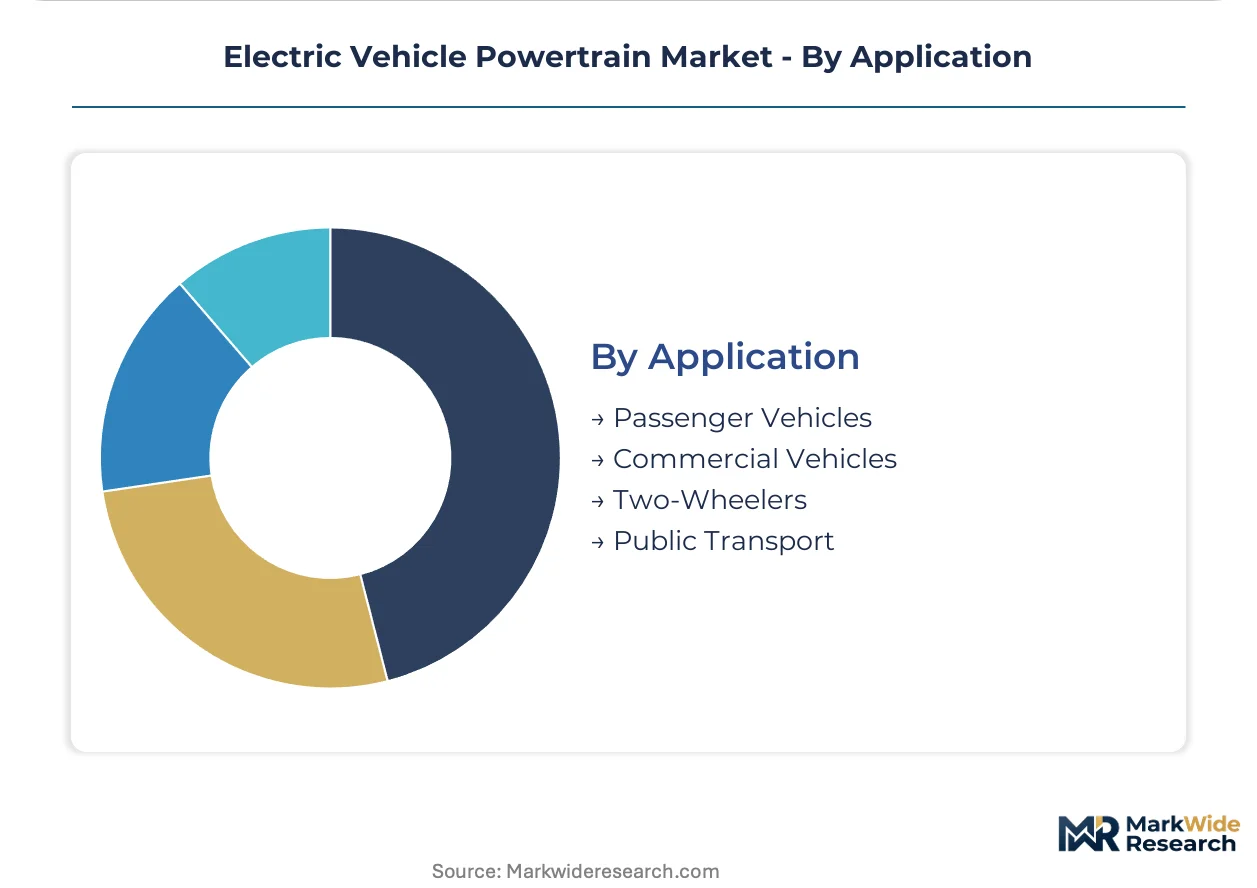
Application:
Volume distribution across vehicle classes reflects divergent duty cycles, regulatory pressure intensity, and infrastructure availability.
- Passenger Vehicles:Absorb the majority of cell output as range targets harden and premium segments electrify first. Chinese and European OEMs compete on 800-volt platform deployment with silicon carbide inverters enabling rapid charging.
- Commercial Vehicles:Fleet-scale procurement is restructuring supplier negotiation dynamics, with multi-year supply agreements replacing spot purchasing. Last-mile delivery operators in Germany and California consolidate around standardized depot charging architectures.
- Two-Wheelers:Southeast Asian markets drive volume, with swappable battery networks addressing urban density constraints.
- Public Transport:Municipal bus electrification in China and European cities sustains dedicated production lines, with fuel cell trials in Korean and German intercity routes.
Dominating cell absorption: Passenger Vehicles. Climbing the fastest: Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium reserves in South America's salt flats and cobalt processing corridors in Central Africa anchor raw-material geography, yet manufacturing gravity concentrates where cell assembly, motor production, and vehicle integration converge.
China
Fleet electrification mandates and MIIT credit quotas force domestic OEMs toward battery-electric platforms. The MIIT new-energy vehicle credit system penalizes manufacturers missing production thresholds. The Yangtze River Delta manufacturing corridor hosts CATL and BYD cell plants alongside Tesla's Shanghai Gigafactory.
Germany
Premium OEM engineering budgets consolidate on 800-volt architectures with silicon carbide inverters. The EU Green Deal's 2035 ICE phase-out eliminates hybrid compliance pathways. The Stuttgart-Munich industrial corridor anchors Volkswagen Group and BMW powertrain development centers.
United States
Fleet operators in California and Texas standardize depot charging infrastructure for last-mile logistics. The EPA tailpipe rules and IRA domestic content credits reshape cell and pack assembly investment. The Detroit-to-Lansing corridor retains motor and inverter engineering despite cell production migrating south.
South Korea
Hyundai and Samsung SDI anchor high-nickel cylindrical cell development for performance platforms. METI-aligned industrial policy supports solid-state research through public-private consortia. The Gyeonggi-Seoul corridor concentrates cathode material R&D and fuel cell stack production.
Japan
Toyota and Panasonic maintain fuel cell and solid-state battery programs alongside prismatic cell supply. METI carbon-neutrality roadmaps extend hydrogen infrastructure investment. The Aichi-Nagoya manufacturing belt hosts integrated motor-inverter production for hybrid and BEV platforms.
Electric Vehicle Powertrain Market Vendor Landscape
Capacity expansion dominates the current landscape as cell manufacturers race to secure offtake agreements before OEM platform locks crystallize. The vendor base concentrates around Asian cell producers and integrated automakers with captive battery programs. Three archetypes define positioning: chemistry specialists controlling cathode innovation, integrated OEMs with in-house cell programs, and Tier 1 system integrators modularizing power electronics. M&A activity targets solid-state startups and silicon carbide wafer sources, while strategic partnerships lock in decade-long supply commitments.
Within the chemistry-specialist tier, CATL and LG Energy Solution exemplify divergent geographic anchoring strategies. Samsung SDI occupies a position bridging cylindrical cell reliability and premium automotive qualification standards. These three entities represent distinct responses to OEM demands for multi-source supply security and chemistry flexibility.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| Tesla |
| General Motors |
| Volkswagen Group |
| BYD |
| Panasonic |
| Ford |
| CATL |
| Others |
Supply Flow & Price Mechanics
Cobalt sulfate and lithium hydroxide contract prices cascade from Yangtze River Delta refiners through three distinct battery pack pricing tiers, with OEMs absorbing volatility via long-term offtake clauses while fleet buyers negotiate embedded residual value guarantees.
Pricing Analysis
Warranty and service bundling separates premium powertrain contracts from transactional component sales, with cell suppliers offering decade-long performance guarantees against capacity fade. Three-tier pricing structure across premium, standard, and economy levels reflects nickel chemistry grade and silicon carbide inverter content. Pricing pressure stems from fleet operators consolidating procurement around total-cost-of-ownership metrics that internalize charging infrastructure and energy arbitrage. Commercial vehicle buyers exhibit highest price sensitivity due to thin operating margins, while premium passenger OEMs prioritize energy density and fast-charge capability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European and North American OEMs mandate simultaneous qualification of cell chemistry variants from three-plus suppliers, extending procurement timelines despite mitigating concentration risk. Cathode active material production clusters in China, South Korea, and Japan, with neodymium magnet processing anchored in the Yangtze River Delta. Supply chains draw from Chilean lithium brine, Indonesian nickel laterite, and Central African cobalt hydroxide. Single-source vulnerability in silicon carbide wafer fabrication limits inverter production scaling. Distribution runs through Tier 1 system integrators that modularize power electronics for cross-platform deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 2035 ICE phase-out erects a cost-of-compliance barrier that favors incumbent OEMs with captive cell programs and certified 800-volt platforms, while marginalizing suppliers lacking REACH chemical stewardship documentation.
For Market Incumbents: Deploy silicon carbide inverter capacity additions in Germany and Texas to secure design wins before platform locks crystallize. Defensive consolidation requires backward integration into cathode material production or exclusive offtake from Yangtze River Delta refiners to hedge cobalt price volatility. Threat from Chinese cell producers with MIIT credit system compliance advantages demands accelerated European qualification timelines.
For New Entrants and Emerging Players: Solid-state battery prototyping capabilities offer a technology-first wedge into premium passenger platforms seeking beyond-lithium-ion energy density. White-space targets include commercial vehicle retrofit kits for Indian diesel chassis and bidirectional charging hardware for California frequency regulation markets. Most penetrable segment: aftermarket conversion providers serving Southeast Asian two-wheeler swappable battery networks.
For Investors and Strategic Acquirers: Samsung SDI or LG Energy Solution announcing cylindrical cell supply agreements with European performance OEMs is the leading indicator that premium platform qualification windows remain open for chemistry specialists. Five-to-ten year viability favors integrated automakers with in-house cell programs and multi-source supply security. Acquisition target archetype: silicon carbide wafer startups with automotive qualification pathways. Signal to monitor: EPA tailpipe rule stringency revisions affecting fleet electrification mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL's high-nickel partnerships with European automakers lock in decade-long cathode chemistry roadmaps. |
| Platform Standardization | 800-volt architectures with silicon carbide inverters enable rapid DC charging across Volkswagen Group and BMW portfolios. |
| Charging Infrastructure Partnership | Depot charging networks for California logistics fleets reduce vehicle downtime and reshape OEM-fleet contract structures. |
| Geographic Manufacturing Footprint | IRA domestic content credits incentivize North American cell and pack assembly independent of Asian supply concentration. |
| Software-Defined Vehicle Investment | Vehicle-to-grid integration creates revenue streams for fleet operators participating in frequency regulation markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator sustainability directors, and power electronics R&D heads. Secondary sources included MIIT production databases, EPA tailpipe rule dockets, EU Green Deal implementation documents, and IHS Markit vehicle registration data. Bottom-up cell demand modeling and top-down OEM electrification budget analysis were triangulated against Yangtze River Delta production capacity disclosures.
Granularity-level modeling addressed component sourcing strategies at the battery chemistry tier, power electronics semiconductor substitution rates, and fleet procurement contract structures across passenger and commercial vehicle applications. Segmentation dimensions included propulsion architecture, vehicle class, end-user type, and regional regulatory cluster. CAGRs were derived from production volume trajectories and content-per-vehicle assumptions across the projection horizon. Industry-specific inputs incorporated silicon carbide inverter adoption curves and high-nickel cathode chemistry penetration rates.
Several conditions sit outside the modeled scope, including solid-state battery commercialization timelines, hydrogen fuel cell heavy-duty adoption pathways, and unannounced regulatory credit trading mechanism revisions. Forecasts reflect assumptions regarding OEM platform electrification commitments and critical mineral supply expansion. Deviation in Chinese export license policies for refined lithium or cobalt would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Engine Actuators Market
Powertrain
LNG Engine Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Clutch Friction Plate Market
Powertrain
Engine Flush Market
Powertrain
Internal Combustion Engine Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Europe Turbocharger Market