
 Turbocharger Market | 2026-2036
Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Turbocharger Market Outlook
Modular turbocharger packaging is pivoting toward integrated electric-assist systems that combine motor-generator units with conventional turbine housings. Garrett Motion Inc. leverages its silicon carbide inverter technology to differentiate in electrified turbos. BorgWarner Inc. sustains manufacturing scale across multiple continents through captive casting and machining operations. IHI Corporation specializes in compact marine turbo configurations that dominate Japanese shipbuilder supply chains.
A turbocharger is a forced-induction device driven by exhaust gas flow that compresses intake air to increase engine power density, typically operating at shaft speeds exceeding 200,000 rpm and boost pressures of 1.5–3.0 bar. Its primary industrial purpose is to enable engine downsizing without sacrificing torque output, thereby reducing fuel consumption and exhaust emissions. Variable geometry turbochargers command the largest revenue pool in passenger diesel applications, while electric turbo technology represents the fastest-expanding segment as 48-volt mild-hybrid architectures proliferate. Twin-scroll configurations anchor gasoline direct-injection platforms where cylinder deactivation strategies require rapid transient response.
EPA tailpipe standards and Euro 7 proposals are forcing turbocharger suppliers to certify particulate filtration compatibility and onboard diagnostic integration. Japan's METI enacts fuel-economy benchmarks that favor turbocharged kei-car engines below 660 cc displacement. Stakeholders must monitor how China's MIIT dual carbon goals and India's BIS emission norms reshape sourcing requirements for localized turbo production.
Market Dynamics
Electric turbocharger architectures are compressing development cycles as 48-volt mild-hybrid platforms force suppliers to merge motor-generator units with conventional turbine housings, rewiring competitive positioning around silicon carbide inverter integration rather than casting scale alone.
Growth Catalysts
- Euro 7 tailpipe mandates:European regulators are accelerating turbocharger electrification by requiring particulate filtration compatibility and onboard diagnostic integration for all new passenger vehicle platforms.
- Commercial vehicle fleet expansion:Freight operators across Germany and the United States are retrofitting existing diesel powertrains with variable geometry turbos to preempt EPA Tier 4 enforcement actions.
- Silicon carbide inverter adoption:Power electronics manufacturers are embedding wide-bandgap semiconductors into electric-assist turbochargers, enabling sustained motor operation above 200,000 rpm shaft speeds.
Market Restraints
- High-performance alloy cost volatility:Inconel turbine wheel prices fluctuate with nickel supply disruptions from Indonesian mining concessions, compressing foundry margins.
- Japanese supplier concentration:IHI Corporation and Mitsubishi Heavy Industries control marine turbocharger supply chains, creating single-source vulnerability for shipbuilders.
- Heat exchanger packaging limits:Intercooler volume constraints in front-wheel-drive architectures cap boost pressure recovery rates below theoretical compressor maps.
Strategic Opportunities
- Indian BIS emission norm alignment:Domestic commercial vehicle manufacturers are localizing turbocharger production to satisfy Bharat Stage VI phase-II enforcement without import duty exposure.
- China MIIT dual carbon goals:The ministry's fuel-economy benchmarks for heavy-duty trucks are mandating twin-scroll turbo adoption across diesel platforms above 3.0-liter displacement.
- Marine electrification convergence:Shipbuilders are integrating electric turbos with battery-hybrid propulsion systems for harbor maneuvering modes, opening auxiliary power unit applications.
Industry Challenges
- Thermal management engineering scarcity:Suppliers face recruitment bottlenecks for engineers capable of simulating transient exhaust pulse energy recovery across multi-cylinder firing orders.
- Certification timeline compression:Euro 7 pre-certification testing protocols require 18-month validation cycles for electric turbo OBD integration, delaying platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turbocharger Market |
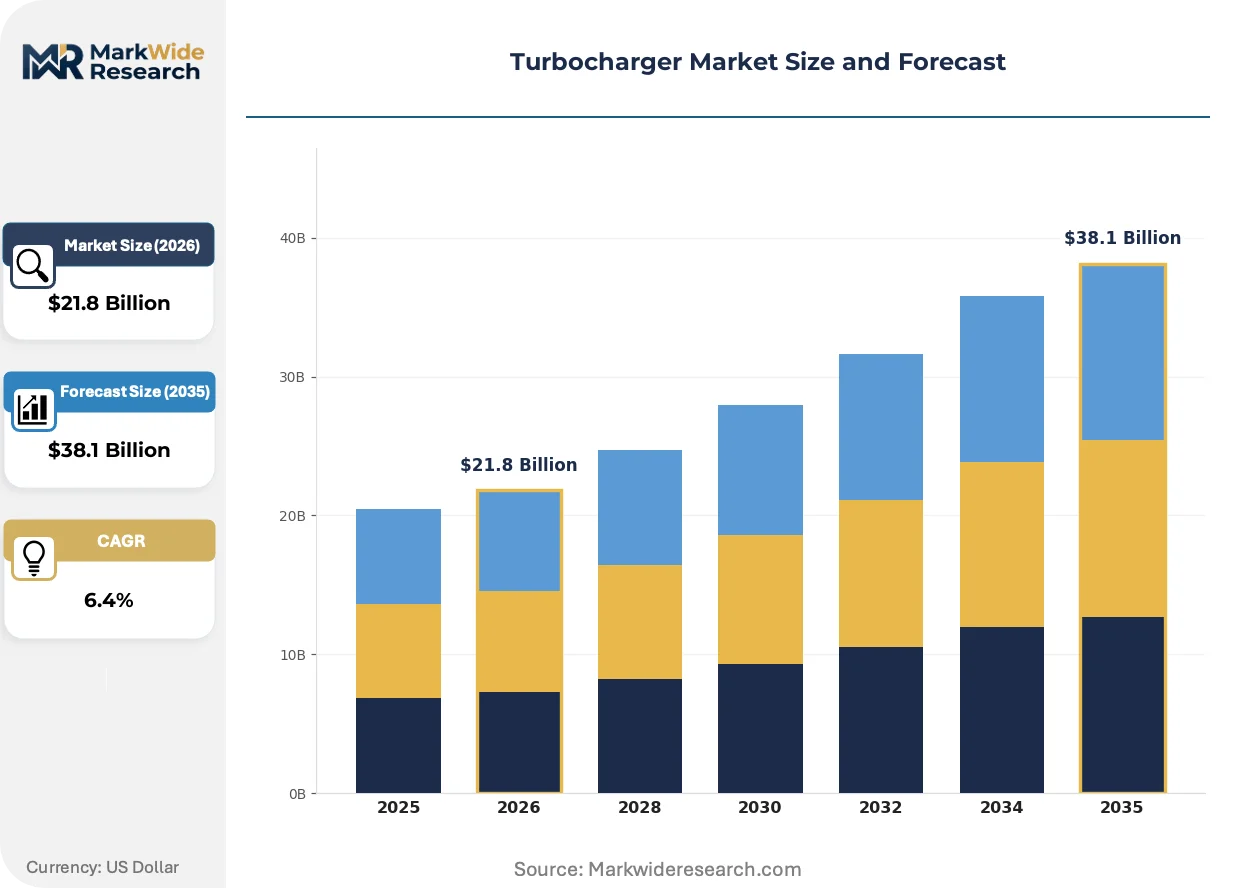
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Geometry, Twin-scroll, Electric Turbo, Traditional Turbo Fuel Type: Gasoline, Diesel, Natural Gas, Biofuels End User: Automotive, Aviation, Marine, Industrial Technology: Mechanical, Electric, Hybrid, Wastegate |
| Companies Covered | BorgWarner Inc., Garrett Motion Inc., Mitsubishi Heavy Industries Ltd., IHI Corporation, Cummins Inc., Continental AG, Honeywell International Inc., MAHLE GmbH, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turbocharger Market Strategic Shifts
Forced-induction technology is bifurcating between legacy internal-combustion optimization and electrified hybrid architectures, with supplier R&D budgets reallocating toward motor-generator integration and away from pure aerodynamic efficiency gains.
Electric turbochargers are expanding into gasoline direct-injection platforms as automakers pursue cylinder deactivation strategies requiring instantaneous transient response. European passenger car manufacturers are adopting 48-volt architectures at scale, compressing the competitive window for conventional wastegate turbos in segments above 150 kW output.
EPA tailpipe standards are forcing turbocharger suppliers to certify particulate filtration compatibility across all diesel applications. The regulatory consequence is a hardware redesign cycle for turbine housing geometries to accommodate downstream diesel particulate filter integration, with commercial vehicle platforms bearing the heaviest compliance burden.
Fleet procurement patterns are consolidating around total cost of ownership metrics that weight fuel economy gains against turbocharger replacement intervals. North American freight operators are negotiating powertrain-as-a-service contracts that bundle turbo maintenance into per-mile pricing, displacing traditional component sourcing through independent distributors.
Turbocharger Market Segmentation
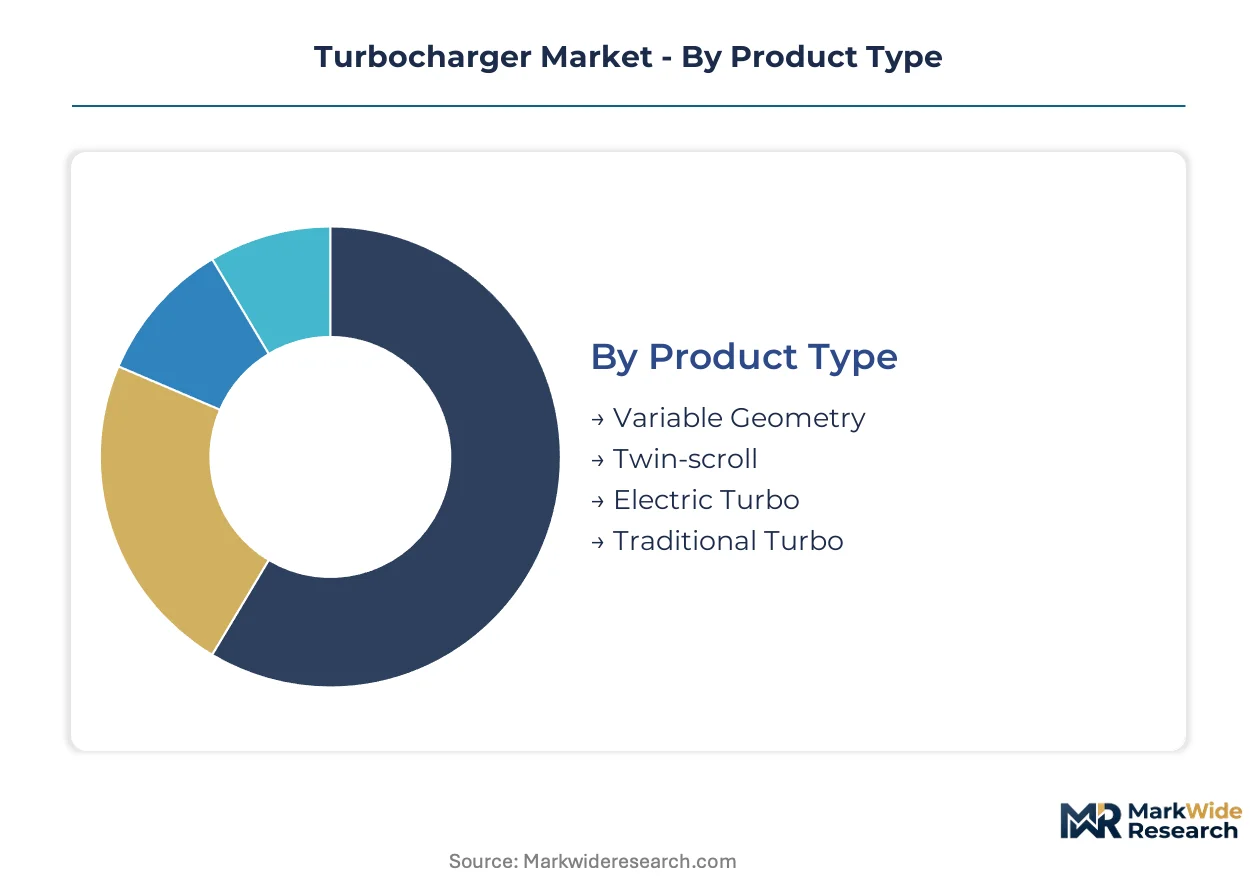
Turbocharger segmentation reveals how forced-induction architectures diverge across combustion chemistries and duty cycles. Suppliers configure compressor maps, bearing systems, and housing geometries to match specific thermal and transient requirements.
Product Type:
Standalone turbocharger assemblies dominate aftermarket replacement channels, while embedded electric-assist systems integrate with 48-volt mild-hybrid power electronics.
- Variable Geometry:Movable vane rings adjust turbine inlet area across engine speed ranges, optimizing exhaust pulse energy recovery. German commercial vehicle fleets specify these for Euro 7 pre-compliance in long-haul diesel platforms.
- Electric Turbo:Motor-generator units eliminate turbo lag through independent compressor spooling. Silicon carbide inverters from Garrett Motion enable sustained operation above 200,000 rpm, attracting gasoline direct-injection programs from Stuttgart and Wolfsburg.
- Twin-scroll:Separated exhaust manifold runners preserve pulse energy for rapid transient response in cylinder-deactivation architectures.
- Traditional Turbo:Fixed-geometry wastegate designs retain cost advantage in emerging market commercial vehicles where diagnostic integration requirements remain less stringent.
Variable geometry leads volumes today; electric turbo is gaining share fastest.
Fuel Type:
Cost tiering separates premium alloy specifications for high-thermal-load applications from standard-grade castings for moderate-duty cycles.
- Diesel:Sustained high-boost operation demands Inconel turbine wheels and liquid-cooled bearing housings. EPA Tier 4 enforcement in the United States and Euro 7 proposals in Germany are mandating particulate filtration compatibility, forcing housing geometry redesigns.
- Gasoline:Higher exhaust gas temperatures require nickel-based superalloys in turbine wheels. Japanese kei-car manufacturers below 660 cc displacement favor compact turbo configurations under METI fuel-economy benchmarks.
- Natural Gas:Lower combustion temperatures permit reduced material specifications, though methane slip regulations complicate catalyst integration.
- Biofuels:Corrosive combustion byproducts from fatty acid methyl esters accelerate turbine housing degradation, requiring specialized coating systems.
Diesel anchors current revenue; gasoline applications are climbing the fastest.
End User:
Application-specific duty cycles dictate bearing system selection, with aviation and marine programs emphasizing reliability over transient response.
- Automotive:Passenger car and commercial vehicle platforms drive procurement scale. Indian manufacturers localize production to satisfy Bharat Stage VI phase-II without import duty exposure.
- Marine:Two-stroke low-speed diesel engines in merchant shipping require turbochargers with diameters exceeding one meter. Japanese shipbuilders rely on IHI Corporation and Mitsubishi Heavy Industries for compact marine configurations.
- Aviation:Auxiliary power units and turboprop engines specify air-cooled bearing systems for weight reduction.
- Industrial:Stationary power generation and oilfield equipment prioritize mean-time-between-overhaul metrics over fuel efficiency.
Automotive dominates unit shipments; marine exhibits the steepest expansion trajectory.
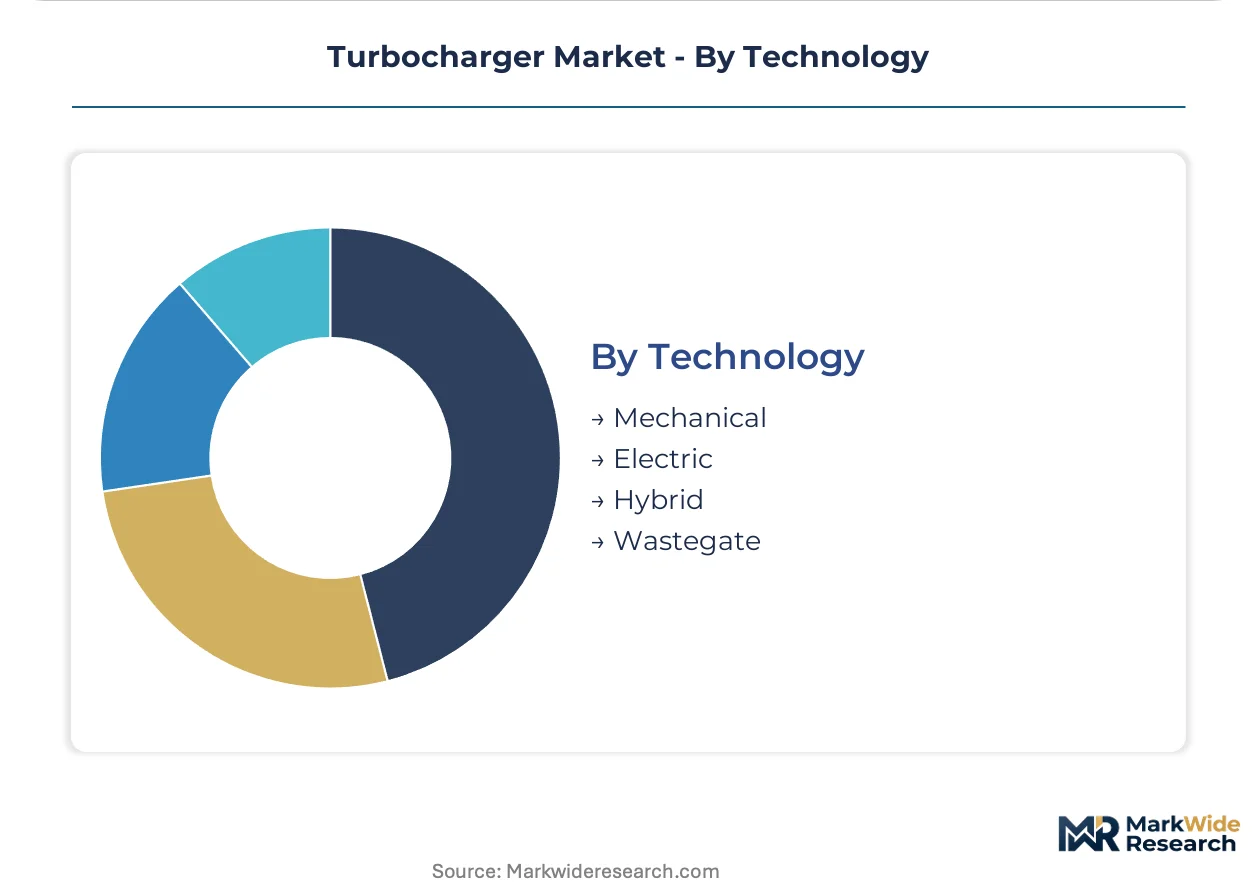
Technology:
Supply concentration favors captive foundry operations for mechanical turbos, while electric and hybrid architectures depend on semiconductor integration partnerships.
- Mechanical:Exhaust-gas-driven compressor systems without electrical augmentation retain installed base in cost-sensitive segments. BorgWarner's captive casting and machining operations sustain manufacturing scale across multiple continents.
- Hybrid:Combined exhaust turbine and electric motor architectures bridge performance gaps during transient load conditions. China's MIIT dual carbon goals for heavy-duty trucks are mandating adoption across diesel platforms above 3.0-liter displacement.
- Electric:Fully decoupled compressor systems eliminate exhaust gas dependency for initial spool-up.
- Wastegate:Pneumatic or electronic bypass valves limit maximum boost pressure in fixed-geometry applications.
Mechanical systems retain volume leadership; hybrid configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turbocharger manufacturing originated in Swiss precision engineering workshops during the 1920s before scaling through German automotive integration. Production lineage now spans captive foundry operations across three continents with distinct regulatory drivers shaping regional specialization.
Germany
Commercial vehicle fleets in Baden-Württemberg and Lower Saxony are retrofitting variable geometry turbos to preempt Euro 7 enforcement. The KBA mandates onboard diagnostic integration for all new diesel platforms above 3.5 tons. Stuttgart anchors a dense supplier ecosystem where Bosch and Continental coordinate tier-one procurement.
United States
Freight operators across the Midwest and Southeast are negotiating powertrain-as-a-service contracts that bundle turbo maintenance into per-mile pricing. EPA Tier 4 standards are forcing housing geometry redesigns for particulate filter compatibility. Michigan-based engineering clusters specialize in silicon carbide inverter integration for electric-assist architectures.
China
Heavy-duty truck manufacturers in Shandong and Jiangsu provinces are adopting twin-scroll configurations to satisfy MIIT dual carbon fuel-economy benchmarks. The ministry mandates turbo adoption across diesel platforms above 3.0-liter displacement. Yangtze River Delta foundries supply captive casting operations for domestic and export markets.
Japan
Kei-car manufacturers below 660 cc displacement favor compact turbo configurations under METI fuel-economy benchmarks. Nagoya-based shipbuilders rely on IHI Corporation and Mitsubishi Heavy Industries for marine turbocharger supply chains. Kansai industrial corridors concentrate precision machining capacity for aviation auxiliary power units.
India
Domestic commercial vehicle manufacturers in Maharashtra and Tamil Nadu are localizing turbocharger production to satisfy Bharat Stage VI phase-II enforcement. BIS emission norms are eliminating import duty exposure for non-compliant suppliers. Pune and Chennai industrial zones host joint ventures between global tier-ones and domestic foundries.
Turbocharger Market Competitive Environment
Premium-margin players sit above commodity-margin players across electric-assist integration capability and foundry alloy specifications. The market structures around three tiers: integrated power electronics specialists, captive casting operations with continental scale, and regional marine-industrial specialists. Strategic archetypes include silicon carbide inverter integrators, multi-continent manufacturing consolidators, and compact marine configuration experts. Dominant competitive moves center on semiconductor partnership formation and backward integration into nickel superalloy supply.
Among Germany-based tier-one suppliers, Continental AG and MAHLE GmbH exemplify the integrated-systems archetype spanning powertrain electronics and forced-induction hardware. Garrett Motion Inc. and BorgWarner Inc. represent the transnational manufacturing tier with captive operations across multiple continents. Japanese industrial conglomerates IHI Corporation and Mitsubishi Heavy Industries occupy specialized positions in marine and aviation turbocharger configurations.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Garrett Motion Inc. |
| Mitsubishi Heavy Industries Ltd. |
| IHI Corporation |
| Cummins Inc. |
| Continental AG |
| Honeywell International Inc. |
| MAHLE GmbH |
| ABB Ltd. |
| Others |
Value Chain & Pricing Dynamics
Freight operators negotiating powertrain-as-a-service contracts concentrate procurement leverage among North American and European fleet managers, compressing component pricing into bundled per-mile structures that favor suppliers with captive aftermarket service networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide inverter-integrated electric turbos from conventional variable geometry units and fixed-geometry wastegate designs. Price differentiation hinges on Euro 7 certification grade and foundry alloy specifications, with Inconel turbine wheels commanding substantial premiums over standard castings. Cost compression in the economy tier is intensifying because Indonesian nickel supply disruptions feed raw material volatility. Fleet procurement managers exhibit highest price sensitivity, while marine and aviation programs prioritize mean-time-between-overhaul reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Volkswagen Group and Stuttgart-based manufacturers, while independent distributors serve fragmented aftermarket replacement. Geographic concentration centers on Germany, China, and Japan, with Yangtze River Delta foundries feeding captive casting operations. Raw material dependencies draw from Indonesian nickel concessions, silicon carbide wafer supply from Japan, and precision bearing steel from Sweden. Single-source vulnerability persists in marine turbocharger supply where Japanese industrial conglomerates dominate merchant shipping configurations. Distribution runs through tier-one supplier consolidation around Bosch and Continental procurement coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as commercial vehicle fleets prioritize total cost of ownership metrics that weight fuel economy gains against replacement intervals, elevating premium electric-assist architectures over commodity turbos.
For Market Incumbents: Acquire silicon carbide inverter integration capabilities to defend against semiconductor specialists entering electrified turbo supply. Deepen backward integration into nickel superalloy supply to buffer Indonesian mining concession volatility. Secure captive aftermarket service networks before fleet powertrain-as-a-service contracts consolidate procurement channels.
For New Entrants and Emerging Players: Begin with Indian commercial vehicle localization partnerships to exploit Bharat Stage VI phase-II enforcement without import duty exposure. Target compact marine turbo configurations where Japanese supplier concentration creates single-source vulnerability for shipbuilders. Pursue joint development agreements with Yangtze River Delta foundries to access China MIIT dual carbon compliance channels.
For Investors and Strategic Acquirers: Tier-one automotive electronics suppliers are the most active acquirer in this space, seeking forced-induction hardware to complement 48-volt mild-hybrid power electronics portfolios. Target foundry operations with Inconel casting expertise and established EPA Tier 4 certification track records. Monitor Euro 7 pre-certification timeline compression as inflection indicator for platform launch delays that would strain supplier working capital.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Garrett Motion leverages wide-bandgap semiconductors to sustain motor operation above 200,000 rpm shaft speeds. |
| Captive Nickel Superalloy Supply | BorgWarner's backward integration into Inconel turbine wheel production buffers Indonesian mining concession disruptions. |
| Marine Electrification Convergence | IHI Corporation integrates electric turbos with battery-hybrid propulsion for harbor maneuvering auxiliary power applications. |
| Indian Localization Partnerships | Domestic manufacturers in Maharashtra and Tamil Nadu satisfy Bharat Stage VI phase-II without import duty exposure. |
| Powertrain-as-a-Service Bundling | North American freight operators consolidate turbo maintenance into per-mile pricing, displacing independent distributor channels. |
Study Parameters
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each combining structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors. Secondary validation draws from EPA Tier 4 enforcement filings, KBA type-approval databases, MIIT fuel-economy benchmark disclosures, and METI kei-car certification records. Bottom-up unit shipment estimates triangulate against top-down value projections across mechanical, hybrid, and electric technology segments.
Rate-of-change decomposition separates volume expansion from mix-shift effects across variable geometry, electric turbo, twin-scroll, and traditional wastegate product types. The analytical framework models fuel type segmentation, end user application, and technology architecture throughout the forecast period. CAGRs derive from production run-rate assumptions tied to Euro 7 and EPA enforcement timelines, with India BIS and China MIIT regulatory milestones as additional forecast inputs.
Several conditions sit outside the modeled scope, including speculative battery-electric vehicle adoption curves that would eliminate turbocharger content, and unilateral trade policy shifts affecting nickel alloy tariff exposure. Forecasts reflect assumptions about regulatory enforcement consistency and semiconductor supply normalization. Periodic stress-testing of base assumptions is recommended against Euro 7 pre-certification delays and Indonesian mining concession policy volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Automotive Powertrain Market
Powertrain
Timing Belt Kits Market
Powertrain
North America Torque Vectoring Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Racing Clutches Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Automotive Timing Chain and Belt Market