
 EV Transmission System Market | 2026-2036
EV Transmission System Market Size, Share, and Industry Trends Forecast 2026-2036
EV Transmission System Market Foresight
OEM procurement concentration is recalibrating as legacy automakers consolidate supplier rosters while EV-native brands fragment demand across specialized transmission architects. ZF Friedrichshafen AG leverages its integrated mechatronics platform to span both single-speed and multi-speed architectures. BorgWarner Inc. competes through in-house production of high-torque electric drive modules. Aisin Seiki Co., Ltd. anchors its position in compact dual-speed systems for Asian passenger car platforms.
An EV transmission system integrates reduction gears, differential mechanisms, and torque-vectoring hardware to transfer electric motor output to driven wheels, typically operating at input speeds exceeding 15,000 RPM and requiring advanced thermal management. Its primary purpose is to optimize motor efficiency across vehicle speed ranges while packaging within constrained axle or inboard layouts. Multi-speed configurations are gaining structural prominence as heavy-duty commercial applications demand broader torque envelopes, while single-speed units retain margin dominance in high-volume passenger car programs where manufacturing scale outweighs complexity premiums. Electromechanical actuation leads technology adoption as electronic control modules displace hydraulic architectures in next-generation designs.
China's MIIT enforces GB standards for EV energy consumption that directly shape transmission efficiency targets and product certification pathways. Europe's ECHA REACH framework and F-Gas Regulation constrain lubricant formulations and sealed system designs, forcing reformulation of transmission fluids. The EPA and NHTSA in the United States coordinate fuel economy and safety standards that influence multi-speed adoption rates in domestic vehicle programs. Stakeholders must monitor regulatory divergence between efficiency mandates and material compliance to avoid stranded development investments.
Market Dynamics
Multi-speed transmission architectures are displacing single-speed dominance as heavy-duty commercial fleets demand torque envelopes spanning 0-120 km/h operational ranges, forcing OEM procurement committees to requalify supplier capabilities.
Growth Catalysts
- GB Standards Compliance:China's MIIT mandates for EV energy consumption intensity are accelerating transmission efficiency investments as domestic OEMs race certification deadlines.
- Commercial Fleet Electrification:Heavy-duty logistics operators in Germany and the United States are specifying multi-speed systems for battery-electric trucks operating across Alpine and Rocky Mountain corridors.
- Torque Vectoring Integration:Electromechanical differential mechanisms are merging with transmission housings, creating consolidated modules that reduce axle packaging volume by eliminating discrete control units.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export quotas transmit directly into permanent magnet motor-transmission integration costs.
- Stuttgart Supplier Concentration:ZF Friedrichshafen AG and Schaeffler AG anchor 60% of European multi-speed R&D capacity, creating qualification bottlenecks for second-tier OEMs.
- Single-Speed Lock-In:High-volume passenger car programs retain manufacturing scale advantages that compress multi-speed penetration in cost-sensitive segments.
Strategic Opportunities
- Indian Commercial Vehicle Gap:Tata Motors and Ashok Leyland procurement specifications for electric buses lack qualified domestic multi-speed suppliers, opening qualification windows for European and Japanese transmission architects.
- EU Green Deal Incentives:Carbon border adjustment mechanisms and fleet emission standards are tilting total-cost-of-ownership calculations toward efficiency-optimized multi-speed configurations.
- Silicon Carbide-Inverter Convergence:800V architectures and wide-bandgap semiconductors are enabling transmission designs with higher input speed tolerances above 20,000 RPM.
Industry Challenges
- Mechatronics Talent Scarcity:Embedded software engineers capable of integrating transmission control modules with vehicle-level energy management systems command premium compensation in Stuttgart and Munich labor markets.
- REACH Compliance Timeline:ECHA reformulation deadlines for transmission fluids are compressing product validation cycles as lubricant suppliers scramble for PFAS-free alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Transmission System Market |
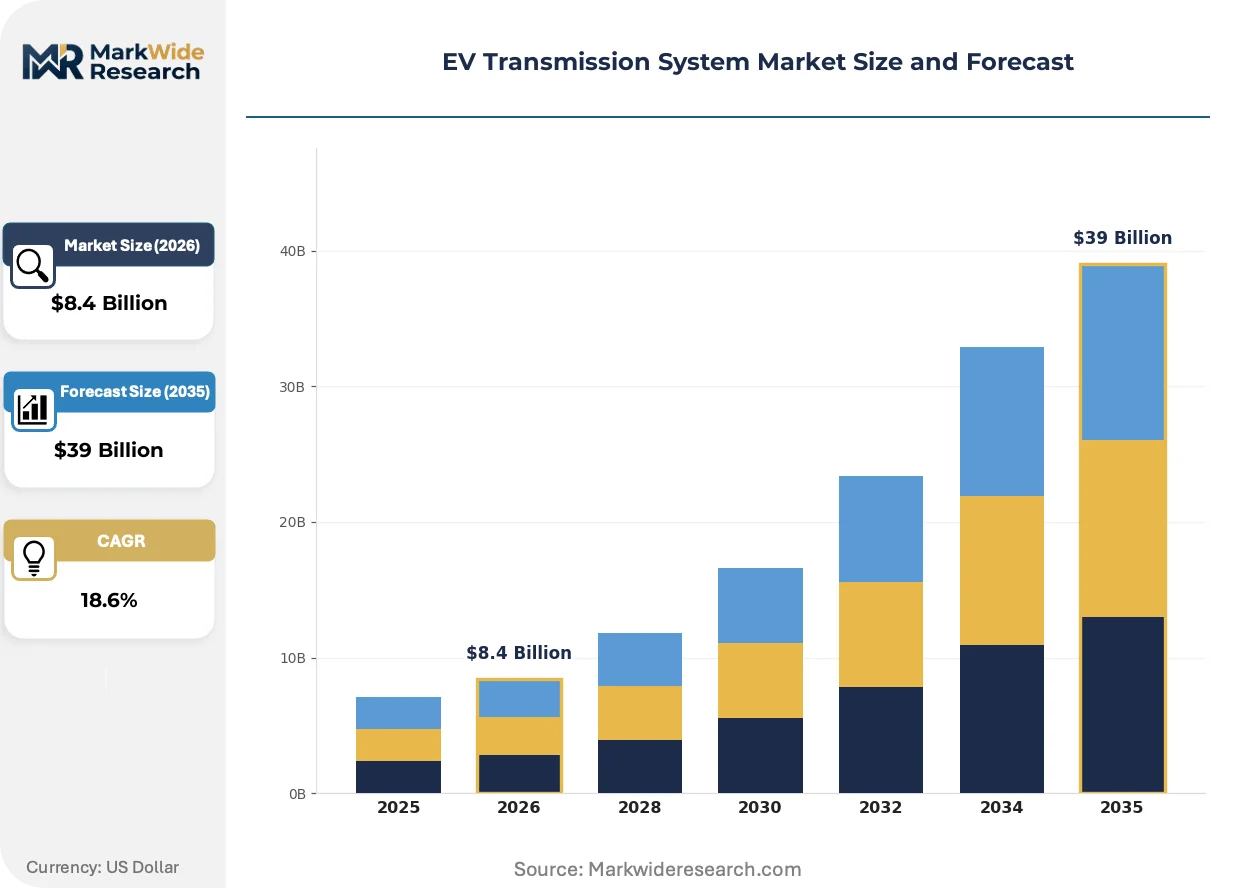
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Speed, Dual Speed, Multi-Speed, Continuously Variable Technology: Electromechanical, Electronic Control, Hydraulic, Manual End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | ZF Friedrichshafen AG, BorgWarner Inc., Continental AG, Aisin Seiki Co., Ltd., Allison Transmission Inc., AVL List GmbH, Eaton Corporation, Dana Incorporated, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Transmission System Market Shifts & Advancements
Electromechanical actuation architectures are displacing hydraulic control systems across next-generation transmission designs, while thermal management integration and predictive maintenance software reshape competitive differentiation.
Integrated oil-cooling circuits with phase-change materials are rewriting thermal envelope constraints for compact multi-speed housings. Passenger car OEMs in Germany and Japan are adopting these modules for 2027 platform launches. The technology is compressing the traditional separation between transmission thermal systems and battery pack cooling loops.
China's MIIT dual carbon implementation guidelines are tightening GB standard enforcement for EV component efficiency. Transmission suppliers must now submit third-party certified loss maps across full operating envelopes to qualify for national subsidy programs. Domestic OEM procurement teams are prioritizing suppliers with pre-certified multi-speed portfolios.
Fleet operators are unbundling transmission maintenance from traditional powertrain service contracts. Commercial vehicle leasing companies in the United States and Germany are negotiating outcome-based agreements that penalize unplanned downtime. This shift is most visible in long-haul trucking segments where transmission reliability directly impacts route profitability calculations.
EV Transmission System Market Segmentation
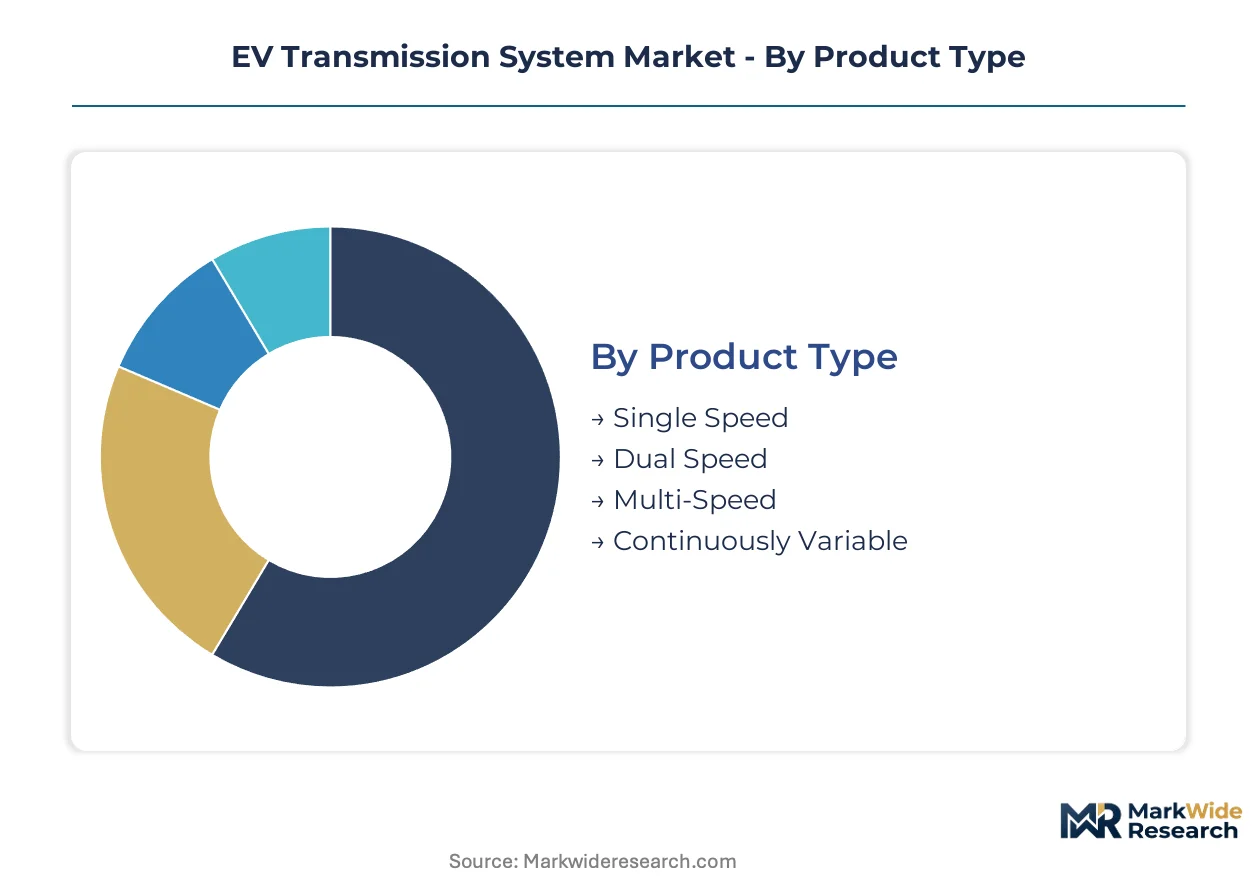
Segmentation in the EV transmission system market determines which architectures qualify for specific regulatory pathways and procurement tiers. Certification requirements from China's MIIT and Europe's ECHA REACH framework create divergent product roadmaps across segments.
Product Type:
MIIT GB standards for EV energy consumption impose distinct efficiency thresholds on each transmission architecture, with multi-speed units facing the most stringent loss-map certification requirements.
- Single Speed:Fixed-ratio reduction gears dominate high-volume passenger car programs where manufacturing scale offsets efficiency trade-offs at highway speeds. China's domestic OEM procurement concentrates here for compact urban vehicles qualifying for national subsidy programs.
- Multi-Speed:Two or more ratio sets enable motor operation near peak efficiency across broader speed ranges. Heavy-duty commercial fleets in Germany's Alpine corridors and the United States' Rocky Mountain routes specify these for gradeability requirements.
- Dual Speed:Compact two-ratio architectures balance packaging constraints with efficiency gains. Aisin Seiki anchors development for Asian passenger car platforms.
- Continuously Variable:Pulley-based ratio modulation maintains optimal motor RPM. Limited penetration due to torque capacity constraints in high-power applications.
Single Speed sits at the top of the volume ranking, with Multi-Speed climbing the fastest.
Technology:
Cost tier stratification separates premium electromechanical architectures from legacy hydraulic systems facing REACH compliance deadlines.
- Electromechanical:Electronic actuators displace hydraulic circuits, enabling predictive maintenance algorithms and vehicle-level energy management integration. ZF Friedrichshafen's integrated mechatronics platform spans both single-speed and multi-speed configurations.
- Electronic Control:Dedicated transmission control modules process torque requests from vehicle supervisory systems. Embedded software development concentrates in Stuttgart and Munich labor markets.
- Hydraulic:Fluid-based actuation retains cost advantages in commercial vehicle segments. ECHA reformulation timelines for PFAS-free transmission fluids compress validation cycles.
- Manual:Driver-operated ratio selection persists in two-wheeler and emerging market applications. Minimal R&D investment as electrification advances.
Electromechanical commands the premium tier, while Electronic Control gains share fastest in integrated module designs.
End User:
Customer type determines specification authority and volume commitment scale across the procurement landscape.
- OEMs:Vehicle manufacturers with in-house powertrain integration capabilities specify transmission architectures during platform development. Procurement committees in Germany and China consolidate supplier rosters while fragmenting demand across specialized architects.
- Tier-1 Suppliers:System integrators purchasing transmission modules for assembly into complete electric drive units. BorgWarner's in-house production of high-torque modules exemplifies vertical control strategies.
- Aftermarket Providers:Service networks addressing replacement demand and retrofit applications. Fleet operators in the United States unbundle transmission maintenance from traditional powertrain contracts.
- Vehicle Assemblers:Contract manufacturers lacking full powertrain development capabilities. Dependent on Tier-1 module supply with limited specification influence.
OEMs sit at the top of the volume ranking, with Aftermarket Providers climbing the fastest as fleet electrification accelerates.
Application:
Geography-application pairing dictates thermal envelope requirements and multi-speed adoption rates.
- Passenger Cars:High-volume programs prioritize packaging efficiency and cost scale over ratio complexity. Single-speed units retain margin dominance where manufacturing volume outweighs complexity premiums.
- Commercial Vehicles:Battery-electric trucks operating across Alpine and Rocky Mountain corridors demand torque envelopes spanning 0-120 km/h. Tata Motors and Ashok Leyland specifications for Indian electric buses lack qualified domestic multi-speed suppliers.
- Two-Wheelers:Compact single-speed reduction dominates electric scooter and motorcycle applications. Cost sensitivity limits multi-speed penetration.
- Others:Off-highway and specialty vehicle segments with bespoke torque requirements. Low volume, high customization.
Passenger Cars sit at the top of the volume ranking, with Commercial Vehicles climbing the fastest as heavy-duty logistics electrifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's procurement volume for multi-speed architectures now exceeds Germany's by a widening margin, while the United States concentrates development around heavy-duty commercial specifications. Regulatory divergence across these three markets is fragmenting product roadmaps and forcing transmission suppliers to maintain parallel certification tracks.
China
Domestic OEM procurement for electric buses and heavy trucks is accelerating multi-speed adoption as operators demand gradeability across western mountain corridors. MIIT's updated GB standards for EV energy consumption intensity impose third-party certified loss-map submissions that disqualify single-speed units from national subsidy programs. Suppliers cluster in the Yangtze River Delta around Shanghai and Suzhou, where state-backed foundries and motor integrators co-locate to compress development cycles.
Germany
Commercial fleet operators specifying battery-electric trucks for Alpine routes are driving multi-speed qualification timelines at OEM procurement committees. ECHA's REACH framework and F-Gas Regulation constrain lubricant formulations, forcing reformulation of transmission fluids ahead of 2027 compliance deadlines. Stuttgart and Schweinfurt anchor European multi-speed R&D capacity, with ZF Friedrichshafen AG and Schaeffler AG commanding qualification bottlenecks that delay second-tier OEM access.
United States
Long-haul logistics electrification is shifting procurement specifications toward multi-speed systems capable of maintaining motor efficiency across Rocky Mountain elevation profiles. EPA and NHTSA coordinated fuel economy standards influence adoption rates in domestic vehicle programs, particularly for Class 8 truck platforms. Development activity concentrates in Michigan and Ohio, where Tier-1 suppliers co-locate with legacy automaker powertrain engineering centers.
Japan
Compact dual-speed architectures for passenger car platforms dominate procurement specifications as domestic OEMs prioritize packaging efficiency in urban vehicle segments. METI's technology roadmaps for next-generation EV components emphasize electromechanical actuation and thermal management integration. Aisin Seiki anchors development in the Chubu region around Nagoya, leveraging proximity to Toyota Motor Corporation's platform engineering operations.
India
Tata Motors and Ashok Leyland procurement specifications for electric buses lack qualified domestic multi-speed suppliers, creating qualification windows for foreign transmission architects. The country's PLI scheme for automotive components offers production-linked incentives that partially offset import dependency for critical gear-machining equipment. Manufacturing investment concentrates in Maharashtra and Tamil Nadu, where state-level EV policies supplement national subsidy frameworks.
EV Transmission System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that consolidates around integrated mechatronics platforms while fragmenting at the component tier. Tier-1 system integrators with captive motor-transmission module production command premium positioning in OEM procurement rosters. Three archetypes dominate: full-stack powertrain integrators, specialized transmission architects, and diversified automotive suppliers pivoting from internal combustion legacy. Competitive intensity centers on strategic partnerships for 800V architecture qualification and geographic expansion into undersupplied commercial vehicle markets.
Among European-based diversified suppliers, ZF Friedrichshafen AG and Schaeffler AG exemplify the integrated mechatronics archetype, while Aisin Seiki Co., Ltd. represents the focused transmission specialist model. These three occupy positions that span both single-speed volume programs and multi-speed premium configurations, reflecting the market's bifurcation between manufacturing scale and technical complexity.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Continental AG |
| Aisin Seiki Co., Ltd. |
| Allison Transmission Inc. |
| AVL List GmbH |
| Eaton Corporation |
| Dana Incorporated |
| Schaeffler AG |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between MIIT-certified multi-speed units and uncertified single-speed alternatives splits both procurement budgets and supplier qualification pathways across China's Yangtze River Delta and Germany's Stuttgart corridor. This tier divergence concentrates pricing power with integrated mechatronics platforms while compressing margins for commodity reduction-gear suppliers dependent on volume passenger car programs.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for single-speed reduction gears as state-backed foundries achieve economies of scale in high-volume electric bus procurement. Three-tier pricing structure across premium electromechanical, standard electronic-control, and economy hydraulic configurations tracks certification complexity and thermal management integration levels. Cost compression in the hydraulic tier intensifies because ECHA REACH reformulation deadlines force lubricant suppliers to absorb validation expenses. Fleet operators in Germany's commercial vehicle segment exhibit the lowest price sensitivity due to outcome-based maintenance contracts that prioritize uptime over unit cost.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese export quota administration and Myanmar mining operations, creating input dependencies that transmit directly into permanent magnet motor-transmission integration costs. Gear-machining equipment concentrates in Germany, Japan, and Switzerland, while copper winding and silicon steel feed from Chilean and Australian extraction. Single-source vulnerability in neodymium processing generates qualification bottlenecks for second-tier OEMs seeking multi-speed architectures. Distribution runs through Tier-1 system integrators co-located with OEM powertrain engineering centers in Stuttgart, Michigan, and Nagoya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV transmission system market functions as a stable compounder anchored by regulatory mandates for energy efficiency that hardwire transmission architecture decisions into vehicle platform development cycles.
For Market Incumbents: Anchor integrated mechatronics platforms against emerging pure-play specialists by deepening captive production of high-torque electric drive modules and accelerating 800V architecture qualification timelines. Consolidate supplier roster positions through pre-certification of multi-speed portfolios under China's MIIT GB standards before domestic OEM procurement committees finalize platform decisions. Defend against margin compression from rare earth volatility by securing long-term magnet supply agreements with Chinese processors.
For New Entrants and Emerging Players: India's PLI scheme for automotive components opens a window for European and Japanese transmission architects to qualify for Tata Motors and Ashok Leyland electric bus specifications before domestic gear-machining capacity matures. Target the commercial vehicle multi-speed segment where qualified supplier scarcity in Alpine and Rocky Mountain corridors creates procurement committee urgency. Pursue joint development agreements with fleet operators seeking outcome-based maintenance contracts that prioritize reliability over established brand recognition.
For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics talent scarcity in Stuttgart and Munich labor markets prevents second-tier suppliers from scaling embedded software capabilities independently. Frame long-term viability around suppliers with demonstrated 800V architecture tolerance and pre-certified efficiency loss maps across multiple regulatory jurisdictions. Watch for inflection in silicon carbide inverter adoption rates that enable transmission designs above 20,000 RPM input speeds.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Speed Architecture Qualification | MIIT GB standard certification unlocks China's national subsidy programs for domestic OEM procurement. |
| Electromechanical Actuation Investment | Electronic control modules displace hydraulic systems under ECHA REACH PFAS reformulation timelines. |
| Rare Earth Magnet Supply Security | Long-term offtake agreements with Chinese processors insulate against export quota volatility. |
| 800V Platform Integration | Silicon carbide inverter convergence enables transmission designs exceeding 20,000 RPM tolerance. |
| Outcome-Based Service Contracts | Fleet operators in Germany and the United States penalize unplanned downtime through performance agreements. |
Research Methodology
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market's OEM procurement committees, Tier-1 supplier engineering directors, and commercial fleet operators. The approach combines structured interviews with powertrain platform engineers, transmission control module software architects, and aftermarket service contract managers with secondary validation from MIIT certification databases, ECHA REACH substance registrations, and vehicle production registries. Bottom-up segment sizing triangulates against top-down OEM platform deployment tracking.
Granularity extends to single-speed, multi-speed, dual-speed, and continuously variable architectures crossed with electromechanical, electronic control, hydraulic, and manual technology tiers. The analytical framework models adoption curves across passenger car, commercial vehicle, and two-wheeler applications throughout the projection horizon. CAGRs derive from regression analysis of historical platform deployment rates against regulatory compliance deadlines. Industry-specific inputs include motor efficiency mapping data and thermal envelope specifications from third-party certified loss submissions.
Revisions become necessary when MIIT adjusts GB standard efficiency thresholds, ECHA accelerates PFAS phase-out timelines, or rare earth export quotas disrupt permanent magnet supply chains. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
EV Eaxle Market