
 Japan Electro Hydraulic Power Steering Market | 2026-2036
Japan Electro Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Electro Hydraulic Power Steering Market Foresight
Skilled mechatronics engineers is rotating toward electrified steering architectures as Japanese automakers phase out pure hydraulic systems. JTEKT Corporation leverages its integrated production of steering columns and electronic control units to dominate OEM supply contracts. NSK Ltd anchors its position through precision bearing technology that reduces EHPS friction losses. Hitachi Astemo, Ltd. competes by combining brake-steer integration expertise with software-defined vehicle platforms.
Electro hydraulic power steering fuses a hydraulic pump driven by an electric motor with electronic control modules, modulating assist force through pulse-width-modulated solenoid valves at pressures typically spanning 8-13 MPa. The system delivers variable steering assistance to reduce engine parasitic load while preserving hydraulic road feel. Sedan and SUV vehicle types absorb the dominant share of EHPS volume as Japanese manufacturers prioritize these platforms for hybrid powertrain compatibility. Medium and high power ratings command the strongest margin pools due to their requirement for advanced thermal management and sensor arrays. Control module and actuator components represent the fastest-expanding segment as software calibration complexity rises.
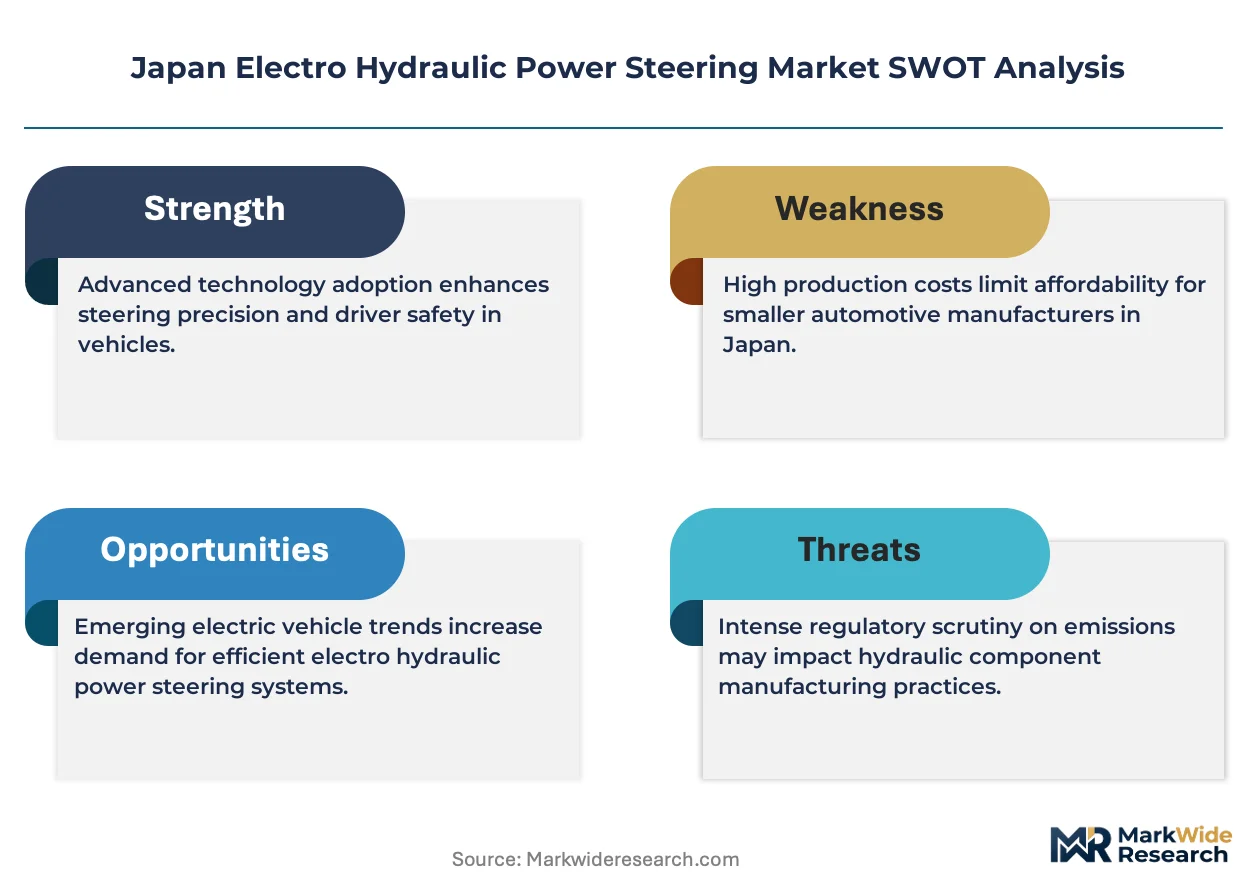
METI fuel-efficiency standards and JIS D 5601 vehicle steering performance specifications shape product development timelines and validation protocols for EHPS suppliers in Japan. PMDA-adjacent automotive functional safety expectations, imported from medical device reliability culture, increasingly influence steering system fail-safe architectures. Stakeholders must monitor how METI's next-phase carbon neutrality roadmaps recalibrate the boundary between EHPS and full steer-by-wire investment.
Market Dynamics
Japanese automakers face irreversible pressure from METI carbon neutrality roadmaps that recalibrate investment boundaries between electro hydraulic architectures and full steer-by-wire systems. Tier-1 suppliers must now engineer dual-capability platforms while maintaining JIS D 5601 compliance.
Growth Catalysts
- Hybrid SUV platform expansion:Japanese OEMs integrate EHPS into electrified utility vehicles to satisfy METI fuel-efficiency mandates without sacrificing hydraulic road feel.
- Sensor fusion advancement:Multi-axis torque and position sensing enables predictive steering assistance algorithms that reduce energy consumption during urban stop-start cycles.
- Kanto corridor clustering:Proximity between JTEKT, NSK, and Hitachi Astemo production facilities in Tokyo-Yokohama compresses prototype-to-validation timelines.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings destabilize brushless motor manufacturing economics for EHPS actuators.
- Single-source hydraulic valve supply:Precision solenoid manufacturing concentrates among a handful of Nagoya-area specialists, creating vulnerability to disruption.
- Full electric steering substitution:Steer-by-wire systems eliminate hydraulic infrastructure entirely, threatening EHPS relevance in next-generation vehicle architectures.
Strategic Opportunities
- Software-defined vehicle convergence:EHPS control modules that integrate with brake-by-wire and ADAS compute platforms open new value pools in chassis-domain centralization.
- Retrofit aftermarket in commercial vehicles:Aging Kei truck and light commercial fleets present upgrade paths for EHPS conversion kits that improve maneuverability.
- Osaka-Kobe industrial corridor expansion:Western Japan manufacturing clusters remain underdeveloped for EHPS component sourcing relative to Kanto.
Industry Challenges
- Mechatronics talent scarcity:Japanese engineering schools produce insufficient graduates fluent in both hydraulic system design and embedded software calibration.
- JIS D 5601 validation timeline compression:Updated steering performance specifications demand extended durability testing that extends product launch cycles.
- Legacy hydraulic toolpath obsolescence:Machine shops must retool for electric motor housing precision while maintaining hydraulic component production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Electro Hydraulic Power Steering Market |
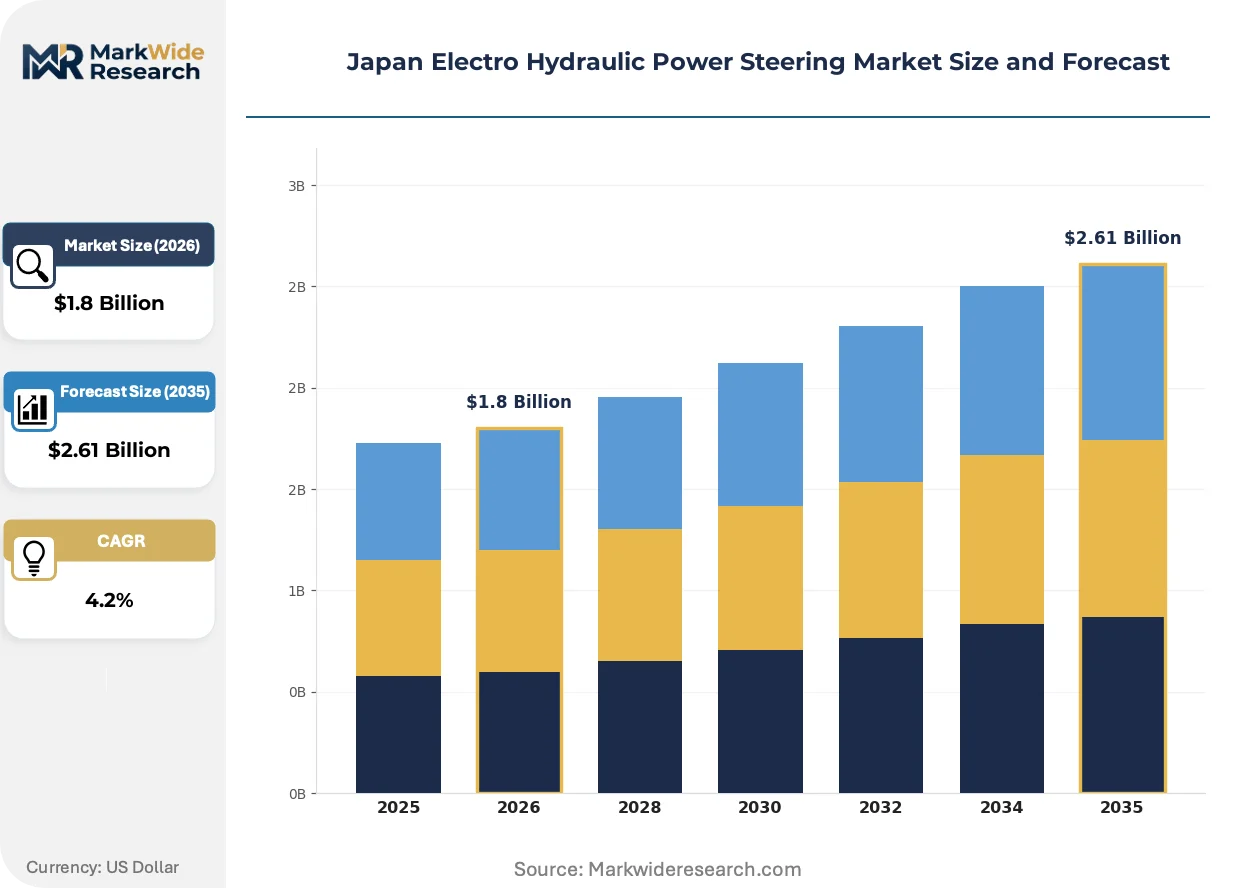
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Component: Steering Wheel, Pump, Actuator, Control Module Power Rating: Low Power, Medium Power, High Power, Ultra High Power End User: OEMs, Aftermarket Providers, Fleet Operators, Tier-1 Suppliers |
| Companies Covered | JTEKT Corporation, NSK Ltd, Nexteer Automotive Group Ltd, ZF Friedrichshafen AG, Robert Bosch GmbH, Showa Group, Hitachi Astemo, Ltd., KYB Corporation, Continental AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Electro Hydraulic Power Steering Market Shifts & Advancements
Electro hydraulic power steering technology is undergoing fundamental rearchitecture as Japanese suppliers fuse electronic control sophistication with hydraulic mechanical reliability. Three convergent developments are reshaping competitive positioning.
Brushless DC motor designs are fragmenting the traditional EHPS supplier landscape by enabling pump units that operate independently of engine speed. Tier-1 integrators in Kanagawa Prefecture now source these motors from specialized producers rather than manufacturing in-house. This modularization compresses development cycles but erodes margin capture for vertically integrated incumbents.
METI's next-phase carbon neutrality roadmaps are forcing recalibration of R&D allocation between evolutionary EHPS refinement and revolutionary steer-by-wire development. Suppliers must maintain dual engineering tracks while JIS D 5601 validation protocols lengthen approval timelines. Medium and high power rating segments face the steepest compliance burden as thermal management requirements intensify.
Fleet procurement patterns in commercial vehicle segments are compressing supplier qualification cycles as logistics operators prioritize total cost of ownership over initial equipment price. Tier-2 distributors in Hokkaido and Kyushu now bundle EHPS installation with predictive maintenance contracts. This service unbundling shifts revenue recognition timing and demands new field engineering capabilities from component manufacturers.
Japan Electro Hydraulic Power Steering Market Segmentation
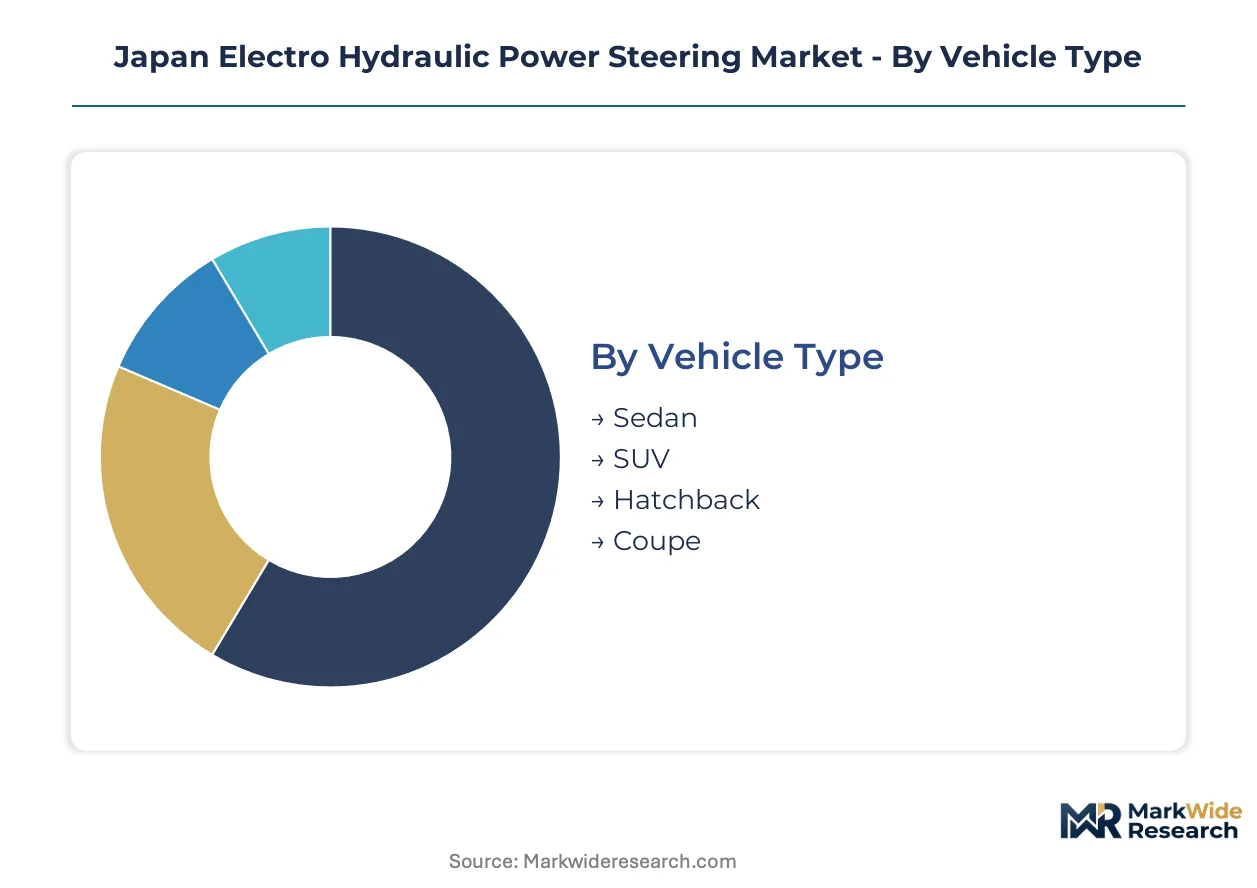
Segmentation in Japan's EHPS market reveals how METI regulatory pressure and hybrid platform engineering priorities concentrate value across distinct technical configurations. Suppliers must align component portfolios with specific vehicle architectures and powertrain integration requirements to capture margin in this transitionary technology phase.
Vehicle Type:
Margin pools concentrate in utility platforms where hybrid electrification mandates intersect with consumer preference for hydraulic steering feedback preservation.
- Sedan:Compact and mid-size sedan architectures integrate EHPS to balance fuel-efficiency targets with precise urban maneuverability. Toyota and Honda hybrid sedans in the Kanto corridor dominate procurement volume, driven by corporate fleet electrification timelines.
- SUV:Electrified utility vehicles command premium EHPS specifications to manage higher curb weights while satisfying METI efficiency benchmarks. Hybrid SUV platforms from Japanese OEMs absorb the dominant share of medium and high power rating production capacity.
- Hatchback:Kei car and compact hatchback segments deploy simplified EHPS variants with reduced pump displacement. Cost pressure from price-sensitive consumer segments constrains sensor array complexity in this category.
- Coupe:Performance-oriented two-door platforms prioritize steering precision and thermal stability for sustained track use. Low volume production runs limit supplier economies of scale despite higher per-unit margins.
Sedan holds installed capacity. SUV is rotating up the share rankings.
Component:
Supply concentration follows the technical complexity gradient from mechanical hardware to software-calibrated electronic modules.
- Steering Wheel:Torque sensor integration within the steering column assembly demands precision machining of splined interfaces. JTEKT and NSK facilities in Kanagawa Prefecture anchor domestic production for this mechanical-electrical boundary component.
- Pump:Brushless DC motor-driven hydraulic pumps operate at pressures spanning 8-13 MPa with pulse-width-modulated flow control. Rare-earth magnet cost volatility in neodymium and dysprosium supply chains destabilizes manufacturing economics for this actuator element.
- Actuator:Solenoid valve assemblies modulate assist force through electronic control unit commands. Nagoya-area precision manufacturers concentrate supply, creating single-source vulnerability for Tier-1 integrators.
- Control Module:Embedded software platforms execute predictive assistance algorithms through multi-axis sensor fusion. This segment is expanding most quickly as brake-steer integration and ADAS domain centralization drive calibration complexity.
Pump retains the largest production footprint. Control Module is climbing the fastest.
Power Rating:
Thermal management requirements and sensor density differentiate margin capture across the power spectrum.
- Medium Power:5-8 kW assist capacity serves compact hybrid SUVs and mid-size sedans with moderate curb weights. Kanto manufacturing corridors concentrate validation and production for this specification tier.
- High Power:8-12 kW output ratings address full-size SUVs and commercial vehicle platforms with elevated steering loads. Advanced thermal management and redundant sensor arrays command the strongest margin pools in this category.
- Low Power:Sub-5 kW systems target Kei vehicles and compact hatchbacks with weight-minimized architectures. Cost engineering pressure limits electronic feature content relative to higher rating tiers.
- Ultra High Power:Exceeding 12 kW output for heavy commercial applications and specialized industrial vehicles. Niche demand volume constrains dedicated production line investment.
Medium Power holds installed capacity. High Power is rotating up the share rankings.
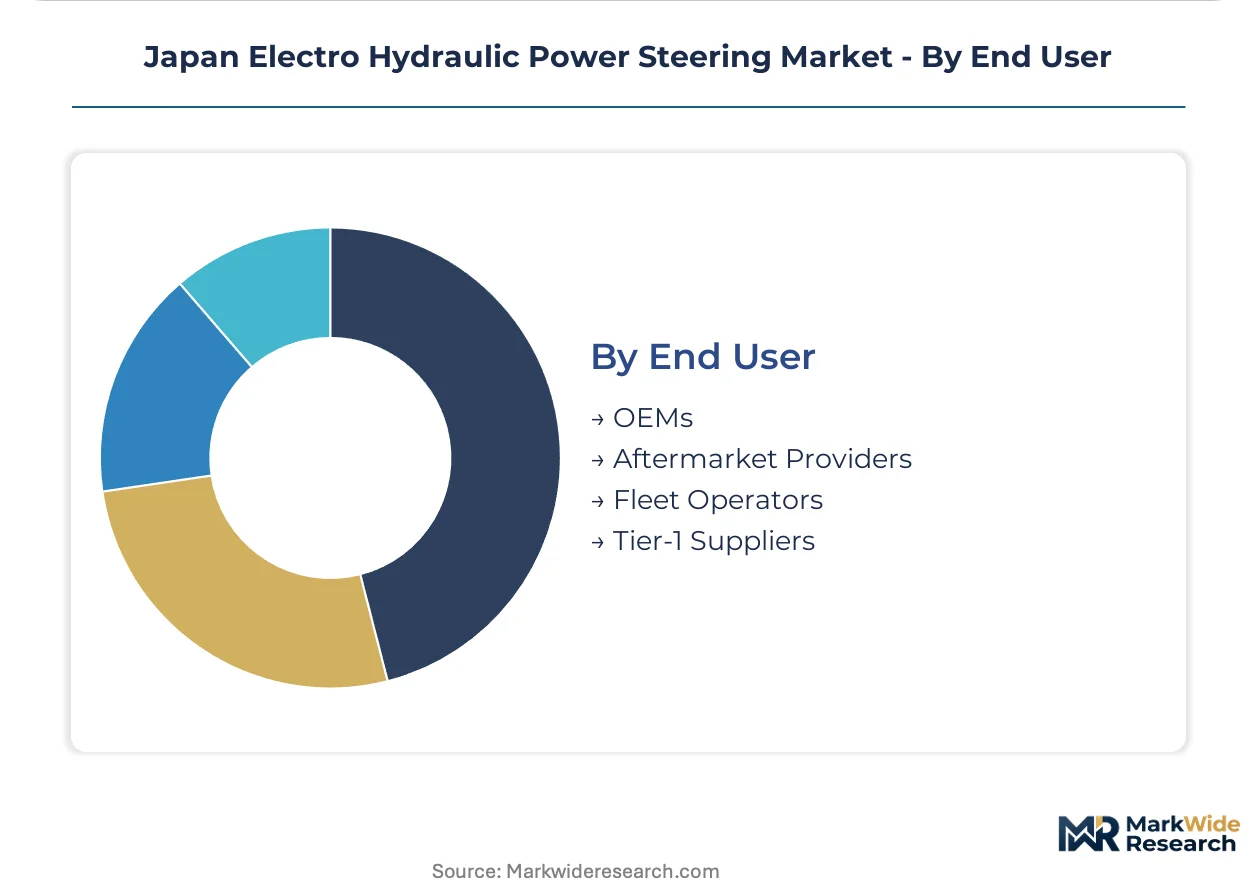
End User:
Procurement authority and qualification timelines segment the customer base across divergent commercial models.
- OEMs:Japanese automakers specify EHPS architectures during platform development cycles with JIS D 5601 compliance mandates. Toyota, Honda, and Nissan integration programs drive volume forecasting and capacity planning for Tier-1 suppliers.
- Fleet Operators:Logistics and commercial vehicle aggregators prioritize total cost of ownership over initial equipment price. Hokkaido and Kyushu distributors now bundle EHPS installation with predictive maintenance contracts, compressing supplier qualification cycles.
- Aftermarket Providers:Independent service networks address aging Kei truck and light commercial fleet upgrade demand. Conversion kit specifications lag OEM architectures by one to two product generations.
- Tier-1 Suppliers:System integrators such as Hitachi Astemo and JTEKT consolidate component sourcing for final assembly to OEM specifications. Their procurement decisions cascade through the Nagoya and Kanto supplier tiers.
OEMs hold installed capacity. Fleet Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI carbon neutrality mandates and JIS D 5601 steering specifications anchor Japan's EHPS development trajectory. Manufacturing corridors concentrate validation capacity and supplier clustering across distinct sub-regional economies.
Kanto
Tokyo-Yokohama manufacturing belt hosts JTEKT, NSK, and Hitachi Astemo production facilities with compressed prototype-to-validation timelines. METI fuel-efficiency standards drive hybrid SUV platform integration at OEM technical centers in Kanagawa Prefecture. Sensor fusion R&D concentrates in Tsukuba science city corridors.
Kansai
Osaka-Kobe industrial corridor remains underdeveloped for EHPS component sourcing relative to eastern manufacturing clusters. Kei truck fleet operators in Osaka Prefecture generate aftermarket conversion kit demand for aging commercial vehicles. Local machine shops retool for electric motor housing precision.
Chubu
Nagoya precision manufacturers concentrate supply of solenoid valve assemblies for Tier-1 integrators. Toyota integration programs in Aichi Prefecture drive medium power rating EHPS volume forecasting. Single-source hydraulic valve vulnerability concentrates among Nagoya-area specialists.
Kyushu
Logistics operators in Fukuoka Prefecture prioritize total cost of ownership in commercial vehicle procurement. Tier-2 distributors bundle EHPS installation with predictive maintenance contracts. Field engineering capabilities expand to service fleet upgrade demand.
Hokkaido
Commercial vehicle aggregators in Sapporo metropolitan area compress supplier qualification cycles. Aging light commercial fleets present retrofit aftermarket paths for EHPS conversion kits. Cold-climate thermal management requirements influence regional specification preferences.
Japan Electro Hydraulic Power Steering Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's EHPS supplier hierarchy. Vertically integrated incumbents capture OEM supply contracts through captive production of steering columns and electronic control units. Modular component specialists and precision machining houses occupy subordinate positions. Dominant competitive moves include backward integration into rare-earth magnet supply chains and software calibration capability acquisition.
Within the integrated systems tier, JTEKT Corporation and NSK Ltd occupy anchor positions through Kanto-based production footprints. Hitachi Astemo, Ltd. represents the brake-steer integration archetype. These three entities exemplify divergent strategic postures: column-electronics integration, precision bearing technology, and chassis-domain centralization respectively.
| Leading Market Players |
|---|
| JTEKT Corporation |
| NSK Ltd |
| Nexteer Automotive Group Ltd |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Showa Group |
| Hitachi Astemo, Ltd. |
| KYB Corporation |
| Continental AG |
| Others |
Supply & Pricing Matrix
Sixty-day prototype-to-validation cycles in Kanto manufacturing corridors compress supplier qualification timelines while concentrating pricing power among vertically integrated incumbents. This temporal compression reinforces margin capture for JTEKT and NSK, while modular component specialists face persistent cost pressure from rare-earth magnet volatility.
Pricing Analysis
Price spreads between Kanto and Osaka-Kobe corridors reflect logistics premiums and regional supplier density gaps. Three-tier pricing structure across premium, standard, and economy levels segments by power rating and sensor array complexity, with high-power EHPS commanding substantial premiums for thermal management. Cost compression in brushless DC motor sourcing is intensifying because neodymium and dysprosium price swings destabilize actuator manufacturing economics. Fleet operators in Kyushu and Hokkaido exhibit highest price sensitivity, prioritizing total cost of ownership over initial equipment outlay.
Supply Chain Analysis
Japan and China anchor EHPS component manufacturing, with Kanto facilities producing steering columns and electronic control units while Chinese suppliers dominate rare-earth magnet refining. Brushless DC motors, precision solenoid valves, and sensor fusion modules draw from concentrated Nagoya and Kanagawa production bases. Single-source vulnerability in hydraulic valve supply creates structural exposure to disruption among Tier-1 integrators. Distribution runs through OEM technical centers and Tier-2 fleet distributors bundling installation with predictive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics engineering fluency in both hydraulic design and embedded software calibration has become the constraining asset in Japan's EHPS supplier hierarchy, creating asymmetric returns for firms that consolidate this dual capability.
For Market Incumbents: Shield OEM supply contracts by deepening captive production of torque sensors and electronic control units against steer-by-wire substitution threats. Prioritize backward integration into rare-earth magnet supply chains to buffer neodymium cost volatility. Expand validation capacity in Kanagawa Prefecture to compress JIS D 5601 compliance timelines. For New Entrants and Emerging Players: Predictive maintenance service bundling represents the most penetrable white-space as incumbent Tier-1s under-serve fleet operators in western Japan. Target Osaka-Kobe corridor expansion for EHPS component sourcing where manufacturing clusters remain underdeveloped relative to Kanto. Pursue Kei truck aftermarket conversion kits through direct distributor partnerships in Hokkaido and Kyushu. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant steering system divisions lacking software-defined vehicle integration. Long-term viability hinges on dual-capability platforms spanning EHPS refinement and steer-by-wire development. Monitor METI carbon neutrality roadmap revisions as the critical inflection signal for R&D allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | EHPS control modules integrating with brake-by-wire and ADAS platforms capture chassis-domain centralization value pools. |
| Backward Integration into Rare-Earth Supply | Captive magnet sourcing insulates brushless DC motor production from dysprosium price volatility destabilizing actuator economics. |
| Geographic Manufacturing Footprint Expansion | Osaka-Kobe corridor facilities address underdeveloped western Japan component sourcing relative to Kanto concentration. |
| Platform Standardization | Dual-capability EHPS and steer-by-wire architectures reduce METI regulatory recalibration risk across product generations. |
| Aftermarket Service Partnership | Predictive maintenance contracts with Kyushu and Hokkaido distributors shift revenue recognition timing for Tier-2 channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 procurement directors, aftermarket distributors, and fleet maintenance managers. Secondary validation drew from METI fuel-efficiency filings, JIS D 5601 specification documents, vehicle production databases, and customs trade records for rare-earth magnet flows. Bottom-up component demand modeling and top-down OEM platform forecasts were triangulated to reconcile volume estimates.
Across the analysis window, projections segmented by vehicle type, power rating, component category, and end-user archetype to capture METI regulatory impacts and hybrid platform adoption curves. CAGRs were derived from weighted scenario modeling incorporating OEM electrification timelines and thermal management content per vehicle. Forecast inputs included JIS D 5601 validation timeline assumptions and rare-earth magnet price trajectory sensitivities.
Forecasts assume regulatory continuity in METI carbon neutrality roadmaps and JIS D 5601 steering specifications; material policy shifts would require re-modeling of R&D allocation scenarios. Supply chain disruption events, steer-by-wire technology acceleration, or rare-earth export restrictions represent specific revision triggers. Recalibration cycles align with material shifts in METI mandate phases and OEM platform electrification announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Turbocharger Actuators Market
Powertrain
Gear Reduction Starter Market
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Coil Spring Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Engine Actuators Market
Powertrain
Automotive Fluid Reservoir Market
Powertrain
Torque Converter Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Automotive Tuner Market
Powertrain
North America Precision Gearbox Market
Powertrain
Japan Electrically Powered Hydraulic Steering Market