
 Engine Flush Market | 2026-2036
Engine Flush Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Flush Market Analysis
The EU F-Gas Regulation is restructuring demand patterns across the engine flush value chain, compelling formulators to eliminate residual solvents with high global warming potential from pre-lube cleaning protocols. Valvoline Inc. leverages its captive blending network across North American refineries to secure feedstock continuity for low-VOC product lines. Liqui Moly GmbH anchors its position through German TÜV-certified formulations that command premium placement in European service centers. CRC Industries Inc. competes on aerosol delivery systems optimized for quick-lube bay throughput.
An engine flush is a solvent-detergent formulation, typically containing polyalphaolefin base stocks combined with dispersant and detergent additive packages at 15-25% concentration, designed to dissolve varnish, sludge, and carbon deposits from internal combustion engine crankcases, oil galleries, and piston ring lands prior to oil change service. Petroleum-based formulations still occupy the largest volume share in price-sensitive aftermarket channels, though synthetic and biodegradable variants are capturing margin pools in regulated European and Japanese markets. Marine Operations application demand is accelerating fastest among the four tracked segments, driven by IMO 2020 sulfur compliance and extended oil drain intervals in commercial vessel engines. Service Centers dominate distribution throughput for professional-grade flushes, while Online Retail channels are fragmenting the DIY owner segment with private-label concentrate offerings.
EPA VOC regulations in the United States, REACH substance restrictions administered by ECHA in Europe, and Japan's METI chemical substance reporting framework collectively constrain formulation flexibility and elevate compliance costs for cross-border suppliers. California Air Resources Board (CARB) consumer product rules have already forced reformulation of several aerosolized flush SKUs sold into the US market. Stakeholders must monitor evolving per- and polyfluoroalkyl substance (PFAS) restrictions, as trace fluorosurfactants in some specialty flush chemistries face prospective phase-out timelines that could disrupt established supply qualifications.
Market Dynamics
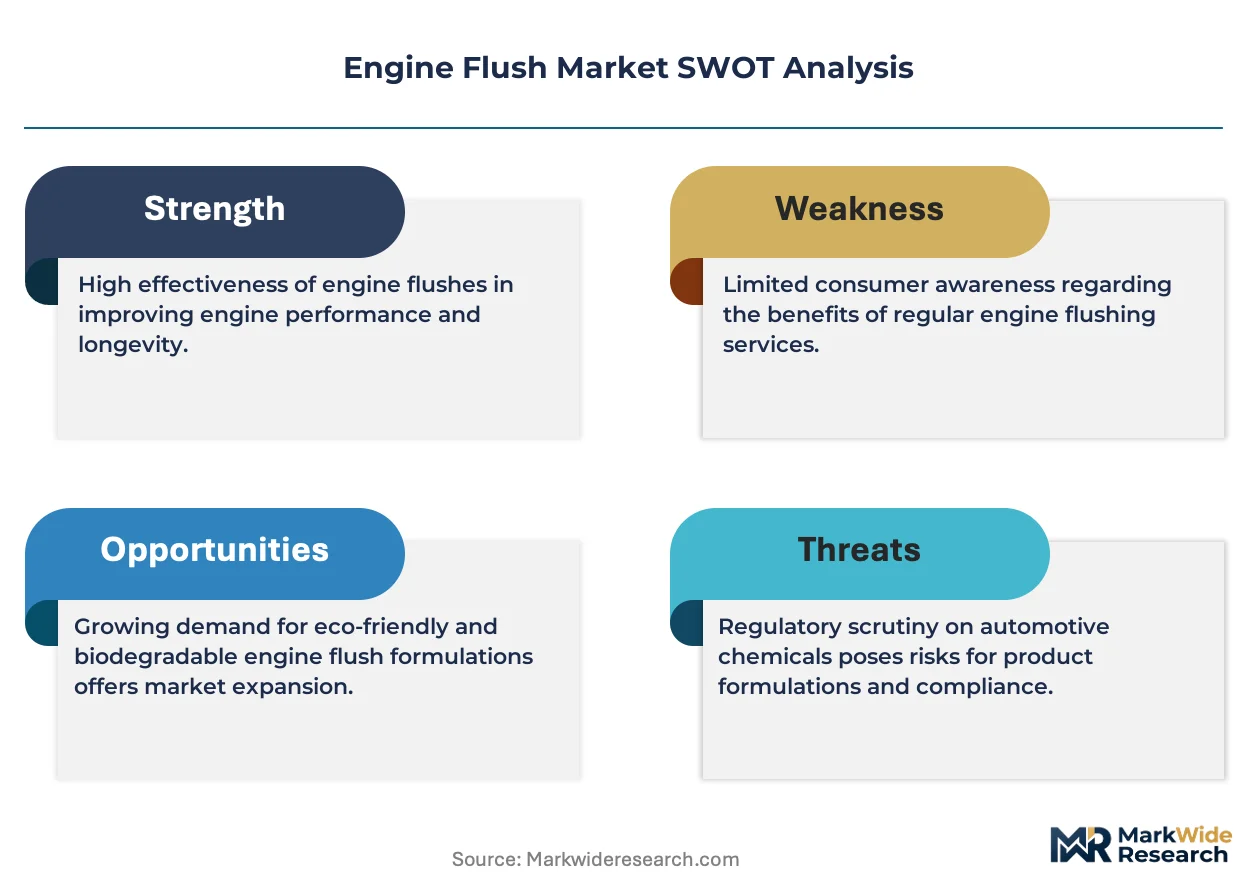
Stringent solvent regulations across the EU, United States, and Japan are forcing formulators to rebuild additive packages around low-VOC base stocks, compressing margins for petroleum-dependent suppliers while creating certification premiums for compliant alternatives.
Growth Catalysts
- IMO 2020 Sulfur Compliance:Marine operators now require intensive pre-service cleaning to protect scrubber-equipped engines and extend drain intervals in heavy-fuel applications.
- German TÜV Inspection Regimes:Mandatory technical inspections for commercial fleets sustain demand for documented flush protocols that demonstrate maintenance compliance.
- Polyalphaolefin Base Stock Advances:Synthetic formulations with superior thermal stability enable extended service intervals in high-performance diesel and gasoline engines.
Market Restraints
- Petroleum Feedstock Volatility:Crude oil price swings directly squeeze margins on conventional mineral-oil-based flush formulations dominating price-sensitive channels.
- REACH Substance Restrictions:ECHA-administered chemical authorizations force continuous reformulation of dispersant and detergent additive packages.
- Biodegradable Substitute Threat:Plant-derived ester formulations from European specialty chemical suppliers capture regulatory-compliant niches in Nordic markets.
Strategic Opportunities
- Japanese METI Chemical Reporting:Mandatory substance disclosure creates first-mover advantage for suppliers with pre-qualified low-fluorosurfactant formulations.
- Online Retail Channel Expansion:Direct-to-consumer concentrate kits bypass traditional service center markups in the DIY owner segment.
- Quick-Lube Bay Automation:Integrated flush-oil-change systems reduce technician labor time and increase throughput in high-volume service networks.
Industry Challenges
- PFAS Phase-Out Timeline Uncertainty:Prospective restrictions on trace fluorosurfactants in specialty chemistries threaten established supply qualifications and require rapid reformulation.
- California CARB Consumer Product Rules:State-level VOC limits for aerosolized products force SKU proliferation and complicate national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Flush Market |
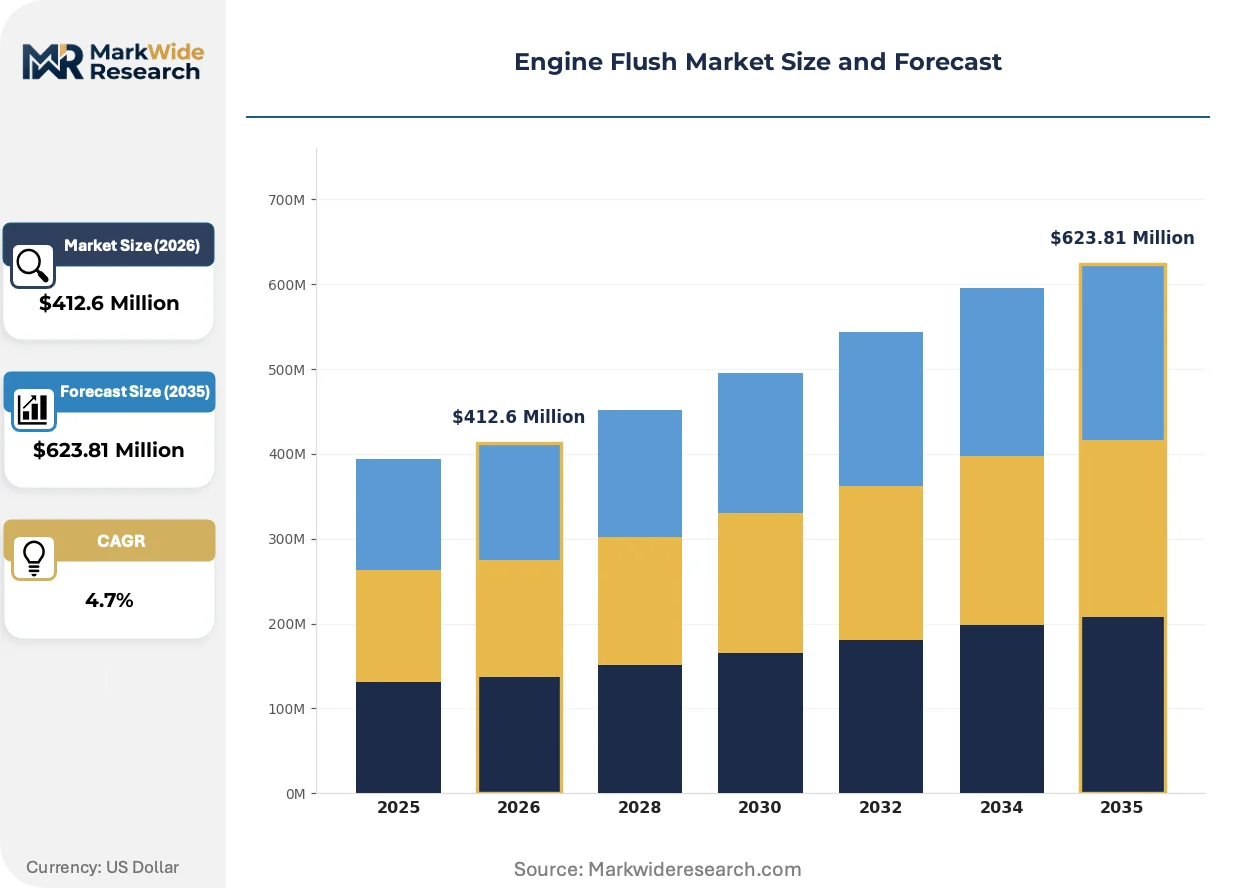
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $623.81 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petroleum-Based, Synthetic, Biodegradable, Additive Concentrate Application: Automotive Maintenance, Fleet Services, Machinery, Marine Operations End User: Repair Shops, Individual Owners, OEMs, Commercial Fleets Distribution Channel: Online Retail, Auto Parts Stores, Service Centers, Wholesale Distributors |
| Companies Covered | Valvoline Inc., Wynn's, Liqui Moly GmbH, Bardahl Manufacturing Corporation, CRC Industries Inc., Chevron Corporation, AMSOIL Inc., Sea Foam Sales Company, Royal Purple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Flush Market Emerging Trajectories
Formulation chemistry and delivery mechanisms are converging around regulatory compliance and labor efficiency, with synthetic base stocks displacing petroleum variants and automated dispensing systems reducing service bay variability.
Closed-loop solvent recovery systems are automating waste handling in high-volume service centers. Major fleet maintenance operators in Germany and the United States deploy these units to reduce hazardous waste disposal costs and document environmental compliance. The technology is automating regulatory reporting while compressing per-service material costs.
REACH substance restrictions administered by ECHA are eliminating residual chlorinated solvents from pre-lube cleaning protocols. Formulators must reformulate around oxygenated and terpene-based alternatives with lower global warming potential. European service centers face the steepest compliance costs, driving consolidation toward suppliers with captive blending networks.
Certification-driven purchasing now dominates commercial fleet procurement decisions. TÜV-certified formulations command placement premiums in German service networks, while EPA-compliant low-VOC products secure municipal and state fleet contracts in the United States. This preference shift is most visible in Germany, where dense aftermarket infrastructure amplifies certification value.
Engine Flush Market Segmentation
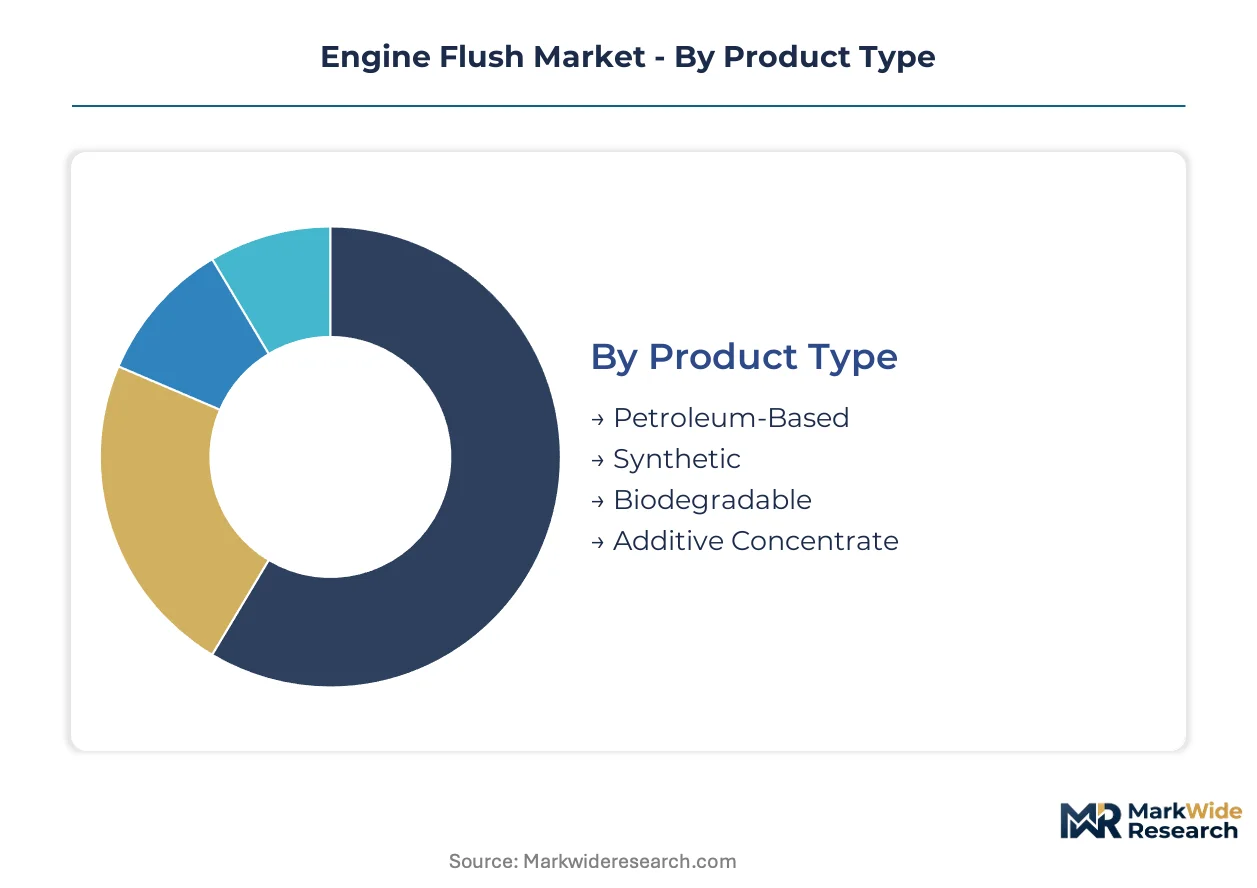
Engine flush formulations diverge sharply across price-performance tiers and regulatory compliance requirements. Each segment category reflects distinct procurement patterns, from bulk fleet purchasing to individual DIY transactions.
Product Type:
Volume concentrates in mineral-oil derivatives, while synthetic and biodegradable variants capture compliance-driven premiums.
- Petroleum-Based:Mineral-oil formulations with dispersant packages at 15-20% concentration dominate price-sensitive aftermarket channels in developing economies. Demand concentrates in independent repair shops across India and Brazil, where cost-per-service drives procurement decisions and regulatory pressure remains limited.
- Synthetic:Polyalphaolefin base stocks combined with advanced detergent chemistry deliver thermal stability for extended drain intervals in high-performance diesel and gasoline engines. German TÜV-certified synthetic formulations command placement premiums in European service centers facing strict emissions compliance documentation.
- Biodegradable:Plant-derived ester formulations from European specialty chemical suppliers serve Nordic markets with stringent environmental procurement mandates.
- Additive Concentrate:Pre-measured dose packs for DIY owners bypass professional service markups through online retail channels.
Mature deployment sits with petroleum-based formulations. Newer deployment is concentrated in biodegradable variants climbing the fastest on regulatory tailwinds.
Application:
Commercial service intervals generate recurring demand, while specialized marine protocols command the steepest expansion trajectory.
- Automotive Maintenance:Scheduled pre-lube cleaning protocols in passenger vehicle service bays represent the baseline volume driver across all geographies.
- Fleet Services:Documented flush procedures for commercial vehicle operators satisfy warranty requirements and total cost of ownership calculations in US and German fleet management.
- Machinery:Construction and agricultural equipment operators require heavy-duty formulations for carbon deposit removal in extended-interval engines.
- Marine Operations:IMO 2020 sulfur compliance mandates intensive pre-service cleaning to protect scrubber-equipped engines and extend drain intervals in heavy-fuel commercial vessels. Ship operators in Singapore, Rotterdam, and Houston anchor demand for high-performance marine formulations.
Procurement scale differentiates fleet services from individual automotive transactions. Technical complexity peaks in marine applications.
End User:
Professional service channels dominate volume throughput, though direct-to-owner sales are fragmenting the lower tier.
- Repair Shops:Independent and franchised service centers purchase bulk formulations through wholesale distributors, with German TÜV-certified products securing preferential placement.
- Individual Owners:DIY enthusiasts source concentrate kits through Amazon and specialized auto parts portals, bypassing labor markups.
- OEMs:Factory-fill and warranty-service specifications from Volkswagen, Toyota, and BMW lock in supplier relationships for certified flush chemistries.
- Commercial Fleets:Municipal and logistics operators mandate documented maintenance protocols for asset depreciation and resale value protection.
Certification requirements concentrate in OEM and fleet procurement. Price sensitivity peaks with individual owners.
Distribution Channel:
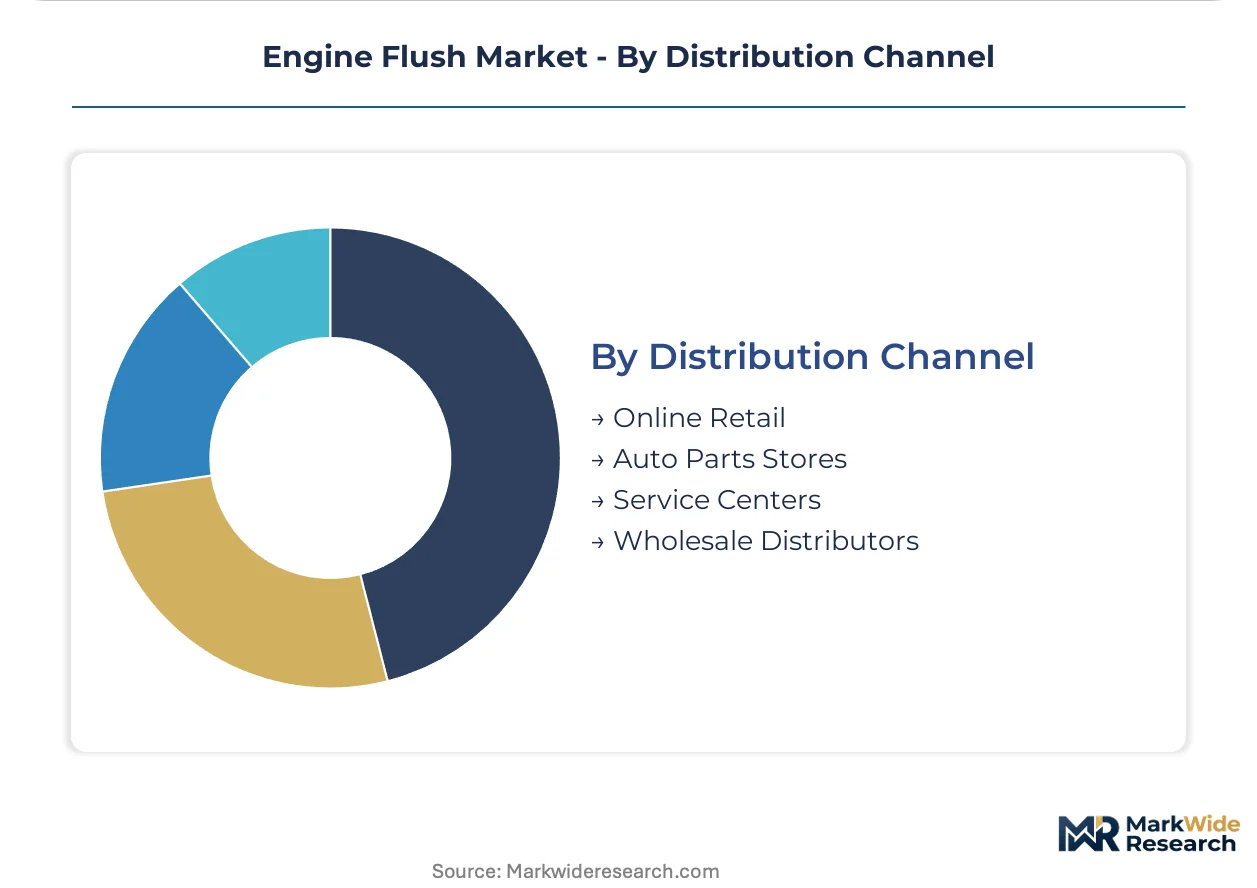
Service center throughput reflects professional-grade formulation demand, while online channels reshape concentrate economics.
- Online Retail:Direct-to-consumer concentrate kits and private-label offerings fragment DIY owner purchasing, with Amazon and RockAuto capturing significant transaction volume.
- Auto Parts Stores:NAPA, O'Reilly, and Advance Auto Parts stock mid-tier petroleum and synthetic formulations for walk-in professional and enthusiast customers.
- Service Centers:Valvoline Instant Oil Change and Jiffy Lube networks drive bulk procurement of TÜV-certified and EPA-compliant formulations for quick-lube bay throughput.
- Wholesale Distributors:Wurth and Grainger supply commercial fleet operators and independent repair shops with drum and tote quantities.
Professional volume flows through service centers and wholesale distributors. Margin compression concentrates in online retail private-label competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors marine formulation demand through its position as Europe's largest bunker fuel hub, where IMO 2020 compliance drives intensive pre-service cleaning protocols for scrubber-equipped vessels calling at Dutch ports.
United States
Commercial fleet operators in Houston and Los Angeles sustain bulk procurement of EPA-compliant low-VOC formulations for documented maintenance protocols. California Air Resources Board consumer product rules force SKU proliferation for aerosolized flush products sold into the US market. Dallas-Fort Worth corridor hosts concentrated quick-lube bay networks driving automated dispensing system adoption.
Germany
Dense automotive aftermarket infrastructure across Bavaria and Baden-Württemberg sustains pull for TÜV-certified high-performance flush formulations. REACH substance restrictions administered by ECHA eliminate residual chlorinated solvents from pre-lube cleaning protocols. Stuttgart industrial cluster concentrates formulator blending operations serving European service center networks.
Japan
Marine operators in Yokohama and Nagoya anchor demand for high-performance formulations protecting scrubber-equipped engines in heavy-fuel applications. METI chemical substance reporting framework constrains formulation flexibility for cross-border suppliers. Chubu region manufacturing bases produce synthetic base stocks with superior thermal stability for extended drain intervals.
Singapore
The world's largest bunkering port drives marine operations segment expansion through intensive pre-service cleaning mandates for vessels transitioning to low-sulfur fuels. Maritime and Port Authority regulations align with IMO 2020 sulfur compliance requirements. Jurong Island chemical hub concentrates specialty ester formulation production for regional vessel servicing.
India
Independent repair shops across Maharashtra and Gujarat dominate price-sensitive aftermarket channels where petroleum-based mineral-oil formulations drive procurement decisions. Central Pollution Control Board norms remain limited compared to European or Japanese equivalents. Mumbai-Pune industrial corridor hosts blending operations serving domestic commercial fleet maintenance networks.
Engine Flush Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and base stock technology. The vendor base stratifies into three tiers: multinational lubricant houses with captive refining networks, European specialty formulators with regulatory certification depth, and regional compounders serving price-sensitive aftermarket channels. Two dominant competitive moves define current positioning: backward integration into polyalphaolefin base stock production and geographic licensing partnerships to secure local regulatory pre-qualification.
Within the multinational lubricant tier, Valvoline Inc. and Chevron Corporation exemplify scale-driven positioning through North American refinery networks. Liqui Moly GmbH anchors the European specialty formulator archetype through German TÜV-certified formulations. CRC Industries Inc. occupies a position in the delivery-system specialist segment through aerosol platform optimization.
| Leading Market Players |
|---|
| Valvoline Inc. |
| Wynn's |
| Liqui Moly GmbH |
| Bardahl Manufacturing Corporation |
| CRC Industries Inc. |
| Chevron Corporation |
| AMSOIL Inc. |
| Sea Foam Sales Company |
| Royal Purple |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates qualified supply access and premium-tier pricing power, as formulators lacking low-global-warming-potential formulations face exclusion from German TÜV-certified procurement channels while certified suppliers capture margin premiums in European service networks.
Pricing Analysis
Throughput-based pricing anchors professional-grade engine flush procurement, with service centers paying per-bay efficiency metrics rather than unit volume. Certification tier and synthetic base stock grade drive price differentiation, separating TÜV-validated formulations from commodity mineral-oil alternatives. Cost compression in petroleum-based segments intensifies as crude volatility squeezes margin pools for independent compounders in price-sensitive channels. Individual DIY owners exhibit highest price sensitivity through online private-label sourcing, while commercial fleets prioritize documented compliance over per-unit cost.
Supply Chain Analysis
REACH substance pre-qualification gates supplier access to European service networks, forcing continuous reformulation investment. Feedstock concentration centers on Germany, the United States, and Japan, with polyalphaolefin base stock production anchored in Chubu region manufacturing bases and North American refinery corridors. Formulation chemistry draws from specialty detergent packages, dispersant additive blends, and oxygenated solvent alternatives. Single-source vulnerability in fluorosurfactant inputs threatens established supply qualifications as PFAS restrictions advance. Distribution runs through wholesale distributors serving drum-quantity fleet operators and automated service center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The engine flush sector sits in a formulation-transition phase, with synthetic polyalphaolefin base stocks displacing legacy petroleum-derived mineral oils across certification-driven procurement channels.
For Market Incumbents: Hedge margin exposure in petroleum-dependent product lines by accelerating captive blending investment in low-VOC synthetic capacity. Secure TÜV pre-qualification for reformulated additive packages before ECHA substance restrictions eliminate residual chlorinated solvents from approved chemistries. Channel control through exclusive service center partnerships protects placement premiums against private-label online fragmentation. For New Entrants and Emerging Players: Commercial marine operators in Singapore and Rotterdam represent the most penetrable buyer archetype, with IMO 2020 compliance mandates creating immediate demand for high-performance scrubber-protection formulations. Biodegradable ester chemistry sourced from European specialty suppliers unlocks Nordic environmental procurement niches underserved by incumbent petroleum-based portfolios. Direct technical sales to vessel maintenance contractors bypass established lubricant house distribution lock-in. For Investors and Strategic Acquirers: First-mover METI chemical substance reporting compliance in Japan is the leading indicator that a supplier has navigated regulatory complexity sufficient for cross-border qualification. Long-term viability favors formulators with backward integration into polyalphaolefin base stock production and captive certification infrastructure across multiple regulatory jurisdictions. Watch for ECHA authorization timeline acceleration signaling consolidation pressure on non-compliant regional compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyalphaolefin Base Stocks | Captive supply of synthetic feedstocks insulates margin pools from crude volatility and secures thermal stability performance claims. |
| TÜV Certification Investment | German technical inspection pre-qualification unlocks premium placement in European service center networks facing documented maintenance mandates. |
| Marine Formulation Development | Scrubber-protection chemistry for IMO 2020 compliance captures fastest-expanding segment in Singapore and Rotterdam bunkering hubs. |
| Low-Fluorosurfactant Reformulation | PFAS-free additive packages preempt supply qualification disruption from prospective ECHA and EPA substance restrictions. |
| Quick-Lube Bay Automation Partnerships | Integrated flush-oil-change systems with Valvoline Instant Oil Change and Jiffy Lube networks lock in volume throughput and reduce technician labor variability. |
Methodological Framework
Independent corroboration across formulator technical directors, commercial fleet procurement managers, and marine engineering officers underwrites the qualitative findings. Primary fieldwork engaged quick-lube bay operators, wholesale distributor category leads, and ECHA regulatory affairs specialists alongside secondary validation through customs trade data, SEC 10-K lubricant segment disclosures, and ACC formulation trend reports. Bottom-up service center throughput estimates and top-down refinery capacity assessments triangulate volume figures.
Comparable-period anchoring to historical fleet maintenance intervals and marine dry-docking cycles structured the projection horizon across the analysis window. Segmentation modeling incorporated product type tier, application intensity, end-user procurement scale, and regional regulatory cluster dimensions. CAGRs derived from slope-log analysis of certified formulation adoption curves and synthetic base stock displacement rates, with marine operations segment expansion calibrated to IMO sulfur regulation implementation phases.
Revisions become necessary when ECHA substance authorization timelines accelerate, PFAS restriction scope expands beyond trace fluorosurfactants, or marine scrubber retrofit rates diverge from bunkering port compliance projections. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock price corridor stability. A model refresh is warranted upon material change in TÜV certification requirement stringency or California CARB consumer product rule expansion to concentrate formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Gear Oil Market
Powertrain
Crankshaft Oil Market
Powertrain
Transmission Control System Market
Powertrain
Power Steering Filter Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Automotive Half Shaft Market
Powertrain
Transmission Fluids Market
Powertrain
Modular Belt Drive Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
France Automotive Engine Oils Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Global Automotive Engine Pulley Market