
 Global Carbon Fiber Bike Market | 2026-2036
Global Carbon Fiber Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Fiber Bike Market Analysis
Recreational riders is bifurcating from professional cyclists as the dominant demand archetype across carbon fiber bike markets. Giant Bicycles leverages its vertically integrated manufacturing base in Taiwan to control raw carbon fiber prepreg costs. Trek Bicycles anchors its North American position through an owned retail network that reduces channel dependency. Specialized differentiates via proprietary layup algorithms that optimize stiffness-to-weight ratios for competitive segments.
Carbon fiber bicycles consist of frames, forks, and components molded from polyacrylonitrile-based or pitch-based carbon fiber reinforced polymer composites, typically achieving frame weights below 900 grams with tensile strengths exceeding 3,500 MPa. Road bikes command premium positioning in value terms due to aerodynamic tube shaping and integrated cockpit designs that justify higher price points. Mountain bikes with full suspension frame designs capture expanding share among amateur cyclists seeking terrain versatility without weight penalties. Distribution through specialty stores retains margin concentration despite online retail growth, as fit consultation and post-sale service remain purchase determinants.
The U.S. Consumer Product Safety Commission and the European Committee for Standardization enforce frame fatigue and impact testing protocols that manufacturers must satisfy for market access. China's SAMR and GB standards govern carbon fiber import specifications and domestic production emissions, reshaping supplier qualification requirements. Japan's JIS standards for bicycle components create additional compliance layers for brands sourcing from multiple Asian manufacturing bases. Stakeholders must monitor evolving frame recyclability mandates and bio-based epoxy resin certifications that will redefine material specifications and supplier relationships.
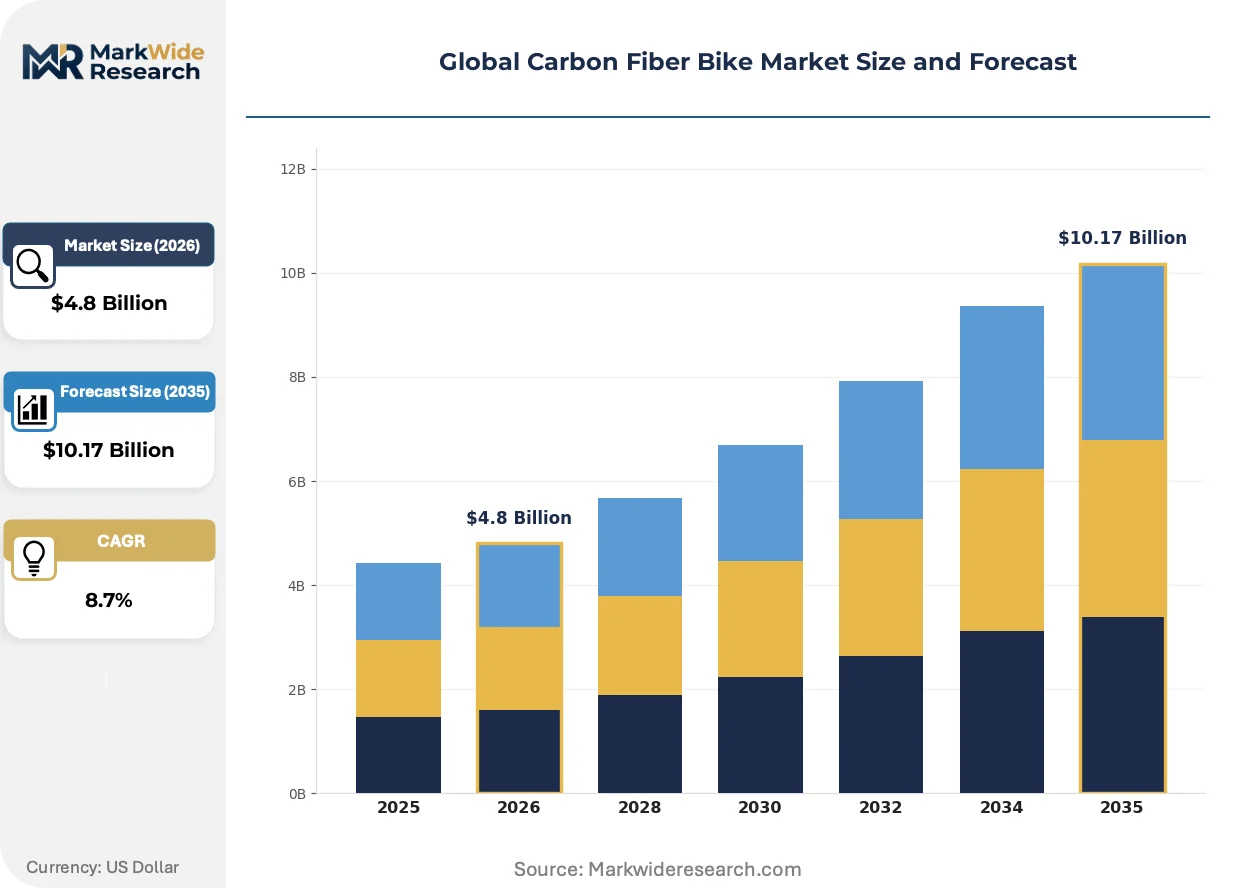
Market Dynamics
Professional racing procurement volumes are compressing frame development cycles while China's dual carbon goals and Europe's E-bike regulations simultaneously tighten material sourcing standards and reshape supplier qualification requirements across the value chain.
Growth Catalysts
- Elite Amateur Cycling Demand:Competitive amateur segments in Germany, Italy, and the United States are driving ultralight frame replacement cycles as cycling infrastructure investment accelerates.
- REACH and RoHS Compliance Evolution:European material standards are forcing epoxy resin and prepreg suppliers to certify bio-based alternatives, opening qualified supplier slots for compliant manufacturers.
- Taiwanese Manufacturing Concentration:Vertically integrated production bases in Taichung and Kaohsiung control raw carbon fiber prepreg costs through captive molding and layup operations.
Market Restraints
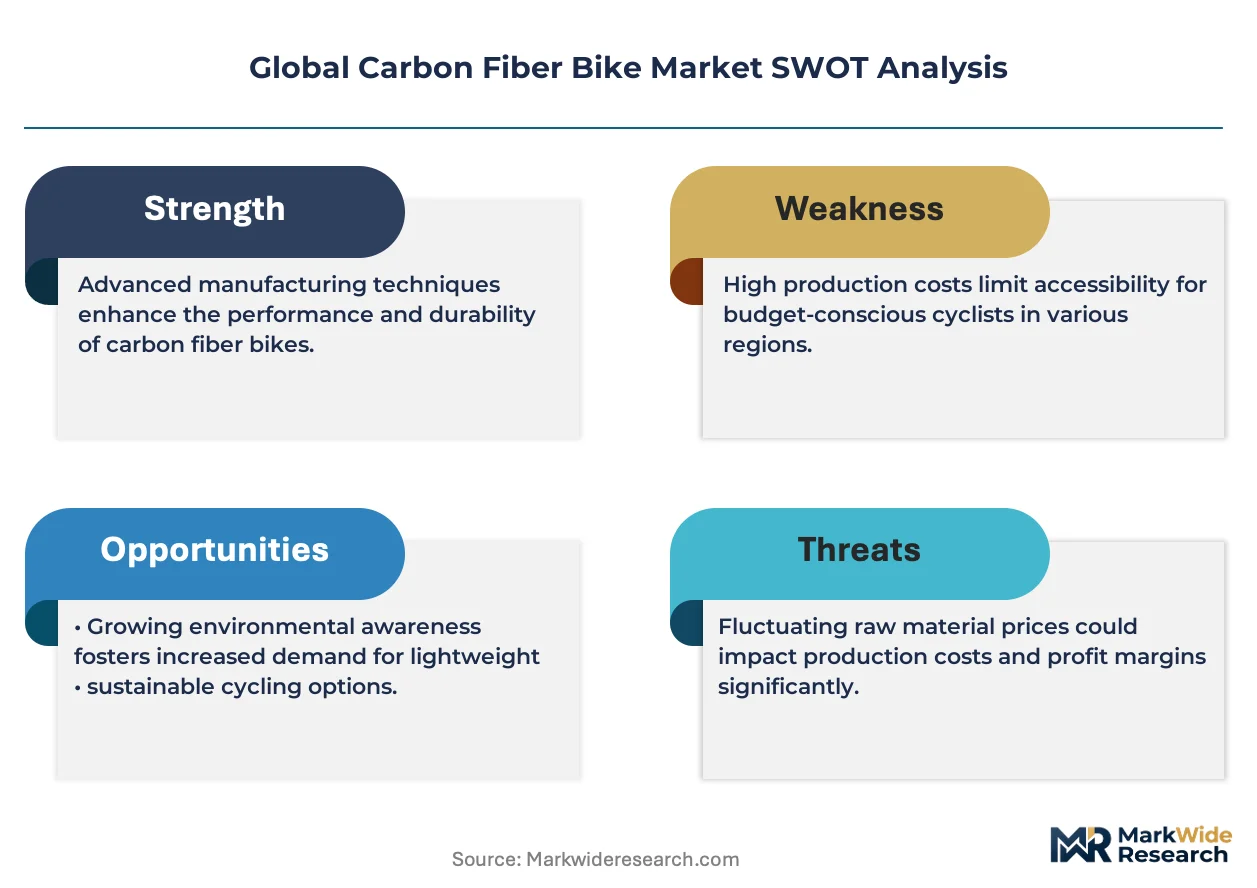
- Polyacrylonitrile Feedstock Volatility:Acrylic precursor prices fluctuate with petrochemical indices, compressing margin stability for frame manufacturers locked into annual contracts.
- Japanese Toray Supply Dominance:Pitch-based and PAN-based carbon fiber supply concentrates among three Japanese chemical conglomerates, creating single-source vulnerability for high-modulus grades.
- Frame Fatigue Testing Burden:The U.S. Consumer Product Safety Commission and European Committee for Standardization impose sequential impact and fatigue protocols that extend product validation timelines.
Strategic Opportunities
- India Cycling Infrastructure Buildout:Metropolitan rail-cycling integration projects in Mumbai, Bangalore, and Delhi create first-time carbon fiber demand among commuter-convert segments.
- Recyclability Mandate Preparation:Anticipated EU Green Deal extensions into bicycle frame end-of-life regulations reward early movers establishing pyrolysis and solvolysis reclamation partnerships.
- Gravel Bike Category Expansion:Terrain-versatile frame geometries are capturing road cyclists seeking single-bike solutions for mixed-surface events and training versatility.
Industry Challenges
- Composite Layup Technician Scarcity:Hand-layup craftsmanship for complex tube junctions and monocoque structures requires multi-year apprenticeship pipelines that Taiwan and China suppliers struggle to scale.
- Multi-Jurisdiction Certification Parallelism:Simultaneous pursuit of JIS component standards, GB emissions compliance, and CPSC frame testing creates documentation redundancy and timeline misalignment.
- Retailer Service Capability Gaps:Specialty store networks lack ultrasonic inspection and repair certification for carbon fiber damage assessment, forcing manufacturer-direct warranty handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Fiber Bike Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Road Bikes, Mountain Bikes, Hybrid Bikes, BMX Bikes End User: Professionals, Amateur Cyclists, Fitness Enthusiasts, Recreational Riders Frame Design: Full Suspension, Hardtail, Rigid, Folding Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Cannondale, Scott, Giant Bicycles, Canyon, Orbea, Trek Bicycles, Colnago, Enve, Specialized, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Fiber Bike Market Emerging Trajectories
Aerodynamic integration and automated manufacturing are compressing the traditional separation between custom frame builders and mass producers. Three developments dominate current competitive positioning.
Automated fiber placement systems are replacing hand layup for primary tube sections in high-volume road frame production. Tier-one Taiwanese and Chinese contract manufacturers are adopting these systems for standardized geometries while reserving manual processes for complex junctions and custom race team orders. This hybrid automation is bifurcating the supplier base into precision-volume specialists and artisan-custom ateliers.
China's SAMR has tightened GB standards for carbon fiber import specifications and domestic production emissions, requiring real-time monitoring of volatile organic compound releases during epoxy curing. Manufacturers with captive prepreg operations must retrofit thermal oxidizers or face production quota restrictions. Domestic Chinese brands sourcing from compliant facilities gain preferential placement in government procurement and state-sponsored cycling events.
Specialty retailers are unbundling after-sales service from initial fit consultation, creating standalone subscription models for seasonal bike fitting and component upgrade planning. This service separation is displacing the traditional bundled purchase experience in United States and German markets where online direct-to-consumer frame sales have eroded storefront foot traffic. Urban cycling clubs in Copenhagen and Amsterdam are piloting fleet maintenance cooperatives that aggregate individual service demand.
Global Carbon Fiber Bike Market Segmentation
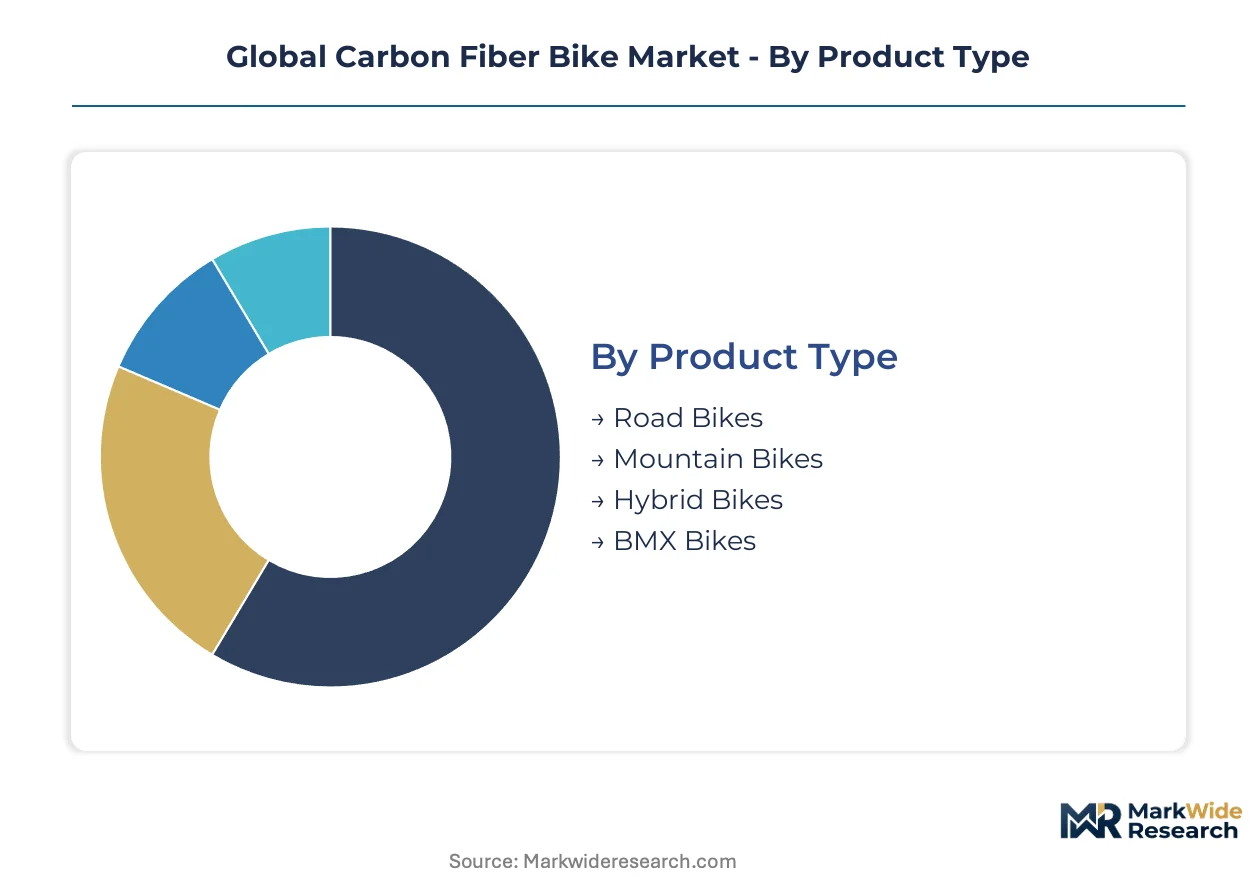
Carbon fiber bike segmentation reveals divergent margin architectures across product categories. Frame design complexity and distribution channel control separate premium capture from commoditization pressure. End-user stratification between professional racing procurement and recreational volume creates distinct supplier qualification tiers.
Product Type:
Premium margin pools concentrate in aerodynamic road frames where tube shaping patents and integrated cockpit designs sustain pricing power.
- Road Bikes:Frames achieve sub-900-gram weights through unidirectional layup sequences and monocoque construction. Demand concentrates in Germany and Italy where UCI racing regulations drive replacement cycles among elite amateur teams.
- Mountain Bikes:Full-suspension carbon rear triangles and linkage systems require complex mold tooling and impact-resistant resin formulations. Amateur cyclists in the United States seeking terrain versatility without weight penalties are expanding this segment's volume base.
- Hybrid Bikes:Commuter-oriented geometries with relaxed stack-to-reach ratios target urban rail-cycling integration projects.
- BMX Bikes:Compact frames prioritize impact durability over weight minimization for track and freestyle disciplines.
Road bikes hold installed capacity. Mountain bikes are rotating up the share rankings.
End User:
Volume concentration sits with recreational riders, while professional procurement drives technology validation and frame development cycle compression.
- Professionals:UCI-registered teams and national federation programs specify custom layup schedules and geometry adjustments. Sponsorship contracts in Italy and Belgium mandate annual frame replacement, creating predictable high-modulus carbon fiber demand.
- Amateur Cyclists:Competitive gran fondo and criterium participants in the United States purchase mid-tier carbon frames with race-proven geometries. Cycling infrastructure investment across Germany accelerates replacement frequency in this cohort.
- Fitness Enthusiasts:Indoor training platform integration drives demand for power-meter-compatible frames with standardized bottom bracket shells.
- Recreational Riders:Weekend cyclists prioritize comfort-oriented endurance geometries and disc brake compatibility over weight minimization.
Professionals anchor technology roadmaps. Amateur cyclists are expanding most quickly as infrastructure investment matures.
Frame Design:
Manufacturing cost tiers separate monocoque rigid structures from multi-component suspension assemblies with moving pivots.
- Full Suspension:Carbon fiber rear triangles integrate with aluminum or carbon linkage systems requiring complex mold tooling and bearing housing precision. Trail and enduro segments in the United States and Canada demand 120-170mm travel configurations with progressive leverage curves.
- Hardtail:Front-suspension-only designs reduce mold complexity while preserving carbon fiber weight advantages for cross-country racing. German and Swiss amateur racing leagues maintain strong preference for hardtail efficiency in marathon formats.
- Rigid:Fixed rear triangles dominate gravel and cyclocross categories where tire clearance and mud-shedding frame shapes take priority over suspension travel.
- Folding:Hinge mechanisms and detachable frame junctions introduce stress concentration points requiring reinforced layup schedules and periodic inspection protocols.
Hardtail designs hold installed capacity. Full suspension is climbing the fastest as trail accessibility expands.
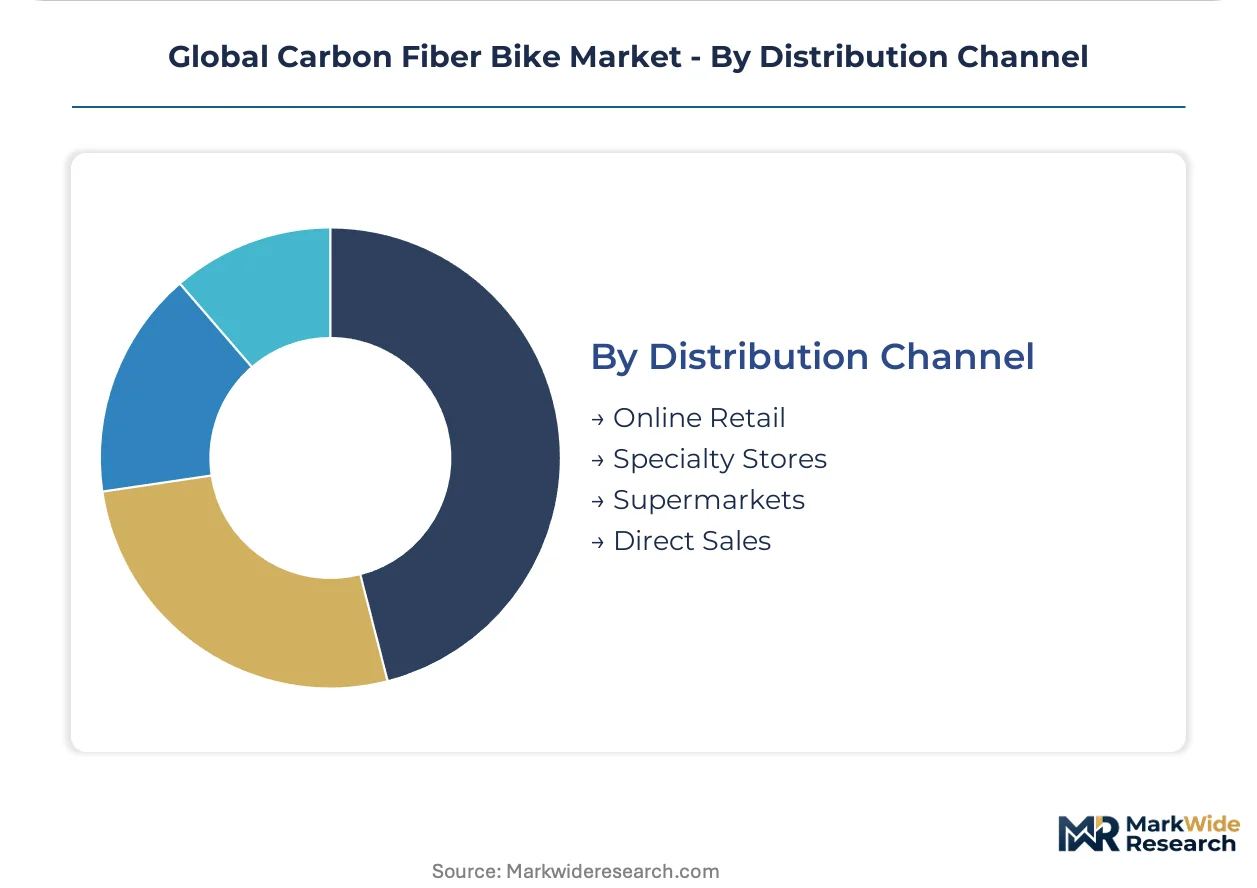
Distribution Channel:
Margin retention concentrates in channels controlling fit consultation and post-sale service capabilities.
- Specialty Stores:Independent retailers provide frame sizing, fit adjustment, and warranty claim handling that justifies premium pricing. German and Dutch markets maintain dense specialty networks with certified carbon fiber repair partnerships.
- Direct Sales:Manufacturer-owned channels capture full margin while requiring investment in remote fit algorithms and customer service infrastructure. United States direct-to-consumer brands have eroded specialty store foot traffic in urban markets.
- Online Retail:Third-party platforms aggregate inventory comparison but lack damage assessment and assembly services, limiting carbon fiber penetration.
- Supermarkets:Mass-market channels carry entry-level aluminum and steel offerings with minimal carbon fiber representation due to service capability gaps.
Specialty stores hold installed capacity. Direct sales is gaining share fastest as fit technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite amateur cyclists and professional racing teams concentrate procurement volumes in Germany, Italy, and the United States, where cycling infrastructure investment accelerates frame replacement cycles and tightens material sourcing standards.
United States
Competitive gran fondo participants and criterium racers drive mid-tier carbon frame demand across metropolitan cycling corridors. The U.S. Consumer Product Safety Commission enforces sequential impact and fatigue testing protocols that extend product validation timelines for market access. California and Colorado host dense specialty retail networks with certified carbon fiber repair partnerships serving amateur racing leagues.
Germany
UCI-registered amateur teams and national federation programs specify custom layup schedules with predictable annual replacement cycles. REACH and RoHS compliance evolution forces epoxy resin suppliers to certify bio-based alternatives, opening qualified supplier slots for compliant manufacturers. The Taunus cycling region and Bavarian alpine corridors concentrate specialty retailer density with integrated fit consultation services.
Italy
Sponsorship contracts with UCI teams mandate annual frame replacement, creating structured high-modulus carbon fiber demand from domestic and export racing programs. The European Committee for Standardization governs frame fatigue and impact testing protocols alongside national cycling federation equipment regulations. The Veneto and Lombardy industrial districts maintain historical frame-building expertise now transitioning to automated fiber placement systems.
China
Domestic brands sourcing from SAMR-compliant facilities gain preferential placement in government procurement and state-sponsored cycling events under dual carbon goals implementation. GB standards for carbon fiber import specifications and domestic production emissions require real-time volatile organic compound monitoring during epoxy curing. Taichung and Kaohsiung manufacturing clusters control raw carbon fiber prepreg costs through captive molding operations serving export markets.
Japan
Pitch-based and PAN-based carbon fiber supply concentrates among domestic chemical conglomerates, creating single-source vulnerability for high-modulus grades required by professional racing procurement. JIS standards for bicycle components create additional compliance layers for brands sourcing from multiple Asian manufacturing bases. Osaka and Nagoya industrial zones anchor precursor material production feeding Taiwanese frame fabricators.
Global Carbon Fiber Bike Market Vendor Landscape
Player mix skews toward vertically integrated Taiwanese manufacturers and brand-holding multinationals with owned retail networks. Market structure exhibits tiered concentration with premium capture by racing-focused specialists and volume scale by mass-market producers. Strategic archetypes include precision-volume specialists leveraging automated fiber placement and artisan-custom ateliers serving race team orders. Dominant competitive moves span geographic expansion into Indian metropolitan rail-cycling integration projects and technology licensing for proprietary layup algorithms.
Among the named fabricators, Giant Bicycles exemplifies the vertically integrated archetype with captive prepreg operations, while Trek Bicycles and Specialized occupy positions as brand-holding multinationals differentiating through distribution control and algorithmic frame optimization respectively. Canyon represents the direct-to-consumer vector eroding specialty store foot traffic through remote fit technology. These three anchors illustrate the competitive tension between manufacturing-scale efficiency and channel-margin retention across the value chain.
| Leading Market Players |
|---|
| Cannondale |
| Scott |
| Giant Bicycles |
| Canyon |
| Orbea |
| Trek Bicycles |
| Colnago |
| Enve |
| Specialized |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Taiwanese contract manufacturers and Japanese precursor suppliers lock in both high-modulus carbon fiber supply access and eighteen-month price visibility for frame fabricators. These contracts insulate Giant Bicycles and tier-one suppliers from acrylic precursor volatility while binding smaller brands to spot-market exposure.
Pricing Analysis
Cost-plus contracts with petrochemical indexation dominate prepreg procurement, passing acrylic precursor fluctuations through to frame manufacturers on quarterly resets. Three-tier pricing structure across premium, standard, and economy levels separates UCI-certified race frames from endurance geometries and entry-level carbon hybrids. Pricing pressure stems from amateur cyclist price sensitivity in United States direct-to-consumer channels, where Canyon and similar brands compress margins. Professional racing teams exhibit lowest price sensitivity, prioritizing stiffness-to-weight ratios and custom layup schedules over unit economics.
Supply Chain Analysis
Inventory cycles stretching six to nine months from prepreg order to frame delivery expose manufacturers to demand forecasting errors and working capital strain. Production concentrates in Taiwan, China, and Japan, with Taichung and Kaohsiung clusters controlling captive molding operations and Osaka feeding precursor materials. Raw material dependencies center on polyacrylonitrile from Toray, Mitsubishi Chemical, and Teijin, plus epoxy resin formulations subject to REACH bio-based mandates. Single-source vulnerability for T1100G and M60J high-modulus grades creates qualification bottlenecks when race teams specify custom schedules. Distribution runs through specialty retailers in Germany and the Netherlands, direct-to-consumer platforms eroding United States storefronts, and manufacturer-owned retail networks anchoring North American premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Carbon Fiber Bike Market tracks a cyclical recovery pattern tied to amateur racing participation rates, which rebound following Olympic cycles and infrastructure investment waves. Elite gran fondo and criterium growth in Germany, Italy, and the United States validates replacement demand durability.
For Market Incumbents: Shield margin architecture by deepening backward integration into prepreg operations or securing exclusive high-modulus fiber allocations from Japanese suppliers. Counter direct-to-consumer erosion through owned retail network expansion in Colorado and California cycling corridors. Certification investment in EU Green Deal recyclability frameworks creates defensive moats against regulatory disruption. For New Entrants and Emerging Players: Anchor in Indian metropolitan rail-cycling integration projects, where commuter-convert segments lack established brand loyalty and price elasticity favors mid-tier carbon hybrids. Target gravel bike white space with terrain-versatile frame geometries capturing road cyclists seeking single-bike solutions. Pursue automated fiber placement licensing from Taiwanese equipment vendors to bypass hand-layup technician scarcity. For Investors and Strategic Acquirers: Automated fiber placement specialists with proprietary layup algorithms represent the most defensible acquisition archetype, commanding technology licensing revenue from mass-market brands. Long-term viability hinges on recyclability mandate preparation and pyrolysis partnership establishment ahead of EU Green Deal extensions. Watch for SAMR production quota restrictions signaling Chinese domestic brand preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prepreg Operations | Captive carbon fiber supply insulates Giant Bicycles from Toray allocation constraints and acrylic volatility. |
| Automated Fiber Placement Adoption | Tier-one Taiwanese manufacturers compress cycle times for standardized road frame geometries while preserving manual capacity. |
| Recyclability Partnership Establishment | Pyrolysis and solvolysis reclamation alliances position early movers for EU Green Deal bicycle frame end-of-life regulations. |
| Direct-to-Consumer Channel Expansion | Remote fit algorithms and owned retail networks capture full margin from amateur cyclists in United States urban markets. |
| Indian Market Entry | Mumbai and Bangalore rail-cycling integration projects create first-time carbon fiber demand among infrastructure-enabled commuters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of UCI equipment regulations, CPSC frame testing protocols, and REACH compliance databases. Primary interviews engaged frame engineering directors at Taiwanese contract manufacturers, procurement leads at brand-holding multinationals, specialty retail owners in Germany and the Netherlands, and carbon fiber precursor specialists at Japanese chemical conglomerates. Secondary validation drew from SAMR GB standard filings, European Committee for Standardization impact test documentation, and customs trade data for carbon fiber bicycle frame imports. Bottom-up demand modeling from amateur racing participation rates and top-down supply assessment from prepreg production capacity were cross-referenced for triangulation.
Segmentation dimensions modeled include product type across road, mountain, hybrid, and BMX categories; end user stratification from professional teams through recreational riders; frame design separating full suspension, hardtail, rigid, and folding architectures; and distribution channel mapping specialty retail, direct sales, online platforms, and mass-market outlets. CAGRs were derived from replacement cycle frequency analysis tied to infrastructure investment maturity and racing participation trends. Industry-specific forecast inputs incorporated UCI regulation revision timelines and SAMR dual carbon goal implementation pacing.
Material uncertainties — polyacrylonitrile feedstock price shocks, REACH bio-based epoxy certification delays, and SAMR production quota restrictions — sit outside the modeled envelope and could compress or extend replacement cycles. Forecasts reflect assumptions about amateur cyclist infrastructure access expansion and professional racing sponsorship stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Boot Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Two-Wheeler Services Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Motorcycle Chain Market
Bikes and Motorcycles
Malaysia Bicycle Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Vietnam Bike-Sharing Market