
 United Kingdom Automotive Engine Oils Market | 2026-2036
United Kingdom Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Automotive Engine Oils Market Analytics
Fleet Services procurement is consolidating across major UK commercial transport operators, reducing supplier counts per tender. Shell leverages its integrated refining network to secure feedstock advantages for premium synthetic grades. BP p.l.c. anchors its position through extensive workshop partnerships and direct OEM supply agreements. Castrol differentiates via motorsport-derived technology credentials that transfer to consumer marketing.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with viscosity grades such as 5W-30 specifying cold-start flow and high-temperature film strength performance. The primary purpose is extending engine operational life while maintaining fuel efficiency under variable duty cycles. Synthetic formulations command margin premiums due to extended drain intervals and OEM approval requirements, while 5W-30 viscosity grade dominates volume through compatibility with modern passenger car engines. Fleet Services represents the fastest-growing end user channel as centralized maintenance contracts favor bulk procurement and oil analysis programs.
The Health and Safety Executive enforces workplace exposure limits for lubricant handling, while UK REACH mandates chemical substance registration and hazard communication throughout the supply chain. The Department for Transport's vehicle emissions standards indirectly shape lubricant specifications through engine design changes. Stakeholders must monitor bio-based and re-refined base oil regulatory pathways as circular economy mandates intensify.
Market Dynamics
Fleet Services consolidation across England's industrial corridor is compressing supplier counts per tender and favoring bulk procurement with embedded oil analysis programs. This structural concentration is reshaping margin structures and technical service requirements for lubricant distributors serving commercial transport operators.
Growth Catalysts
- UK REACH chemical disclosure mandates:The tightening registration requirements for lubricant formulations are accelerating premium synthetic grade adoption as manufacturers invest in compliant additive packages that deliver extended drain intervals.
- Centralized Fleet Services contracts:Major commercial transport operators across the Birmingham-Manchester corridor are consolidating maintenance procurement, creating pull-through demand for high-volume synthetic formulations with OEM approval credentials.
- Re-refined base oil pathways:Circular economy mandates from the Department for Transport are opening regulatory space for recycled base stocks in commercial fleet applications.
Market Restraints
- Group II/III base oil import dependence:UK lubricant blenders rely on seaborne feedstock deliveries from Northwest European refiners, exposing margin stability to freight rate volatility and currency fluctuations.
- Additive package concentration:Four global chemical suppliers control the majority of detergent-dispersant-inhibitor formulations, limiting formulation differentiation and compressing blender gross margins.
- Internal combustion engine displacement:Battery electric vehicle penetration in UK passenger car parc is eroding the addressable market for traditional engine lubricants in the consumer segment.
Strategic Opportunities
- Workshop partnership densification:Independent garage networks in Northern England remain fragmented, offering acquisition targets for lubricant distributors seeking captive offtake channels.
- Hydrogen combustion engine lubricants:Emerging heavy-duty powertrain trials by UK freight operators require novel formulations managing hydrogen embrittlement and water contamination.
- Extended drain interval service models:Oil condition monitoring integration with telematics platforms enables Fleet Services providers to monetize predictive maintenance rather than fluid volume alone.
Industry Challenges
- OEM approval certification timelines:Securing Volkswagen 504/507 or Mercedes-Benz 229.5 specifications requires 18-24 month testing cycles, delaying product launch windows for new synthetic grades.
- Technical service workforce gaps:Field lubrication engineers with tribology expertise and Fleet Services account management experience command premium compensation in the tight UK labour market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Automotive Engine Oils Market |
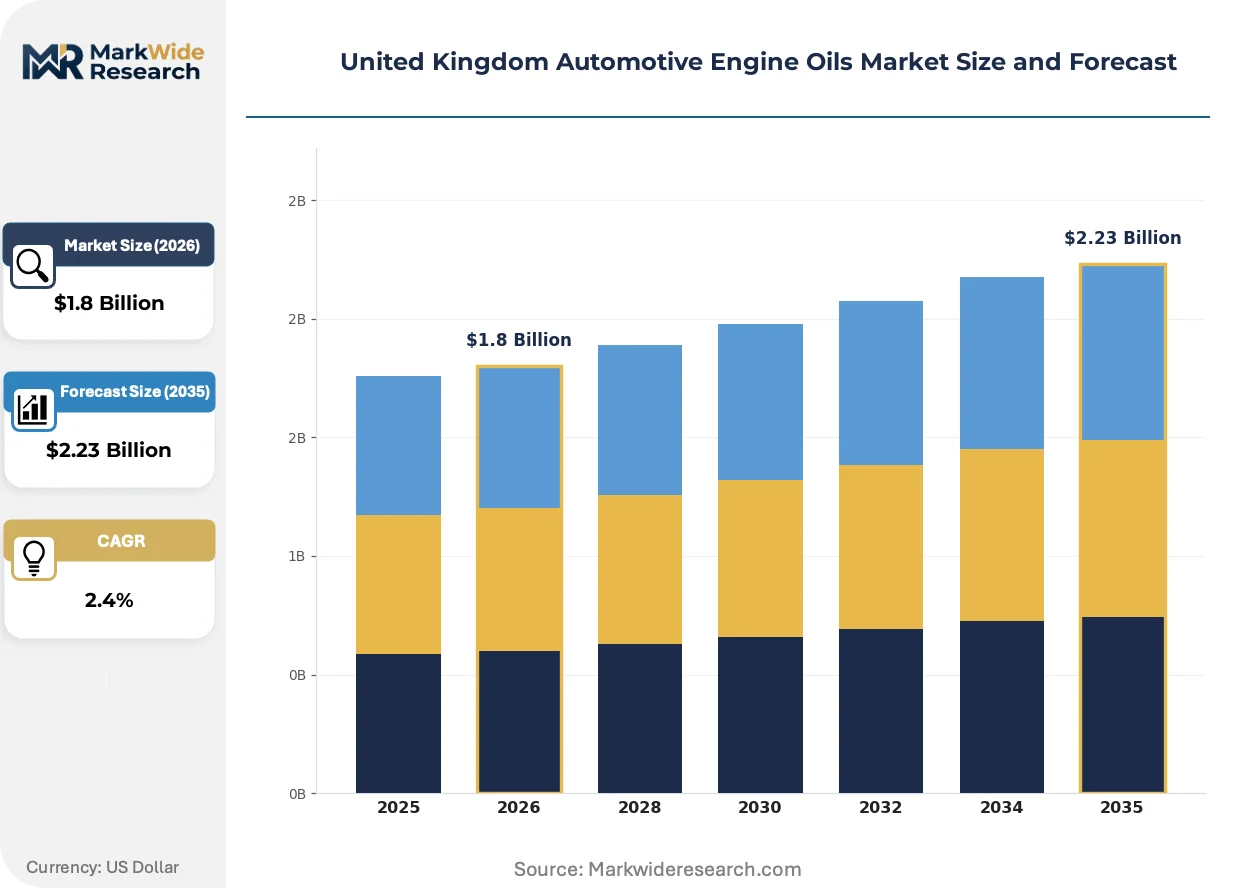
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Conventional, High Mileage, Diesel Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Bottle, Drum, Pail, Bulk End User: OEMs, Workshops, Retailers, Fleet Services |
| Companies Covered | Shell, BP p.l.c., ExxonMobil Corporation, Castrol, TotalEnergies S.E., Fuchs Group, Chevron Corporation, Exol Lubricants Limited, Morris Lubricants, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Automotive Engine Oils Market Evolving Landscape
Digital integration across lubricant supply chains is compressing the traditional distributor-wholesaler-retailer hierarchy. Real-time viscosity monitoring and predictive drain algorithms are displacing calendar-based maintenance schedules.
Artificial intelligence-driven oil analysis platforms are automating the interpretation of wear metal spectroscopy and particle count data. Fleet Services operators in the Midlands are deploying these systems at scale, reducing laboratory turnaround from days to hours. The technology is automating procurement trigger decisions, bypassing traditional distributor sales touchpoints entirely.
UK REACH substance restriction proposals for zinc dialkyldithiophosphate anti-wear additives are forcing reformulation investments across the supply chain. The Health and Safety Executive's workplace exposure limit enforcement is accelerating the shift to sealed dispensing systems in commercial workshops. Heavy-duty diesel engine oils face the most acute technical adaptation requirements as ash content limits tighten.
Centralized procurement through Fleet Services aggregators is displacing spot purchasing at individual depots. Major logistics operators are unbundling lubricant supply from broader maintenance contracts, creating standalone tenders that favor technical service capability over brand recognition. This pattern concentrates most visibly across England's motorway freight corridors where fuel-card-integrated maintenance networks dominate.
United Kingdom Automotive Engine Oils Market Segmentation
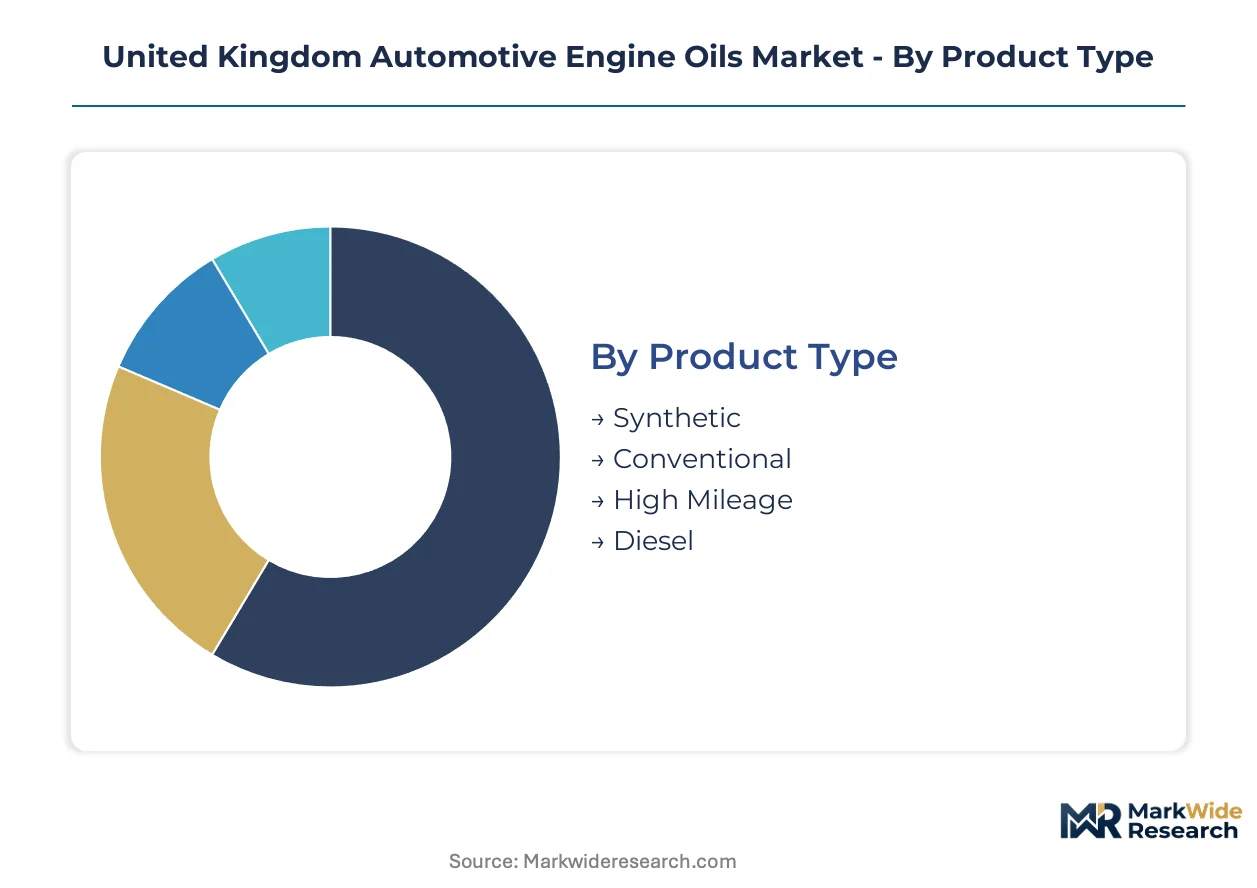
Segmentation in the UK automotive engine oils market reveals how formulation technology, distribution format, and customer procurement behavior create distinct margin profiles. Understanding these divisions exposes where synthetic premiums concentrate and where bulk logistics reshape competitive positioning.
Product Type:
Formulation chemistry determines whether oils function as standalone service items or embedded within long-drain maintenance programs.
- Synthetic:Manufactured from chemically engineered base stocks with uniform molecular structures, delivering thermal stability and extended drain intervals. Demand clusters in Fleet Services contracts across the Birmingham-Manchester corridor where OEM approval credentials and oil analysis integration justify price premiums.
- Conventional:Refined from crude petroleum with natural molecular variation, positioned for price-sensitive consumer segments and older vehicle parc. Workshop networks in Northern England still move significant volumes through bundled service packages despite synthetic conversion trends.
- High Mileage:Contains seal conditioners and anti-wear additives targeting engines exceeding 75,000 miles. Aging UK passenger car parc sustains demand through independent garage channels.
- Diesel:Higher total base number formulations neutralizing soot-induced acidity in compression-ignition engines. Commercial transport operators specify these for HGV and van fleets under centralized procurement.
Volume placements concentrate in Synthetic; the faster expansion belongs to High Mileage as vehicle parc aging extends.
Viscosity Grade:
Grade selection tracks engine design evolution and climate-driven cold-start requirements across UK operating conditions.
- 5W-30:The dominant multi-grade specification balancing low-temperature pumpability with high-temperature film strength. Modern passenger car OEM approvals from Volkswagen and Ford anchor demand in franchised workshop networks.
- 0W-20:Ultra-low viscosity formulation reducing parasitic friction for fuel economy compliance. Hybrid and downsized turbocharged engines in corporate fleets drive adoption despite higher formulation costs.
- 10W-40:Traditional multi-grade serving older vehicle stock and light commercial applications. Independent garages maintain inventory for service simplicity.
- 15W-50:Heavy-duty grade for high-performance and severe-duty applications. Motorsport-derived demand transfers to enthusiast segments with limited volume scale.
5W-30 commands the largest volume footprint; 0W-20 is climbing the fastest as OEM engine architecture tightens tolerances.
Packaging Type:
Container format aligns with customer scale and inventory velocity, separating retail convenience from industrial logistics.
- Bulk:Tanker-delivered fluid for high-throughput Fleet Services depots and major workshop groups. The Birmingham-Manchester industrial corridor hosts the densest concentration of bulk storage installations.
- Drum:205-litre steel containers serving mid-scale commercial workshops with moderate consumption rates. Steel drum return logistics create working capital friction for smaller distributors.
- Bottle:Consumer retail formats from 1-litre to 5-litre sizes. Motor factor and supermarket channels compete on shelf placement and brand recognition.
- Pail:20-25 litre plastic containers bridging retail and commercial segments. Independent garages favour pails for service bay flexibility without bulk infrastructure.
Drum placements dominate workshop procurement; Bulk is gaining share fastest as Fleet Services consolidation accelerates.
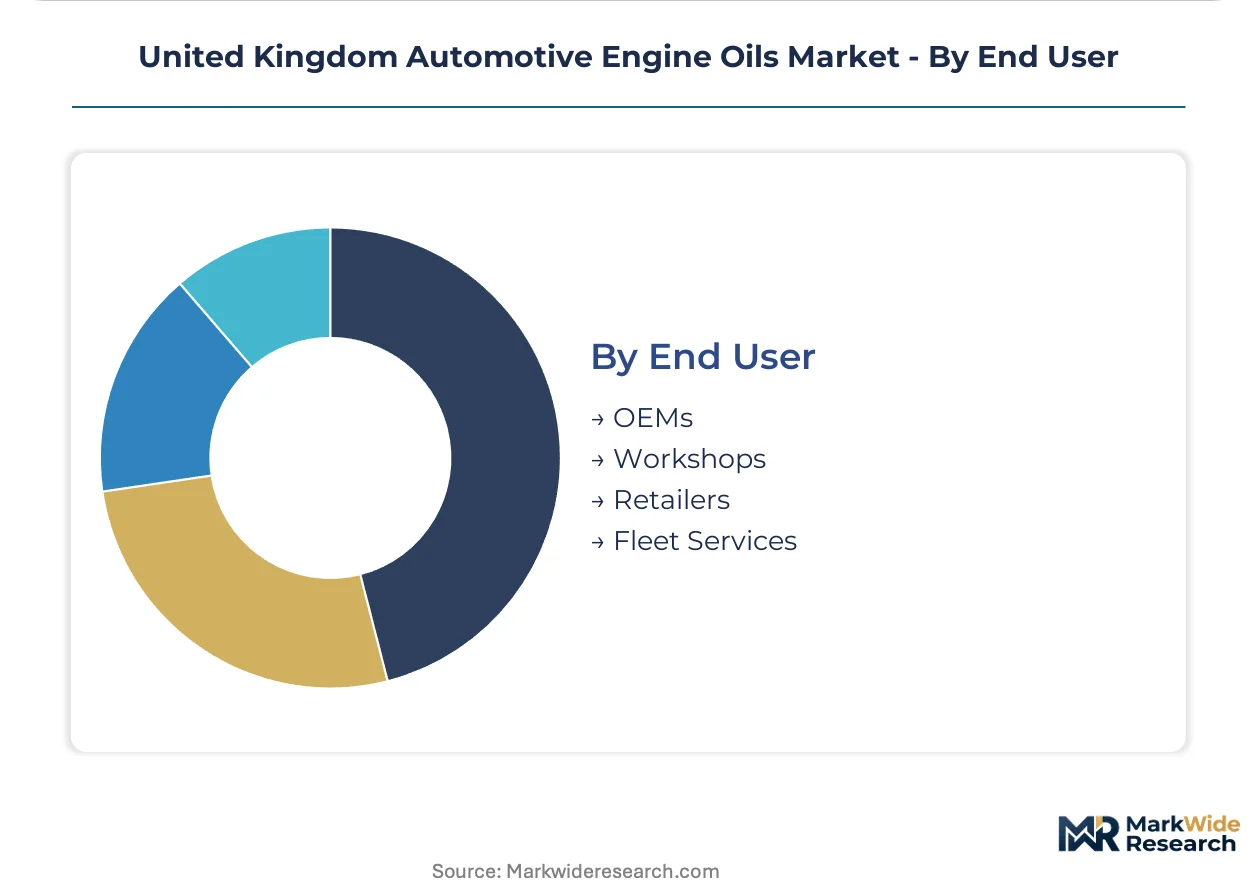
End User:
Customer type determines technical service intensity, contract structure, and brand loyalty mechanics.
- Fleet Services:Centralized maintenance procurement for commercial transport operators with embedded oil analysis and predictive drain programs. England's motorway freight corridors host the most sophisticated aggregators.
- Workshops:Franchise and independent service bays combining fluid sales with labour revenue. Technical support and training programs differentiate supplier relationships.
- OEMs:Factory-fill supply agreements and aftermarket genuine parts channels. Approval certification timelines create 18-24 month barriers to entry for new synthetic grades.
- Retailers:Motor factors, supermarkets, and online channels serving DIY maintenance. Price transparency and brand marketing drive conversion.
Workshops anchor current volume; Fleet Services shows the steepest expansion trajectory as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial transport density across England's industrial corridor concentrates lubricant demand in the Midlands and North West, with Scotland and Wales presenting distinct fleet service requirements shaped by remote logistics and devolved environmental regulations.
Midlands
The Birmingham-Manchester corridor hosts the densest concentration of Fleet Services aggregators, where centralized procurement contracts favor bulk synthetic formulations with embedded oil analysis. UK REACH enforcement through the Health and Safety Executive tightens chemical disclosure requirements for lubricant formulations processed through regional blending facilities. Wolverhampton and Stoke-on-Trent industrial zones concentrate re-refined base oil processing capacity serving circular economy mandates.
North England
Major logistics operators across Yorkshire and Lancashire unbundle lubricant supply from broader maintenance contracts, creating standalone tenders that prioritize technical service capability. The Department for Transport's vehicle emissions standards indirectly shape lubricant specifications through HGV fleet renewal programs. Teesside chemical processing clusters supply additive packages to regional blenders serving commercial transport corridors along the M62 motorway freight axis.
London and Southeast
Corporate fleet managers in the capital prioritize ultra-low viscosity grades for hybrid vehicle parc compliance with urban emissions zones. Transport for London's direct vision standard and clean air zone policies accelerate commercial vehicle turnover, pulling through OEM-approved synthetic demand. Gatwick and Heathrow airport logistics hubs concentrate high-specification diesel formulations for ground support equipment under centralized procurement.
Scotland
Remote freight operators across the Highlands and Islands require extended drain interval formulations to minimize service bay access constraints. The Scottish Environment Protection Agency enforces stricter waste oil recovery targets than England, accelerating re-refined base stock adoption in Aberdeen's offshore supply vessel sector. Grangemouth refining infrastructure anchors regional base oil supply security for North Sea commercial fleets.
Wales
Heavy quarrying and construction equipment fleets across South Wales drive demand for high-ash diesel formulations despite tightening passenger car synthetic conversion. Natural Resources Wales administers lubricant waste regulations that diverge from English enforcement patterns, creating compliance complexity for cross-border distributors. Newport and Cardiff port logistics clusters concentrate marine-engine lubricant blending capacity with technology transfer to on-road commercial applications.
United Kingdom Automotive Engine Oils Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty synthetic niches and re-refined circular economy positioning. The supplier base compresses around integrated refiners with captive base oil supply, independent blenders with regional workshop networks, and additive technology licensors. Three archetypes dominate: multinational integrated majors leveraging feedstock economics, mid-scale independents anchoring local service relationships, and specialty formulators targeting OEM approval credentials. Competitive moves concentrate on workshop partnership densification and Fleet Services contract consolidation.
Within the integrated major tier, Shell and BP p.l.c. exemplify scale-driven positioning through refining network control and direct OEM supply relationships. Castrol occupies a motorsport-derived technology archetype that transfers credibility to consumer and fleet marketing. Among independent specialists, Exol Lubricants Limited and Morris Lubricants represent regional blending capacity with workshop network anchoring across Northern England.
| Leading Market Players |
|---|
| Shell |
| BP p.l.c. |
| ExxonMobil Corporation |
| Castrol |
| TotalEnergies S.E. |
| Fuchs Group |
| Chevron Corporation |
| Exol Lubricants Limited |
| Morris Lubricants |
| Others |
Value Network & Pricing Analysis
UK REACH chemical disclosure mandates gate both qualified supply and premium-tier pricing access, as compliant additive packages and extended-drain synthetic formulations command margin premiums while excluding non-compliant blenders from Fleet Services tenders.
Pricing Analysis
Volume placements concentrate in conventional grades serving price-sensitive independent garages, while margin capture clusters in synthetic formulations with OEM approval credentials for Fleet Services contracts. Price differentiation hinges on certification tier and volume scale, with Volkswagen 504/507 or Mercedes-Benz 229.5 specifications justifying substantial premiums. Cost compression in conventional grades is intensifying because workshop networks in Northern England bundle fluid sales with labour revenue. Retail DIY channels show highest price sensitivity; Fleet Services aggregators with embedded oil analysis programs show lowest.
Supply Chain Analysis
Seaborne freight costs from Northwest European refiners expose UK lubricant blenders to currency fluctuation and margin instability. Feedstock draws from Belgium, the Netherlands, and Germany; additive packages rest on detergent-dispersant-inhibitor formulations controlled by four global chemical suppliers. Single-source vulnerability concentrates in Group II/III base oil import dependence. Distribution runs through tanker-delivered bulk for Fleet Services depots, drum formats for mid-scale workshops, and bottle retail for consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with players pursuing captive base oil supply to defend margin structures against import-dependent competitors.
For Market Incumbents: Lock in workshop partnership densification across Northern England's fragmented independent garage networks before emerging entrants acquire captive offtake channels. Prioritize backward integration into re-refined base oil processing capacity at Wolverhampton and Stoke-on-Trent to meet circular economy mandates. Battery electric vehicle penetration in passenger car parc threatens long-term addressable market; hydrogen combustion engine lubricant development offers heavy-duty offset. For New Entrants and Emerging Players: E-commerce platforms serving DIY maintenance enthusiasts represent the most penetrable route, bypassing established distributor-wholesaler hierarchies. Target high-mileage formulations for aging UK vehicle parc through direct-to-garage digital procurement. White-space exists in oil condition monitoring integration with telematics platforms for predictive Fleet Services contracts. For Investors and Strategic Acquirers: Standalone lubricant tenders unbundled from broader maintenance contracts is the leading indicator that technical service capability is displacing brand recognition as the primary valuation driver. Mid-scale independent blenders with regional workshop anchoring across Yorkshire and Lancashire present acquisition targets. Watch for OEM approval certification backlog creating 18-24 month barriers that entrench incumbent positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-refined Base Oil | Circular economy mandates from the Department for Transport accelerate recycled feedstock adoption in commercial fleet applications. |
| OEM Approval Certification Investment | Volkswagen 504/507 and Mercedes-Benz 229.5 specifications create 18-24 month barriers that entrench synthetic grade incumbents. |
| Fleet Services Contract Consolidation | Centralized procurement across England's Birmingham-Manchester corridor favors bulk logistics and embedded oil analysis programs. |
| Workshop Partnership Densification | Independent garage networks in Northern England remain fragmented acquisition targets for captive offtake channel control. |
| Hydrogen Combustion Engine Lubricant Development | UK freight operator trials require novel formulations managing hydrogen embrittlement and water contamination in heavy-duty powertrains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with lubricant blenders, Fleet Services procurement directors, workshop network operators, and additive technology suppliers. UK REACH substance registration databases, Health and Safety Executive workplace exposure guidelines, and Department for Transport vehicle emissions standards provided regulatory boundary conditions. Bottom-up volume triangulation across formulation grades, viscosity specifications, and packaging formats converged with top-down market sizing.
Data-stream reconciliation across supply-side production capacity, demand-side fleet parc analysis, and trade flow verification shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, viscosity grade, packaging format, and end-user procurement behavior. CAGRs derived from elasticity-adjusted volume projections incorporating OEM drain interval specifications and synthetic conversion trajectories. Re-refined base oil regulatory pathways and hydrogen combustion engine trial timelines served as scenario inputs.
Inputs from UK REACH registration databases and Health and Safety Executive enforcement records were available through the study window; gaps in real-time Fleet Services contract pricing introduce uncertainty bands around volume-value conversions. Forecasts reflect assumptions about synthetic grade adoption rates and circular economy mandate implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
EV Powertrain Market
Powertrain
Clutch Hub Puller Market
Powertrain
Crankshaft Position Sensor Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Timing Belt Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Clutch Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Transmission Oil Pumps Market
Powertrain
United States Automotive Engine Oils Market