
 Chassis Dynamometers Market | 2026-2036
Chassis Dynamometers Market Size, Share, and Industry Trends Forecast 2026-2036
Chassis Dynamometers Market Outlook
German test equipment manufacturing is realigning toward high-precision emissions certification systems. HORIBA Group leverages its Kyoto-based R&D base to sustain technology leadership in particulate measurement integration. AVL List GmbH anchors European OEM relationships through Graz-engineered powertrain test solutions. Mustang Dynamometer competes in North American aftermarket channels with modular dynamometer platforms.
Chassis dynamometers are precision electromechanical systems that apply controlled mechanical loads to vehicle wheels for measuring power output, fuel consumption, and exhaust emissions under simulated road conditions; units typically employ AC synchronous or eddy current absorption mechanisms capable of simulating inertial loads from 500 kg to 15,000 kg equivalent vehicle mass. Four-wheel drive configurations command premium positioning as electrified powertrains proliferate. Emissions testing applications face structural transformation as regulatory thresholds tighten. Electric absorption technology is displacing hydraulic alternatives in new installations due to energy recovery capabilities and programmable load precision.
EPA certification protocols in the United States and Euro 7 preparatory frameworks through EMA and member state type-approval authorities are mandating expanded real-driving emissions correlation with laboratory dynamometer results. China's MEE enforces GB standards alignment with WLTP-equivalent test cycles, forcing equipment upgrades at domestic vehicle plants. Stakeholders must monitor regulatory divergence between major automotive markets to anticipate capital deployment timing for test infrastructure modernization.
Market Dynamics
The chassis dynamometers sector is undergoing structural recalibration as Euro 7 preparatory protocols and China's GB standards alignment force automotive OEMs to retool test infrastructure ahead of tightened tailpipe and particulate thresholds.
Growth Catalysts
- Euro 7 Preparatory Frameworks:EMA and member state type-approval authorities are mandating expanded real-driving emissions correlation with laboratory dynamometer results, forcing test cell capacity expansion at German and Italian vehicle plants.
- Electric Powertrain Validation:Battery-electric and hybrid architectures require four-wheel drive dynamometer configurations for torque vectoring and regenerative braking calibration, pulling demand in South Korea and China.
- AC Synchronous Absorption:Electric absorption mechanisms with energy recovery capabilities are displacing hydraulic alternatives in new installations, driven by programmable load precision and operating cost reduction.
Market Restraints
- High-Precision Sensor Input Costs:Particulate number counters and FTIR exhaust analyzers rely on specialized optical components subject to supply concentration in German and Japanese component supply chains.
- Regulatory Divergence Friction:Misalignment between EPA certification protocols, Euro 7 frameworks, and China's MEE enforcement timelines forces equipment suppliers to maintain multiple certification tracks simultaneously.
- Extended Replacement Cycles:Dynamometer bases and absorption units operate on fifteen-to-twenty-year lifespans, compressing recurring revenue opportunities for original equipment providers.
Strategic Opportunities
- India Automotive Test Infrastructure:Domestic OEMs and component suppliers are building emissions certification capability ahead of BIS implementation of Bharat Stage VI Phase 2 equivalents, creating first-mover positioning for equipment providers.
- Retrofit and Upgrade Services:Existing two-wheel drive installations at North American and European facilities present conversion revenue as electrified powertrains mandate all-wheel drive testing capability.
- Software-Defined Test Cycles:Integration of dynamometer hardware with cloud-based data acquisition platforms enables remote calibration support and predictive maintenance contracts.
Industry Challenges
- Mechatronics Talent Scarcity:Synchronous motor control, real-time embedded systems, and emissions measurement science require specialized engineering profiles in short supply across Graz, Stuttgart, and Nagoya industrial clusters.
- Multi-Protocol Certification Complexity:Test equipment must simultaneously satisfy EPA, EMA, and MEE validation requirements, extending development timelines and engineering validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chassis Dynamometers Market |
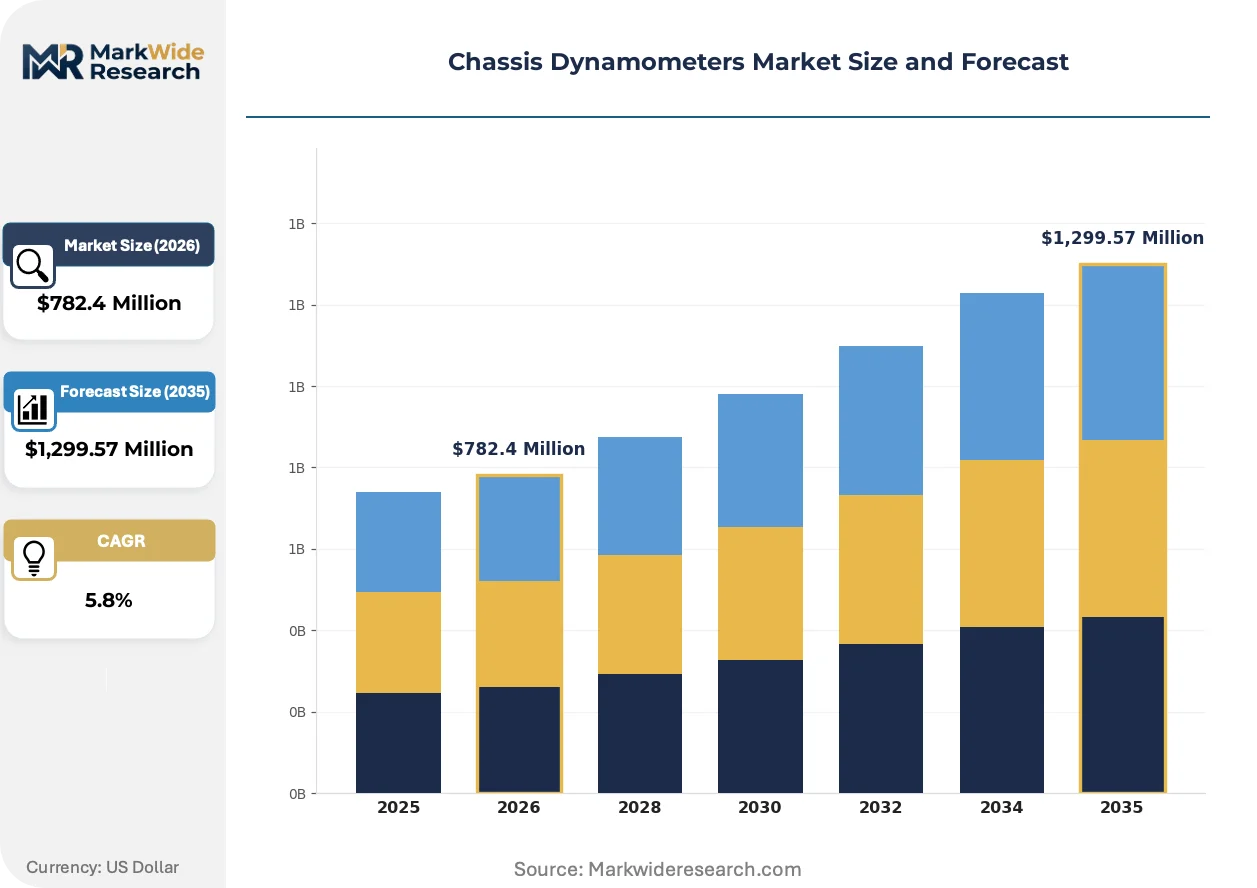
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,299.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheel Drive, Four-Wheel Drive, All-Wheel Drive, Mobile End User: Automobile Manufacturers, Research Institutions, Aftermarket Providers, Fleet Owners Technology: AC Synchronous, DC Braking, Hydraulic, Electric Application: Performance Testing, Fuel Economy Testing, Emissions Testing, Durability Testing |
| Companies Covered | HORIBA Group, AVL List GmbH, Mustang Dynamometer, MEIDENSHA CORPORATION, Ono Sokki, Rototest International AB, MAHA Maschinenbau Haldenwang, MTS Systems Corporation, Power Test, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chassis Dynamometers Market Strategic Shifts
Hardware-software convergence is redefining competitive positioning in chassis dynamometers, as electromechanical load application merges with virtual vehicle simulation and cloud-based test data management to compress development cycles.
AC synchronous absorption technology is consolidating market preference for new installations. These systems recover electrical energy during deceleration simulation rather than dissipating it as heat. German and Japanese OEM test facilities are specifying synchronous configurations for all-wheel drive cells. The technology is consolidating supplier margins by reducing auxiliary cooling infrastructure and enabling continuous-duty test cycles previously impractical with eddy-current alternatives.
China's MEE enforcement of GB standards alignment with WLTP-equivalent test cycles is forcing equipment upgrades at domestic vehicle plants. The regulation mandates correlation between laboratory dynamometer results and portable emissions measurement system data collected on public roads. Domestic Chinese OEMs and joint-venture facilities are responding with accelerated procurement of four-wheel drive configurations capable of simulating complex urban driving profiles.
Service unbundling is reshaping buyer-supplier relationships in the aftermarket channel. North American independent test facilities and vehicle modification shops are separating hardware acquisition from calibration support and test cycle programming. This pattern is most visible in California and Texas, where specialty builders purchase modular dynamometer platforms while sourcing EPA-compliant test procedures and emissions analyzer integration from third-party engineering services firms.
Chassis Dynamometers Market Segmentation
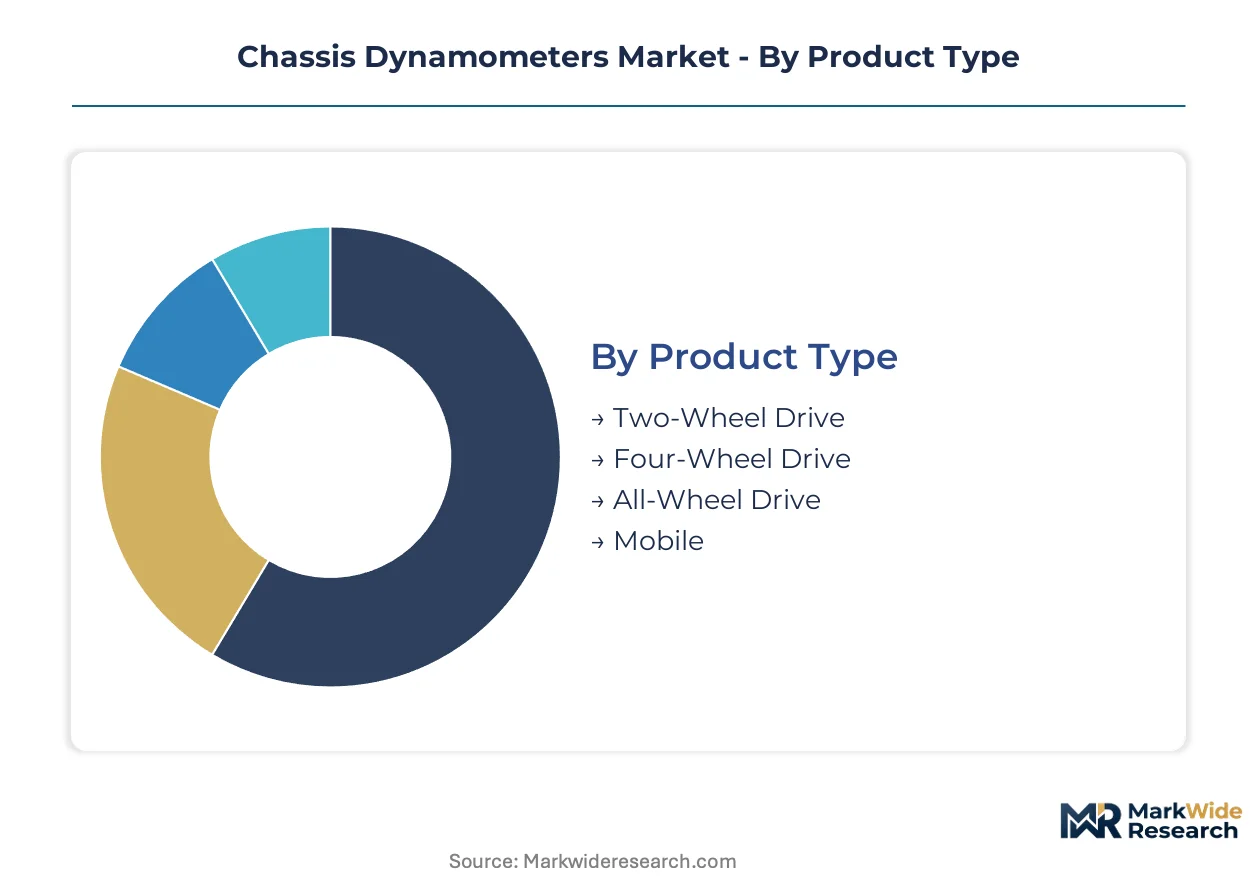
Chassis dynamometer procurement varies sharply by test protocol complexity and vehicle architecture requirements. Equipment specification cascades from regulatory certification mandates through powertrain electrification trends, creating distinct performance tiers across product configurations.
Product Type:
Standard two-wheel drive platforms dominate entry-level installations, while four-wheel and all-wheel drive variants command premium positioning for electrified powertrain validation.
- Two-Wheel Drive:Single-axle absorption units employ eddy-current or AC synchronous mechanisms for front- or rear-wheel drive vehicle testing. Fleet operators in Texas and California specify these for routine power verification and diagnostic screening where regulatory certification is not required.
- Four-Wheel Drive:Dual-axle configurations with independent torque control simulate complex traction scenarios for hybrid and battery-electric vehicles. South Korean OEMs in Ulsan and Chinese manufacturers in Shanghai are expanding test cell capacity with these systems ahead of GB standards alignment.
- All-Wheel Drive:Precision torque-vectoring dynamometers enable calibration of multi-motor electric architectures. German OEM facilities in Stuttgart and Munich specify these for Euro 7 preparatory testing.
- Mobile:Transportable trailer-mounted units serve field validation and motorsport applications. Independent test contractors in North America deploy these for on-site fleet certification.
Leading the category by volume: Two-Wheel Drive. Growing fastest: Four-Wheel Drive.
End User:
Procurement authority concentrates with OEMs building in-house certification capability, while aftermarket channels fragment across independent service providers and fleet operators.
- Automobile Manufacturers:German and Japanese OEMs anchor demand through vertically integrated test facilities. These buyers specify integrated emissions analyzer compatibility and multi-protocol software support.
- Research Institutions:University engineering departments and national laboratories in the United States and Germany acquire dynamometers for powertrain research. Funding cycles and grant dependencies create lumpy procurement patterns.
- Aftermarket Providers:Independent vehicle modification shops and specialty tuners purchase modular platforms. California smog certification shops drive steady replacement demand.
- Fleet Owners:Commercial vehicle operators in logistics and transit sectors deploy dynamometers for preventive maintenance programs. Cost sensitivity favors refurbished two-wheel drive units.
Dominant procurement volume sits with Automobile Manufacturers. Aftermarket Providers are expanding most quickly on electrification service demand.
Technology:
Absorption mechanism selection determines energy recovery capability, load precision, and cooling infrastructure requirements across installation types.
- AC Synchronous:Regenerative systems recover electrical energy during deceleration simulation, eliminating heat dissipation infrastructure. New OEM installations in Germany and Japan specify this technology exclusively.
- DC Braking:Ward Leonard or similar configurations persist in legacy installations. Replacement demand is compressing as operators migrate to synchronous alternatives.
- Hydraulic:Fluid-based absorption using water or oil couplings retains niche presence in heavy-duty commercial vehicle testing. Indian commercial vehicle plants in Pune maintain installed base.
- Electric:Broad category encompassing eddy-current and powder brake variants. Aftermarket providers in Texas favor these for lower capital outlay and simpler maintenance.
AC Synchronous commands the highest share of new installations. Electric (non-synchronous) retains largest installed base.
Application:
Test cycle specification drives hardware configuration, with emissions certification imposing the most stringent precision and correlation requirements.
- Performance Testing:Power output measurement and acceleration simulation for vehicle development and marketing claims. Motorsport facilities in the United Kingdom and Italy specify high-speed configurations.
- Fuel Economy Testing:Standardized drive cycle replication for corporate average fuel economy compliance. EPA certification protocols in the United States mandate specific inertia weight simulation accuracy.
- Emissions Testing:Correlation of laboratory dynamometer results with portable emissions measurement system data. Euro 7 preparatory frameworks through EMA are forcing test cell upgrades.
- Durability Testing:Accelerated life cycle simulation for powertrain components. Commercial vehicle manufacturers in Japan deploy continuous-duty configurations.
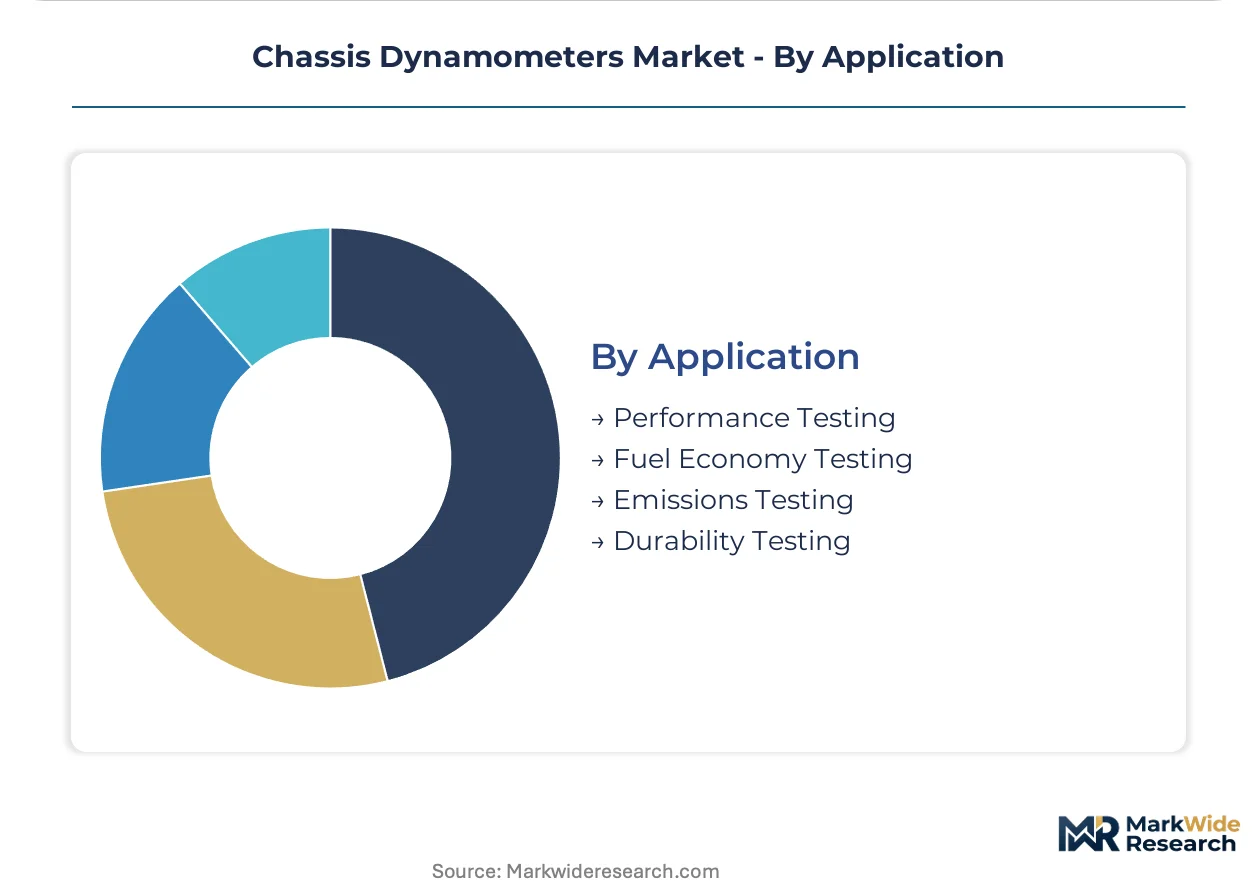
Emissions Testing generates highest equipment specification intensity. Durability Testing shows steepest expansion trajectory on commercial vehicle electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized steel and precision-machined components from German and Japanese industrial bases supply the electromechanical foundations for chassis dynamometer manufacturing. Equipment procurement clusters around automotive R&D centers where regulatory certification requirements concentrate test infrastructure investment.
Germany
OEM test cell expansion in Stuttgart and Munich responds to KBA enforcement of Euro 7 preparatory protocols. The EMA framework mandates correlation between laboratory dynamometer results and real-driving emissions data. Baden-Württemberg's automotive engineering corridor anchors European demand for four-wheel drive configurations.
United States
EPA certification protocols drive procurement at vehicle development centers in Michigan and California. The IRA's clean vehicle tax credits accelerate powertrain electrification programs requiring upgraded test infrastructure. Detroit's engineering base sustains demand for durability testing configurations.
China
Domestic OEMs in Shanghai and Beijing expand four-wheel drive capacity ahead of MEE enforcement of GB standards alignment with WLTP-equivalent cycles. The MIIT's new energy vehicle mandates pull demand toward all-wheel drive torque vectoring validation. Yangtze River Delta manufacturing clusters concentrate equipment deployment.
Japan
METI's carbon neutrality roadmap forces test infrastructure modernization at Nagoya and Tokyo facilities. JIS standards harmonization with international certification protocols sustains replacement demand. Chubu region precision engineering suppliers feed synchronous motor component requirements.
South Korea
Hyundai and Kia electrification programs in Ulsan and Gwangju drive four-wheel drive dynamometer procurement. The MFDS alignment with international emissions measurement standards forces analyzer upgrades. Seoul Capital Area engineering services clusters support calibration contract growth.
Chassis Dynamometers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-integrated test cycle management and cloud-based data platforms. The vendor base stratifies between vertically integrated precision equipment manufacturers and modular platform assemblers serving aftermarket channels. Two dominant archetypes prevail: Kyoto-engineered measurement science specialists and Graz-anchored powertrain test solution providers. Competitive moves center on synchronous absorption technology licensing and retrofit service network expansion.
Within the precision measurement tier, HORIBA Group and AVL List GmbH exemplify contrasting geographic anchoring strategies. HORIBA's Kyoto-based operations represent Japanese consolidation of particulate measurement integration capabilities. AVL's Graz-engineered solutions anchor European OEM relationships through vertically integrated powertrain test cell design. Mustang Dynamometer occupies a distinct position in North American aftermarket channels, exemplifying modular platform competition against integrated system providers. These three entities collectively represent the geographic and business model segmentation defining competitive positioning.
| Leading Market Players |
|---|
| HORIBA Group |
| AVL List GmbH |
| Mustang Dynamometer |
| MEIDENSHA CORPORATION |
| Ono Sokki |
| Rototest International AB |
| MAHA Maschinenbau Haldenwang |
| MTS Systems Corporation |
| Power Test |
| Others |
Value Chain & Pricing Dynamics
Euro 7 emissions compliance mandates gate qualified supply access and premium-tier pricing power for chassis dynamometer manufacturers serving European OEM certification programs. Equipment suppliers must demonstrate correlation protocols between laboratory dynamometer results and real-driving emissions data to command tier-one positioning, while aftermarket providers face pricing compression from unbundled service competition.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier suppliers from modular platform competitors in the chassis dynamometer market. Project-based pricing dominates OEM certification contracts, with price differentiation driven by multi-protocol software support and synchronous absorption technology integration. Cost compression in the aftermarket channel intensifies as independent test facilities separate hardware acquisition from third-party calibration services. Fleet operators and independent modification shops exhibit highest price sensitivity, while German and Japanese OEMs prioritize precision and correlation capability over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart, Munich, and Nagoya engineering centers, while aftermarket distribution runs through regional equipment distributors in Texas and California. Precision-machined components and synchronous motor assemblies draw from German and Japanese industrial bases, with specialized optical sensors for particulate measurement anchored in Japanese component supply chains. Single-source vulnerability concentrates in high-precision sensor inputs for FTIR exhaust analyzers. Equipment manufacturers maintain dual certification tracks to manage regulatory divergence friction across EPA, EMA, and MEE validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chassis dynamometer sector sits in a technology-transition phase as AC synchronous absorption systems displace hydraulic and legacy electric alternatives across new OEM installations. This electromechanical shift reconfigures competitive positioning and capital deployment priorities for market participants.
For Market Incumbents: To counter emerging software-integrated platform competitors, HORIBA Group and AVL List GmbH should deepen captive supply of synchronous motor control systems and expand retrofit service networks at European and North American facilities with legacy two-wheel drive installations. Certification investment in multi-protocol test cycle software will defend positioning against modular platform assemblers.
For New Entrants and Emerging Players: Capture the India automotive test infrastructure buildout ahead of BIS implementation of Bharat Stage VI Phase 2 equivalents, where domestic OEMs and component suppliers lack established supplier relationships. Cloud-based test data management and predictive maintenance contracts offer a software-first go-to-market angle distinct from capital-intensive equipment manufacturing.
For Investors and Strategic Acquirers: Accelerated procurement of four-wheel drive configurations by Chinese OEMs ahead of MEE enforcement of GB standards alignment is the leading indicator that torque-vectoring validation capability will command acquisition premiums. Target equipment providers with synchronous absorption technology licensing and established calibration service networks. Periodic monitoring of Euro 7 preparatory protocol finalization timelines will signal inflection timing for European test infrastructure modernization capex.
| Strategic Initiative | Industry Significance |
|---|---|
| Synchronous Absorption Technology Licensing | Energy recovery capabilities reduce operating costs at German and Japanese OEM facilities. |
| Retrofit Service Network Expansion | Two-wheel drive conversion revenue accelerates as electrified powertrains mandate all-wheel drive testing. |
| Multi-Protocol Software Development | Simultaneous EPA, EMA, and MEE validation extends addressable market for certification equipment. |
| Cloud-Based Test Data Platform Integration | Remote calibration support enables recurring revenue contracts with North American aftermarket providers. |
| India Market Entry Partnership | BIS Phase 2 preparatory demand creates first-mover positioning in emissions certification infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this chassis dynamometer market analysis. Primary interviews with OEM test cell engineers, aftermarket equipment distributors, and emissions measurement specialists combined with EPA certification protocol documentation, EMA type-approval frameworks, and MIIT new energy vehicle mandates. Bottom-up equipment procurement tracking and top-down automotive R&D capex analysis provided triangulation across the analysis window.
Data-stream reconciliation connected vehicle production forecasts, regulatory timeline assumptions, and powertrain electrification trajectories across the projection horizon. Segmentation dimensions modeled include product configuration, absorption technology, end-user archetype, and application protocol complexity. CAGRs derived from equipment replacement cycle analysis and test infrastructure modernization capex patterns. Industry-specific inputs incorporated Euro 7 preparatory protocol development and China's GB standards alignment enforcement timelines.
The model holds under stable regulatory implementation schedules and continuous powertrain electrification; deviation in emissions standard delay or synchronous motor component supply disruption would shift equipment procurement timing and geographic demand concentration. Periodic stress-testing of base assumptions against MEE enforcement announcements and KBA certification requirement updates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Automated Guided Cart Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market