
 Engine Tuner Market | 2026-2036
Engine Tuner Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Tuner Market Foresight
EPA Tier 3 emission standards is broadening the cost-of-entry calculus for aftermarket engine tuning, forcing calibration houses to invest in certified emissions testing infrastructure. COBB Tuning leverages its in-house dynamometer network to validate street-legal calibrations across multiple vehicle platforms. HP Tuners anchors its position through proprietary software that interfaces with factory ECU architectures without hardware replacement. BorgWarner competes by extending its turbocharger expertise into integrated boost-control tuning packages for OEM and aftermarket channels.
An engine tuner is an electronic device or software platform that modifies engine control unit parameters—fuel injection timing, ignition advance, boost pressure thresholds, and air-fuel ratios—to optimize power output, thermal efficiency, or emissions compliance. These systems operate through OBD-II ports, bench-mode flashing, or piggyback interceptors, serving both consumer performance upgrades and professional motorsport applications. Flash tuning dominates the technology landscape due to its reversible, non-invasive nature and compatibility with modern encrypted ECU architectures. The automotive aftermarket end-user segment leads volume, while racing teams command premium pricing for bespoke calibration services. Performance enhancement applications anchor demand, though emission control tuning is gaining structural importance as regulatory compliance becomes a purchase prerequisite.
FCC governs wireless telemetry interfaces in connected tuning devices, EPA sets tailpipe emission limits that aftermarket modifications must preserve, and CARB administers the executive order certification system that determines street-legal status in California and sixteen adopting states. Compliance with these overlapping frameworks shapes product development roadmaps and determines market access for non-certified devices. Stakeholders must monitor the trajectory of EPA enforcement against defeat-device provisions and the expansion of CARB reciprocal agreements into additional state jurisdictions.
Market Dynamics
Encrypted ECU architectures from Bosch, Continental, and Denso are forcing calibration houses to abandon piggyback interceptors in favor of bench-mode flashing and OBD-II bypass protocols. This technical pivot elevates R&D thresholds and concentrates development among firms with direct OEM data-licensing relationships.
Growth Catalysts
- EPA Tier 3 tailpipe mandates:Compliance requirements for nitrogen oxide and particulate matter limits are expanding the addressable market for emission-legal tuning solutions that preserve factory catalyst efficiency.
- Track-day participation:Amateur motorsport events at circuits like Silverstone, Suzuka, and Laguna Seca are sustaining demand for switchable calibration maps that toggle between street-legal and competition modes.
- Flex-fuel sensor integration:Ethanol content analyzers paired with adaptive fuel tables are enabling safe E85 operation on factory hardware without injector replacement.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries produce the majority of ECU communication chips used in tuning interfaces, exposing calibration houses to allocation delays.
- Defeat-device enforcement:EPA civil penalty authority under the Clean Air Act creates liability exposure for distributors of emission-control-defeating software.
- Flash counter detection:Factory ECUs with permanent modification logging void powertrain warranties and suppress consumer willingness to tune.
Strategic Opportunities
- India two-wheeler segment:BS6 Phase II emission standards and the country's 125 million registered motorcycles create a white space for affordable fuel-injection remapping tools.
- Telematics-linked tuning:Integration with connected vehicle platforms enables over-the-air calibration updates and subscription-based performance tiering.
- Heavy-duty diesel retrofit:CARB-verified emission control strategies for pre-2010 truck engines open fleet service channels beyond passenger vehicles.
Industry Challenges
- Reverse engineering talent scarcity:Factory ECU encryption protocols require specialized firmware analysis skills that command premium compensation and lengthen hiring cycles.
- Homologation timeline compression:CARB executive order certification demands 50,000-mile durability testing that extends product launch schedules by 18-24 months.
- Cross-platform calibration complexity:Each vehicle powertrain variant requires individualized spark, fuel, and boost mapping that fragments development resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Tuner Market |
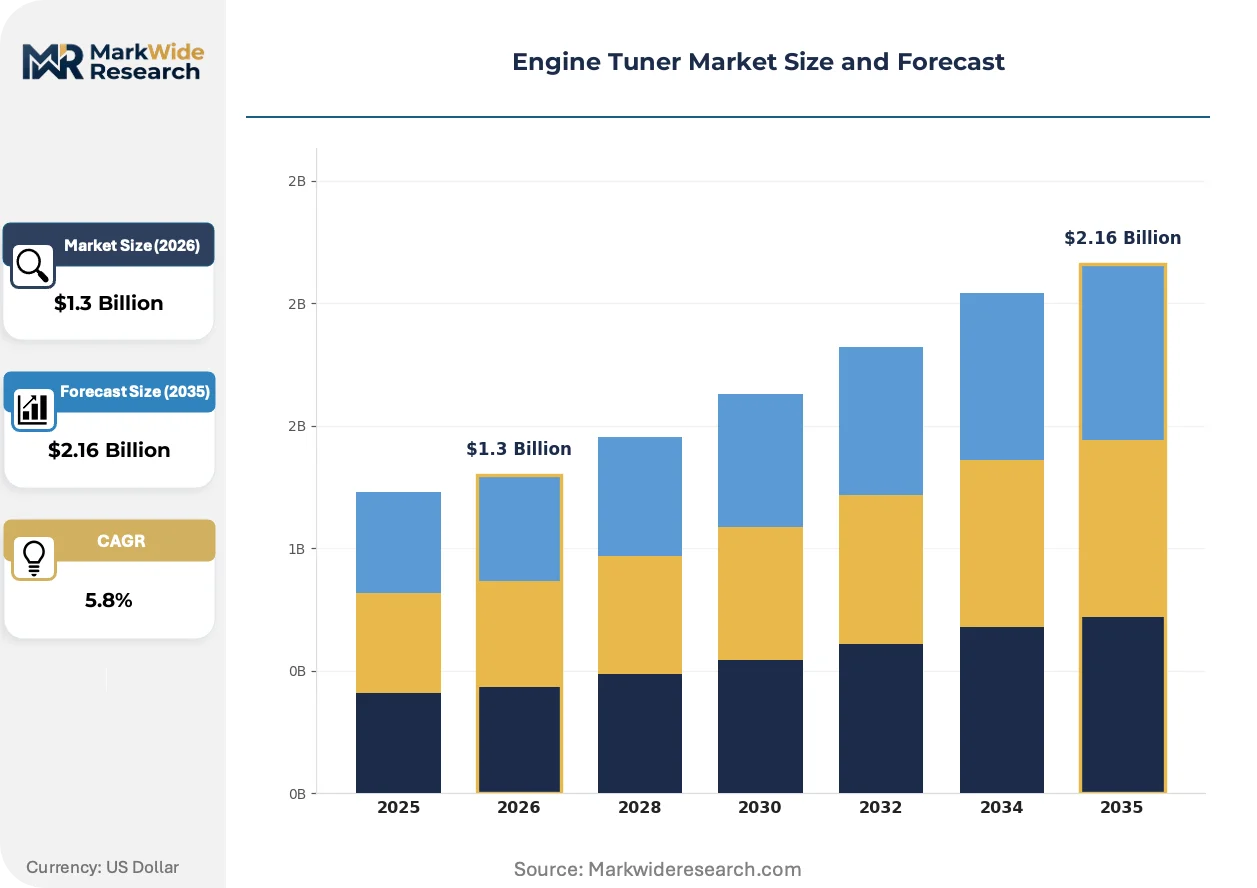
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Tuners, ECU Programming Tools, Diagnostic Scanners, Performance Chips End User: Automotive Aftermarket, OEMs, Racing Teams, DIY Enthusiasts Technology: Flash Tuning, Chip Tuning, Piggyback Systems, Software-Based Programming Application: Performance Enhancement, Fuel Efficiency, Emission Control, Engine Diagnostics |
| Companies Covered | COBB Tuning, HP Tuners, AEM Electronics, Alientech SRL, Magic Motorsports, Derive Systems, BorgWarner, APR, Garrett Motion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Tuner Market Shifts & Advancements
Flash-based calibration protocols are displacing hardware-intensive tuning methods across both consumer and professional segments. This shift compresses marginal costs while elevating software IP as the primary competitive differentiator.
Cloud-connected dyno logging is rewriting how tuners validate street calibrations. Remote data upload from customer vehicles enables iterative map refinement without physical shop visits. Professional calibration houses in Germany and Japan are adopting this workflow to serve dispersed motorsport clients. The practice is compressing the feedback loop between road testing and map release.
CARB's expansion of reciprocal agreements into sixteen adopting states is tightening the regulatory perimeter for uncertified devices. The executive order system now determines street-legal status across a majority of US vehicle registrations. Aftermarket distributors are consolidating inventory around CARB-verified SKUs and discontinuing gray-market imports. This policy diffusion is elevating compliance documentation to a primary purchase criterion.
Buyer preference is rotating toward emission-legal performance tiers that preserve factory warranty coverage. Enthusiast forums and social media channels amplify verification of CARB EO numbers and flash counter stealth. This behavioral shift favors calibration providers with documented regulatory compliance over raw power claims. The United States and Germany exhibit the strongest certification-driven purchasing patterns.
Engine Tuner Market Segmentation
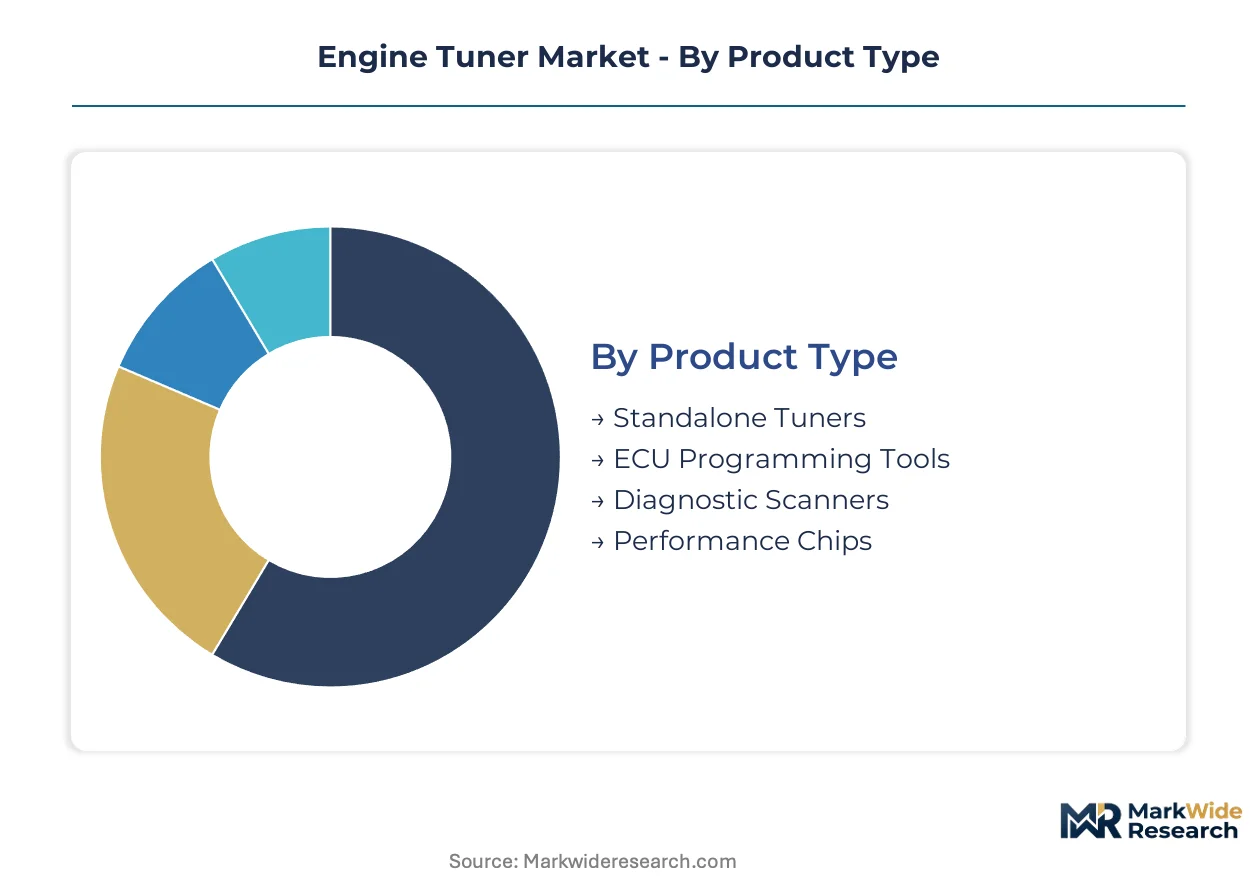
Engine tuner segmentation reveals how supply-side capabilities align with divergent customer technical sophistication and regulatory exposure. Product architecture choices determine whether vendors compete on hardware margins or recurring software licensing.
Product Type:
Supply concentration favors vendors with integrated manufacturing of both hardware interfaces and proprietary calibration software.
- Standalone Tuners:Handheld devices with pre-loaded maps for specific vehicle platforms. Demand concentrates in the United States where CARB executive order certification determines street-legal retail access. EPA enforcement against defeat devices elevates compliance documentation to a primary purchase filter.
- ECU Programming Tools:Laptop-based software suites enabling custom map authoring. Professional calibration houses in Germany and Japan anchor demand for these systems, where direct OEM data-licensing relationships create supply concentration among established firmware analysis firms.
- Diagnostic Scanners:OBD-II interfaces with read-only capabilities for fault code extraction. Fleet service channels drive volume.
- Performance Chips:Physical module replacements requiring ECU socket modification. Legacy demand persists among pre-2000 vehicle owners.
Today's leader: Standalone Tuners. Tomorrow's challenger: ECU Programming Tools.
End User:
Application requirements fragment procurement patterns across warranty-sensitive consumers and liability-tolerant competition operators.
- Automotive Aftermarket:Independent garages and specialty retailers serving consumer performance upgrades. Volume concentrates in jurisdictions with mature motorsport cultures—United States, Germany, Japan—where enthusiast infrastructure sustains recurring calibration purchases.
- Racing Teams:Professional motorsport operations requiring bespoke calibration for specific track conditions. Laguna Seca, Silverstone, and Suzuka circuit proximity anchors regional service provider ecosystems.
- OEMs:Vehicle manufacturers integrating tuning capabilities into factory infotainment systems.
- DIY Enthusiasts:Individual consumers performing home garage installations. Social media verification of CARB EO numbers shapes purchase behavior.
Automotive Aftermarket commands current volume. Racing Teams capture premium pricing tiers.
Technology:
Encrypted ECU architectures from Bosch, Continental, and Denso are forcing technical pivots that elevate R&D thresholds.
- Flash Tuning:Direct ECU memory rewriting through OBD-II or bench-mode protocols. Reversible modifications preserve factory warranty coverage where flash counter stealth succeeds. This segment gains share fastest as encrypted architectures render hardware interceptors obsolete.
- Chip Tuning:Physical EPROM replacement requiring ECU disassembly. Pre-2005 vehicle applications dominate residual demand.
- Piggyback Systems:Signal interceptors modifying sensor inputs before ECU processing. Regulatory pressure and encryption advances compress addressable market.
- Software-Based Programming:Cloud-connected platforms enabling over-the-air calibration updates. Telematics integration opens subscription revenue models.
Flash Tuning dominates technology selection. Software-Based Programming offers the steepest expansion trajectory.
Application:
Regulatory compliance is displacing raw power metrics as the primary purchase determinant across all customer segments.
- Performance Enhancement:Power and torque optimization for acceleration and top-speed improvement. United States enthusiast demand increasingly filters through CARB EO number verification before purchase commitment.
- Emission Control:Calibration preserving or improving tailpipe pollutant metrics. EPA Tier 3 nitrogen oxide and particulate matter mandates expand addressable market for certified solutions.
- Fuel Efficiency:Air-fuel ratio optimization for consumption reduction. Fleet operators anchor commercial demand.
- Engine Diagnostics:Fault detection and logging capabilities. Integration with connected vehicle platforms enables predictive maintenance services.
Performance Enhancement retains volume leadership. Emission Control is climbing the fastest as compliance becomes prerequisite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calibration engineering talent concentrates in Germany's automotive corridor, Japan's precision electronics belt, and the United States' motorsport hubs. These workforce clusters anchor regional demand patterns and shape regulatory compliance capabilities.
United States
Amateur track-day participation at Laguna Seca and amateur drag strips sustains demand for switchable calibration maps. EPA Tier 3 enforcement under the Clean Air Act elevates compliance documentation to a primary purchase filter. Southern California's aftermarket garage ecosystem drives volume for CARB-certified handheld tuners.
Germany
Professional calibration houses serving Nürburgring and Hockenheim circuit proximity anchor premium bespoke services. KBA type-approval requirements for emission-relevant modifications shape product development timelines. Stuttgart's automotive engineering cluster concentrates firmware reverse-engineering expertise for encrypted Bosch ECU architectures.
Japan
Suzuka Circuit and Fuji Speedway proximity sustains motorsport calibration demand alongside domestic tuning culture. METI safety standards for vehicle modifications create compliance thresholds for consumer-facing products. Nagoya's automotive supplier corridor hosts specialized dyno facilities for Denso and Continental ECU validation.
United Kingdom
Silverstone and Brands Hatch track-day programs sustain amateur motorsport tuning demand. DVSA inspection requirements for modified vehicles influence consumer preference for reversible flash solutions. Motorsport Valley's engineering services cluster around Oxfordshire and Northamptonshire supports professional calibration houses.
India
BS6 Phase II emission standards and 125 million registered motorcycles create white space for affordable fuel-injection remapping. BIS certification requirements for automotive electronics shape import and domestic manufacturing strategies. Pune's automotive component belt hosts emerging calibration service providers for two-wheeler platforms.
Engine Tuner Market Competitive Landscape
The competitive structure tilts toward software-centric calibration houses with direct OEM data-licensing relationships. R&D thresholds from encrypted ECU architectures have concentrated development among firms with specialized firmware analysis capabilities. Two archetypes dominate: integrated hardware-software vendors with in-house dyno networks, and pure-play software platforms licensing ECU interface protocols. Competitive moves center on geographic expansion into emission-regulated markets and technology licensing for telematics-linked tuning.
Among North American specialists, COBB Tuning and HP Tuners exemplify divergent strategic positions within the software-centric tier. COBB Tuning represents the integrated archetype with captive validation infrastructure, while HP Tuners occupies the pure-play software licensing position. European presence concentrates in Italian and German specialists, with Alientech SRL and Magic Motorsports anchoring the continental calibration house tradition. BorgWarner's turbocharger heritage extends into boost-control tuning packages, representing industrial-component diversification into aftermarket channels.
| Leading Market Players |
|---|
| COBB Tuning |
| HP Tuners |
| AEM Electronics |
| Alientech SRL |
| Magic Motorsports |
| Derive Systems |
| BorgWarner |
| APR |
| Garrett Motion |
| Others |
Supply & Pricing Matrix
Semiconductor wafer pricing indices from Taiwan-based foundries cascade through ECU interface manufacturing into tiered calibration product pricing. Cost compression in entry-level handheld tuners intensifies as chip allocation delays force volume manufacturers toward premium software-licensing models that offset hardware margin erosion.
Pricing Analysis
Bundled hardware-software packages dominate the premium tier, while unbundled software licenses capture mid-market professional calibration houses. Price differentiation hinges on CARB executive order certification status and proprietary OEM data-licensing depth. Pricing pressure stems from encrypted ECU architectures elevating R&D amortization across smaller production runs. DIY enthusiasts exhibit highest price sensitivity; racing teams and OEM channels demonstrate lowest.
Supply Chain Analysis
Direct-to-garage distribution channels handle aftermarket volume, while direct-to-OEM relationships anchor enterprise calibration services. Taiwan, China, and South Korea concentrate ECU communication chip fabrication. The supply chain draws from rare earth elements for magnetic components, copper for wiring harnesses, and specialized polymers for thermal housing. Single-source vulnerability in Taiwan-based foundry capacity creates allocation risk. Distribution runs through specialty automotive retailers, online direct-to-consumer platforms, and professional calibration house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA Tier 3 compliance costs in the United States and BS6 Phase II regulatory gaps in India, where emission tuning tools face lower certification barriers.
For Market Incumbents: Acquire firmware reverse-engineering talent pools to defend against encrypted ECU architecture escalation. Consolidate around CARB-verified calibration libraries before reciprocal agreement expansion tightens retail access. Deepen backward integration into in-house dynamometer networks to compress validation timelines and reduce third-party testing dependency.
For New Entrants and Emerging Players: Capture India's two-wheeler fuel-injection remapping white space before domestic calibration houses scale. Target affordable diagnostic-tuner hybrids for BS6 Phase II motorcycle garages in Pune and Chennai. Lead with telematics-linked subscription pricing to bypass upfront hardware cost barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play software platforms licensing ECU interface protocols rather than hardware-dependent vendors. Long-term viability favors firms with documented OEM data-licensing relationships and CARB certification track records. Monitor EPA enforcement action frequency against defeat-device distributors as inflection indicator for compliance-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CARB Executive Order Certification Investment | Unlocks retail access across sixteen adopting states and California's aftermarket garage ecosystem. |
| OEM Data-Licensing Agreement | Secures direct ECU architecture access for encrypted Bosch, Continental, and Denso platforms. |
| Telematics Platform Integration | Enables over-the-air calibration updates and recurring subscription revenue from connected vehicles. |
| India Two-Wheeler Market Entry | Addresses 125 million registered motorcycles under BS6 Phase II emission standards. |
| Cloud-Connected Dyno Network Expansion | Compresses feedback loops between road testing and map release for dispersed motorsport clients. |
Research Methodology
Multiple input streams — calibration house technical directors, aftermarket garage owners, OEM platform engineers, and regulatory compliance officers — were reconciled against EPA enforcement databases, CARB executive order registries, vehicle production statistics, and semiconductor trade flow data. Bottom-up unit economics from tuning device bill-of-materials were triangulated with top-down market sizing from regional vehicle registration and motorsport participation rates.
Data-stream reconciliation across the projection horizon modeled segmentation by product architecture, end-user sophistication tier, technology protocol, and application compliance requirement. CAGRs were derived from installed base growth, replacement cycle compression, and regulatory-driven upgrade mandates. Forecast inputs incorporated ECU encryption evolution timelines and CARB reciprocal agreement expansion patterns.
Underlying measurement precision varies by segment; flash tuning and software-based programming carry tighter precision than legacy chip tuning and piggyback systems given visibility into OEM data-licensing relationships. Forecasts reflect assumptions around EPA enforcement intensity and semiconductor allocation normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Driveline Market
Powertrain
Iridium Spark Plug Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Power Steering Filter Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Torque Limiter Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Automotive PTC Heaters Market
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Fuel Pumps Market
Powertrain
Engine Flush Market