
 Automotive PTC Heaters Market | 2026-2036
Automotive PTC Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive PTC Heaters Market Insights
The gap between premium integrated thermal systems and commodity standalone heaters is shifting procurement criteria across the supply base. Eberspächer leverages its European manufacturing footprint to anchor high-specification contracts with German OEMs. BorgWarner competes through vertical integration into power electronics, sustaining margin capture across the heating control stack. MAHLE GmbH specializes in modular architectures that accommodate multiple voltage platforms, differentiating its portfolio as electrification diversifies.
Automotive PTC heaters are self-regulating ceramic elements composed of barium titanate-based compounds that exhibit positive temperature coefficient resistance, typically operating between 12V and 800V depending on vehicle architecture, with primary purpose to deliver efficient cabin comfort and battery thermal conditioning without external control circuitry. Battery heaters command the fastest expansion within product type segmentation, driven by lithium-ion preconditioning requirements in sub-zero climates. Integrated systems dominate technology segmentation, absorbing control electronics and sensors into single modules that OEMs specify for platform standardization across passenger and commercial vehicle lines.
The EPA tailpipe and efficiency standards, NHTSA safety regulations for occupant thermal systems, and China's GB/T standards for NEV components collectively shape certification burdens and product qualification timelines. ECHA REACH compliance on ceramic material compositions constrains supplier formulation choices, particularly for European aftermarket channels. Stakeholders must monitor how battery chemistry evolution toward solid-state architectures alters heating load profiles and voltage compatibility requirements.
Market Dynamics
Electrification of vehicle architectures is compressing thermal system design cycles, forcing PTC heater suppliers to synchronize development roadmaps with battery platform voltages that now span 400V to 800V ranges.
Growth Catalysts
- China's NEV subsidy regime:Tiered incentive structures for new energy vehicles mandate localized thermal component sourcing, pulling PTC assembly capacity into the Yangtze River Delta cluster.
- Lithium-ion preconditioning requirements:Sub-zero battery performance degradation in Nordic and North American climates necessitates dedicated heating elements for thermal conditioning.
- Ceramic formulation advances:Barium titanate-based compounds with enhanced Curie point stability enable self-regulating elements that operate across wider voltage windows without external control circuitry.
Market Restraints
- Raw material concentration:High-purity barium titanate supply concentrates among Asian specialty chemical producers, exposing heater manufacturers to input cost volatility and qualification delays.
- ECHA REACH compliance burdens:Ceramic material composition disclosures for European aftermarket channels extend product qualification timelines by 8-14 months.
- Silicon carbide heating element substitution:Emerging wide-bandgap semiconductor heaters threaten PTC dominance in premium 800V architectures where efficiency thresholds are tightest.
Strategic Opportunities
- Commercial vehicle electrification:Battery-electric buses and medium-duty trucks in Germany and the Netherlands require scalable modular heating systems that PTC architectures accommodate.
- Solid-state battery compatibility:Next-generation cell chemistries with narrower operating temperature bands will intensify demand for precision thermal conditioning solutions.
- Integrated control electronics convergence:Combining power electronics, sensors, and heating elements into single modules creates platform-standardization value for OEMs spanning passenger and commercial lines.
Industry Challenges
- Power electronics talent scarcity:Shortage of engineers capable of designing high-voltage control circuitry for 800V architectures delays product development cycles.
- Multi-voltage platform certification:OEMs require simultaneous validation across 12V, 48V, 400V, and 800V systems, multiplying testing overhead and documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive PTC Heaters Market |
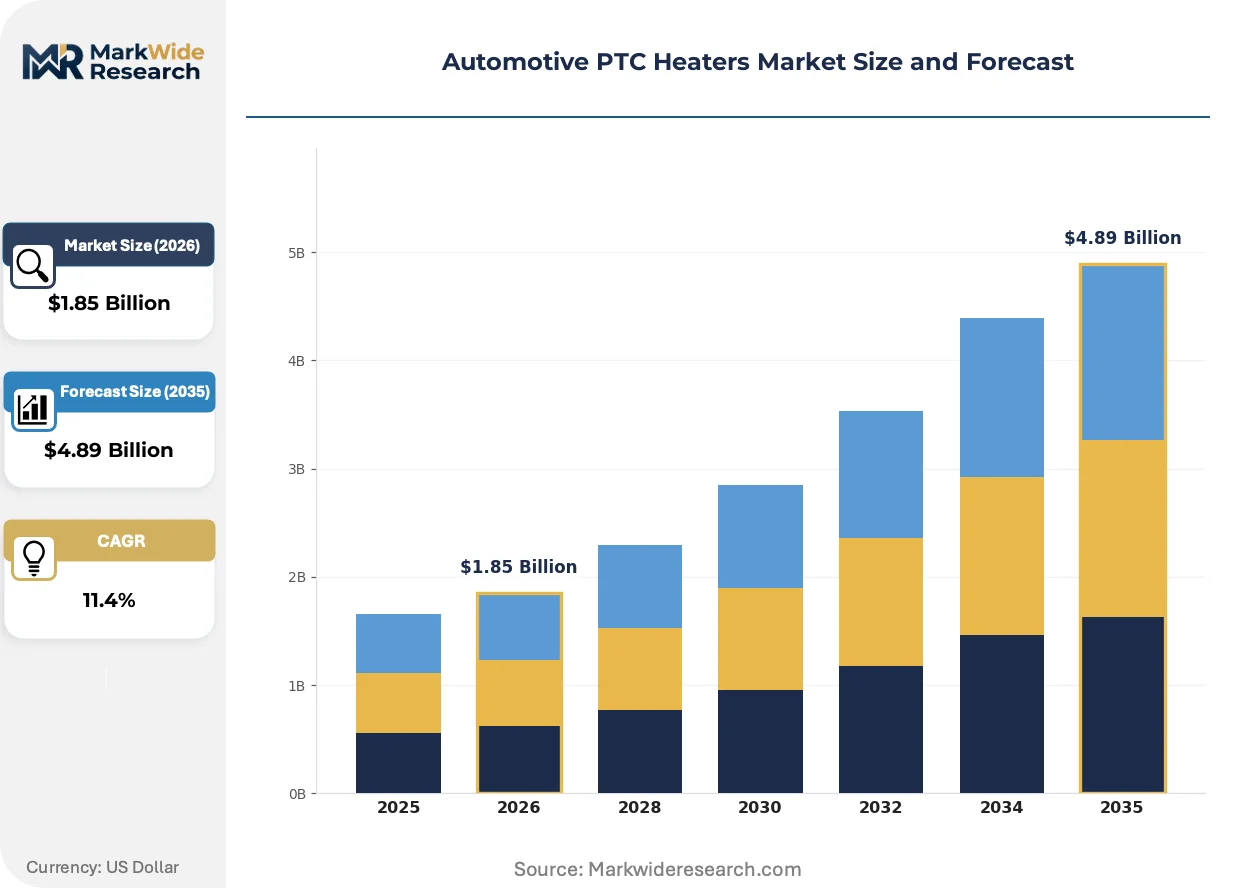
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Heaters, Interior Heaters, Seat Heaters, Battery Heaters Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Technology: Self-Regulating, Thermal Management, Smart Heating, Integrated Systems End User: OEMs, Aftermarket Suppliers, Vehicle Manufacturers, Automotive Assemblers |
| Companies Covered | Eberspächer, BorgWarner, MAHLE GmbH, Denso, Webasto, Valeo, Tenneco, DBK Group, Yageo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive PTC Heaters Market Trends and Innovations
Control electronics miniaturization and sensor fusion are collapsing the traditional separation between heating elements and thermal management systems, creating integrated modules that OEMs specify for platform-scale deployment.
Silicon-carbide-based power semiconductors are integrating into PTC control circuits, enabling faster switching frequencies and reduced thermal losses. Tier-1 suppliers are adopting these devices for 800V battery electric vehicle programs. This integration is compressing the efficiency gap between discrete and integrated heating architectures.
Germany's KBA enforcement of cabin efficiency mandates under EU Green Deal frameworks is tightening thermal system performance thresholds. OEMs must document watt-per-degree heating metrics to receive type approval. Battery preconditioning applications face the steepest compliance gradients.
Fleet operators are consolidating supplier relationships around platform-compatible thermal modules rather than component-level sourcing. This concentration favors suppliers offering multi-voltage architectures with unified control interfaces. The shift is most pronounced in European commercial vehicle procurement.
Automotive PTC Heaters Market Segmentation
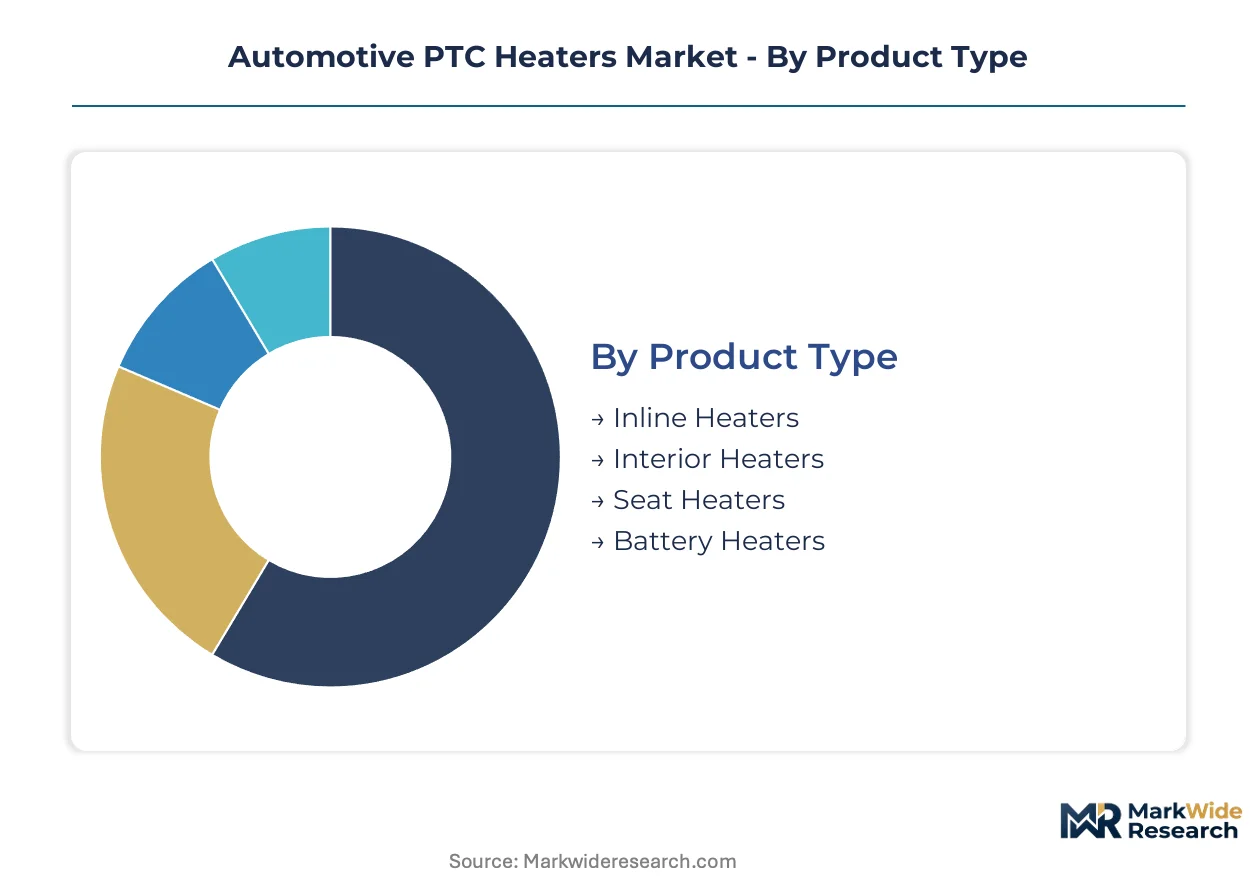
Segmentation in automotive PTC heaters reflects divergent thermal load requirements across vehicle architectures. Voltage compatibility and integration depth separate premium specifications from commodity supply.
Product Type:
Heater configuration varies with thermal target and installation geometry.
- Inline Heaters:Fluid-circulating elements embedded in coolant loops deliver targeted battery pack conditioning. Demand clusters in Nordic passenger EV programs where sub-zero preconditioning preserves lithium-ion capacity.
- Battery Heaters:Direct-contact ceramic assemblies with barium titanate cores maintain cell operating windows. China's NEV subsidy tiers accelerate procurement from Yangtze River Delta assemblers for localized platform compliance.
- Interior Heaters:Cabin air modules with integrated blower assemblies.
- Seat Heaters:Low-voltage surface warming elements for occupant comfort.
Mature deployment sits with Interior Heaters. Newer deployment is concentrated in Battery Heaters.
Application:
Vehicle electrification intensity determines heater specification and voltage architecture.
- Electric Vehicles:High-voltage architectures demand 400V-800V compatible ceramic formulations with self-regulating Curie point stability. German KBA cabin efficiency mandates tighten watt-per-degree thresholds for type approval.
- Commercial Vehicles:Battery-electric buses and medium-duty trucks in the Netherlands require scalable modular systems. Fleet procurement concentrates around platform-compatible thermal modules with unified control interfaces.
- Passenger Vehicles:Mixed powertrain compatibility across ICE and electrified platforms.
- Hybrid Vehicles:Dual thermal management for combustion and electric drive systems.
Volume concentration remains with Passenger Vehicles. Steepest expansion trajectory belongs to Commercial Vehicles.
Technology:
Control integration depth separates commodity elements from system-level supply.
- Integrated Systems:Single modules absorbing power electronics, sensors, and heating elements enable OEM platform standardization. ECHA REACH compliance on ceramic compositions extends European aftermarket qualification timelines.
- Self-Regulating:Barium titanate-based compounds with positive temperature coefficient resistance operate without external control circuitry. Asian specialty chemical producers concentrate high-purity feedstock supply.
- Thermal Management:Coordinated multi-zone heating with battery-cabin load balancing.
- Smart Heating:Sensor-fusion-enabled predictive thermal conditioning.
Technology maturation centers on Self-Regulating architectures. Silicon carbide integration is advancing fastest within Integrated Systems.
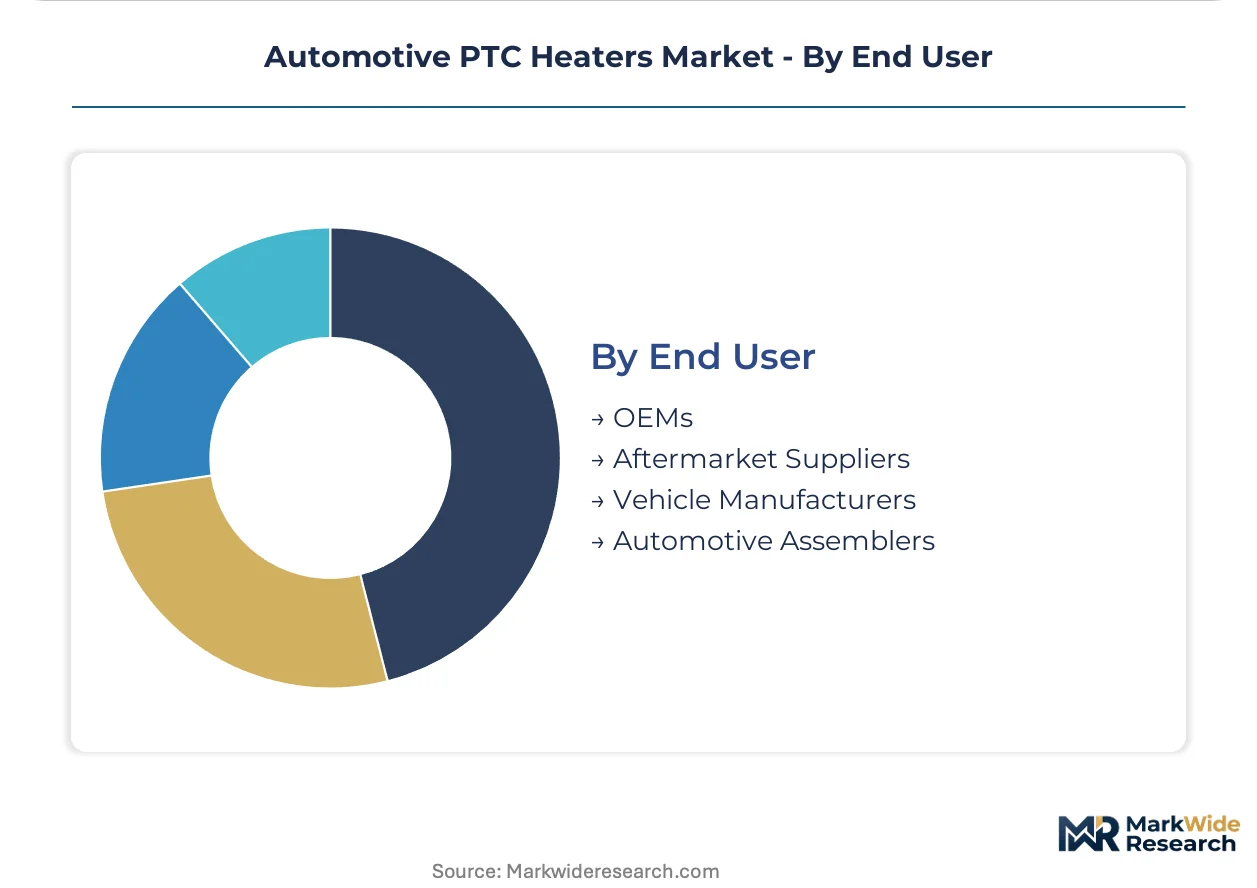
End User:
Procurement authority separates captive supply from open market distribution.
- OEMs:Direct platform specification with multi-voltage certification requirements spanning 12V through 800V systems. German manufacturers anchor high-specification contracts through localized European manufacturing footprints.
- Vehicle Manufacturers:Joint venture entities in China's Yangtze River Delta cluster source PTC assemblies under NEV localization mandates.
- Aftermarket Suppliers:Replacement channel distribution with regional certification burdens.
- Automotive Assemblers:Contract manufacturing arrangements for thermal system integration.
Contract value concentrates with OEMs. Channel expansion is gaining share fastest in Aftermarket Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta automotive cluster anchors PTC heater procurement, with Shanghai, Suzhou, and Ningbo hosting joint venture assembly plants under China's NEV localization mandates.
China
Domestic OEMs and joint ventures in Jiangsu and Zhejiang provinces source localized PTC assemblies to satisfy MIIT subsidy tiers for new energy vehicles. GB/T standards for NEV components enforce strict thermal performance certification. The Yangtze River Delta concentration pulls barium titanate feedstock through Ningbo port logistics corridors.
Germany
KBA enforcement of EU Green Deal cabin efficiency mandates tightens watt-per-degree thresholds for type approval across passenger and commercial EV programs. ECHA REACH compliance on ceramic compositions extends aftermarket qualification timelines. Manufacturing footprints in Stuttgart and Munich anchor high-specification contracts with domestic OEMs.
United States
EPA tailpipe standards and NHTSA safety regulations for occupant thermal systems shape product qualification timelines for lithium-ion preconditioning applications. Sub-zero battery performance degradation in Nordic-influenced northern states drives dedicated heating element demand. Detroit-area engineering centers coordinate 400V-800V platform development with Asian ceramic suppliers.
Japan
METI carbon neutrality roadmaps accelerate electrification timelines for domestic OEM thermal systems. JIS standards govern ceramic element reliability testing for automotive applications. Nagoya-area manufacturing corridors specialize in self-regulating barium titanate formulations for export markets.
South Korea
MFDS automotive component safety frameworks align with global EV platform standards. Seoul Capital Area battery-electric vehicle programs require 800V-compatible ceramic heating architectures. Busan-Ulsan industrial complexes concentrate feedstock processing for export to European and North American Tier-1 suppliers.
Automotive PTC Heaters Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the PTC heater supply base. Foundry-dependent ceramic element manufacturers face margin pressure from integrated module suppliers capturing control electronics value. Three archetypes dominate: European system integrators with captive manufacturing, Asian component specialists with feedstock advantages, and diversified thermal management conglomerates spanning multiple vehicle architectures. Competitive moves concentrate on backward integration into power electronics and geographic co-location with battery platform engineering centers.
Within the European integrated systems tier, Eberspächer GmbH and MAHLE GmbH exemplify manufacturers anchoring high-specification OEM relationships through localized production footprints. BorgWarner Inc. occupies a position representing diversified thermal management players with upstream control over power electronics design.
| Leading Market Players |
|---|
| Eberspächer |
| BorgWarner |
| MAHLE GmbH |
| Denso |
| Webasto |
| Valeo |
| Tenneco |
| DBK Group |
| Yageo |
| Others |
Pricing and Supply Chain Analysis
Barium titanate feedstock costs cascade through three pricing tiers, with Asian specialty chemical producers capturing upstream margin before Yangtze River Delta assemblers apply NEV localization premiums for domestic OEM contracts.
Pricing Analysis
Watt-per-degree heating efficiency serves as the value-based pricing anchor for OEM type approval under Germany's KBA cabin efficiency mandates. Three-tier pricing structure across premium integrated modules, standard self-regulating elements, and economy standalone heaters separates certification grade and voltage compatibility. Cost compression in economy standalone tiers is intensifying because silicon carbide heating element substitution threatens PTC dominance in 800V architectures. Fleet operators in commercial vehicle procurement show least price sensitivity due to platform standardization requirements, while aftermarket suppliers face greatest pressure from ECHA REACH compliance documentation burdens.
Supply Chain Analysis
ECHA REACH compliance on ceramic material compositions gates European aftermarket qualification timelines, extending product validation by 8-14 months. High-purity barium titanate supply concentrates among China, Japan, and South Korea specialty chemical producers, exposing heater manufacturers to input cost volatility. The supply chain draws from barium titanate cores, power electronics semiconductors, and sensor arrays as critical inputs. Single-source vulnerability in Asian feedstock processing creates structural risk. Distribution runs through Tier-1 supplier direct contracts with OEM platform engineering centers, supplemented by joint venture assembly in China's Yangtze River Delta cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
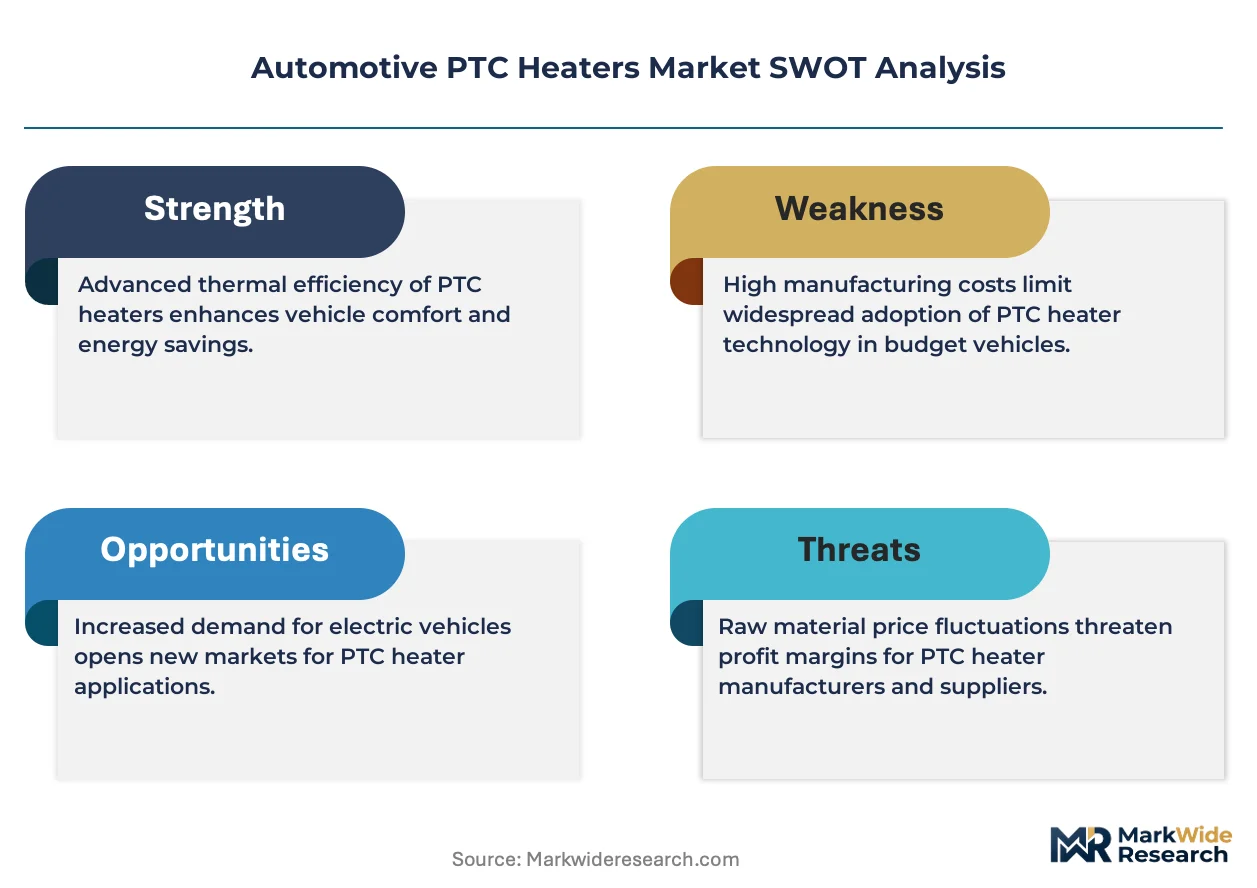
Barium titanate feedstock concentration among Asian specialty chemical producers props pricing power for integrated module suppliers, constraining margin expansion for foundry-dependent ceramic element manufacturers.
For Market Incumbents: To counter silicon carbide heating element substitution in premium 800V architectures, Eberspächer and MAHLE should deepen backward integration into power electronics design and expand captive barium titanate formulation capacity in European manufacturing footprints. Certification investment for multi-voltage platform validation across 12V through 800V systems anchors high-specification OEM relationships against emerging wide-bandgap semiconductor competitors. For New Entrants and Emerging Players: China's GB/T standards for NEV components in the Yangtze River Delta cluster opens a window for localized PTC assembly partnerships with joint venture entities seeking subsidy tier compliance. Battery-electric bus procurement in the Netherlands represents the most penetrable white-space target, with fleet operators consolidating around platform-compatible thermal modules. A go-to-market angle emphasizing modular architectures for 400V-800V voltage flexibility addresses commercial vehicle electrification intensity. For Investors and Strategic Acquirers: KBA enforcement of EU Green Deal cabin efficiency mandates tightening watt-per-degree thresholds is the leading indicator that integrated control electronics convergence will accelerate platform standardization value capture. The 5-10 year viability window favors acquisition targets with captive ceramic formulation expertise and established OEM platform engineering relationships. Watch for solid-state battery chemistry announcements narrowing operating temperature bands as the inflection signal for precision thermal conditioning demand intensification.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Integrated modules absorbing power electronics and sensors enable OEMs to specify single thermal architectures across passenger and commercial vehicle lines. |
| Battery Supply Agreement | Direct contracts with lithium-ion cell manufacturers anchor heating element demand for preconditioning applications in sub-zero climates. |
| Software-Defined Vehicle Investment | Sensor-fusion-enabled predictive thermal conditioning differentiates smart heating architectures from commodity ceramic elements. |
| Geographic Manufacturing Footprint | Localized production in Germany's Stuttgart and Munich corridors satisfies KBA type approval proximity requirements for European OEM contracts. |
| Charging Infrastructure Partnership | Alignment with 800V fast-charging network deployment synchronizes high-voltage heating element roadmaps with battery platform voltage evolution. |
Research Methodology
Multi-period observation of NEV subsidy tier structures, KBA cabin efficiency mandate enforcement, and silicon carbide heating element development timelines anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and ceramic formulation specialists. Secondary validation drew from MIIT production databases, ECHA REACH compliance filings, EPA tailpipe standard updates, and vehicle registration data. Bottom-up assembly cost modeling and top-down market sizing triangulated volume and value estimates.
Segment-weighting across product type, application, technology, and end user dimensions shaped the analytical framework, with voltage compatibility and integration depth as cross-cutting modifiers. CAGRs were derived from regression analysis of historical platform deployment rates applied to electrification intensity projections. Battery chemistry evolution toward solid-state architectures and multi-voltage certification requirements served as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide heating element substitution or solid-state battery thermal load profiles would alter the outlook. Forecasts reflect documented assumptions on NEV subsidy regime continuity and ECHA REACH compliance burden stability. A model refresh is warranted upon material change in China's MIIT localization mandates or KBA watt-per-degree threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Powertrain Management System Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Racing Clutches Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Automotive Tuner Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Drive Shaft Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Automatic Transmission Market
Powertrain
Brazil Automotive Market
Powertrain
Automotive Camless Engine Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Iridium Spark Plug Market
Powertrain
North America Torque Vectoring Market
Powertrain
Gasoline Direct Injection (GDI) System Market