
 Test Automation Systems for Powertrain Dynamometer Market | 2026-2036
Test Automation Systems for Powertrain Dynamometer Market Size, Share, and Industry Trends Forecast 2026-2036
Test Automation Systems for Powertrain Dynamometer Market Analytics
Modular hardware-software bundles is decoupling as buyers favor à la carte procurement of control systems and data analytics modules. AVL List GmbH leverages its Austrian engineering heritage to dominate high-precision dynamometer integration. Horiba sustains leadership in emission testing workflows through deep instrumentation expertise. Siemens competes by extending its digital twin architecture into powertrain validation environments.
Test automation systems for powertrain dynamometers encompass sensor arrays, real-time controllers, data acquisition hardware, and supervisory software orchestrating torque, speed, thermal, and emissions measurement across engine and e-motor test cells. These systems execute automated test sequences with repeatability below 0.1% measurement uncertainty, enabling compliance validation and R&D optimization for conventional, hybrid, and electric powertrains. Software and data analytics segments are capturing expanding margin pools as artificial intelligence-enabled predictive maintenance and cloud-based remote monitoring displace on-premise legacy architectures. Hardware retains volume dominance but faces commoditization pressure from open-platform control systems.
EPA emission regulations and Euro 7 standards from the European Commission are mandating expanded test cycles that multiply dynamometer operating hours and automation complexity. China's MIIT enforces GB standards for new energy vehicle powertrain efficiency, compelling domestic and foreign labs to upgrade test infrastructure. Stakeholders must weigh captive software development against third-party platform partnerships as regulatory test breadth expands.
Market Dynamics
Powertrain electrification is fragmenting test automation requirements as laboratories simultaneously validate internal combustion, hybrid, and fully electric architectures under divergent thermal and torque protocols. This structural bifurcation is forcing dynamometer suppliers to engineer modular platforms capable of rapid reconfiguration between engine and e-motor test cells without hardware replacement.
Growth Catalysts
- EPA Tier 3 emission standards:Extended test cycles for particulate matter and cold-start emissions are multiplying dynamometer operating hours at US-based powertrain development centers.
- China's MIIT GB standards:Mandatory efficiency certification for new energy vehicle powertrains is compelling domestic and foreign automakers to upgrade test infrastructure in Shanghai and Beijing.
- Hybrid powertrain proliferation:Dual-mode validation requirements spanning combustion and electric torque paths are expanding automation complexity and system attach rates.
Market Restraints
- High-precision torque sensor costs:Strain-gauge and optical encoder assemblies represent 35-45% of system hardware expenditure, creating capital barriers for mid-tier test facilities.
- Control software vendor concentration:Proprietary real-time operating systems from Austrian and German suppliers create platform lock-in and limit interoperability with third-party analytics modules.
- Legacy asset stranding:Existing engine test cells with 15-20 year depreciation cycles delay replacement demand even where electrification mandates new capability.
Strategic Opportunities
- India powertrain lab expansion:Domestic OEMs and global Tier-1 suppliers are establishing test centers in Pune and Chennai to support export-oriented engine programs and local EV platforms.
- Artificial intelligence-enabled predictive maintenance:Machine learning models trained on vibration and thermal signatures can reduce unplanned dynamometer downtime and extend calibration intervals.
- Cloud-based remote monitoring architectures:Distributed engineering teams require browser-accessible test cell supervision, displacing on-premise SCADA installations with SaaS delivery models.
Industry Challenges
- Mechatronics engineering talent scarcity:Integration of precision mechanical systems with real-time embedded controls demands hybrid skill sets concentrated in Stuttgart, Munich, and Detroit metropolitan areas.
- Multi-physics simulation fidelity gaps:Correlating physical dynamometer results with digital twin predictions requires specialized calibration expertise that outpaces current workforce development.
- Certification timeline compression:Accelerated vehicle program cycles are squeezing validation windows, forcing test automation systems to execute overnight sequences with zero fault tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test Automation Systems for Powertrain Dynamometer Market |
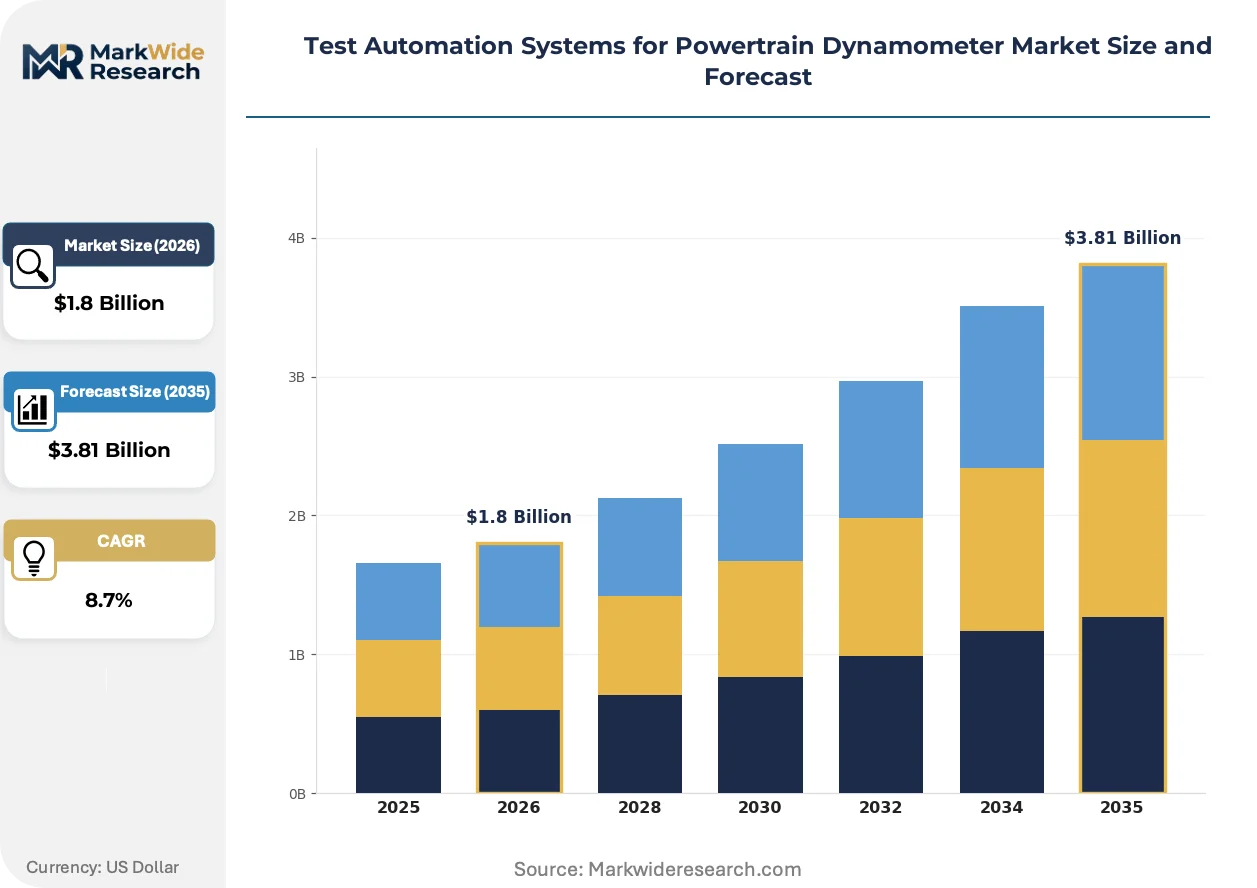
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Integrated Solutions, Control Systems End User: Automotive Manufacturers, Tier-1 Suppliers, Research Institutions, Aftermarket Providers Technology: Modular Automation, Cloud-Based Solutions, Artificial Intelligence, Data Analytics Application: Performance Testing, Emission Testing, Durability Testing, Calibration |
| Companies Covered | AVL List GmbH, Horiba, Siemens, National Instruments, Keysight Technologies, dSPACE, FEV Europe GmbH, KRATZER AUTOMATION AG, Froude, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test Automation Systems for Powertrain Dynamometer Market Evolving Landscape
Test automation architectures are converging around software-defined control planes that decouple hardware acquisition from analytics procurement, enabling laboratories to upgrade capability without full system replacement. This modularization is reshaping vendor competitive dynamics and buyer negotiation leverage.
Silicon-carbide power electronics is electrifying dynamometer motor drive systems by enabling higher switching frequencies and reduced thermal losses in regenerative loading applications. European powertrain labs in Germany and Austria are adopting these drives for e-motor characterization above 20,000 RPM. The technology is electrifying the competitive landscape for high-speed electric powertrain validation, compressing the performance gap between premium and mid-tier system suppliers.
The European Commission's Euro 7 framework is mandating real-driving emissions correlation through chassis dynamometer sequences that replicate urban, rural, and motorway duty cycles. This regulatory expansion is forcing test cell automation systems to integrate GPS trace playback and altitude simulation capabilities previously reserved for vehicle-level proving grounds. Powertrain development centers in Stuttgart, Wolfsburg, and Turin are prioritizing dynamometer investments that satisfy these extended validation protocols.
Automotive OEM procurement departments are unbundling hardware and software contracts, negotiating separate agreements for control systems, data acquisition hardware, and cloud analytics subscriptions. This disaggregation favors specialized vendors in sensor instrumentation and AI-enabled diagnostics while eroding margins for integrated platform suppliers. The shift is most pronounced among German and US-based manufacturers with centralized purchasing functions and established vendor qualification programs.
Test Automation Systems for Powertrain Dynamometer Market Segmentation
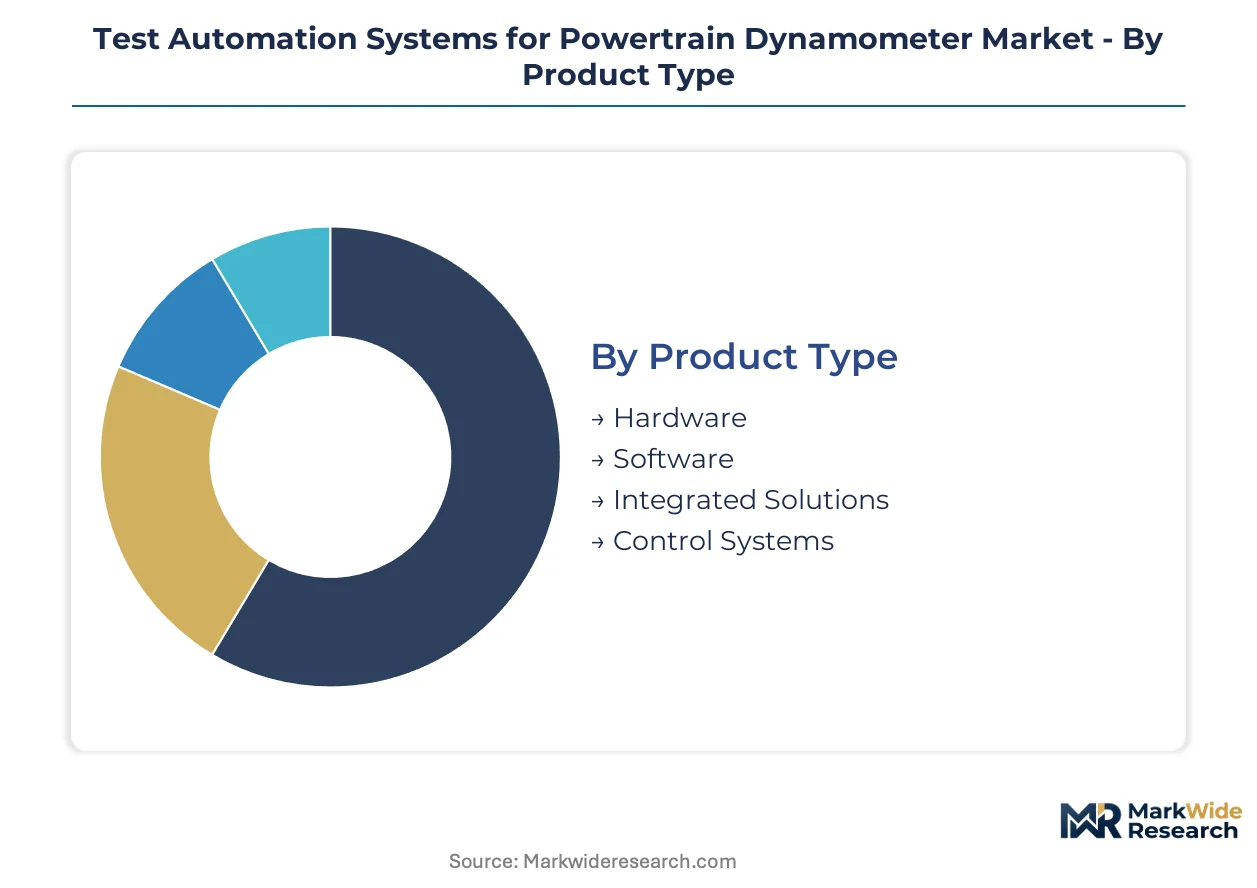
Powertrain dynamometer test automation systems fragment across hardware, software, and service layers with divergent margin profiles and procurement cycles. Understanding these divisions clarifies where capital deployment concentrates and where vendor consolidation pressure builds.
Product Type:
Hardware components demand the heaviest upfront capital outlay, with precision torque sensors and regenerative motor drives consuming 35-45% of total system expenditure. Software and control modules carry lower acquisition costs but higher lifetime service attach rates.
- Hardware:Sensor arrays, data acquisition modules, and motor drive assemblies constitute the physical measurement layer. German and Austrian engineering centers in Stuttgart and Graz anchor procurement for high-precision strain-gauge and optical encoder systems as Euro 7 validation protocols extend test cycle requirements.
- Software:Supervisory control platforms orchestrate test sequencing, calibration routines, and regulatory report generation. Cloud-native architectures are displacing on-premise SCADA installations as distributed engineering teams in Detroit and Shanghai demand browser-accessible supervision.
- Integrated Solutions:Bundled hardware-software packages from single-source vendors. Procurement departments at major automotive OEMs are unbundling these contracts to negotiate separate agreements for physical and digital components.
- Control Systems:Real-time embedded controllers executing torque and speed regulation with sub-millisecond latency. Proprietary operating systems from Central European suppliers create platform lock-in that limits third-party analytics interoperability.
Most installed capacity flows through Hardware. Expansion is steepest in Software.
End User:
Customer type determines contract scale, technical specification depth, and service engagement intensity. Automotive manufacturers dominate absolute spending while research institutions drive early technology adoption.
- Automotive Manufacturers:Captive powertrain development centers at OEMs operate the largest test cell networks. EPA Tier 3 and Euro 7 mandates are multiplying dynamometer operating hours at US and European validation facilities as emission test cycles lengthen.
- Tier-1 Suppliers:Independent powertrain component manufacturers operating contract test services for multiple OEM programs. These facilities prioritize modular platforms capable of rapid reconfiguration between engine and e-motor test protocols.
- Research Institutions:University and national laboratory test cells focused on pre-competitive R&D and regulatory harmonization studies. China's MIIT-funded labs in Shanghai and Beijing are upgrading infrastructure to support GB standard certification for new energy vehicle powertrains.
- Aftermarket Providers:Independent test services supporting warranty validation, remanufacturing quality assurance, and performance modification compliance. This segment concentrates in mature automotive markets with aging vehicle parc.
Automotive Manufacturers deploy the most test cell capacity. Research Institutions are expanding most quickly.
Technology:
Technology architecture choices determine upgrade flexibility, data sovereignty, and long-term vendor relationships. The shift toward software-defined control planes is decoupling hardware procurement from analytics capability.
- Modular Automation:Reconfigurable hardware-software architectures enabling rapid switching between combustion, hybrid, and electric powertrain validation. European labs are adopting these platforms to manage structural bifurcation in test requirements.
- Cloud-Based Solutions:SaaS delivery models for test supervision, data storage, and remote diagnostics. Distributed engineering teams require browser-accessible test cell monitoring that displaces on-premise infrastructure.
- Artificial Intelligence:Machine learning models trained on vibration and thermal signatures to predict equipment failures and optimize calibration intervals. Silicon-carbide power electronics adoption above 20,000 RPM e-motor characterization is generating training data volumes that favor AI-enabled analysis.
- Data Analytics:Post-processing platforms for test result visualization, regulatory report generation, and design optimization feedback. Unbundling from control software is creating procurement leverage for specialized analytics vendors.
Modular Automation commands the largest installed base. Cloud-Based Solutions are gaining share fastest.
Application:
Application type dictates test cycle duration, environmental conditioning requirements, and automation complexity. Emission validation carries the most stringent regulatory compliance burden.
- Performance Testing:Torque-speed mapping, thermal efficiency measurement, and transient response characterization. High-speed e-motor validation above 20,000 RPM is driving adoption of silicon-carbide power electronics in German and Austrian test facilities.
- Emission Testing:Particulate matter, NOx, and greenhouse gas quantification under standardized and real-driving cycles. Euro 7 mandates for GPS trace playback and altitude simulation are forcing integration of chassis dynamometer capabilities into powertrain test cells.
- Durability Testing:Accelerated life cycling, thermal shock protocols, and mechanical fatigue accumulation. Overnight test sequences with zero fault tolerance are compressing validation windows as vehicle program cycles accelerate.
- Calibration:Control algorithm refinement for engine management and e-motor inverter systems. Multi-physics simulation fidelity gaps between physical dynamometer results and digital twin predictions are extending calibration timelines.
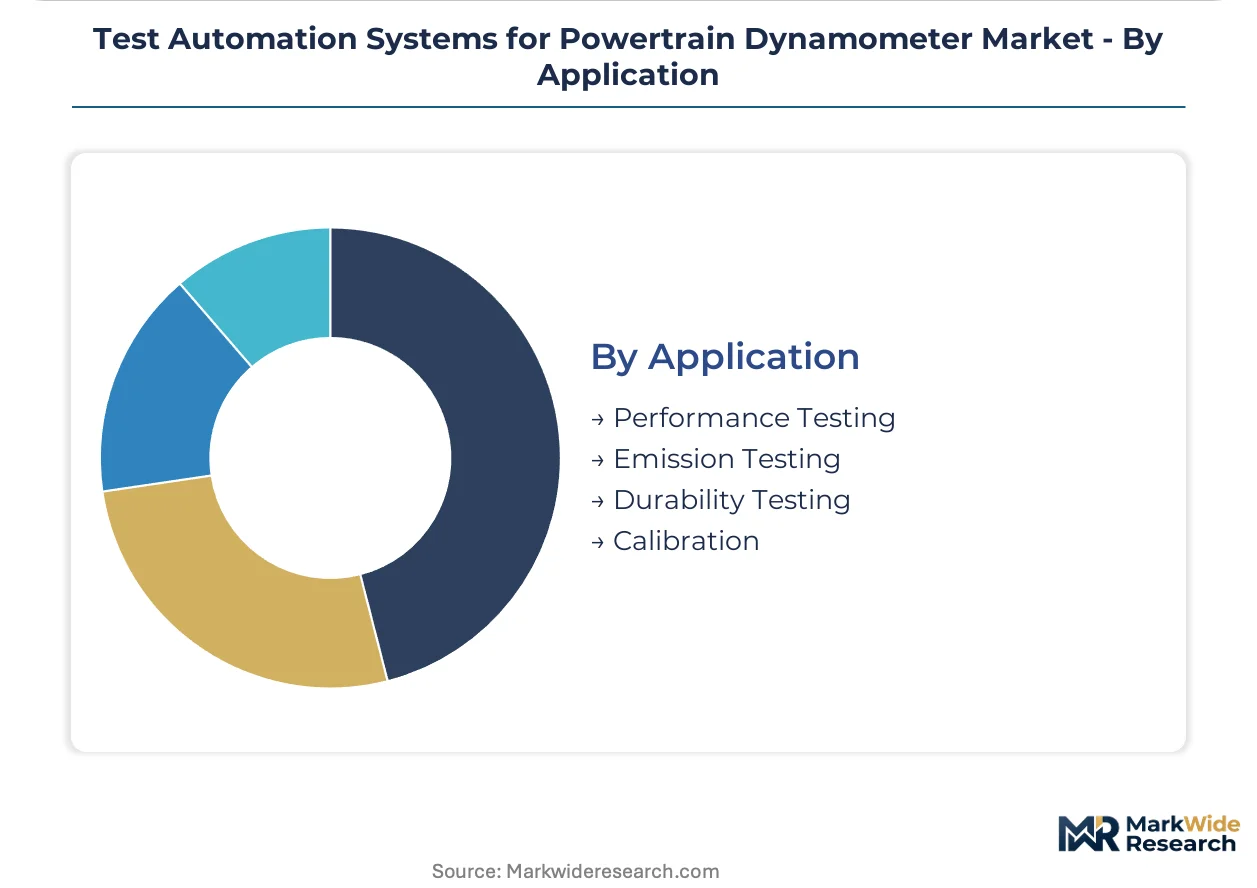
Performance Testing absorbs the most installed capacity. Emission Testing is climbing the fastest as regulatory breadth expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powertrain dynamometer test automation originated in German automotive engineering centers during the 1980s, spreading to Detroit and Nagoya as emission regulations tightened. Stuttgart's concentration of OEM development labs established the technical templates later adopted in Shanghai and Chennai.
Germany
Stuttgart and Wolfsburg host Europe's densest clusters of powertrain validation facilities. Euro 7 emission standards from the European Commission mandate GPS trace playback and altitude simulation capabilities that German labs are integrating into test cells. Bavarian engineering centers around Munich are deploying silicon-carbide power electronics for high-speed e-motor characterization above 20,000 RPM.
China
Shanghai and Beijing powertrain laboratories are upgrading infrastructure to meet MIIT GB standards for new energy vehicle efficiency certification. The Yangtze River Delta concentration of EV manufacturers is driving demand for modular test platforms capable of rapid reconfiguration. Domestic OEMs in Shenzhen are establishing captive test facilities to reduce reliance on foreign validation services.
United States
Detroit metropolitan powertrain development centers are multiplying dynamometer operating hours to satisfy EPA Tier 3 extended test cycles for particulate matter and cold-start emissions. Michigan-based Tier-1 suppliers are investing in hybrid powertrain validation capability to serve dual-mode torque path requirements. California emission labs are integrating chassis dynamometer sequences previously reserved for proving grounds.
Japan
Nagoya and Tokyo automotive engineering centers maintain precision torque measurement expertise developed during lean manufacturing era. METI efficiency mandates for hybrid systems are expanding automation complexity at domestic OEM test facilities. Toyota City suppliers are adopting cloud-based remote monitoring to support distributed engineering teams across multiple continents.
India
Pune and Chennai are emerging as test hub locations for export-oriented engine programs and local EV platforms. Domestic OEMs are establishing powertrain validation centers to reduce overseas testing costs for vehicles destined for Middle East and African markets. Government production-linked incentive schemes are attracting global Tier-1 suppliers to establish regional test infrastructure.
Test Automation Systems for Powertrain Dynamometer Market Competitive Landscape
The competitive structure tilts toward integrated platform specialists with deep instrumentation heritage. Three tiers have formed: Austrian and German engineering houses with proprietary control systems, Japanese precision equipment manufacturers, and North American software-defined automation vendors. Consolidation pressure is building as procurement departments unbundle hardware and software contracts. Strategic moves concentrate on modular platform development and cloud analytics partnerships rather than vertical integration.
Among Central European engineering specialists, AVL List GmbH, Horiba, and Siemens occupy positions defined by their historical concentration in emission testing workflows and dynamometer integration. AVL List GmbH represents the Austrian precision engineering archetype with captive test cell expertise. Horiba exemplifies Japanese instrumentation depth applied to regulatory compliance sequences. Siemens anchors the industrial automation tier extending digital twin architectures into validation environments. These three demonstrate how geographic engineering heritage translates into differentiated platform positioning.
| Leading Market Players |
|---|
| AVL List GmbH |
| Horiba |
| Siemens |
| National Instruments |
| Keysight Technologies |
| dSPACE |
| FEV Europe GmbH |
| KRATZER AUTOMATION AG |
| Froude |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement departments concentrated in Stuttgart, Detroit, and Shanghai negotiate pricing through unbundled hardware-software contracts that separate control system acquisition from analytics module subscriptions. This buyer concentration favors modular procurement models over integrated platform bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-precision torque measurement systems from mid-tier open-platform controllers and entry-level sensor arrays. Certification grade for Euro 7 and EPA Tier 3 compliance commands substantial premiums, while volume scale discounts apply to multi-cell laboratory deployments. Cost compression in the hardware tier intensifies as silicon-carbide power electronics commoditizes regenerative drive systems. Tier-1 suppliers operating contract test services exhibit the highest price sensitivity; captive OEM development centers prioritize performance over unit cost.
Supply Chain Analysis
Mechatronics engineering talent scarcity in Stuttgart, Munich, and Graz constrains production scaling for precision strain-gauge assemblies and real-time embedded controllers. Manufacturing concentrates in Germany, Austria, and Japan, with optical encoder production drawing from specialized optics clusters in Bavaria and Nagoya. Single-source vulnerability persists for proprietary real-time operating systems from Central European vendors. Distribution runs through direct OEM sales teams for large contracts and specialized industrial distributors for mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain test automation functions as a stable compounder anchored by regulatory mandates that expand validation cycle requirements regardless of macroeconomic cycles.
For Market Incumbents: Anticipate margin erosion from open-platform control systems by deepening proprietary software lock-in through AI-enabled predictive maintenance modules. Invest in certification engineering for Euro 7 GPS trace playback capabilities before compliance deadlines tighten. Capacity addition in China's Yangtze River Delta region captures MIIT-funded laboratory upgrades. For New Entrants and Emerging Players: The mid-tier price-point gap between AVL-grade integrated platforms and economy sensor arrays offers entry space for cloud-native analytics specialists. Target India's Pune and Chennai test hub expansion where domestic OEMs seek alternatives to European validation services. Pursue partnership-first go-to-market positioning with established motor drive manufacturers to bypass control software development barriers. For Investors and Strategic Acquirers: Industrial automation conglomerates with digital twin architectures represent the most active acquirer in this space, seeking to extend platform coverage into powertrain validation. Five-to-ten-year viability rests on software attach rate expansion rather than hardware volume growth. Acquisition target archetypes include specialized AI diagnostics vendors with automotive training datasets. Monitor silicon-carbide power electronics adoption curves above 20,000 RPM as inflection indicator for high-speed e-motor test cell demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Enables rapid reconfiguration between combustion and electric test protocols without hardware replacement. |
| Cloud Analytics Partnership | Displaces on-premise SCADA installations with browser-accessible supervision for distributed engineering teams. |
| AI-Enabled Predictive Maintenance | Reduces unplanned dynamometer downtime using vibration and thermal signature machine learning models. |
| Silicon-Carbide Drive Integration | Compresses performance gaps between premium and mid-tier suppliers in high-speed e-motor characterization. |
| Euro 7 Compliance Certification | Mandates GPS trace playback and altitude simulation capabilities previously reserved for proving grounds. |
Research Methodology
Multiple input streams — executive interviews with powertrain development directors, procurement data from Tier-1 supplier networks, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged test cell operations managers, OEM platform engineers, and aftermarket service heads across Stuttgart, Detroit, Shanghai, and Pune. Secondary validation drew from EPA emission certification databases, MIIT GB standard publications, European Commission Euro 7 framework documents, and automotive production registration data. Bottom-up cell-count modeling and top-down OEM R&D expenditure analysis were cross-referenced for triangulation.
Historical capacity installation patterns were cross-referenced against panel input from engineering directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology architecture, and application protocol. CAGRs were derived from regression analysis of equipment procurement cycles against regulatory timeline acceleration. Industry-specific forecast inputs include powertrain electrification mix shifts and emission test cycle expansion mandates.
Caveats apply where Euro 7 implementation delays or EPA Tier 3 enforcement modifications could materially shift the outlook for validation infrastructure investment. Forecasts reflect assumptions about regulatory timeline adherence and OEM program cycle compression rates. Practitioners should monitor MIIT GB standard revision schedules and silicon-carbide power electronics cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Paddle Shifter Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Engine Tuner Market
Powertrain
Steering Damper Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Engine Starter Market
Powertrain
Global Driveline Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Car Oil Filter Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Automotive Hydrostatic Fan Drive System Market